
 ASEAN Digital Transformation Market | 2026-2036
ASEAN Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Digital Transformation Market Insights
Platform licensing revenue is tilting from perpetual software models toward subscription-based cloud architectures across Southeast Asia. Microsoft Corporation leverages its Azure regional data centers in Singapore and Indonesia to anchor enterprise workloads requiring local residency. SAP SE competes through industry-specific ERP templates tailored for ASEAN manufacturing and palm oil supply chains. FPT Corporation dominates Vietnam's public sector digitization through its system integration capabilities and government relationships.
ASEAN Digital Transformation encompasses the integration of cloud computing, artificial intelligence, and data analytics into enterprise and government operations across Southeast Asia, typically delivered through API-connected microservices architectures with sub-100 millisecond latency requirements for real-time decision support. Its primary purpose is replacing legacy paper-based and siloed electronic systems with interoperable digital infrastructure that reduces transaction costs and improves service delivery speed. Public Cloud deployments lead in revenue scale as hyperscalers expand Jakarta and Bangkok availability zones, while Artificial Intelligence represents the fastest-expanding technology segment as banks and telcos deploy conversational interfaces and fraud detection models. Managed Services capture disproportionate margin pools because ASEAN enterprises lack sufficient in-house DevOps and cybersecurity talent to operate complex multi-cloud environments independently.
Singapore's Personal Data Protection Commission, Indonesia's Ministry of Communication and Informatics, and Thailand's National Cyber Security Agency collectively enforce data localization and breach notification standards that dictate cloud provider certification requirements and contract terms. BIS and CDSCO standards in India, though outside ASEAN, indirectly pressure regional pharmaceutical exporters to maintain compatible digital traceability systems. Organizations must monitor evolving cross-border data flow agreements between ASEAN member states and assess whether their current deployment architectures satisfy emerging sovereignty requirements without fragmenting operational coherence.
Market Dynamics
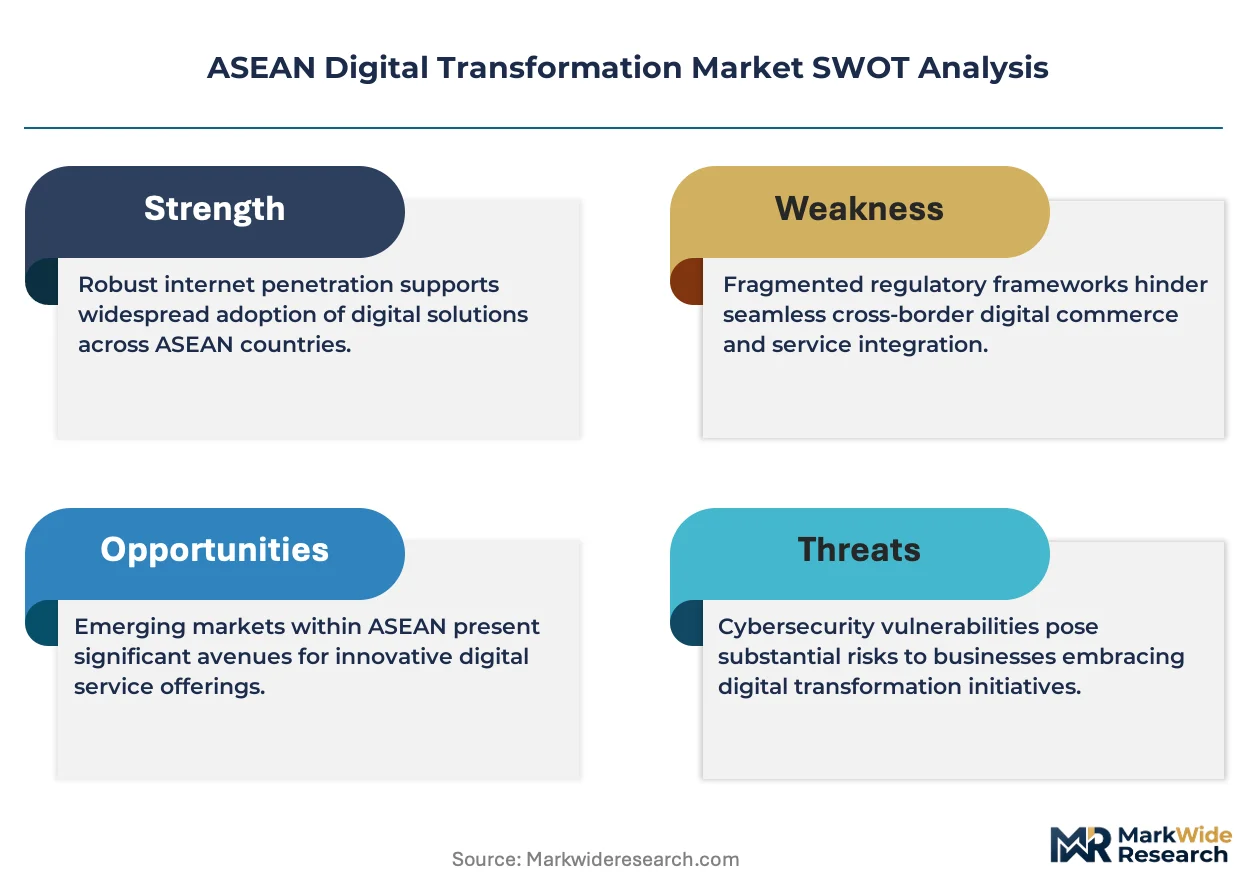
Cloud-native architectures are collapsing the traditional on-premise software licensing model across Southeast Asia, as hyperscalers establish sovereign data zones and regulators tighten cross-border data flow enforcement.
Growth Catalysts
- Indonesia's National Digital Identity Program:The government's biometric ID rollout mandates enterprise-grade identity verification infrastructure, driving demand for API-connected authentication services across banking and e-commerce sectors.
- Cross-border data transfer frameworks:ASEAN member states are harmonizing data localization standards, reducing compliance fragmentation and enabling regional cloud workload portability for multinational enterprises.
- Conversational AI deployment:Banking institutions in Singapore and Thailand are rapidly adopting natural language processing interfaces for customer service automation, creating pull-through demand for underlying GPU infrastructure and MLOps platforms.
Market Restraints
- DevOps talent scarcity:Vietnam and Philippines face acute shortages of certified Kubernetes administrators and cloud security architects, inflating implementation timelines and professional services costs.
- Input cost volatility:GPU and specialized AI accelerator procurement costs fluctuate with global semiconductor supply constraints, compressing margins for managed service providers offering fixed-price AI infrastructure contracts.
- Regulatory fragmentation:Divergent data breach notification timelines between Singapore's PDPC and Indonesia's Kominfo create operational complexity for enterprises operating multi-country architectures.
Strategic Opportunities
- Philippines BPO digitization:The country's contact center industry is modernizing legacy voice infrastructure with real-time transcription and sentiment analysis, creating demand for edge computing deployments in Cebu and Clark.
- Malaysia's MyDIGITAL blueprint:Federal cloud-first procurement mandates are opening public sector opportunities for hybrid cloud integrators meeting domestic data residency certification requirements.
- 5G-IoT convergence:Thailand's smart city initiatives in Bangkok and Phuket are driving integrated deployments of cellular IoT sensors with municipal data platforms, favoring vendors with telco partnership ecosystems.
Industry Challenges
- Multi-cloud orchestration complexity:ASEAN enterprises lack in-house Site Reliability Engineering capacity to manage workloads across Azure, AWS, and Google Cloud simultaneously without service degradation.
- Legacy mainframe integration:Core banking systems in Indonesia and Vietnam still run on COBOL-based architectures, requiring expensive middleware layers to connect with modern API gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Digital Transformation Market |
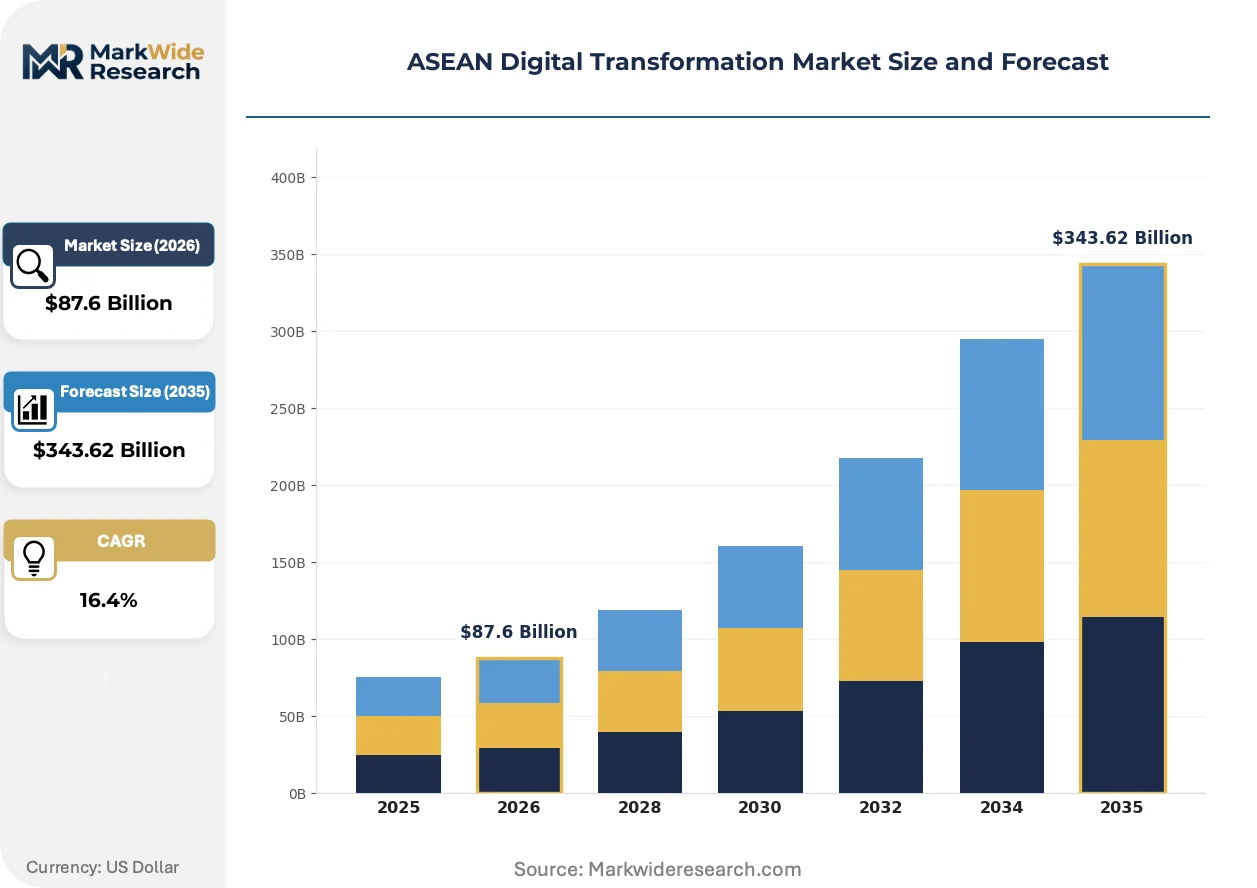
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $343.62 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Technology: Artificial Intelligence, Internet of Things, Blockchain, Big Data End User: SMEs, Large Enterprises, Government Agencies, Non-Profit Organizations Service Type: Consulting, Managed Services, Training, Support Services |
| Companies Covered | Accenture PLC, Google LLC, IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, Cisco Systems Inc, Grab, FPT Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Digital Transformation Market Trends and Innovations
API-first microservices architectures are displacing monolithic enterprise software across Southeast Asian financial services and logistics sectors, compressing deployment cycles from quarters to weeks.
Serverless computing is collapsing the traditional infrastructure provisioning model for variable-workload applications. Indonesian e-commerce platforms are adopting function-as-a-service architectures for flash-sale traffic spikes. This compression eliminates upfront capacity planning and shifts cost structures to per-execution metering.
Singapore's PDPC enforcement of cross-border data transfer accountability mechanisms is reshaping vendor contracting practices. Financial institutions must now document data flow mapping and implement standard contractual clauses. Banks are responding by prioritizing Azure and AWS regions with in-country data residency certifications.
Subscription-based consumption models are displacing perpetual license procurement in enterprise software. Thai manufacturing conglomerates now prefer annual SaaS commitments with embedded professional services over multi-year on-premise deployments. This shift concentrates purchasing power with CFO-led finance teams rather than CIO-led technical evaluation committees.
ASEAN Digital Transformation Market Segmentation
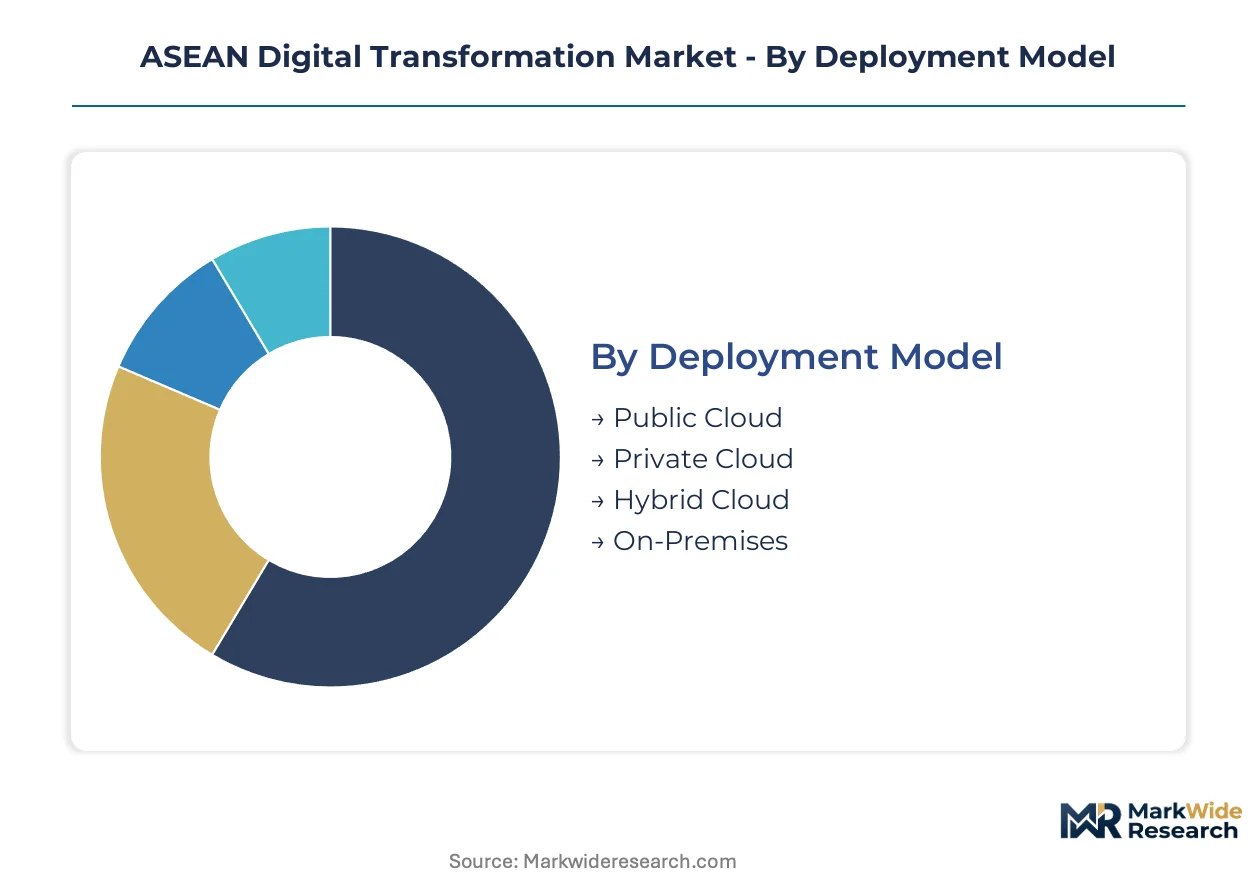
Deployment architectures and service delivery models across Southeast Asia fragment along regulatory maturity, talent availability, and data sovereignty requirements. Understanding these fault lines clarifies where procurement authority concentrates and which vendor configurations win.
Deployment Model:
Mature hyperscaler regions like Singapore contrast with emerging sovereign cloud zones in Indonesia and Vietnam, creating a deployment maturity spectrum that shapes enterprise buying patterns.
- Public Cloud:Hyperscaler regions in Singapore and Jakarta anchor enterprise workloads requiring sub-100 millisecond latency for real-time analytics. Indonesian e-commerce platforms and Thai banking consortia drive demand for auto-scaling compute during transaction spikes.
- Hybrid Cloud:Split architectures allow Malaysian manufacturers to keep sensitive design data on-premises while bursting non-critical workloads to Azure or AWS. This configuration dominates where Kominfo or PDPC data localization rules apply selectively by data classification.
- Private Cloud:Single-tenant infrastructure serves Vietnamese state-owned enterprises and Philippine government agencies with air-gapped security requirements. Procurement runs through systems integrators with domestic security clearances.
- On-Premises:Legacy COBOL-based core banking systems in Indonesia and Vietnam persist where middleware migration costs exceed cloud rental savings over five-year horizons.
Public Cloud handles the majority of throughput; Hybrid Cloud is the fastest mover on share as regulatory clarity improves.
Technology:
Cost tier separation distinguishes capital-intensive infrastructure technologies from software-layer implementations with lower barrier-to-entry.
- Artificial Intelligence:GPU-intensive machine learning pipelines power conversational banking interfaces in Singapore and fraud detection models across ASEAN payment networks. Vietnamese and Philippine DevOps scarcity inflates implementation timelines.
- Internet of Things:Cellular-connected sensor networks in Bangkok and Phuket smart city deployments integrate with municipal data platforms. Thailand's 5G spectrum allocation accelerates edge computing procurement for real-time traffic and utilities management.
- Big Data:Distributed analytics platforms process e-commerce transaction volumes for Indonesian marketplaces and logistics optimization for regional supply chains.
- Blockchain:Distributed ledger pilots concentrate in Singapore trade finance and cross-border remittance corridors, though production deployment remains limited by interoperability standards gaps.
Artificial Intelligence captures the highest absolute investment; Internet of Things is climbing the fastest as 5G infrastructure matures.
End User:
Customer type determines contract structure, with government procurement favoring multi-year system integration awards versus enterprise preference for annual SaaS commitments.
- Large Enterprises:Thai manufacturing conglomerates and Singaporean financial institutions lead ERP modernization, shifting from perpetual licenses to subscription cloud architectures with embedded professional services.
- Government Agencies:Malaysia's MyDIGITAL blueprint and Indonesia's national digital identity program mandate domestic data residency, favoring hybrid cloud integrators with local certification. FPT Corporation dominates Vietnam's public sector through established relationships.
- SMEs:Indonesian e-commerce sellers and Philippine BPO operators adopt serverless function-as-a-service models to eliminate upfront capacity planning for variable workloads.
- Non-Profit Organizations:Grant-funded digitization initiatives in education and health sectors rely on discounted cloud credits and pro-bono consulting from hyperscaler corporate social responsibility programs.
Large Enterprises commit the greatest contract value; Government Agencies are gaining share fastest as sovereign cloud frameworks mature.
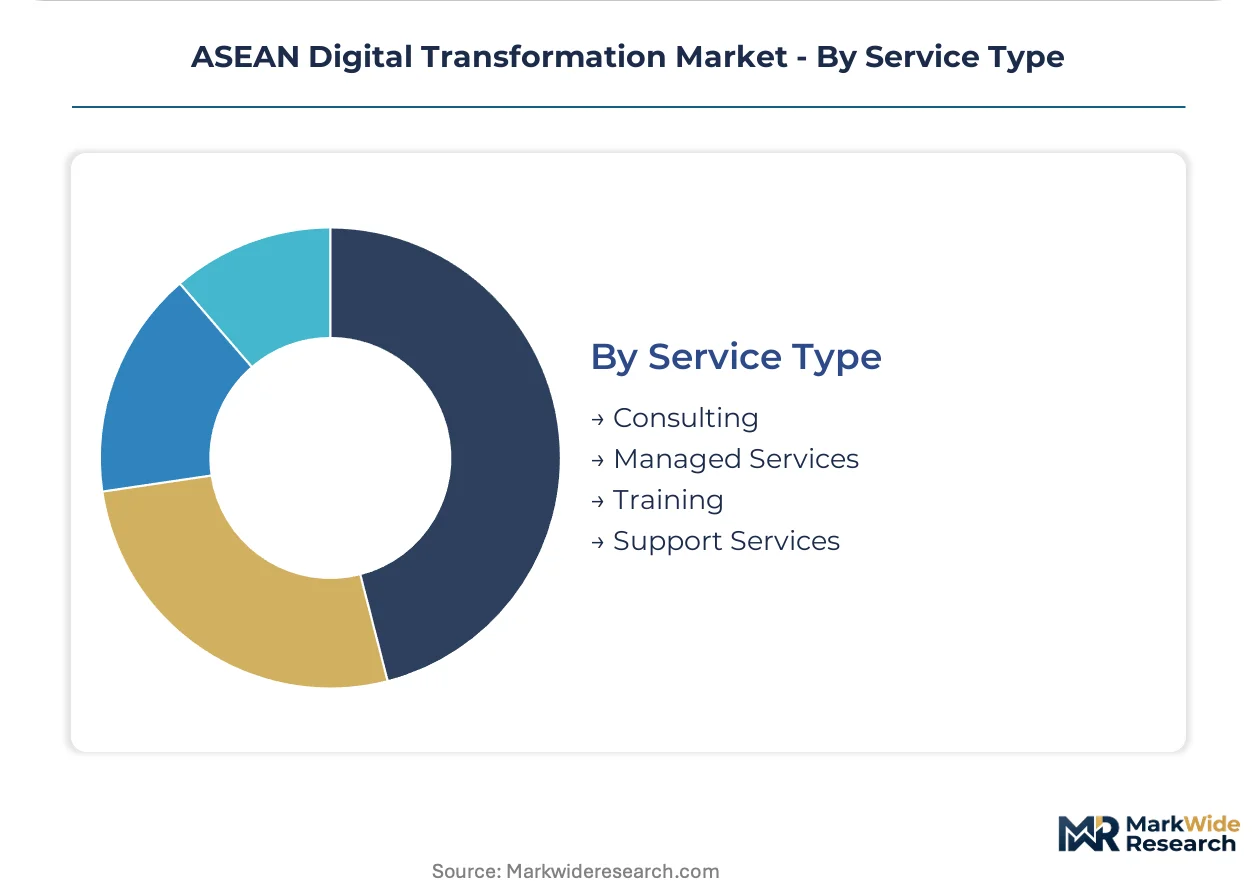
Service Type:
Margin concentration separates high-touch consulting and managed services from commoditized support functions.
- Managed Services:24/7 Site Reliability Engineering and security operations center coverage addresses acute ASEAN talent scarcity in Kubernetes administration and cloud security architecture. Providers capture disproportionate margin pools through multi-year operational contracts.
- Consulting:Cloud migration assessment and legacy mainframe integration projects command premium day rates where COBOL-to-API middleware expertise is scarce, particularly in Indonesian and Vietnamese banking sectors.
- Training:Certification programs for AWS, Azure, and Google Cloud address the pipeline gap for cloud-native engineers, often bundled with enterprise software procurement.
- Support Services:Break-fix and ticket-based assistance operates on thinner margins, frequently offshore to Philippine technical support centers.
Managed Services generates the highest recurring revenue; Consulting shows the steepest expansion trajectory as legacy modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia consumes digital transformation infrastructure as sovereign cloud capacity for national identity systems, while Singapore deploys identical technologies for cross-border financial analytics—revealing a consumption-mix split between state-directed and market-driven architectures.
Singapore
Financial institutions and maritime logistics operators drive demand for low-latency analytics and AI-powered compliance automation. The Personal Data Protection Commission enforces strict cross-border data transfer accountability mechanisms with mandatory breach notifications. Marina Bay and Jurong East host concentrated clusters of cloud-native fintech development and enterprise AI research centers.
Indonesia
The national digital identity program and e-commerce marketplace expansion create massive pull for API-connected authentication and auto-scaling compute infrastructure. Kominfo mandates domestic data residency for citizen biometric information and government cloud workloads. Jakarta and Surabaya anchor hyperscaler availability zones serving banking consortia and retail platform operators.
Thailand
Banking sector conversational AI deployment and smart city sensor networks accelerate GPU infrastructure and edge computing procurement. The National Cyber Security Agency coordinates breach response protocols and critical infrastructure protection standards. Bangkok and Phuket concentrate 5G-IoT integration projects linking municipal utilities with real-time data platforms.
Vietnam
State-owned enterprise digitization and manufacturing supply chain modernization sustain demand for hybrid cloud and legacy system integration. Domestic cybersecurity certification requirements favor systems integrators with government security clearances. Hanoi and Ho Chi Minh City host public sector digital service delivery hubs and software export development zones.
Malaysia
Federal cloud-first procurement mandates under the MyDIGITAL blueprint open public sector opportunities for hybrid cloud integrators. Domestic data residency certification requirements shape vendor selection for sensitive government workloads. Kuala Lumpur and Penang concentrate financial services digitization and electronics manufacturing supply chain technology upgrades.
ASEAN Digital Transformation Market Competitive Landscape
Capability concentration sits with regional systems integrators possessing government security clearances and legacy modernization expertise; scale advantage sits with hyperscalers operating sovereign data zones across multiple ASEAN jurisdictions. The market structures around three tiers: global cloud platforms with local availability zones, regional specialists with public sector relationships, and boutique consultancies addressing talent scarcity gaps. Dominant competitive moves include hyperscaler expansion of Jakarta and Bangkok data centers and strategic partnerships between global software vendors and domestic integrators.
Within the regional specialist tier, FPT Corporation exemplifies the government-anchored integrator archetype through its Vietnam public sector concentration. Among global platform providers, Microsoft Corporation and SAP SE occupy positions at opposite ends of the deployment spectrum—Azure regional infrastructure versus industry-specific ERP templates. These three entities collectively illustrate how vendor selection in ASEAN digital transformation splits between sovereign compliance requirements and enterprise application standardization.
| Leading Market Players |
|---|
| Accenture PLC |
| Google LLC |
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Cisco Systems Inc |
| Grab |
| FPT Corporation |
| Others |
Pricing and Supply Chain Analysis
GPU and AI accelerator procurement volatility determines both margin compression in managed service contracts and hyperscaler capacity expansion sequencing across Southeast Asia. Singapore's PDPC data residency mandates and Indonesia's Kominfo localization rules fragment procurement authority, forcing tiered infrastructure investment strategies that widen pricing spreads between sovereign-certified and standard cloud deployments.
Pricing Analysis
Long-term managed service contracts with embedded professional services dominate enterprise procurement, though Indonesian e-commerce platforms increasingly favor serverless per-execution metering for variable workloads. Price differentiation hinges on data residency certification tier and volume commitment scale, with government workloads commanding premiums for domestic security clearances. Cost compression in standard public cloud tiers intensifies as hyperscalers expand Jakarta and Bangkok availability zones. CFO-led finance teams at Thai manufacturing conglomerates exhibit highest price sensitivity through annual SaaS renegotiation cycles, while Vietnamese state-owned enterprises accept premium pricing for air-gapped private infrastructure.
Supply Chain Analysis
Upstream semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with NVIDIA and AMD GPU supply rationing cascading through ASEAN channel partners. Cloud infrastructure hardware draws from Chinese server assembly and Malaysian electronics manufacturing zones, while specialized AI accelerators rest on single-source dependencies. Tariff exposure on networking equipment imports into Vietnam and the Philippines elevates total cost of ownership for edge computing deployments. Distribution runs through Singapore-based regional distributors with local stocking facilities in Jakarta and Ho Chi Minh City to meet sub-100 millisecond latency requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN digital transformation fragments across regulatory maturity lines, creating acquisition opportunities for specialists bridging sovereign compliance and enterprise standardization. Indonesia's national identity program and Malaysia's MyDIGITAL blueprint concentrate public sector demand, while banking conversational AI and BPO digitization pull commercial investment.
For Market Incumbents: Entrench through exclusive system integration relationships with Indonesian and Vietnamese government agencies, leveraging security clearance moats against hyperscaler direct sales. Acquire boutique Kubernetes training providers in Manila and Ho Chi Minh City to address DevOps talent scarcity before competitors replicate capability. Prioritize Azure and AWS sovereign zone certifications to defend against emerging domestic cloud challengers. For New Entrants and Emerging Players: Mid-market Philippine BPO operators represent the most penetrable entry point, with legacy voice infrastructure modernization creating immediate demand for real-time transcription and sentiment analysis platforms. Indonesian SME e-commerce sellers adopting serverless architectures offer low-friction initial deployment opportunities with land-and-expand potential. Partner with telco channel programs in Thailand to bundle 5G-IoT edge computing solutions for smart city pilots. For Investors and Strategic Acquirers: ASEAN cross-border data flow harmonization agreements reshape the acquisition landscape, elevating regional specialists with multi-country compliance expertise above single-market players. Target systems integrators possessing simultaneous PDPC, Kominfo, and Thai NCSA certification pathways. Watch for GPU supply allocation announcements from hyperscalers as inflection indicators for managed service provider margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | PDPC and Kominfo data residency mandates create procurement gatekeeping for government workloads. |
| Legacy Mainframe Integration | COBOL-to-API middleware expertise commands premium pricing in Indonesian and Vietnamese banking sectors. |
| DevOps Talent Pipeline Investment | Certification programs address acute Kubernetes administrator scarcity inflating implementation timelines. |
| Telco Partnership Ecosystem | 5G-IoT convergence in Bangkok and Phuket smart cities favors vendors with cellular infrastructure integration. |
| Regional Availability Zone Expansion | Jakarta and Bangkok hyperscaler capacity anchors sub-100 millisecond latency for real-time analytics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud architects at Singaporean financial institutions, procurement officers at Indonesian e-commerce platforms, government IT directors in Vietnam, and managed service executives across the region. Secondary validation drew from hyperscaler capex disclosures, ASEAN regulatory agency enforcement bulletins, and customs data on networking equipment imports. Bottom-up triangulation against top-down market sizing ensured segmentation coherence across deployment models and service types.
Calibration against historical cloud adoption curves in comparable emerging markets anchored growth rate assumptions across the projection horizon. The analytical framework modeled deployment architecture, organization size, vertical industry, integration complexity, and regulatory jurisdiction as core segmentation dimensions. CAGRs were derived from elasticity-adjusted technology penetration curves, with specific weighting applied to Indonesia's national digital identity procurement timelines and Malaysia's federal cloud-first mandates.
Stress conditions across GPU supply rationing, cross-border data flow policy divergence, and DevOps talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hyperscaler capacity expansion sequencing and sovereign cloud framework implementation pace. Cross-checking against hyperscaler regional revenue disclosures and systems integrator backlog reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
France Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
Telco Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
Innovation Management Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
South East Asia Digital Transformation Market
Digital Transformation
Workplace Transformation Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Nigeria Digital Transformation Market
Digital Transformation
Global Application Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
Oman Digital Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
Japan Digital Transformation Market
Digital Transformation
Italy Digital Transformation Market