
 Thailand Digital Transformation Market | 2026-2036
Thailand Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Digital Transformation Market Insights
Thailand's Personal Data Protection Act is rebalancing procurement priorities toward compliant data architectures. Microsoft Corporation anchors enterprise cloud transitions through its Bangkok availability zones. SAP SE specializes in ERP modernization for Thai manufacturing conglomerates navigating Industry 4.0 mandates.
Digital transformation encompasses the integration of cloud computing, artificial intelligence, and Internet of Things technologies into core business operations to automate workflows and enable real-time decision-making. The technology dimension shows cloud computing leading current spend while artificial intelligence claims the fastest expansion trajectory. Within deployment modes, hybrid cloud configurations capture premium margin pools as Thai enterprises balance latency requirements against PDPA-driven data sovereignty needs.
Thailand's Ministry of Digital Economy and Society enforces PDPA compliance timelines that accelerate enterprise security spending. The National Broadcasting and Telecommunications Commission shapes telecommunications infrastructure standards enabling 5G-enabled IoT rollouts. Stakeholders must monitor regulatory enforcement intensity in Bangkok versus provincial markets to calibrate channel investments and localization strategies.
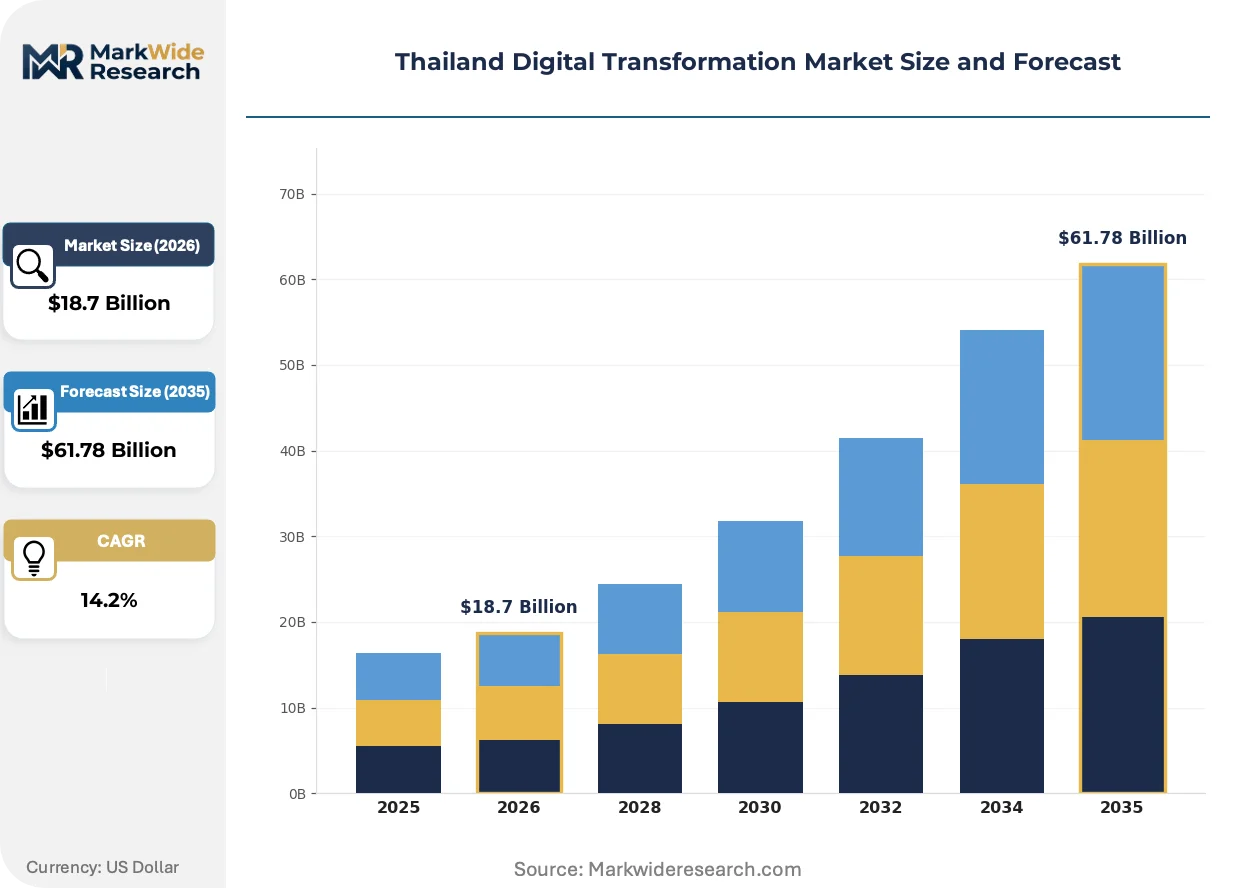
Market Dynamics
Thailand's Personal Data Protection Act enforcement is compressing enterprise cloud procurement timelines while mandating data localization architectures that favor hybrid deployment models.
Growth Catalysts
- PDPA Compliance Mandates:Thailand's Ministry of Digital Economy and Society enforces strict data sovereignty requirements that accelerate enterprise spending on compliant cloud infrastructure and security tooling.
- Manufacturing 4.0 Upgrades:Thai automotive and electronics conglomerates deploy ERP modernization and IoT-enabled predictive maintenance to meet Industry 4.0 productivity targets.
- 5G Infrastructure Rollout:The National Broadcasting and Telecommunications Commission's spectrum allocation enables real-time industrial automation and smart city deployments across Bangkok's metropolitan cluster.
Market Restraints
- Data Localization Costs:PDPA-driven domestic data center requirements impose capital intensity on foreign cloud providers seeking Thai market entry.
- Technical Talent Scarcity:Shortage of certified cloud architects and cybersecurity specialists constrains implementation velocity for mid-market enterprises.
- Legacy System Interoperability:Proprietary on-premise ERP installations in Thai family-owned conglomerates resist API-native integration with modern SaaS platforms.
Strategic Opportunities
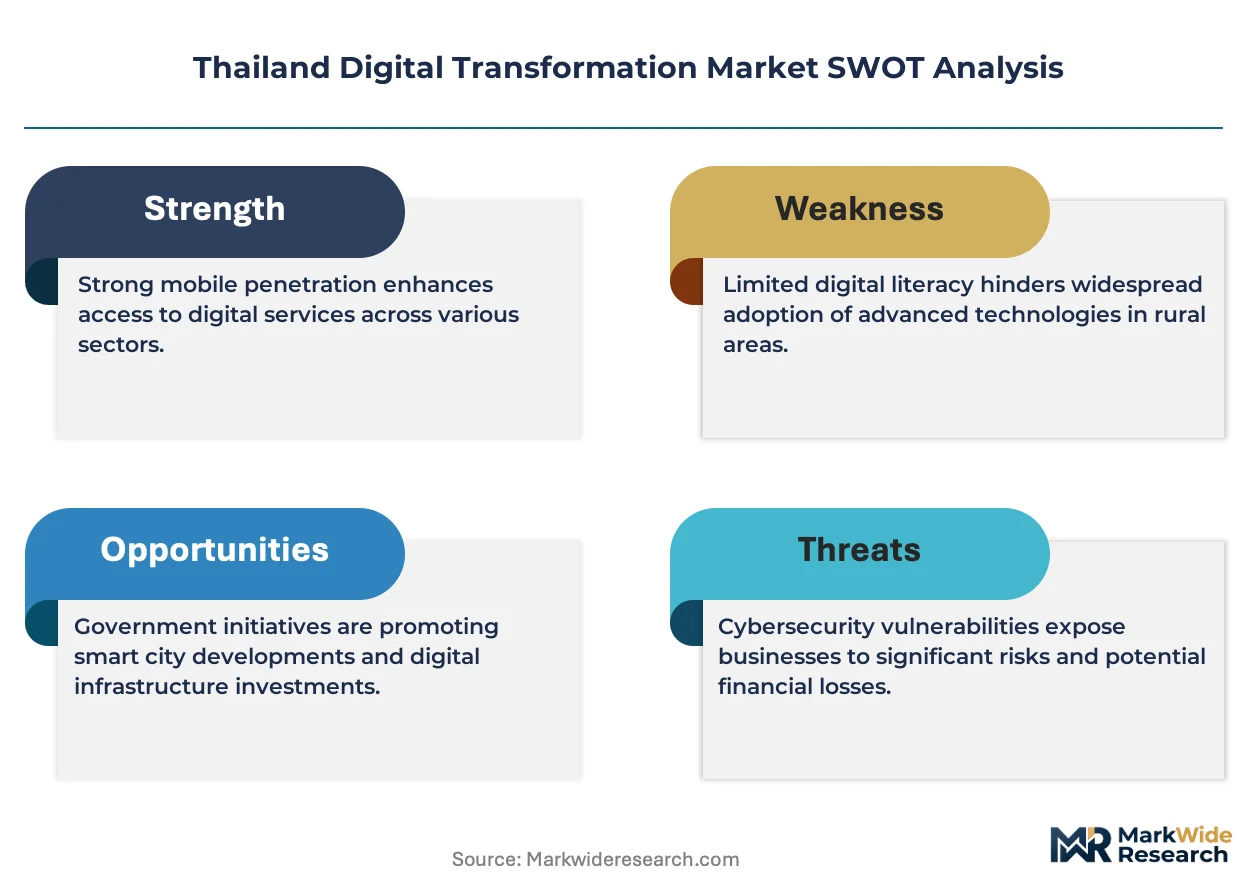
- Eastern Economic Corridor Expansion:Industrial zones in Chonburi and Rayong provinces present greenfield digital infrastructure deployment opportunities for manufacturing automation vendors.
- AI-IoT Convergence:Edge computing platforms combining computer vision with sensor networks enable predictive quality control in Thai food processing and packaging operations.
- Regulatory Sandbox Participation:Bank of Thailand's fintech sandbox permits controlled testing of blockchain-based trade finance and digital identity solutions.
Industry Challenges
- Cybersecurity Certification Timelines:PDPA-mandated data protection officer appointments and breach notification protocols strain compliance capacity at provincial Thai enterprises.
- Intergenerational Technology Transfer:Family-controlled Thai conglomerates face governance friction when digitizing founder-era manual processes and paper-based approval workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Digital Transformation Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Big Data Analytics, Artificial Intelligence, Internet of Things Industry Vertical: BFSI, Retail, Healthcare, Education Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Solution: Digital Marketing, E-Commerce, Customer Engagement, Process Automation |
| Companies Covered | Accenture PLC, Google LLC, Microsoft Corporation, IBM Corporation, Amazon Web Services, True Corporation, AIS Business, Siemens AG, SAP SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Digital Transformation Market Trends and Innovations
Thai enterprises are rearchitecting technology stacks around data sovereignty requirements while adopting AI-driven automation at the operational edge. These shifts compress legacy upgrade cycles and reshape vendor competitive positioning.
Edge computing infrastructure is decentralizing data processing from centralized cloud regions to factory floors and retail locations. Thai automotive suppliers and convenience store chains deploy containerized micro-datacenters to achieve sub-10 millisecond latency for quality inspection and inventory management. This architecture is decentralizing IT decision authority from Bangkok headquarters to provincial operations managers.
Thailand's Personal Data Protection Act enforcement is tightening cross-border data transfer protocols for multinational corporations. The Ministry of Digital Economy and Society requires explicit consent mechanisms and breach notification within 72 hours. Financial services and healthcare providers in Bangkok are responding by localizing customer databases and appointing dedicated data protection officers.
Enterprise buyers in Thailand are consolidating vendor relationships around integrated platform providers rather than best-of-breed point solutions. Procurement committees at Thai banks and manufacturers now prioritize single-contract accountability for cloud, security, and productivity workloads. This pattern is most pronounced in Bangkok's central business district where IT governance complexity drives preference for unified service-level agreements.
Thailand Digital Transformation Market Segmentation
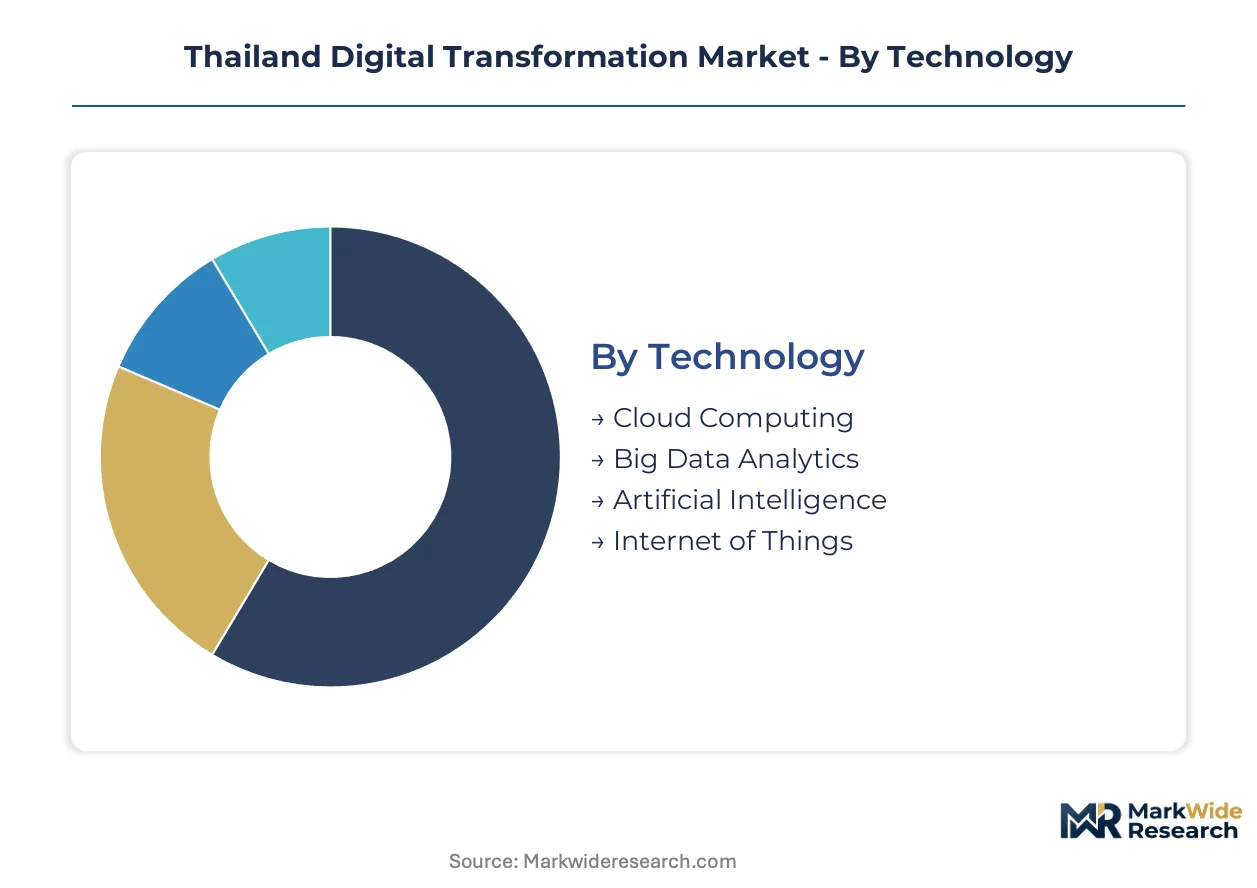
Thailand's digital transformation market fragments across four critical dimensions that shape vendor positioning and procurement patterns. Technology choices determine infrastructure architecture, while deployment models reflect PDPA compliance pressures. Industry verticals concentrate demand in Bangkok's metropolitan cluster, and solution types reveal automation maturity across Thai enterprises.
Technology:
Enterprise buyers in Thailand prioritize technology investments based on implementation risk and immediate productivity impact rather than speculative capabilities.
- Cloud Computing:Distributed infrastructure services spanning compute, storage, and networking resources delivered through subscription models. Thai banking institutions and conglomerates concentrate procurement in Bangkok's availability zones, driven by PDPA-mandated data sovereignty requirements that favor domestic or regional cloud regions.
- Artificial Intelligence:Machine learning platforms and cognitive automation tools enabling predictive analytics and natural language processing. Demand clusters in Thai automotive and electronics manufacturing corridors where computer vision quality inspection and predictive maintenance address Industry 4.0 productivity mandates.
- Big Data Analytics:Data warehousing and business intelligence platforms processing structured and unstructured enterprise information. Thai retail chains and logistics operators deploy these tools for demand forecasting and supply chain optimization.
- Internet of Things:Sensor networks and connected device platforms enabling real-time operational monitoring. Smart city deployments in Bangkok and industrial automation in Eastern Economic Corridor manufacturing zones drive adoption.
Volume sits with cloud computing; growth tilts toward artificial intelligence.
Industry Vertical:
Regulatory intensity and competitive pressure create divergent digital maturity profiles across Thai sectors.
- BFSI:Banking, financial services, and insurance institutions deploy core system modernization and digital payment infrastructure. Thai commercial banks concentrate investment in Bangkok's central business district, responding to Bank of Thailand fintech sandbox opportunities and PDPA compliance deadlines.
- Healthcare:Hospital information systems, telemedicine platforms, and electronic health record digitization. Private hospital chains in Bangkok and provincial medical centers invest in patient data management systems under Ministry of Public Health interoperability standards.
- Retail:Omnichannel commerce platforms and inventory management systems. Thai convenience store networks and department store operators deploy point-of-sale modernization and customer analytics.
- Education:Learning management systems and virtual classroom infrastructure. Thai universities and vocational institutes invest in hybrid delivery platforms following Ministry of Education digital curriculum mandates.
Procurement volume concentrates in BFSI; healthcare claims the steepest expansion trajectory.
Deployment:
Data residency requirements and latency sensitivity shape infrastructure location decisions for Thai enterprises.
- Hybrid Cloud:Integrated architectures combining public cloud elasticity with private infrastructure control. Thai conglomerates favor this model to balance PDPA data localization mandates against scalability needs, particularly in financial services and healthcare sectors.
- Private Cloud:Dedicated infrastructure environments operated for single-tenant use. Thai government agencies and state enterprises deploy these configurations for classified information systems under National Cyber Security Agency guidelines.
- Public Cloud:Multi-tenant infrastructure services operated by hyperscale providers. Thai startups and mid-market enterprises adopt these for cost efficiency in non-sensitive workloads.
- On-Premises:Legacy infrastructure retained in enterprise data centers. Family-owned Thai conglomerates maintain these systems for proprietary ERP installations resisting cloud migration.
Hybrid cloud captures premium pricing; public cloud accounts for volume deployment.
Solution:
Functional automation priorities reflect operational pain points rather than technology novelty.
- Process Automation:Robotic process automation and workflow orchestration tools eliminating manual tasks. Thai manufacturing conglomerates and logistics operators deploy these for procurement and invoice processing in Bangkok headquarters and Eastern Economic Corridor facilities.
- Customer Engagement:CRM platforms and contact center modernization enabling personalized interaction. Thai retail banks and telecommunications providers invest in omnichannel service architecture.
- Digital Marketing:Programmatic advertising and customer data platforms. Thai consumer goods companies and e-commerce operators deploy these for audience targeting and campaign optimization.
- E-Commerce:Online storefront platforms and marketplace integration tools. Thai SMEs and traditional retailers invest in digital sales channels following pandemic-accelerated consumer behavior shifts.
Process automation leads enterprise spending; e-commerce solutions expand most quickly among mid-market adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangkok's metropolitan enterprise cluster concentrates Thailand's digital transformation demand, with financial institutions and conglomerates driving cloud procurement and automation investment across the capital's central business district.
Bangkok Metropolitan Region
Thai commercial banks and family-owned conglomerates headquartered in Bangkok deploy hybrid cloud architectures to satisfy PDPA data localization mandates. The Ministry of Digital Economy and Society enforces compliance timelines that accelerate security spending. Sathorn and Silom districts host the densest concentration of enterprise data center investments and fintech sandbox participants.
Eastern Economic Corridor
Industrial zones in Chonburi and Rayong provinces attract manufacturing automation vendors serving automotive and electronics suppliers. The Eastern Economic Corridor Office coordinates smart factory incentives aligned with Industry 4.0 productivity targets. Laem Chabang port logistics operators deploy IoT-enabled supply chain tracking systems.
Chiang Mai and Northern Region
Digital service providers in Chiang Mai specialize in software development and business process outsourcing for Bangkok-headquartered enterprises. The Thailand Board of Investment promotes regional digital workforce development through specialized training programs. Nimmanhaemin Road technology parks house mid-market SaaS vendors serving provincial retail chains.
Phuket and Southern Tourism Corridor
Hospitality operators across Phuket and Krabi invest in guest experience digitization and operational automation platforms. The Tourism Authority of Thailand mandates digital service standards for international visitor-facing operations. Patong and Kata beach zones concentrate demand for cloud-based property management and payment infrastructure.
Khon Kaen and Northeastern Hub
Agribusiness and food processing enterprises in Khon Kaen province adopt predictive analytics for supply chain optimization. The Ministry of Agriculture and Cooperatives promotes precision farming technology adoption across Isaan region cooperatives. Udon Thani industrial estates host edge computing deployments for quality control in rice and tapioca processing facilities.
Thailand Digital Transformation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance complexity and integration depth. The Thailand digital transformation market structures around three tiers: hyperscale cloud providers commanding infrastructure contracts, enterprise consultancies managing complex ERP modernization programs, and regional systems integrators delivering localized implementation services. Strategic archetypes include PDPA compliance specialists, Industry 4.0 automation vendors, and fintech infrastructure providers. Competitive dynamics center on strategic partnerships with Thai conglomerates and geographic expansion into provincial industrial zones.
Among global technology providers, Microsoft Corporation and Amazon Web Services anchor the hyperscale cloud tier, while SAP SE occupies a position within the enterprise application modernization segment. Accenture PLC exemplifies the consultancy-led transformation archetype. These three entities represent distinct strategic positions: infrastructure platform dominance, ERP system incumbent status, and professional services integration capability respectively.
| Leading Market Players |
|---|
| Accenture PLC |
| Google LLC |
| Microsoft Corporation |
| IBM Corporation |
| Amazon Web Services |
| True Corporation |
| AIS Business |
| Siemens AG |
| SAP SE |
| Others |
Pricing and Supply Chain Analysis
PDPA-mandated data localization requirements are compressing procurement timelines for Thai enterprises and forcing cloud providers to establish domestic infrastructure, which elevates capital intensity and reshapes vendor pricing power toward compliance-certified offerings.
Pricing Analysis
Outcome-based pricing tied to system uptime and transaction throughput anchors enterprise SaaS contracts in Thailand. Subscription tiers stratify across premium compliance-grade, standard business, and economy mid-market levels, with PDPA certification and data residency guarantees commanding material premiums. Cost compression in the mid-market tier is intensifying because local systems integrators compete aggressively on implementation fees. Provincial SMEs exhibit highest price sensitivity, while Bangkok-headquartered banks and conglomerates prioritize single-contract accountability over unit cost.
Supply Chain Analysis
Freight and cross-border data transfer costs are elevating preference for regional cloud regions over distant hyperscale zones. Infrastructure hardware draws from Taiwan, South Korea, and China, while enterprise software licensing rests on US and European parent entities. Single-source vulnerability concentrates in specialized cybersecurity tooling subject to export control restrictions. Distribution runs through Bangkok-based systems integrators with provincial branch networks serving Eastern Economic Corridor manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over compliance-certified data center capacity to defend margin pools against foreign hyperscale entrants.
For Market Incumbents: Anticipate margin compression from Chinese cloud providers entering through Thai joint ventures by deepening backward integration into domestic data center real estate and PDPA certification consulting. Prioritize multi-year anchor tenancy agreements with Bangkok banking conglomerates to lock in revenue visibility. For New Entrants and Emerging Players: Thailand's Personal Data Protection Act opens a window for specialized compliance-as-a-service vendors to capture provincial enterprise demand underserved by global hyperscalers. Target mid-market manufacturers in Chonburi and Rayong with bundled edge computing and data protection officer outsourcing. Lead with fixed-fee PDPA readiness assessments to establish trust before infrastructure upsell. For Investors and Strategic Acquirers: Re-rating potential sits with regional systems integrators possessing PDPA-certified delivery capabilities given accelerating enforcement timelines from Thailand's Ministry of Digital Economy and Society. Frame long-term viability around five-to-ten-year cloud migration runway in family-owned conglomerates. Monitor Bank of Thailand fintech sandbox admission velocity as inflection indicator for digital infrastructure spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Buildout | Captures PDPA-mandated localization demand from Bangkok financial institutions. |
| PDPA Compliance Certification | Creates differentiated positioning against unqualified foreign cloud competitors. |
| Edge Computing Partnership | Enables sub-10 millisecond latency for Eastern Economic Corridor smart factories. |
| Vertical Integration into Cybersecurity | Secures recurring revenue from data protection officer mandates. |
| Provincial Channel Expansion | Accesses underserved mid-market demand in Khon Kaen and Chiang Mai. |
Research Methodology
Independent corroboration across CTO interviews at Thai banking conglomerates, procurement officer discussions at Eastern Economic Corridor manufacturers, and regulatory affairs leads at cloud providers underwrites the qualitative findings. Secondary validation draws from Thailand Ministry of Digital Economy and Society enforcement notices, Bank of Thailand fintech sandbox disclosures, and National Broadcasting and Telecommunications Commission spectrum allocation records. Bottom-up demand modeling and top-down market sizing triangulate to the segment outputs.
Rate-of-change decomposition across technology adoption curves, regulatory compliance deadlines, and infrastructure deployment timelines structures the analytical framework. Segmentation dimensions span deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derive from fitted growth curves against historical spending patterns and policy-mandated investment floors. Forecast inputs include 5G base station rollout schedules and Industry 4.0 productivity target enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for sovereign cloud architectures would alter the outlook. Forecasts reflect assumptions regarding PDPA enforcement consistency and hyperscale provider market entry decisions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
MENA Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Innovation Management Market
Digital Transformation
France Digital Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
Digital Transformation in Supply Chain Market
Digital Transformation
Oman Digital Transformation Market
Digital Transformation
Italy Digital Transformation Market
Digital Transformation
Global Application Transformation Market
Digital Transformation
North America Digital Transformation Market
Digital Transformation
Telco Transformation Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
ASEAN Digital Transformation Market
Digital Transformation
South Korea Digital Transformation Market
Digital Transformation
United States Digital Transformation Market