
 Global Digital Workplace Transformation Service Market | 2026-2036
Global Digital Workplace Transformation Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Workplace Transformation Service Market Foresight
Managed service provider channels is fragmenting as hyperscalers build direct enterprise relationships while regional system integrators defend local accounts. Microsoft leverages its Azure cloud backbone to anchor hybrid deployment conversations with Fortune 500 CIOs. IBM competes through Red Hat OpenShift integrations that sustain mainframe-to-cloud migration pipelines for regulated industries. Accenture differentiates via industry-specific transformation studios that control end-to-end change management contracts.
Digital workplace transformation services encompass the consulting, implementation, and ongoing management of technologies that modernize how employees access applications, collaborate, and execute workflows across distributed environments. These services typically integrate identity management protocols, API-based connectivity layers, and zero-trust security architectures to unify fragmented productivity toolsets into coherent operating environments. Cloud migration and security integration represent the most mature service categories, where margin pools have compressed due to vendor consolidation and automation of baseline assessments. Automation solutions represent the fastest-expanding segment as organizations deploy intelligent process discovery tools to map and eliminate redundant manual workflows before platform migration.
The EU AI Act, GDPR, and ISO 27001 collectively shape procurement requirements by mandating algorithmic transparency in employee monitoring tools and cross-border data residency controls. The US SEC and HIPAA impose additional compliance layers on financial services and healthcare deployments, forcing providers to maintain jurisdiction-specific infrastructure certifications. Stakeholders must monitor whether emerging EU CSRD disclosure rules will extend to carbon accounting for cloud infrastructure supporting workplace platforms, as this would reroute procurement criteria toward providers with verified renewable energy supply chains.
Market Dynamics
Hyperscaler direct enterprise engagement is compressing traditional channel margins while forcing regional integrators to defend accounts through localized compliance expertise and legacy system specialization.
Growth Catalysts
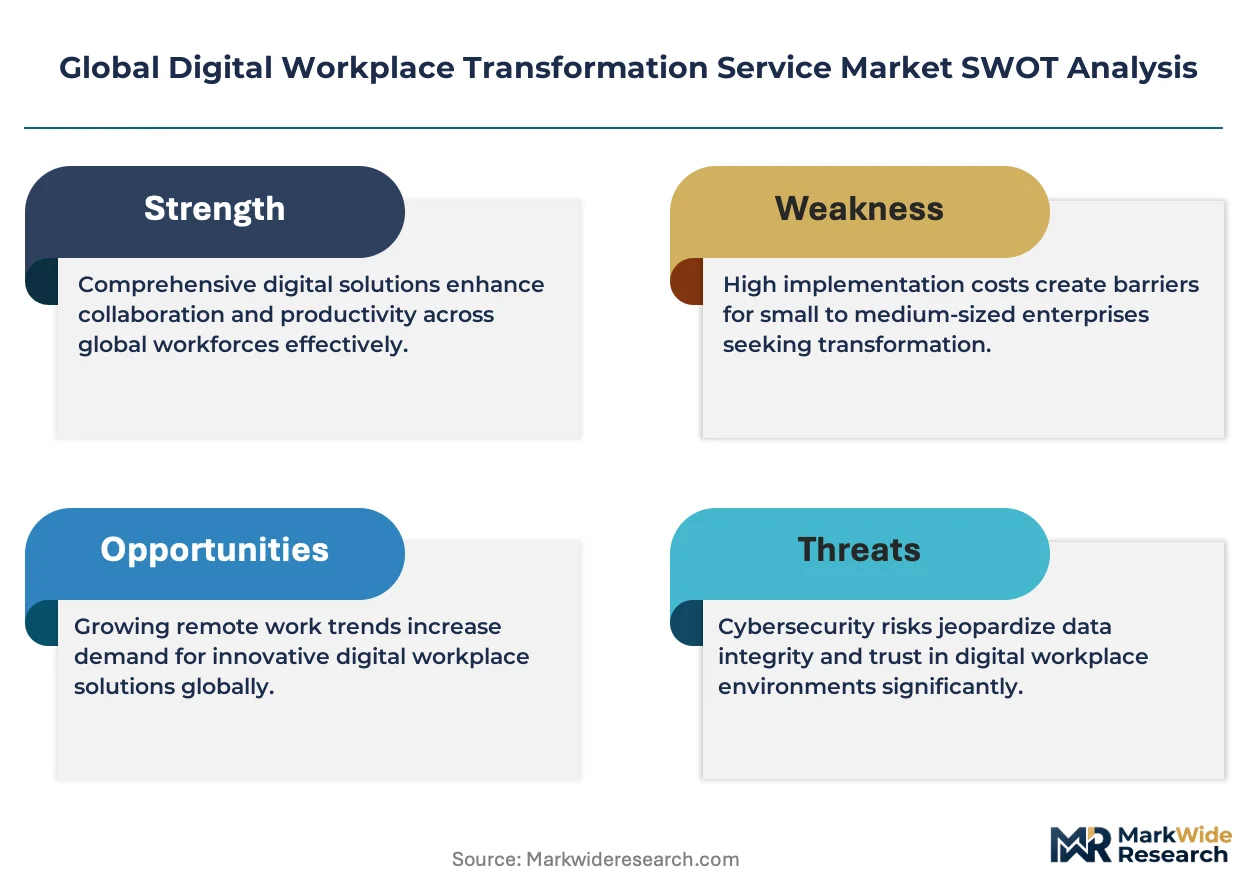
- EU AI Act compliance mandates:Financial institutions in Germany and France must deploy algorithmic transparency tools for employee monitoring, creating immediate procurement urgency for certified workplace platforms.
- Industrial automation convergence:German automotive and machinery manufacturers are integrating shop-floor automation with cloud-based collaboration layers, requiring specialized migration services.
- Zero-trust security architecture:US healthcare and federal contractors under HIPAA and FISMA are rebuilding access protocols, driving replacement cycles for legacy VPN-dependent workplace stacks.
Market Restraints
- Cross-border data residency costs:GDPR Article 44-49 enforcement is forcing providers to maintain redundant EU, UK, and Swiss infrastructure, raising operational overhead for multi-national deployments.
- Legacy mainframe dependency:Banking and insurance clients in Japan and the US retain critical workflows on IBM Z systems, creating integration friction that extends project timelines.
- Substitute internal builds:Large technology firms with captive engineering teams are developing proprietary workplace platforms rather than purchasing managed services.
Strategic Opportunities
- CSRD carbon accounting extension:Pending EU disclosure rules may mandate Scope 3 reporting for cloud infrastructure, advantaging providers with verified renewable energy supply chains.
- Intelligent process discovery:Convergence of process mining with AI-driven workflow mapping creates new service lines for pre-migration redundancy elimination.
- India PLI scheme alignment:Manufacturing incentives are accelerating captive center establishment, creating demand for workplace modernization in Pune and Chennai industrial corridors.
Industry Challenges
- Mainframe-to-cloud skill scarcity:Cobol and assembler expertise required for financial services migration is retiring faster than certification programs can replenish.
- Multi-framework compliance stacking:Simultaneous ISO 27001, SOC 2 Type II, and FedRAMP certification timelines stretch 14-18 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Workplace Transformation Service Market |
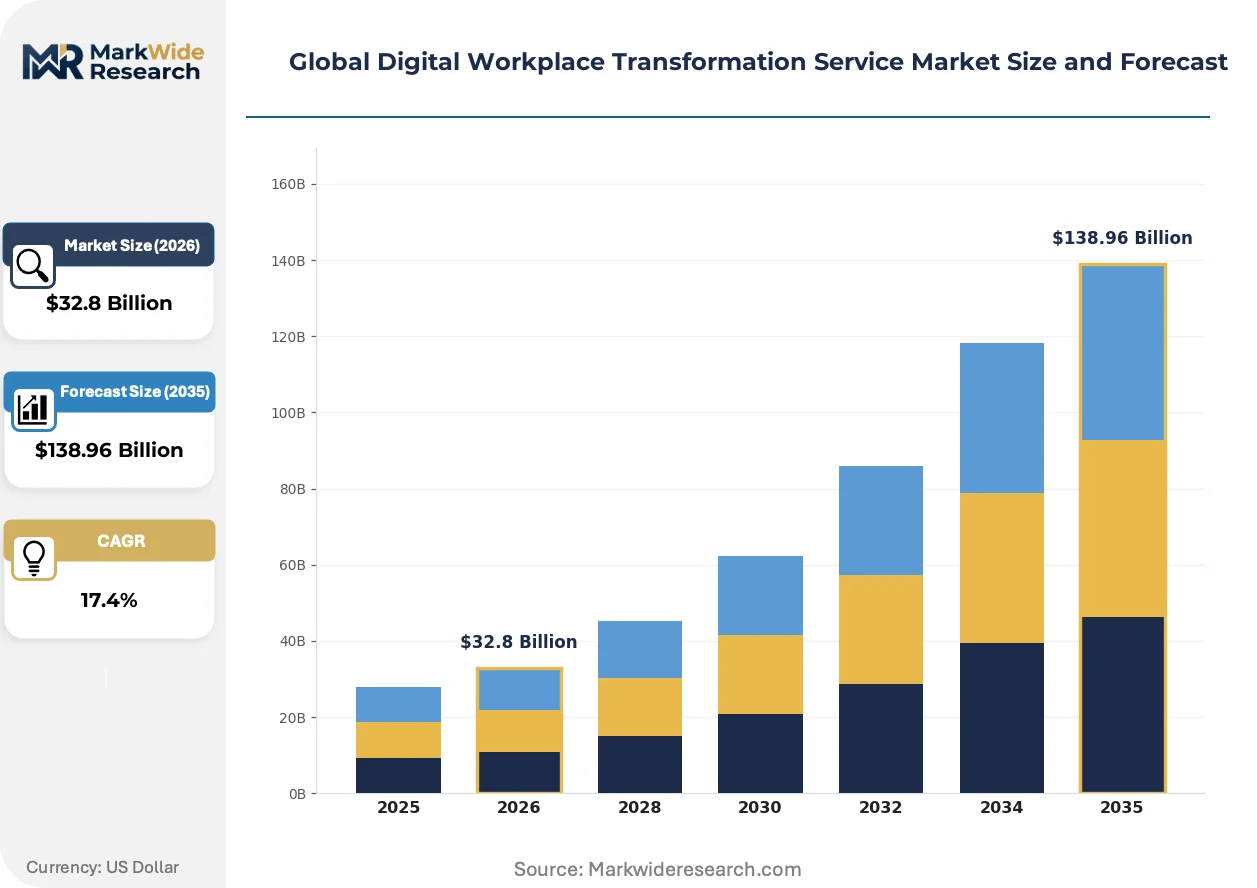
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $138.96 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Migration, Data Analytics, Collaboration Tools, Security Integration, Automation Solutions Application: Remote Work Enablement, Workflow Optimization, Employee Engagement, Knowledge Management, Digital Training End User Industry: Information Technology, Banking and Finance, Telecommunications, Manufacturing, Government Agencies Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | Microsoft, IBM, Accenture, Cisco Systems, Atos, Deloitte, Salesforce, Cognizant, Tata Consultancy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Workplace Transformation Service Market Shifts & Advancements
Agentic AI systems are rewriting service delivery models by automating the discovery and remediation of workflow inefficiencies before human consultants engage. This compression of the assessment phase is redistributing value toward implementation and change management.
Intelligent process discovery platforms are digitizing manual workflow mapping that previously consumed 40% of project hours. Banking and insurance procurement teams in London and Frankfurt are mandating these tools in RFPs. The technology is digitizing baseline assessment work, compressing margins for pure-play consulting while elevating providers with proprietary automation IP.
The EU AI Act's risk classification framework for employee-facing algorithms is forcing providers to maintain dual development tracks. High-risk applications in performance monitoring and biometric access now require conformity assessments before deployment. Financial services and logistics buyers in Germany, France, and the Netherlands are prioritizing vendors with existing notified body relationships.
Subscription-to-outcome contracting is displacing seat-based pricing in enterprise renewals. Manufacturing and energy buyers in Texas and Alberta are tying 30-40% of fees to measurable productivity gains. This shift is visible most acutely in Fortune 500 industrial accounts where CFO scrutiny of SaaS spend has intensified.
Global Digital Workplace Transformation Service Market Segmentation
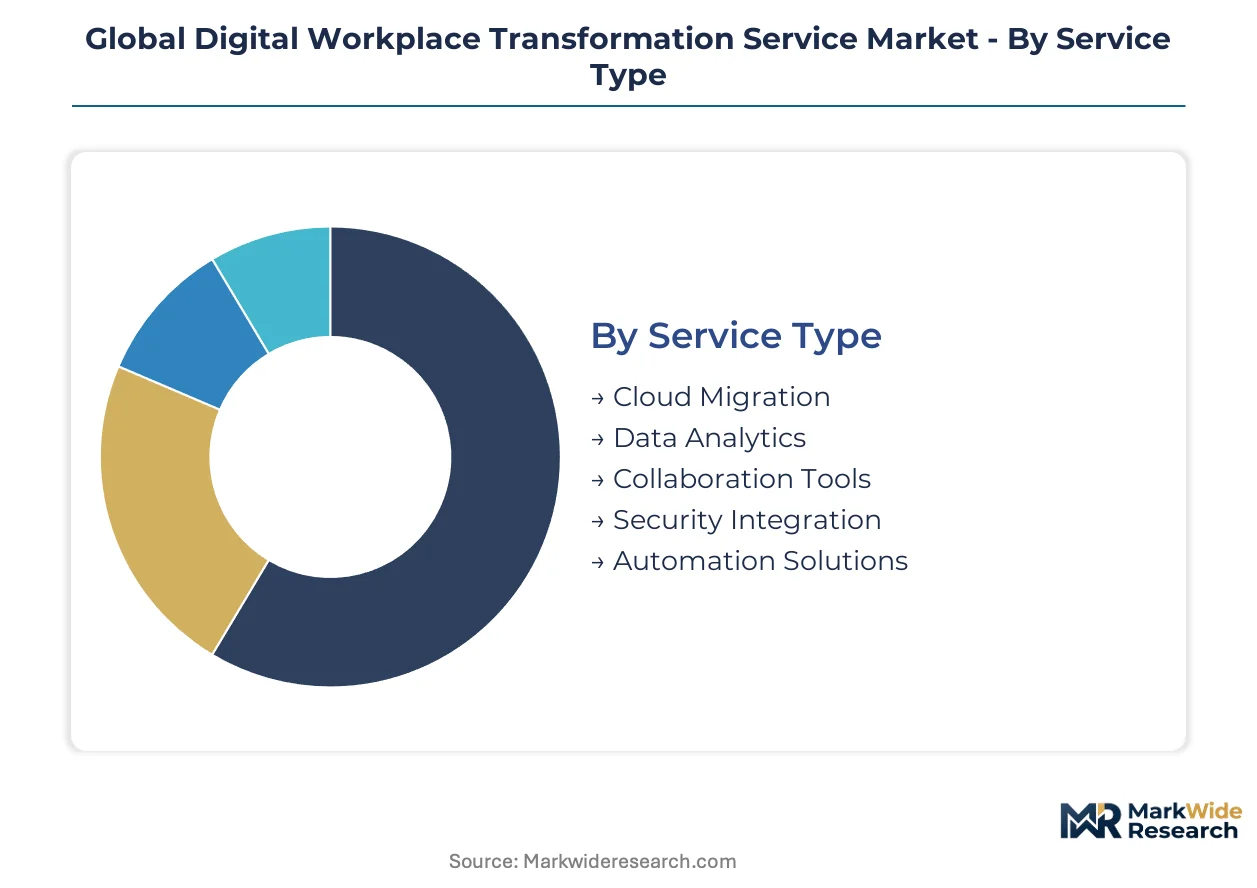
Service differentiation in digital workplace transformation follows the technical maturity of underlying infrastructure. Procurement patterns diverge sharply between organizations modernizing legacy stacks versus those building cloud-native environments from inception.
Service Type:
The use-case spectrum spans foundational infrastructure migration through intelligent automation layers.
- Cloud Migration:Lift-and-shift and re-platforming services dominate revenue pools as enterprises evacuate aging data centers. German automotive manufacturers and US federal contractors under FedRAMP drive sustained demand for certified migration pathways.
- Automation Solutions:Intelligent process discovery and robotic process automation represent the steepest expansion trajectory. Banking procurement teams in London and Frankfurt now mandate pre-migration workflow mapping tools in competitive tenders.
- Security Integration:Zero-trust architecture implementation and identity federation services address post-migration hardening requirements. HIPAA-covered entities and EU GDPR-regulated firms require jurisdiction-specific certification stacks.
- Collaboration Tools:Unified communications platform deployment and Teams/Slack workspace configuration. Demand concentrates in technology sector distributed workforces.
- Data Analytics:Workplace telemetry and productivity measurement dashboard implementation. CSRD-aligned carbon accounting for cloud infrastructure is emerging as a procurement criterion.
The dominant share belongs to Cloud Migration, while Automation Solutions is closing the gap fastest.
Application:
Cost tier segmentation separates baseline connectivity provision from premium change management engagements.
- Workflow Optimization:Process mining and intelligent automation eliminate redundant manual steps before platform migration. Japanese insurance carriers and German machinery producers represent high-intensity demand clusters.
- Remote Work Enablement:Secure access architecture and endpoint management for distributed workforces. Post-pandemic standardization has compressed margins for baseline implementations.
- Employee Engagement:Digital experience platforms and sentiment analytics tools. EU AI Act algorithmic transparency requirements are reshaping vendor qualification criteria.
- Knowledge Management:Enterprise search and institutional memory preservation systems. Professional services firms in New York and London drive specialized capture methodology demand.
- Digital Training:Immersive onboarding and reskilling platform deployment. Manufacturing corridors in Pune and Chennai under India's PLI scheme show accelerating procurement velocity.
Workflow Optimization commands premium pricing, with Employee Engagement gaining share fastest among outcome-based contracts.
End User Industry:
Volume concentration tracks regulatory complexity and legacy system density.
- Banking and Finance:Compliance-driven transformation integrating mainframe workflows with cloud-native collaboration. SEC, HIPAA, and GDPR Article 44-49 enforcement sustains multi-jurisdiction infrastructure requirements.
- Manufacturing:Shop-floor automation convergence with enterprise collaboration layers. German automotive and industrial machinery sectors lead integration complexity.
- Information Technology:Native cloud adoption and developer experience platform deployment. Internal build-versus-buy tension constrains external service penetration.
- Government Agencies:FedRAMP and ISO 27001-certified secure workplace modernization. US federal and EU member state procurement cycles extend 18-24 months.
- Telecommunications:Field workforce enablement and customer service platform unification. Legacy billing system integration creates project friction.
Banking and Finance retains the largest contract value, though Manufacturing is expanding most quickly through industrial automation convergence.
Deployment Model:
Customer type stratification separates cloud-native adopters from regulated entities requiring controlled infrastructure.
- Hybrid Cloud:Workload-optimized distribution across on-premises and public cloud resources. Microsoft Azure and Red Hat OpenShift anchor Fortune 500 architecture decisions.
- Private Cloud:Dedicated infrastructure for data residency and sovereignty requirements. Swiss banking and German automotive procurement teams prioritize certified private deployments.
- Public Cloud:Shared infrastructure for non-sensitive collaboration and productivity workloads. Margin compression from hyperscaler direct engagement is forcing provider specialization.
- On-Premises:Air-gapped or latency-critical systems in defense and critical infrastructure. Japan and US federal requirements sustain this category despite cloud migration pressure.
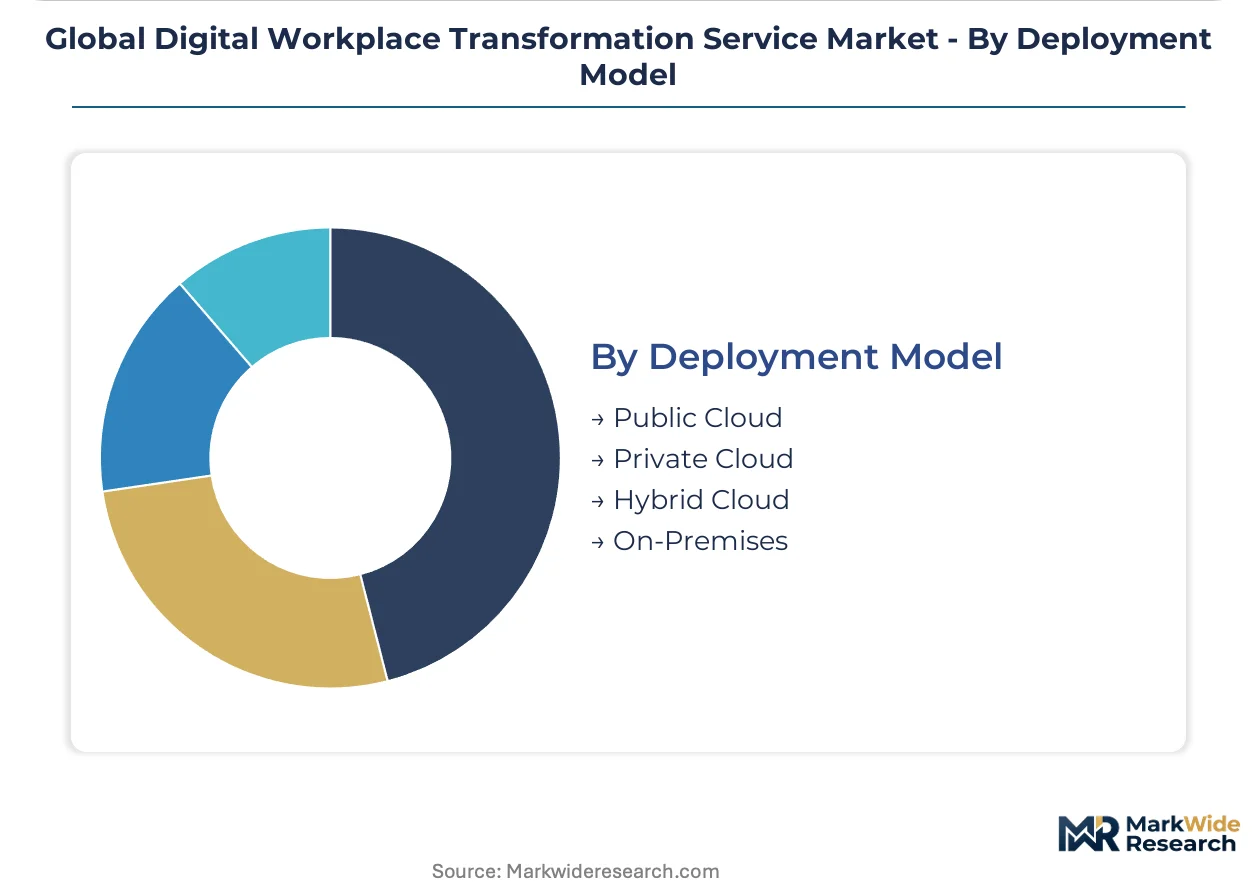
Hybrid Cloud dominates current procurement, with Private Cloud climbing the fastest under EU data residency enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Cologne high-speed rail corridor and the Rhine-Main logistics network position Germany as the continental anchor for industrial workplace modernization across the European Union.
United States
FedRAMP certification requirements and HIPAA enforcement drive federal and healthcare procurement cycles. The SEC mandates algorithmic transparency for employee monitoring tools in financial services. Technology corridors in Seattle and Austin concentrate cloud-native workplace deployments for enterprise software firms.
Germany
Automotive and machinery manufacturers integrate shop-floor automation with enterprise collaboration layers. The EU AI Act and GDPR Article 44-49 enforcement require dual-track development for high-risk employee-facing algorithms. Industrial clusters in Stuttgart and Munich anchor demand for hybrid cloud migration services.
United Kingdom
Financial services firms in London rebuild workplace stacks for post-Brexit data sovereignty requirements. The Financial Conduct Authority and Information Commissioner's Office impose layered compliance on cross-border collaboration tools. The Thames Valley technology corridor sustains demand for zero-trust security architecture implementations.
India
Manufacturing incentives under the PLI scheme accelerate captive center establishment in industrial corridors. RBI and SEBI regulations govern financial services workplace modernization for compliance workflows. Pune and Chennai manufacturing zones drive procurement velocity for digital training and reskilling platforms.
Japan
Insurance carriers and banking institutions retain critical workflows on IBM Z mainframe systems, creating integration friction. METI guidelines shape industrial automation convergence with cloud-based collaboration. Tokyo and Osaka financial districts sustain demand for specialized mainframe-to-cloud migration expertise.
Global Digital Workplace Transformation Service Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct tiers: hyperscalers with direct enterprise relationships, global system integrators with industry-specific studios, and regional specialists defending local accounts through compliance expertise. Strategic archetypes include cloud-native platform anchors, legacy-to-cloud migration specialists, and automation-first consultancies. Dominant competitive moves encompass strategic partnerships with hyperscaler infrastructure providers and vertical portfolio diversification into adjacent security and analytics services.
Within the hyperscaler tier, Microsoft and IBM occupy positions as platform anchors for hybrid deployment conversations. Accenture exemplifies the global integrator archetype with industry-specific transformation capabilities. These three entities represent the primary competitive vectors shaping procurement criteria across Fortune 500 accounts, with each anchoring distinct technology ecosystems that influence downstream service provider positioning.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Accenture |
| Cisco Systems |
| Atos |
| Deloitte |
| Salesforce |
| Cognizant |
| Tata Consultancy Services |
| Others |
Supply & Pricing Matrix
Overcapacity in Indian IT services delivery centers is compressing billable rates for baseline cloud migration work while simultaneously pushing providers toward higher-margin automation and security integration offerings. German automotive manufacturers and US federal contractors now demand certified compliance architectures that sustain premium pricing tiers despite commoditization pressure elsewhere.
Pricing Analysis
Volume-discount tiering separates Fortune 500 anchor clients from mid-market accounts and regional implementations. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FedRAMP and ISO 27001 compliance commanding substantial premiums. Cost compression in baseline cloud migration is intensifying because hyperscaler direct sales bypass traditional channel markups. Mid-market manufacturing accounts in India and Southeast Asia exhibit highest price sensitivity, while Swiss banking and German automotive procurement teams prioritize compliance over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced AI chips and quantum encryption technologies are fragmenting cross-border service delivery capabilities. Talent supply concentrates in India, Poland, and Vietnam for delivery capacity, while solution architecture expertise clusters in Germany, the United Kingdom, and the United States. Raw material dependencies include specialized semiconductor components for zero-trust hardware, proprietary process mining software licenses, and certified data center infrastructure. Single-source vulnerability in mainframe-to-cloud migration skills creates bottleneck risk. Distribution runs through hyperscaler marketplaces, direct enterprise sales teams, and regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positions. Switching costs for embedded workplace platforms compound as compliance certifications stack across multiple jurisdictions.
For Market Incumbents: Pre-empt margin erosion in baseline cloud migration by embedding intelligent process discovery tools into standard service catalogs before pure-play automation specialists scale. Vertical integration into proprietary AI-driven workflow mapping IP creates differentiation against hyperscaler direct engagement. Defend German automotive and Swiss banking accounts through accelerated EU AI Act conformity assessment capabilities. For New Entrants and Emerging Players: Mid-market commercial buildings and industrial facilities in India's PLI scheme corridors represent the most penetrable entry point, where captive center establishment outpaces incumbent service coverage. Specialized mainframe-to-cloud migration expertise for Japanese insurance carriers offers second-mover advantage as retirement-driven skill scarcity intensifies. Go-to-market execution through hyperscaler marketplace listings reduces customer acquisition friction. For Investors and Strategic Acquirers: Capital is best deployed toward automation-first consultancies with proprietary process mining IP and established notified body relationships for EU AI Act compliance. Long-term viability across the analysis window hinges on regulatory certification depth rather than scale economics. Watch for CSRD carbon accounting mandate expansion as inflection signal for provider renewable energy supply chain verification.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Process mining boutiques with automotive sector relationships command premium multiples. |
| Platform Integration | Red Hat OpenShift and Azure backbone anchoring sustains mainframe migration pipelines. |
| Geographic Expansion | Pune and Chennai industrial corridors under PLI scheme accelerate digital training demand. |
| Strategic Partnership | Notified body relationships for EU AI Act conformity assessments create procurement preference. |
| Product Launch | Agentic AI workflow discovery tools compress assessment phases and elevate implementation margins. |
Research Methodology
A spread of perspectives from CIOs at Fortune 500 manufacturers, compliance officers at EU-regulated financial institutions, channel partners in hyperscaler ecosystems, and procurement leads at German automotive firms converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory implementation guidance, and ISO certification registry data. Bottom-up service line buildups triangulated against top-down macroeconomic demand models.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include service type, deployment model, end-user industry vertical, and regional regulatory cluster complexity. CAGRs derived from historical trajectory analysis adjusted for policy implementation timelines and technology substitution curves. Forecast inputs incorporated EU AI Act enforcement phase-ins and mainframe skill retirement velocity.
Practitioners should monitor regulatory enforcement intensity, hyperscaler direct sales expansion, and CSRD disclosure rule finalization for early signals. Forecasts reflect documented assumptions on compliance timeline adherence and technology adoption S-curves. Material shifts in EU AI Act risk classification scope or mainframe-to-cloud migration automation breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Global Application Transformation Market
Digital Transformation
Germany Digital Transformation Market
Digital Transformation
Netherlands Digital Transformation Market
Digital Transformation
North America Digital Transformation Market
Digital Transformation
Oman Digital Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
Telco Transformation Market
Digital Transformation
Malaysia Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
Indonesia Digital Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
Australia and New Zealand Digital Transformation Market
Digital Transformation
Innovation Management Market