
 Digital Platform Scale Market | 2026-2036
Digital Platform Scale Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Platform Scale Market Insights
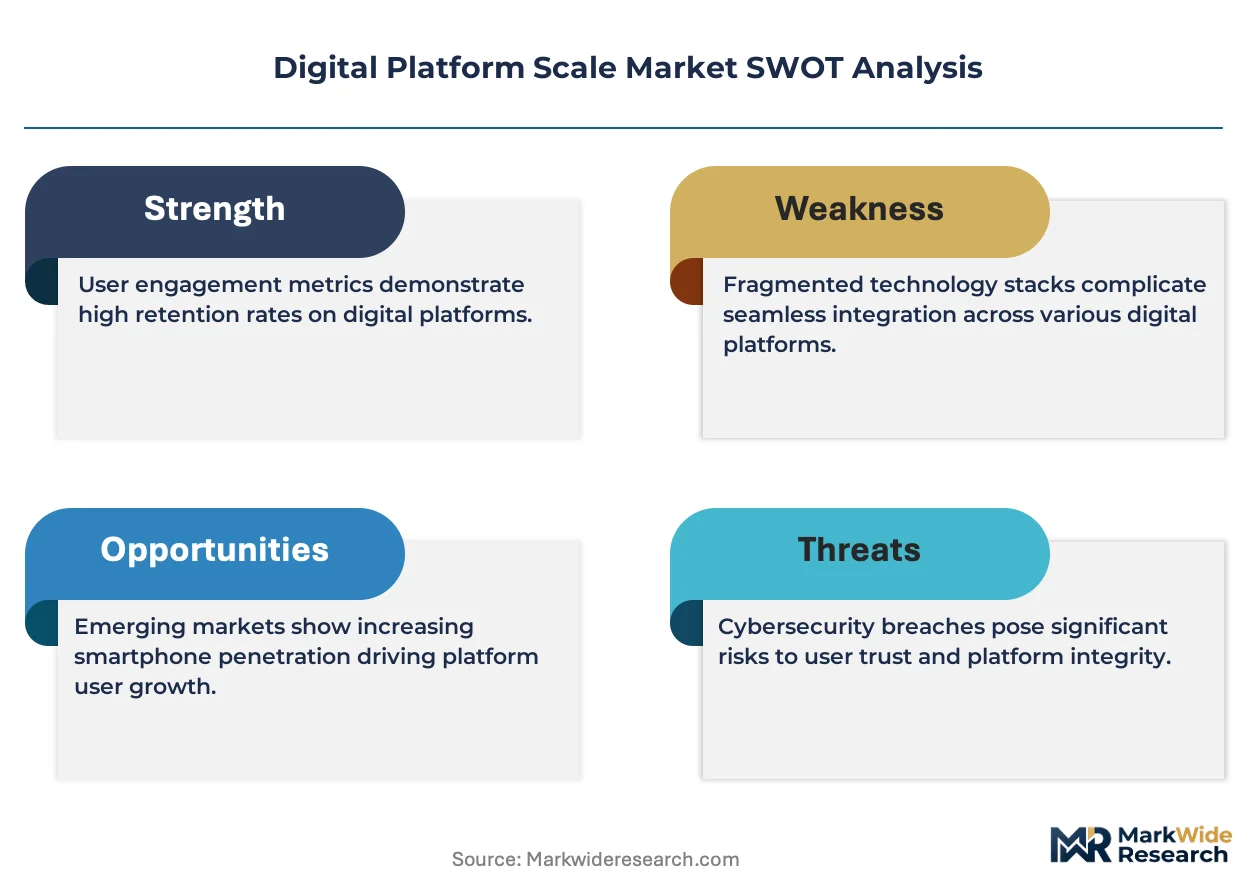
Asset-light leasing and subscription-based financing for precision weighing equipment is narrowing the competitive field to vendors with strong balance sheets and recurring revenue infrastructure. Mettler Toledo leverages its global service network to bundle hardware with cloud analytics subscriptions. Rice Lake Weighing Systems anchors its position through captive manufacturing of load cells and indicators in North America. Adam Equipment competes aggressively on freemium software tiers that reduce upfront capital barriers for mid-sized food processors.
Digital platform scales integrate strain-gauge or electromagnetic force-compensation load cells with embedded processors, touchscreen interfaces, and wireless connectivity to capture, store, and transmit weight data for inventory, trade, or regulatory compliance. The primary purpose spans commercial transaction verification, industrial process control, and traceability mandates in food, pharmaceutical, and logistics chains. Enterprise Resource Planning platform types dominate installed value as manufacturers demand seamless weight-data feeds into SAP and Oracle environments. Cloud-Native deployment is expanding fastest among third-party logistics operators managing distributed warehouse networks. Data Management platforms concentrate margin pools where calibration records and audit trails command premium pricing for pharmaceutical and chemical clients.
The National Type Evaluation Program (NTEP) in the United States and the EU's Measuring Instruments Directive (MID) enforce legal-for-trade accuracy classes, forcing sensor upgrades and recertification cycles that sustain replacement demand. ISO 9001 quality management and IEC 61508 functional safety standards further segment vendor eligibility for hazardous-area installations in oil and gas or chemical processing. Stakeholders must weigh captive cloud infrastructure investments against multi-tenant architectures as cybersecurity frameworks harden around connected industrial equipment.
Market Dynamics
Cloud-native deployment architectures are forcing sensor manufacturers to rebuild software stacks around real-time data pipelines rather than standalone hardware margins.
Growth Catalysts
- EU MID Recertification Mandates:Germany's food processing sector faces compulsory sensor upgrades under Measuring Instruments Directive accuracy classes, triggering replacement cycles across industrial automation investments.
- Strain-Gauge Load Cell Integration:Embedded processors with wireless connectivity enable seamless weight-data feeds into SAP and Oracle ERP environments, accelerating enterprise adoption.
- Third-Party Logistics Networks:Distributed warehouse operators in the United States demand real-time weight synchronization across cloud-native platforms for inventory optimization.
Market Restraints
- Semiconductor Component Volatility:Embedded processor and wireless module supply concentrates in East Asian foundries, exposing manufacturers to input cost swings and allocation constraints.
- Legal-for-Trade Certification Friction:NTEP approval timelines in the United States extend 12-18 months for new sensor platforms, delaying revenue recognition on next-generation products.
- Mechanical Scale Substitution:Low-cost analog weighing systems retain installed base in emerging market logistics where connectivity infrastructure remains underdeveloped.
Strategic Opportunities
- Pharmaceutical Calibration Services:FDA 21 CFR Part 11 compliance requirements for electronic records create premium-margin pools around audit-trail data management and automated calibration scheduling.
- India Cold Chain Expansion:FSSAI traceability mandates for perishable goods distribution drive demand for connected platform scales in temperature-controlled logistics infrastructure.
- AI-Edge Sensor Fusion:Machine learning inference at the load-cell level enables predictive maintenance and anomaly detection, converging weighing hardware with industrial IoT analytics stacks.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time operating system development for IEC 61508 functional safety certification requires specialized skill sets concentrated among automotive and aerospace software engineers.
- Multi-Tenant Cloud Security Hardening:Cybersecurity frameworks for connected industrial equipment demand continuous compliance monitoring against evolving NIST standards, stretching vendor operational bandwidth.
- Legacy RS-232 Integration Complexity:Brownfield manufacturing environments in chemical processing retain serial-connected indicators, complicating wireless retrofit deployments without production line disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Platform Scale Market |
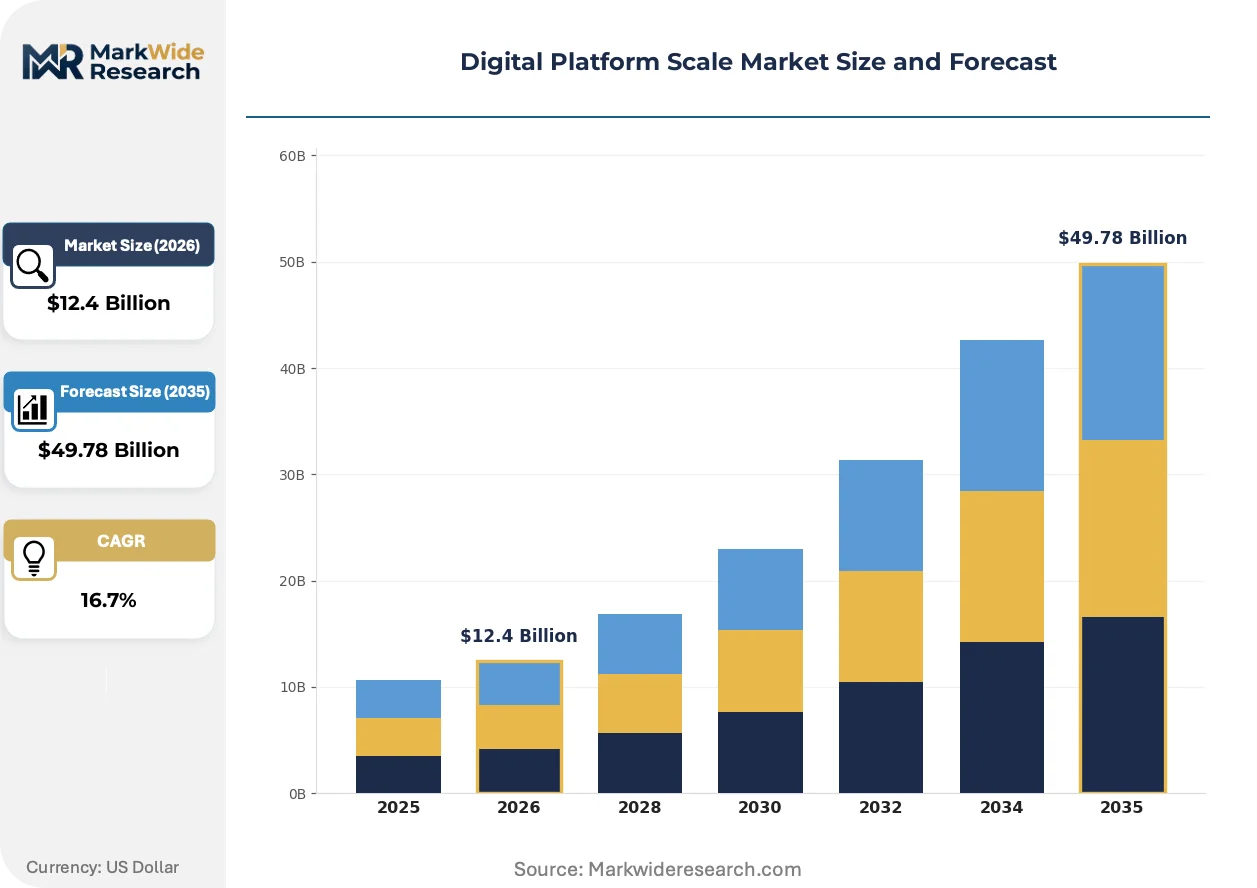
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $49.78 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Mode: Cloud-Native, On-Premises, Hybrid Cloud, Multi-Cloud Platform Type: Enterprise Resource Planning, Customer Experience, Data Management, Developer Tools, Analytics Platforms Target Industry: Financial Services, Telecommunications, Manufacturing, Public Sector, Transportation Business Model: Subscription, Freemium, Pay-As-You-Go, Licensing, Usage-Based Billing |
| Companies Covered | Mettler Toledo, A&D Company, Ohaus Corporation, Rice Lake Weighing Systems, Sartorius Group, Adam Equipment, Avery Weigh-Tronix, Fairbanks Scales, Kern & Sohn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Platform Scale Market Trends and Innovations
Electromagnetic force-compensation technology is collapsing the performance gap between laboratory-grade precision and industrial durability, reshaping buyer expectations across regulated industries.
Strain-gauge load cells with integrated edge processors are collapsing the traditional separation between measurement hardware and data infrastructure. Pharmaceutical manufacturers in Switzerland and Germany now specify embedded Linux environments with containerized analytics as standard procurement criteria. This convergence compresses vendor differentiation toward software-defined calibration workflows rather than raw sensor accuracy specifications.
REACH substance restrictions on load-cell adhesives and RoHS lead-free soldering mandates are accelerating material science investment across European manufacturing footprints. Sensor housings must now demonstrate compliance with both chemical safety and electromagnetic compatibility directives to maintain CE marking eligibility. German industrial automation buyers increasingly disqualify vendors lacking documented full-material-declaration databases.
Subscription-based financing for precision weighing equipment is displacing outright purchase contracts among mid-sized food processors facing capital constraint pressures. Third-party logistics operators in the Netherlands and Belgium now specify usage-based pricing tied to transaction volume rather than hardware depreciation schedules. This shift transfers balance-sheet risk to vendors while demanding recurring revenue infrastructure that smaller sensor manufacturers struggle to provision.
Digital Platform Scale Market Segmentation
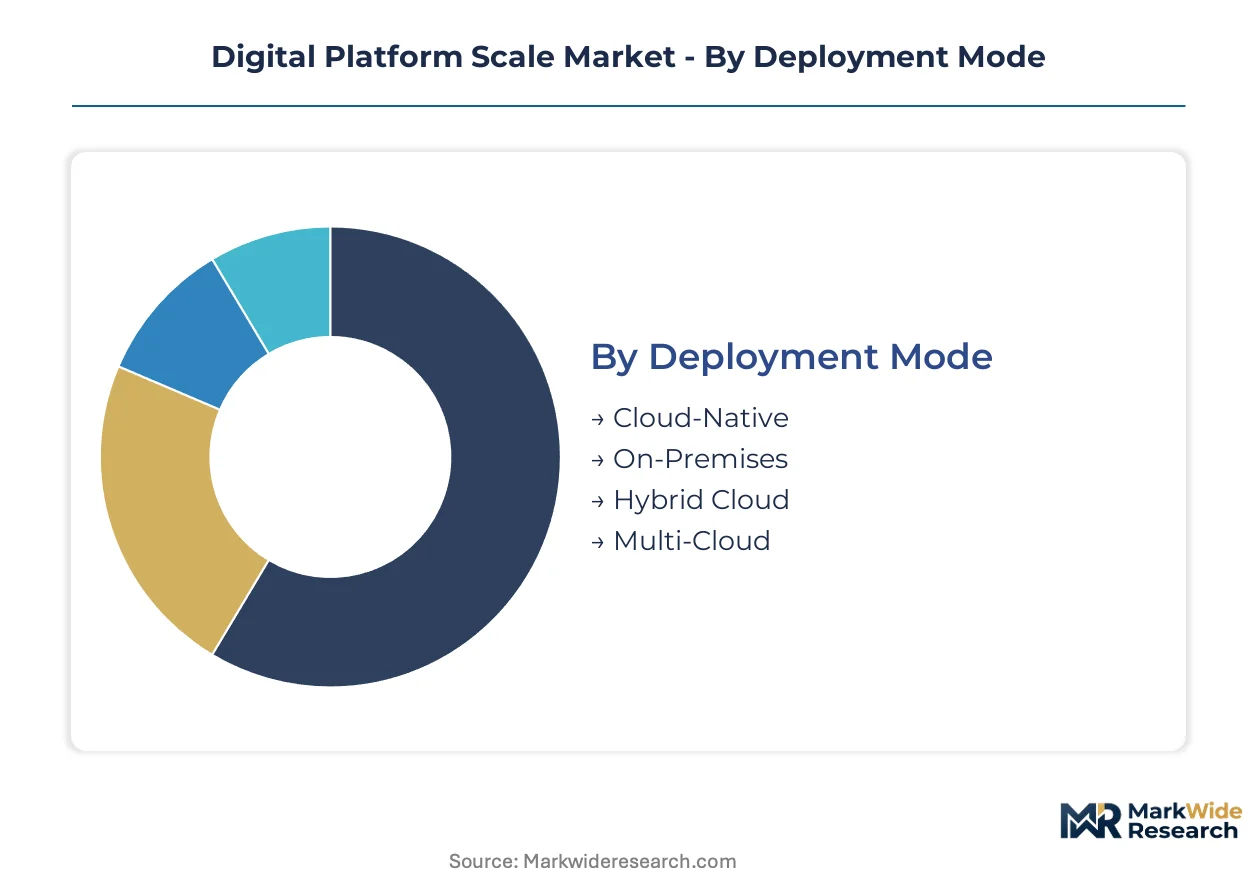
Deployment architecture and platform integration depth determine vendor viability in digital platform scales, as buyers prioritize seamless ERP connectivity and flexible financing over standalone hardware specifications.
Deployment Mode:
Cloud-native architectures span distributed logistics networks requiring real-time weight synchronization, while on-premises systems retain dominance in regulated manufacturing environments with strict data sovereignty requirements.
- Cloud-Native:Containerized microservices enable elastic scaling for third-party logistics operators managing multi-warehouse inventory visibility. Demand concentrates among Dutch and Belgian distribution hubs seeking usage-based operational expenditure models rather than capital-intensive hardware depreciation.
- On-Premises:Dedicated server installations host calibration databases and audit trails for pharmaceutical manufacturers under FDA 21 CFR Part 11 compliance mandates. German chemical processors specify air-gapped environments to satisfy IEC 61508 functional safety certification for hazardous-area installations.
- Hybrid Cloud:Split architectures process sensitive weight data locally while pushing analytics workloads to public infrastructure, appealing to mid-sized food processors navigating EU MID recertification timelines.
- Multi-Cloud:Redundant deployments across competing hyperscaler environments mitigate vendor lock-in risks for enterprise-scale logistics networks with continental coverage requirements.
Established volume favors On-Premises; emerging adoption favors Cloud-Native.
Platform Type:
Integration depth with enterprise software stacks separates premium-margin offerings from commodity hardware, as buyers demand pre-certified connectors rather than custom API development.
- Enterprise Resource Planning:Native SAP and Oracle connectors dominate procurement specifications among industrial automation buyers in Germany, where seamless weight-data feeds into production planning systems justify sensor upgrade investments.
- Data Management:Calibration record repositories and automated audit-trail generation command premium pricing from Swiss pharmaceutical manufacturers facing Swissmedic inspection protocols.
- Customer Experience:Branded portal interfaces for shipment tracking attract third-party logistics operators competing on transparency metrics in competitive freight markets.
- Analytics Platforms:Predictive maintenance algorithms applied to load-cell degradation patterns gain traction among chemical processors seeking to minimize unplanned downtime in continuous production environments.
- Developer Tools:Open API ecosystems enable custom integration with legacy warehouse management systems, addressing brownfield manufacturing environments with entrenched RS-232 serial infrastructure.
Revenue concentration sits with Enterprise Resource Planning; steepest expansion trajectory belongs to Data Management.
Target Industry:
Regulatory stringency and traceability mandates create divergent procurement patterns across verticals, with food and pharmaceutical compliance requirements driving replacement cycles distinct from capital-intensive manufacturing.
- Manufacturing:Industrial automation investments in Germany prioritize MID-certified precision for process control applications, with strain-gauge platforms replacing mechanical systems in assembly-line quality verification.
- Transportation:Freight billing accuracy demands drive cloud-native adoption among third-party logistics networks, where real-time weight synchronization across distributed warehouses optimizes load consolidation.
- Financial Services:Bullion and currency handling operations specify electromagnetic force-compensation technology for transaction-grade precision, particularly in Swiss vaulting and precious metals trading infrastructure.
- Public Sector:Postal and customs applications favor ruggedized platforms with extended calibration intervals, reflecting budget constraints and remote maintenance access limitations.
- Telecommunications:Equipment weight verification for cell tower installations and data center rack loading represents a niche specification segment with moderate growth.
Replacement intensity defines Manufacturing; network effects dominate Transportation.
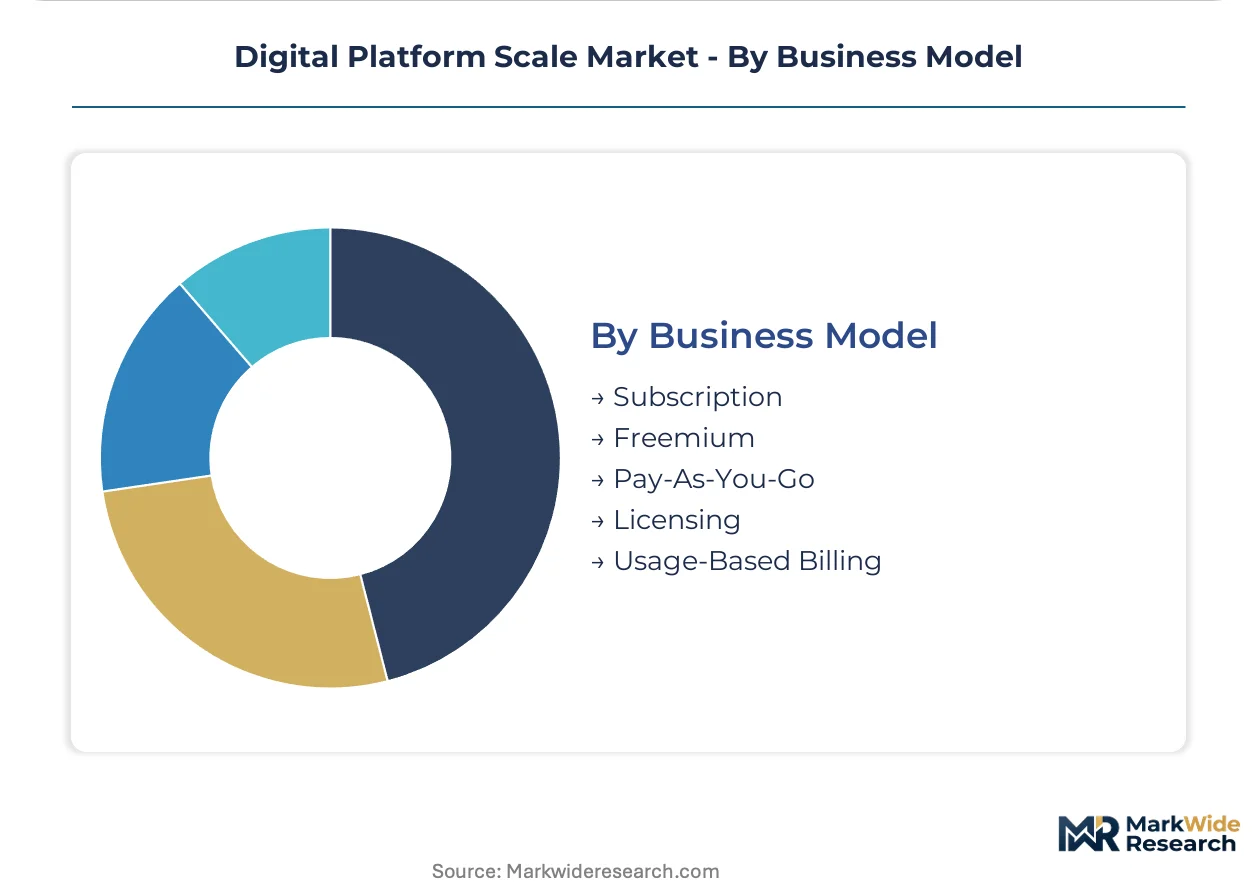
Business Model:
Capital availability and operational expenditure preferences reshape competitive dynamics, as asset-light structures transfer balance-sheet risk to vendors with sufficient recurring revenue infrastructure.
- Subscription:Monthly hardware-plus-software bundles from established service networks displace outright purchase contracts among mid-sized food processors facing working capital constraints.
- Usage-Based Billing:Per-transaction pricing aligns vendor incentives with logistics operator volume growth, particularly in Netherlands-Belgium corridor distribution hubs with seasonal demand fluctuation.
- Freemium:Tiered software access reduces upfront barriers for smaller processors, with premium analytics and compliance modules monetizing regulatory complexity.
- Pay-As-You-Go:Elastic scaling without minimum commitments appeals to pilot deployments and temporary logistics capacity expansions.
- Licensing:Perpetual software rights with maintenance contracts retain favor among conservative manufacturing procurement functions with rigid capital approval processes.
Contract velocity favors Subscription; margin expansion favors Usage-Based Billing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation buyers in Germany, food processors in Switzerland, and third-party logistics operators in the Netherlands represent the three dominant procurement archetypes shaping regional demand patterns for precision weighing infrastructure.
Germany
Industrial automation investments in Bavaria and Baden-Württemberg drive replacement cycles for MID-certified strain-gauge platforms. The Measuring Instruments Directive enforces legal-for-trade accuracy classes that compel sensor upgrades across automotive assembly lines. Stuttgart's precision engineering cluster hosts manufacturing facilities where process control applications demand seamless ERP integration.
United States
Third-party logistics networks across Chicago and Dallas-Fort Worth metro areas prioritize cloud-native deployments for distributed warehouse synchronization. NTEP approval timelines extend 12-18 months for new sensor platforms, delaying revenue recognition on next-generation products. Memphis distribution hubs specify real-time weight data feeds into Oracle and SAP environments for freight billing accuracy.
Switzerland
Pharmaceutical manufacturers in Basel and Geneva command premium-margin calibration services under Swissmedic inspection protocols. Electromagnetic force-compensation technology dominates bullion vaulting and precious metals trading infrastructure. Zurich-based chemical processors specify air-gapped environments to satisfy IEC 61508 functional safety certification for hazardous-area installations.
Netherlands
Rotterdam and Amsterdam distribution corridors adopt usage-based pricing models tied to transaction volume rather than hardware depreciation schedules. Containerized microservices enable elastic scaling for multi-warehouse inventory visibility among Dutch and Belgian logistics operators. The Randstad logistics cluster leads adoption of subscription-based financing for precision weighing equipment.
India
FSSAI traceability mandates for perishable goods distribution drive connected platform scale demand in Maharashtra and Gujarat cold chain infrastructure. Mumbai and Ahmedabad logistics hubs face capital constraints that favor freemium software tiers reducing upfront barriers. The country's national food safety regulator enforces documentation requirements that sustain replacement demand for cloud-connected weighing systems.
Digital Platform Scale Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered vendor structure where balance-sheet strength determines financing option breadth. Consolidation concentrates among service-network operators bundling hardware with recurring analytics subscriptions, while fragmentation persists among regional load-cell fabricators. Two strategic archetypes dominate: integrated multinationals with captive cloud infrastructure and mid-sized specialists with captive manufacturing of core sensor components. Competitive moves center on portfolio diversification into calibration services and backward integration into load-cell production.
Within the integrated multinational tier, Mettler Toledo and Sartorius Group exemplify channel-controlling archetypes with established recurring revenue infrastructure. Rice Lake Weighing Systems occupies a position among North American specialists emphasizing captive manufacturing of indicators and load cells. These three anchors represent distinct competitive vectors: global service network scale, precision laboratory heritage, and regional supply-chain control respectively.
| Leading Market Players |
|---|
| Mettler Toledo |
| A&D Company |
| Ohaus Corporation |
| Rice Lake Weighing Systems |
| Sartorius Group |
| Adam Equipment |
| Avery Weigh-Tronix |
| Fairbanks Scales |
| Kern & Sohn |
| Others |
Pricing and Supply Chain Analysis
Stuttgart's precision engineering cluster anchors European load-cell fabrication capacity, concentrating upstream component supply and granting incumbent manufacturers outsized pricing leverage over mid-sized food processors facing MID recertification deadlines. Cost-plus contracts with quarterly semiconductor indexation dominate procurement agreements, transferring foundry volatility downstream while preserving margin buffers for vendors with captive manufacturing.
Pricing Analysis
Cost-plus contracts with quarterly semiconductor indexation structure vendor-buyer relationships, embedding raw material pass-through clauses that shield manufacturers from foundry volatility. Price differentiation hinges on MID certification tier and ERP integration depth, with SAP-native platforms commanding premium positioning over serial-connected legacy systems. Pricing pressure stems from subscription financing adoption among capital-constrained processors, compressing upfront hardware margins. Mid-sized food processors exhibit highest price sensitivity, while pharmaceutical manufacturers under Swissmedic protocols show lowest elasticity due to compliance-driven procurement.
Supply Chain Analysis
Aluminum alloy feedstock and strain-gauge resistive elements draw from German, Japanese, and Taiwanese metallurgical suppliers, with specialized adhesive chemistries sourced from Swiss and German specialty chemical producers. Embedded processors and wireless modules rest on East Asian foundry output, creating single-source vulnerability around semiconductor allocation cycles. Distribution runs through authorized service networks rather than direct OEM channels, with Mettler Toledo and Sartorius maintaining captive installation and calibration infrastructure across key logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where ERP-native interoperability determines vendor viability, with SAP and Oracle ecosystem certification now functioning as the primary competitive moat rather than raw sensor precision.
For Market Incumbents: Pre-empt cloud-native challengers by bundling hardware with predictive maintenance analytics subscriptions, leveraging existing service network density to capture usage-based billing revenue before mid-sized specialists build recurring infrastructure. Backward integration into electromagnetic force-compensation cell production secures margin control against East Asian component volatility. For New Entrants and Emerging Players: Establish a beachhead in India's FSSAI-mandated cold chain segment, where capital constraints and traceability requirements create appetite for freemium software tiers with modular compliance upgrades. Target Maharashtra and Gujarat logistics hubs with containerized microservices architectures that bypass legacy ERP integration complexity. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription financing is displacing outright purchase contracts and transferring balance-sheet risk to vendors with sufficient service network scale. Acquisition targets should demonstrate captive load-cell manufacturing and existing cloud-native deployment pipelines. The signal to watch is NTEP approval velocity for AI-edge sensor platforms, indicating which vendors can compress 12-18 month certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Containerized microservices enable elastic scaling for Dutch and Belgian logistics operators managing multi-warehouse networks. |
| Backward Integration into Load-Cell Production | Captive manufacturing of strain-gauge cells insulates Rice Lake Weighing Systems from East Asian semiconductor allocation volatility. |
| Subscription-Based Financing Rollout | Monthly hardware-plus-software bundles displace capital-intensive purchase contracts among mid-sized German food processors. |
| FDA 21 CFR Part 11 Compliance Module Development | Automated audit-trail generation commands premium pricing from Basel pharmaceutical manufacturers under Swissmedic protocols. |
| AI-Edge Sensor Fusion Investment | Machine learning inference at the load-cell level converges weighing hardware with industrial IoT analytics stacks for predictive maintenance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating plant engineers at German automotive assembly lines, procurement leads at Dutch third-party logistics networks, calibration service directors at Swiss pharmaceutical manufacturers, and aftermarket heads at North American weighing equipment distributors. Secondary validation drew from EU MID certification databases, NTEP approval filings, SAP and Oracle partner ecosystem directories, and customs records for load-cell component trade flows. Bottom-up unit economics triangulated against top-down market sizing across deployment mode, platform type, and target industry dimensions.
Calibration against historical replacement cycles and regulatory mandate timelines anchored the analytical framework, with segmentation modeling spanning cloud-native, on-premises, hybrid cloud, and multi-cloud deployment architectures alongside ERP, data management, and analytics platform types. CAGRs were derived from installed base depreciation curves and compliance-driven upgrade elasticities, incorporating semiconductor supply volatility and certification timeline uncertainty as scenario variables across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in industrial automation capital expenditure cycles or East Asian foundry utilization rates would shift the trajectory. Forecasts reflect documented assumptions around MID recertification enforcement intensity and cloud-native adoption elasticity among logistics operators. Cross-checking against EU industrial production indices and NTEP approval queue lengths is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Telco Transformation Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
Malaysia Digital Transformation Market
Digital Transformation
Brazil Digital Transformation Market
Digital Transformation
North America Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
UK Digital Transformation Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
Indonesia Digital Transformation Market
Digital Transformation
Netherlands Digital Transformation Market
Digital Transformation
South East Asia Digital Transformation Market
Digital Transformation
Thailand Digital Transformation Market
Digital Transformation
Workplace Transformation Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
Digital Transformation Consulting Market