
 Israel Digital Transformation Market | 2026-2036
Israel Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Digital Transformation Market Insights
Israel's cloud infrastructure expansion is reconfiguring how domestic enterprises provision compute and storage at scale. Microsoft Corporation leverages its Azure regions to anchor government and financial workloads with local data residency guarantees. Check Point Software Technologies Ltd. differentiates through native security integrations that compete with imported platform offerings. IBM Corporation specializes in hybrid orchestration tools that sustain legacy system interoperability during migration cycles.
Israel digital transformation encompasses the systematic integration of cloud computing, artificial intelligence, and cybersecurity protocols into organizational workflows to replace analog processes with automated, data-driven operations. This discipline requires API-first architecture, zero-trust network segmentation, and real-time analytics pipelines to enable continuous process optimization across distributed environments. Cloud Computing services dominate current expenditure as enterprises exit owned data centers, while Cybersecurity solutions capture expanding margin pools driven by National Cyber Directorate compliance mandates. AI and Machine Learning technologies represent the fastest-growing technology dimension, particularly within Financial Services end users deploying predictive risk models.
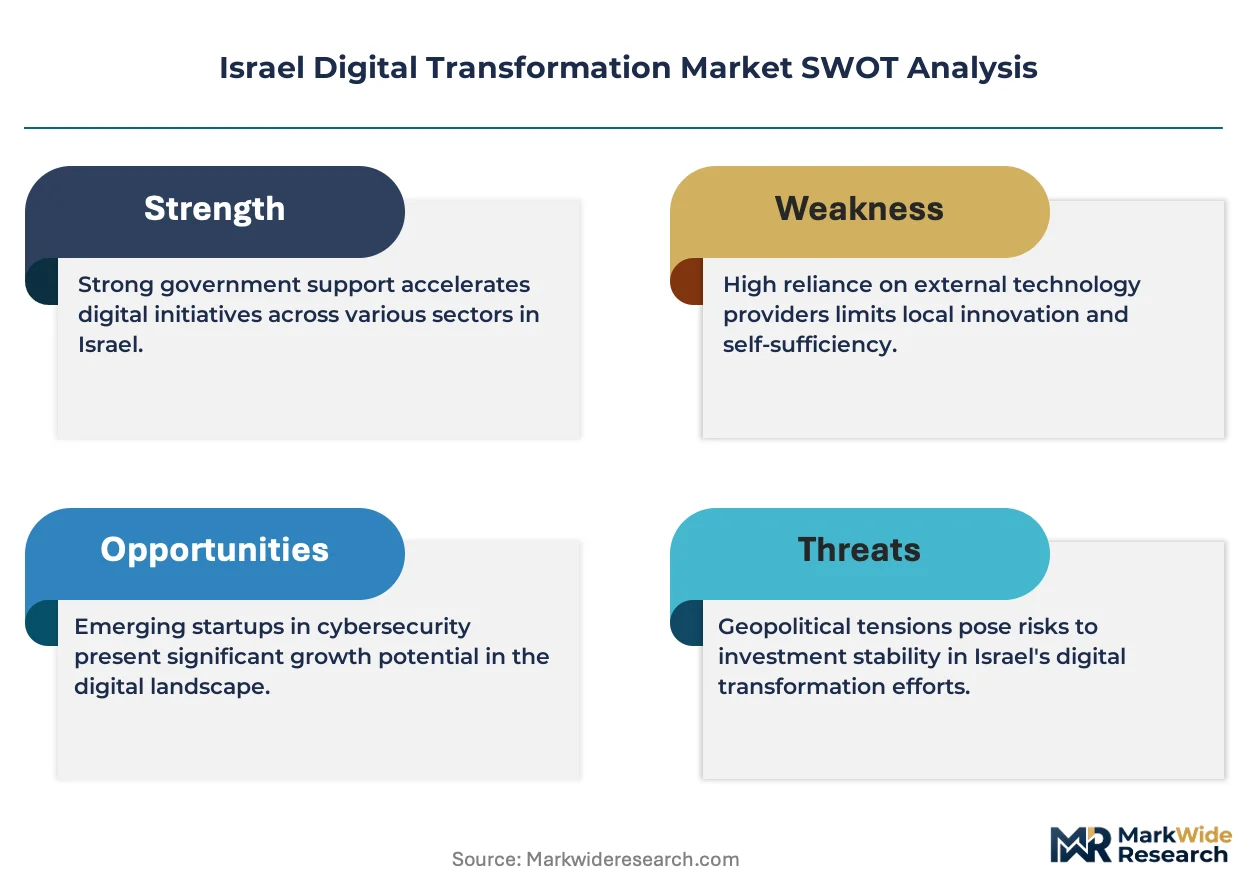
The National Cyber Directorate issues binding directives that dictate security baselines for critical infrastructure operators, creating regulated demand for CyberArk Software Ltd. and Check Point Software Technologies Ltd. solutions. BIS standards alignment and ISO 27001 certification requirements further shape product specifications for vendors serving government and healthcare segments. Stakeholders must monitor evolving directive scopes and cloud sovereignty negotiations to anticipate procurement priority shifts.
Market Dynamics
Binding National Cyber Directorate directives are forcing critical infrastructure operators to replace legacy perimeter defenses with zero-trust architectures, reshaping procurement priorities across Israeli defense, finance, and healthcare sectors.
Growth Catalysts
- Cloud Sovereignty Mandates:Government data residency requirements are accelerating migration to locally hosted Azure regions for sensitive workloads.
- Financial Services AI Adoption:Predictive risk modeling deployments in banking and insurance are expanding compute infrastructure budgets.
- Defense Contractor Modernization:Military R&D clusters in Tel Aviv's technology corridor are adopting Kubernetes-native development pipelines.
Market Restraints
- Specialized Talent Scarcity:Shortages of DevSecOps engineers and zero-trust architects constrain implementation timelines.
- Legacy System Interoperability:Decades-old mainframe dependencies in government agencies complicate API-first migration strategies.
- Input Cost Volatility:GPU and specialized AI accelerator prices fluctuate with global semiconductor supply constraints.
Strategic Opportunities
- Negev Technology Corridor Expansion:Government incentives are drawing enterprise R&D facilities to Beersheba's emerging cyber cluster.
- Healthcare Digitalization Gap:Hospital networks outside Tel Aviv metro remain underpenetrated for electronic health record modernization.
- AI-Cybersecurity Convergence:Real-time threat detection platforms combining machine learning with SOAR automation represent unclaimed white space.
Industry Challenges
- Certification Timeline Compression:ISO 27001 and BIS standards alignment for government contracts requires 12-18 month validation cycles.
- Integration Complexity:Hybrid cloud orchestration demands sustained engineering investment to maintain legacy system uptime during transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Digital Transformation Market |
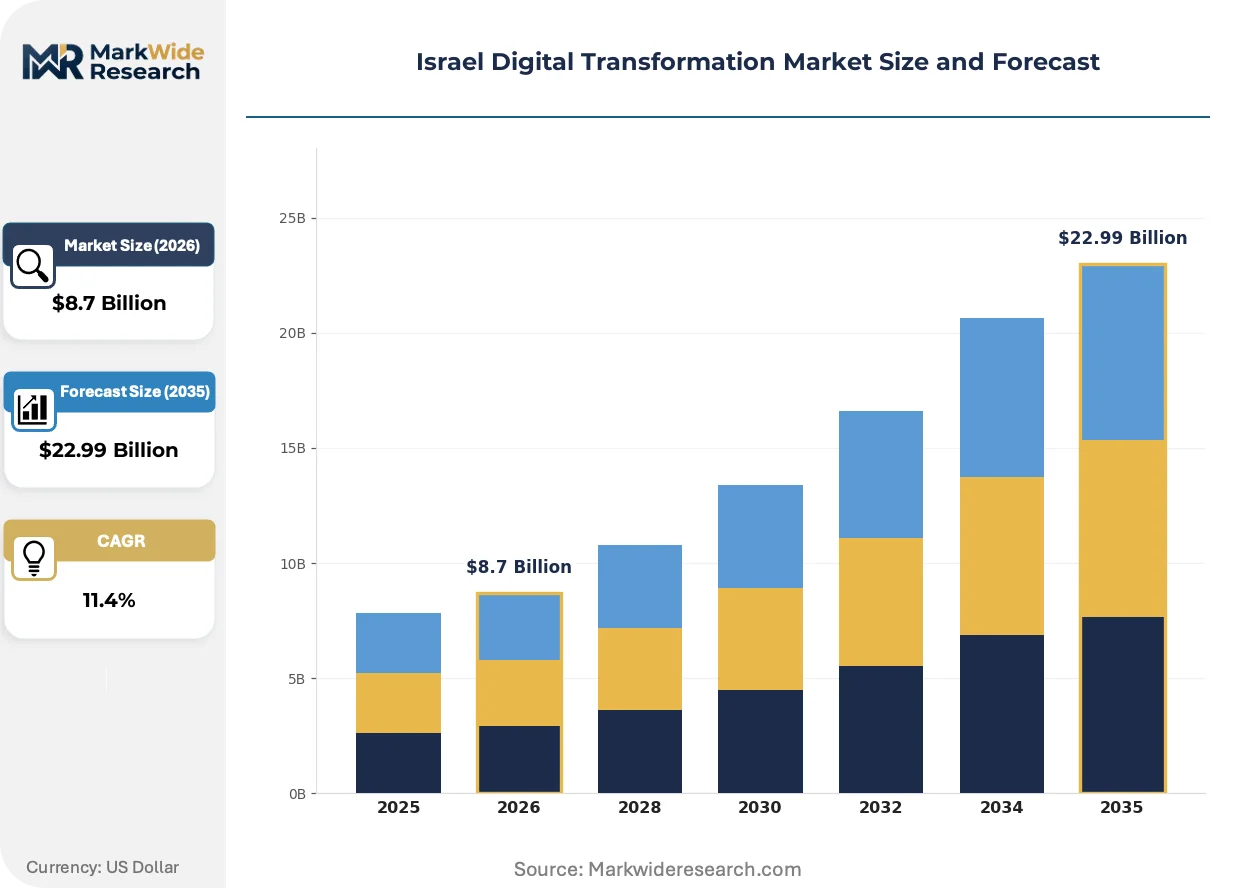
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Computing, Data Analytics, Cybersecurity, IoT Solutions Technology: AI, Machine Learning, Blockchain, AR/VR End User: Government, Financial Services, Healthcare, Retail Deployment: On-Premise, Hybrid, Public Cloud, Private Cloud |
| Companies Covered | Google LLC (Alphabet Inc.), Microsoft Corporation, IBM Corporation, CyberArk Software Ltd., Accenture PLC, Check Point Software Technologies Ltd., Amdocs Ltd., NICE Ltd., Amazon Web Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Digital Transformation Market Trends and Innovations
Agentic AI systems and sovereign cloud architectures are redefining how Israeli enterprises balance automation depth with data control requirements.
Agentic AI platforms that autonomously execute multi-step workflows without human intervention are rendering obsolete rule-based RPA tools in financial services back offices. Israeli banks are piloting these systems for fraud detection and compliance reporting. The shift is compressing vendor consolidation timelines as institutions demand unified AI-security stacks rather than point solutions.
National Cyber Directorate binding directives on critical infrastructure security baselines are mandating continuous compliance monitoring rather than periodic audits. Operators in energy, water, and telecommunications must deploy real-time telemetry to national security operations centers. Healthcare providers face the steepest adaptation curves due to fragmented legacy architectures.
Subscription-based consumption models for cybersecurity platforms are displacing perpetual license purchases among mid-market enterprises. Value-added resellers in Tel Aviv's technology corridor are restructuring compensation around customer outcome metrics rather than upfront deal size. Manufacturing verticals show the strongest preference shift, driven by CFO mandates to convert capex to opex.
Israel Digital Transformation Market Segmentation
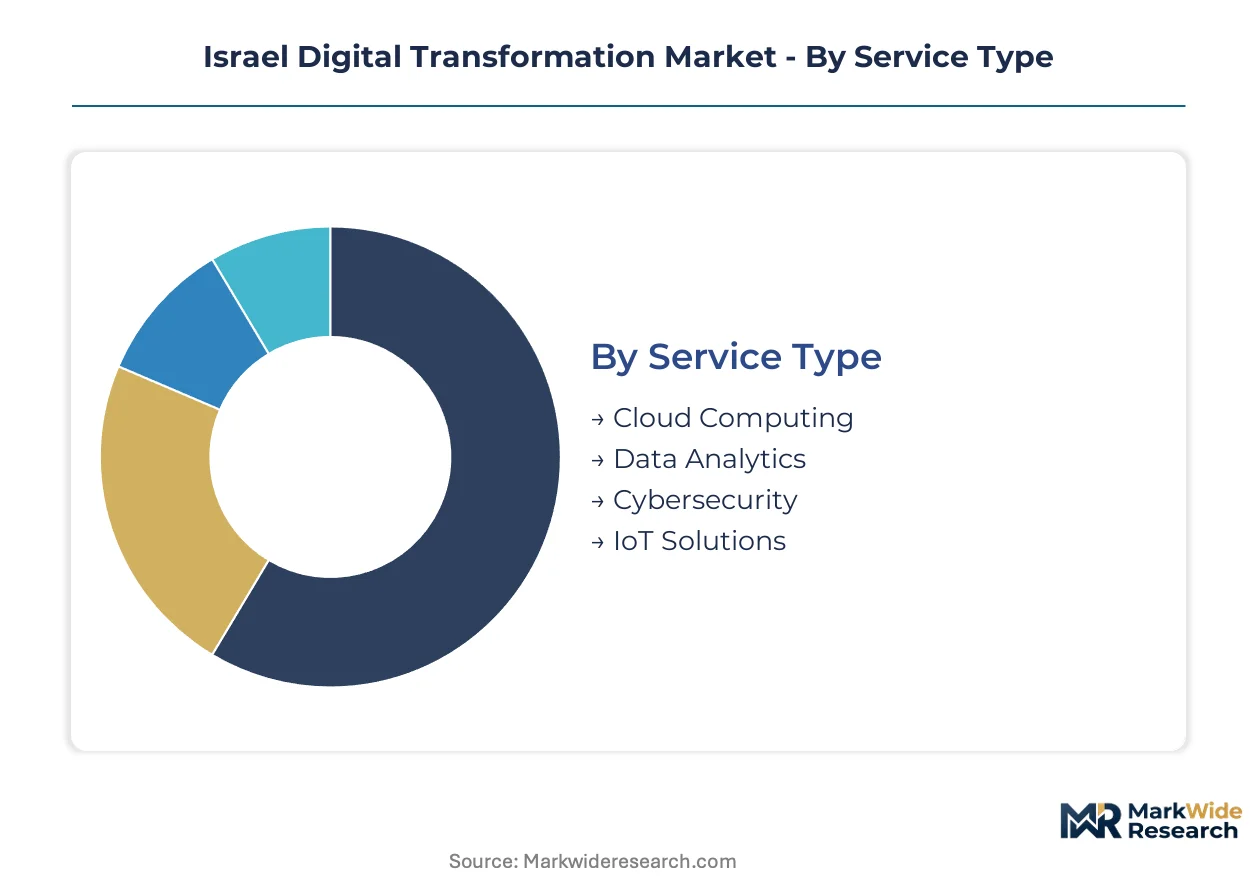
Israel's digital transformation market segments reveal distinct procurement patterns shaped by National Cyber Directorate mandates, defense contractor requirements, and Tel Aviv metro enterprise density. Understanding these divisions exposes where compliance costs concentrate and which technology stacks capture implementation budgets.
Service Type:
Cost tier differentiation across service types separates commodity infrastructure from high-margin specialized offerings that command premium positioning.
- Cloud Computing:Infrastructure-as-a-Service and platform services enabling exit from owned data centers. Tel Aviv financial institutions and government digital service hubs drive concentrated demand for local Azure regions with data residency guarantees.
- Cybersecurity:Zero-trust architecture implementations, identity management, and threat detection platforms. National Cyber Directorate binding directives on critical infrastructure operators mandate continuous compliance monitoring, expanding margin pools for vendors serving energy, water, and telecommunications sectors.
- Data Analytics:Real-time processing pipelines and predictive modeling engines for operational intelligence.
- IoT Solutions:Sensor networks and edge computing deployments for industrial automation and smart infrastructure.
Cloud Computing holds installed capacity. Cybersecurity is rotating up the share rankings.
Technology:
Application maturity across technology layers shows AI and Machine Learning advancing fastest while Blockchain and AR/VR remain in targeted pilot phases.
- AI:Agentic systems executing multi-step workflows autonomously in financial services back offices. Israeli banks deploy these platforms for fraud detection and compliance reporting, compressing vendor consolidation timelines toward unified AI-security stacks.
- Machine Learning:Predictive risk models in banking and insurance expanding compute infrastructure budgets. Financial Services end users represent the steepest expansion trajectory for this segment.
- Blockchain:Distributed ledger applications for supply chain traceability and digital identity verification.
- AR/VR:Immersive training simulations and remote collaboration tools for defense R&D clusters.
Machine Learning captures expanding R&D allocation. Blockchain maintains niche deployment profiles.
End User:
Customer type segmentation exposes where procurement authority concentrates and which verticals face the steepest compliance adaptation curves.
- Financial Services:Banking and insurance institutions deploying predictive risk models and automated compliance systems. AI adoption in this segment drives the fastest compute infrastructure budget expansion.
- Government:National agencies and critical infrastructure operators subject to National Cyber Directorate binding directives. Data residency requirements accelerate migration to locally hosted cloud regions for sensitive workloads.
- Healthcare:Hospital networks facing fragmented legacy architectures and steep adaptation curves for continuous compliance monitoring mandates.
- Retail:Omnichannel platforms and customer analytics for consumer-facing operations.
Financial Services leads technology investment intensity. Healthcare is rotating up the priority rankings as modernization gaps close.
Deployment:
Supply concentration across deployment models reflects sovereignty requirements, legacy system constraints, and workload sensitivity differentiation.
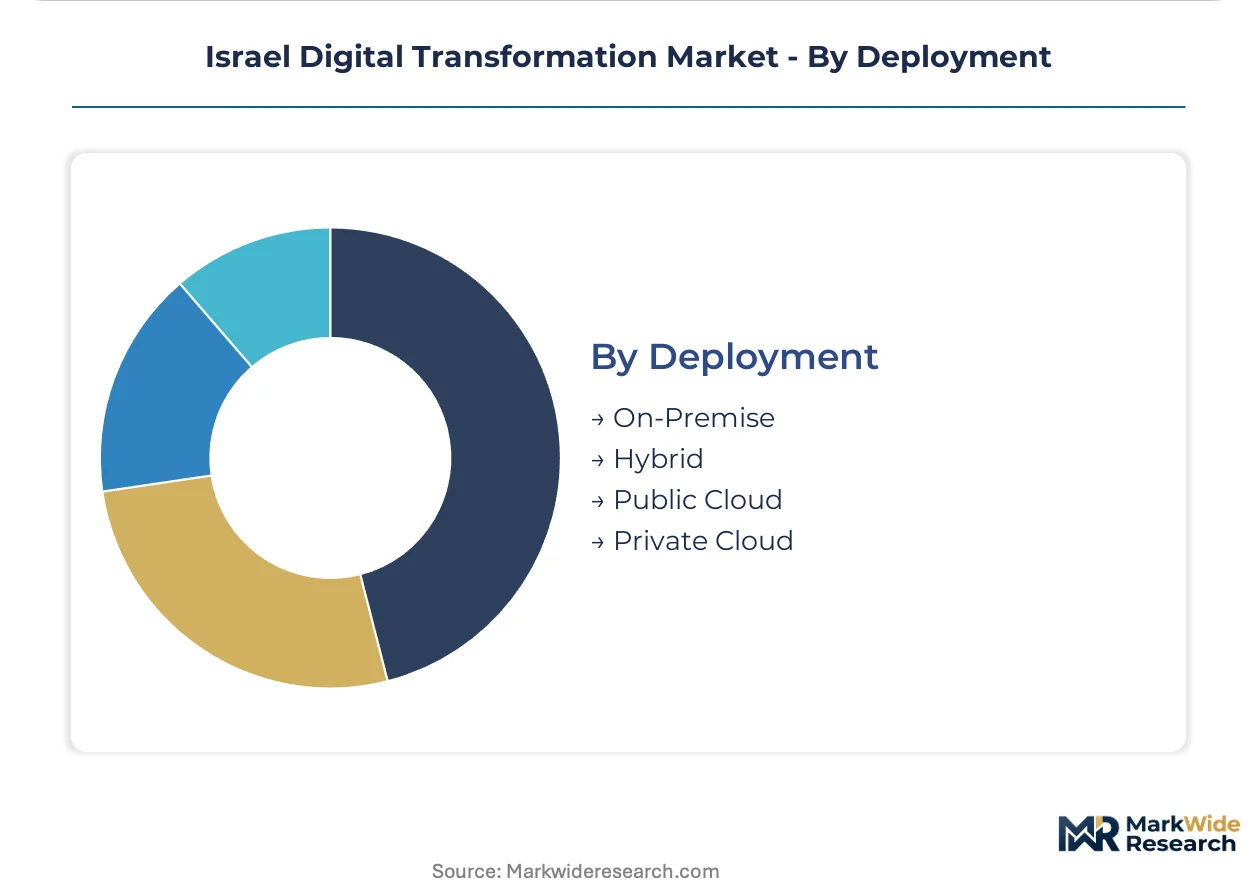
- Public Cloud:Scalable compute and storage resources hosted by hyperscale providers with local data residency options. Government and financial workloads concentrate in Azure regions meeting sovereignty mandates.
- Hybrid:Orchestrated environments sustaining legacy system interoperability during migration cycles. IBM specializes in tools serving this segment where decades-old mainframe dependencies complicate API-first strategies.
- Private Cloud:Dedicated infrastructure for classified defense workloads and regulated healthcare data.
- On-Premise:Remaining owned data center capacity in agencies with extended deprecation timelines.
Hybrid holds transitional workload volume. Public Cloud is rotating up the share rankings as residency guarantees mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Cyber Directorate anchors Israel's digital transformation governance through binding directives that reshape procurement across critical infrastructure sectors. Tel Aviv's metropolitan technology corridor concentrates enterprise R&D clusters and government digital service hubs. Sub-regional differentiation emerges across Israel's technology geography.
Tel Aviv Metropolitan Area
Financial services institutions and defense contractors drive concentrated cloud infrastructure demand in Israel's central coastal zone. The National Cyber Directorate mandates data residency requirements for sensitive government workloads. Microsoft Azure regions host banking and insurance predictive risk modeling deployments while Check Point Software Technologies Ltd. anchors cybersecurity integrations.
Beersheba and the Negev Technology Corridor
Government incentives are drawing enterprise R&D facilities southward to Israel's emerging cyber cluster. The Israel Defense Forces' technology units and academic partnerships feed specialized talent pipelines. CyberArk Software Ltd. and defense-focused startups occupy positions within this expanding ecosystem.
Jerusalem Government Hub
National agencies and critical infrastructure operators concentrate procurement authority in Israel's administrative capital. National Cyber Directorate binding directives on energy, water, and telecommunications sectors mandate continuous compliance monitoring. IBM Corporation hybrid orchestration tools sustain legacy system interoperability during migration cycles.
Haifa Industrial Zone
Port logistics and manufacturing verticals generate IoT and edge computing demand in Israel's northern coastal region. Industrial automation deployments face legacy system constraints. Subscription-based cybersecurity platform consumption is displacing perpetual license purchases among mid-market enterprises.
Israel Digital Transformation Market Competitive Landscape
Capability concentration sits with specialized cybersecurity and cloud-native vendors; scale advantage sits with hyperscale platform providers with local data residency infrastructure. The vendor base separates into three strategic tiers: global cloud platforms with sovereign region deployments, Israeli-born security specialists with native directive compliance, and systems integrators managing hybrid migration complexity. Dominant competitive moves include strategic partnerships between global platforms and local compliance specialists, plus portfolio diversification into AI-security convergence.
Within the Israeli-born security specialist tier, CyberArk Software Ltd. and Check Point Software Technologies Ltd. occupy positions exemplifying native National Cyber Directorate alignment. Microsoft Corporation represents the hyperscale platform archetype with Azure region infrastructure anchoring government and financial workloads. IBM Corporation sits within the hybrid orchestration specialist category, serving agencies with decades-old mainframe dependencies.
| Leading Market Players |
|---|
| Google LLC (Alphabet Inc.) |
| Microsoft Corporation |
| IBM Corporation |
| CyberArk Software Ltd. |
| Accenture PLC |
| Check Point Software Technologies Ltd. |
| Amdocs Ltd. |
| NICE Ltd. |
| Amazon Web Services |
| Others |
Pricing and Supply Chain Analysis
Haifa Port's container throughput costs feed directly into Tel Aviv metro enterprise procurement budgets, compressing margins for imported GPU accelerators while amplifying price spreads between cloud-native and legacy-hybrid deployment tiers. National Cyber Directorate compliance mandates concentrate buyer power among critical infrastructure operators who negotiate volume discounts against certified vendor shortlists.
Pricing Analysis
Price spreads widen between Tel Aviv metro and Negev corridor deployments due to logistics cost differentials and talent availability premiums. Subscription-based SaaS tiers dominate cybersecurity platform consumption, with ISO 27001 certification grade and after-sales support bundling as primary differentiation drivers. Pricing pressure intensifies in mid-market manufacturing verticals where CFO mandates accelerate opex conversion timelines. Government agencies show lowest price sensitivity due to directive-mandated procurement authority, while retail sector buyers drive hardest bargain terms.
Supply Chain Analysis
Upstream semiconductor feedstock flows from Taiwan, South Korea, and the United States anchor GPU and AI accelerator availability for Israeli cloud region expansion. Specialized hardware components including custom ASICs and high-bandwidth memory modules draw from concentrated East Asian fabrication networks. Single-source vulnerability in advanced node manufacturing presents structural exposure to geopolitical export restrictions. Distribution runs through Tel Aviv technology corridor value-added resellers who restructure compensation around customer outcome metrics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's digital transformation market functions as a regulatory-moat arena where National Cyber Directorate entrenchment creates high switching costs for critical infrastructure operators. Network effects compound through Azure region density and compliance-certified vendor consolidation.
For Market Incumbents: Build regulatory moat depth by embedding continuous compliance monitoring APIs directly into national security operations center architectures. Deepen backward integration into sovereign cloud infrastructure to counter hyperscaler price competition. Acquire specialized DevSecOps talent pipelines through Beersheba academic partnerships before scarcity intensifies implementation bottlenecks. For New Entrants and Emerging Players: Build out AI-security convergence platforms targeting healthcare networks outside Tel Aviv metro where electronic health record modernization gaps persist. Focus initial beachhead on hospital systems facing fragmented legacy architectures and steep National Cyber Directorate adaptation curves. Pursue channel partnerships with established value-added resellers who have restructured around outcome-based compensation models. For Investors and Strategic Acquirers: Carve-out targets emerge from defense contractor technology spin-offs holding classified workload clearances and specialized Kubernetes-native development capabilities. Long-term viability hinges on sustained government R&D procurement and cloud sovereignty negotiation outcomes. Monitor National Cyber Directorate directive scope expansions as primary inflection signal for compliance-mandated spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies AI-security stacks for Israeli banks replacing fragmented point solutions with agentic workflow systems. |
| Strategic Partnership | Links hyperscale Azure regions with CyberArk identity management to satisfy National Cyber Directorate data residency mandates. |
| Acquisition of Specialist Firm | Captures zero-trust architecture boutiques serving energy and water sector continuous compliance monitoring requirements. |
| Geographic Expansion | Establishes Negev corridor presence to access Israel Defense Forces technology unit talent pipelines and government incentives. |
| Product Launch | Introduces sovereign cloud offerings with BIS standards pre-certification to compress government procurement validation cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud architects, cybersecurity procurement officers, National Cyber Directorate compliance leads, and value-added reseller channel heads. Secondary validation drew from hyperscaler capex disclosures, SEC filings of listed Israeli technology vendors, National Cyber Directorate directive publications, and hospital procurement database records. Bottom-up service-type demand modeling and top-down technology spend allocation triangulated market size estimates.
Calibration against historical cloud infrastructure deployment velocities and AI compute budget expansion patterns anchored projection reliability across the analysis window. Segmentation dimensions modeled include service type, technology layer, end-user vertical, and deployment model complexity. CAGRs derived from slope analysis of adoption curve inflection points, with specific weighting applied to financial services AI adoption trajectories and defense contractor modernization pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sovereign cloud challengers or accelerated National Cyber Directorate directive scope expansions would shift outcomes materially. Cross-checking against hyperscaler regional revenue disclosures and government IT procurement auction records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
China Digital Transformation Market
Digital Transformation
South East Asia Digital Transformation Market
Digital Transformation
Thailand Digital Transformation Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
Workplace Transformation Market
Digital Transformation
Digital Transformation in Healthcare Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
Indonesia Digital Transformation Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Contact Center Transformation Market
Digital Transformation
Retail Digital Transformation Market
Digital Transformation
Global Network Transformation Market
Digital Transformation
Germany Digital Transformation Market