
 Canada Digital Transformation Market | 2026-2036
Canada Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Digital Transformation Market Insights
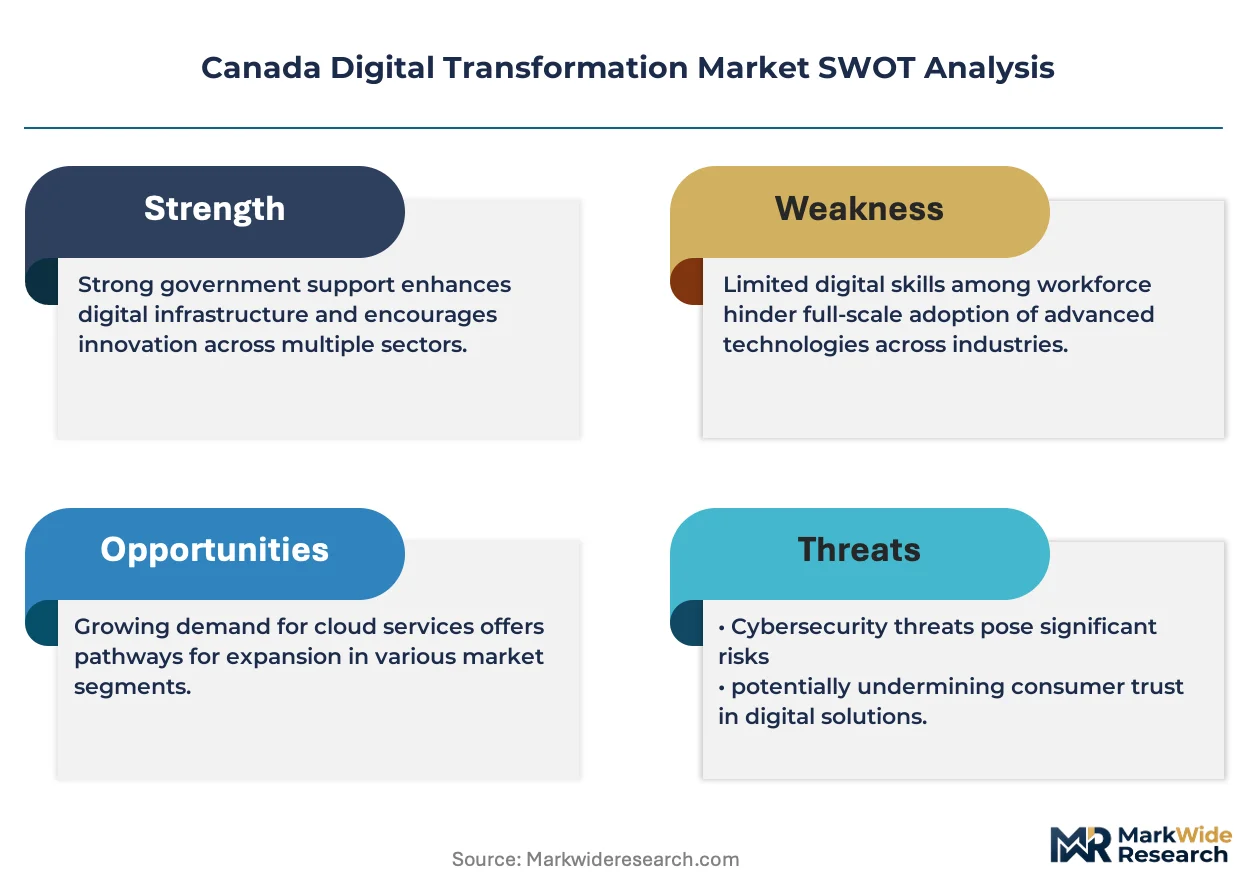
Enterprise-grade cloud security specifications are redrawing procurement criteria across Canadian digital transformation programs. Microsoft Corporation leverages its Azure sovereignty certifications to anchor public sector contracts requiring domestic data residency. IBM Corporation specializes in hybrid cloud orchestration for regulated industries navigating compliance complexity. Telus Corporation controls telecommunications-integrated digital service bundles that differentiate its enterprise offerings from pure-play software vendors.
Canada digital transformation encompasses the systematic integration of cloud computing architectures, AI-driven analytics engines, and IoT sensor networks into legacy operational workflows, typically requiring API-first middleware layers to bridge on-premises databases with distributed cloud environments. The primary purpose is to automate decision pipelines, reduce operational latency, and generate predictive intelligence from fragmented enterprise data reservoirs. Cloud-based deployment models now capture the dominant margin pool as recurring subscription revenue displaces perpetual license structures, while artificial intelligence within the technology segment represents the fastest-expanding capability investment as Canadian firms prioritize predictive maintenance and customer sentiment analysis. Cybersecurity tools within the solution category command premium pricing due to mandatory breach disclosure requirements under federal privacy legislation.
Health Canada, the Office of the Privacy Commissioner, and the Canadian Centre for Cyber Security collectively shape market access through data localization mandates, breach notification protocols, and critical infrastructure protection standards that elevate compliance costs for non-domestic platform providers. The Digital Charter Implementation Act proposals would further tighten consent mechanisms and algorithmic accountability, directly influencing AI and big data analytics procurement specifications. Stakeholders must monitor forthcoming federal cloud adoption frameworks and provincial health data interoperability mandates to anticipate shifts in vendor qualification requirements and enterprise budget allocation.
Market Dynamics
Federal cloud sovereignty mandates and Health Canada's AI guidance are compressing procurement cycles while elevating compliance thresholds for enterprise infrastructure vendors.
Growth Catalysts
- Digital Charter Implementation Act:Proposed algorithmic accountability requirements force enterprises to upgrade data governance platforms ahead of enforcement timelines.
- Toronto-Waterloo corridor concentration:Enterprise software and cybersecurity clusters generate talent spillovers that reduce implementation costs for adjacent adopters.
- Cloud-first procurement policies:Federal and provincial agencies now mandate API-first architectures, accelerating middleware and integration platform investments.
Market Restraints
- Data localization infrastructure costs:Domestic data residency requirements under Privacy Commissioner guidelines force redundant regional cloud deployments.
- Legacy system entrenchment:Financial services and healthcare providers operate COBOL-dependent core systems that resist API-layer abstraction.
- Regulatory fragmentation:Provincial health data interoperability standards in Ontario, British Columbia, and Quebec create multi-jurisdictional compliance burdens.
Strategic Opportunities
- Atlantic Canada underpenetration:Halifax and Moncton enterprise markets show lagging cloud adoption relative to central Canada, creating first-mover service provider openings.
- AI-enabled medical devices:Health Canada's regulatory clarity on diagnostic algorithms opens procurement pathways for hospital system predictive analytics.
- 5G-IoT convergence:Telus Corporation's telecommunications infrastructure enables edge computing bundles for manufacturing and resource extraction verticals.
Industry Challenges
- Cloud architecture skill scarcity:Kubernetes and multi-cloud orchestration expertise concentrates in Toronto and Vancouver, creating wage premiums elsewhere.
- Interoperability certification delays:Health Canada and provincial health authorities maintain separate validation protocols for electronic health record integrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Digital Transformation Market |
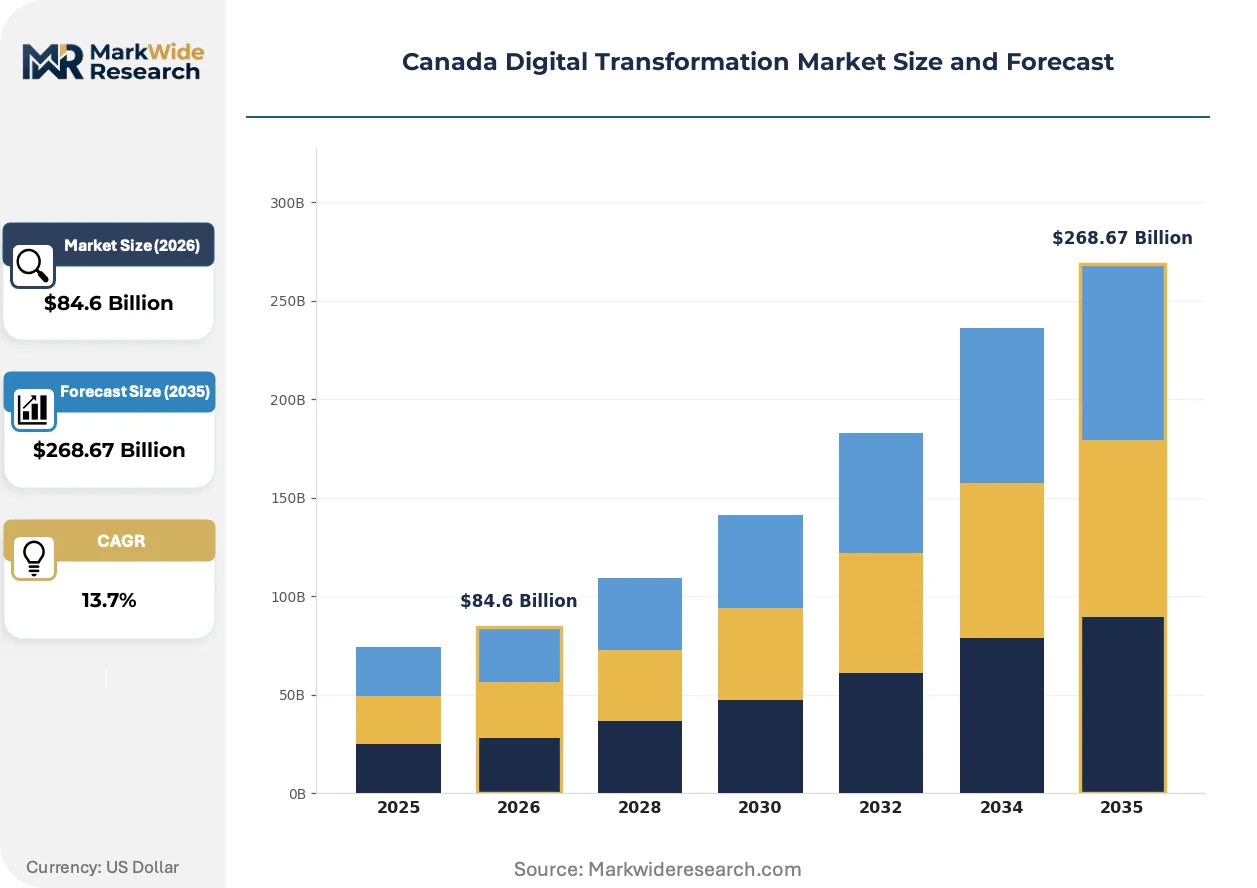
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $268.67 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, Managed Services Technology: Artificial Intelligence, Big Data Analytics, Internet of Things, Blockchain End User: Healthcare Providers, Financial Institutions, Retail Industry, Telecommunication Solution: ERP Systems, CRM Solutions, E-commerce Platforms, Cybersecurity Tools |
| Companies Covered | Telus Corporation, Accenture PLC, IBM Corporation, Google LLC, Oracle Corporation, Microsoft Corporation, Cisco Systems, Bell Canada, Telefonaktiebolaget LM Ericsson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Digital Transformation Market Trends and Innovations
Generative AI capabilities are compressing enterprise analytics deployment timelines while API-first middleware architectures dissolve traditional systems integration bottlenecks.
Large language model-powered code generation is supplanting manual legacy system modernization in Canadian banking and insurance sectors. Royal Bank of Canada and Toronto-Dominion Bank have deployed internal copilot tools that accelerate COBOL-to-Java translation. This compression of technical debt remediation is enabling faster cloud migration timelines than prior manual refactoring approaches permitted.
Health Canada's guidance on machine learning-enabled medical devices establishes pre-market validation requirements for algorithmic transparency. Device manufacturers must now submit performance monitoring protocols alongside traditional safety documentation. Diagnostic imaging AI vendors are responding by embedding continuous learning safeguards that prevent model drift in clinical deployment.
Subscription-based infrastructure provisioning is displacing capital-intensive perpetual license models among mid-market enterprises. Managed service providers in Calgary and Montreal now bundle cloud migration, cybersecurity operations, and compliance monitoring into single-contract arrangements. Resource extraction firms in Alberta and Saskatchewan exhibit the fastest uptake of this consolidated procurement structure.
Canada Digital Transformation Market Segmentation
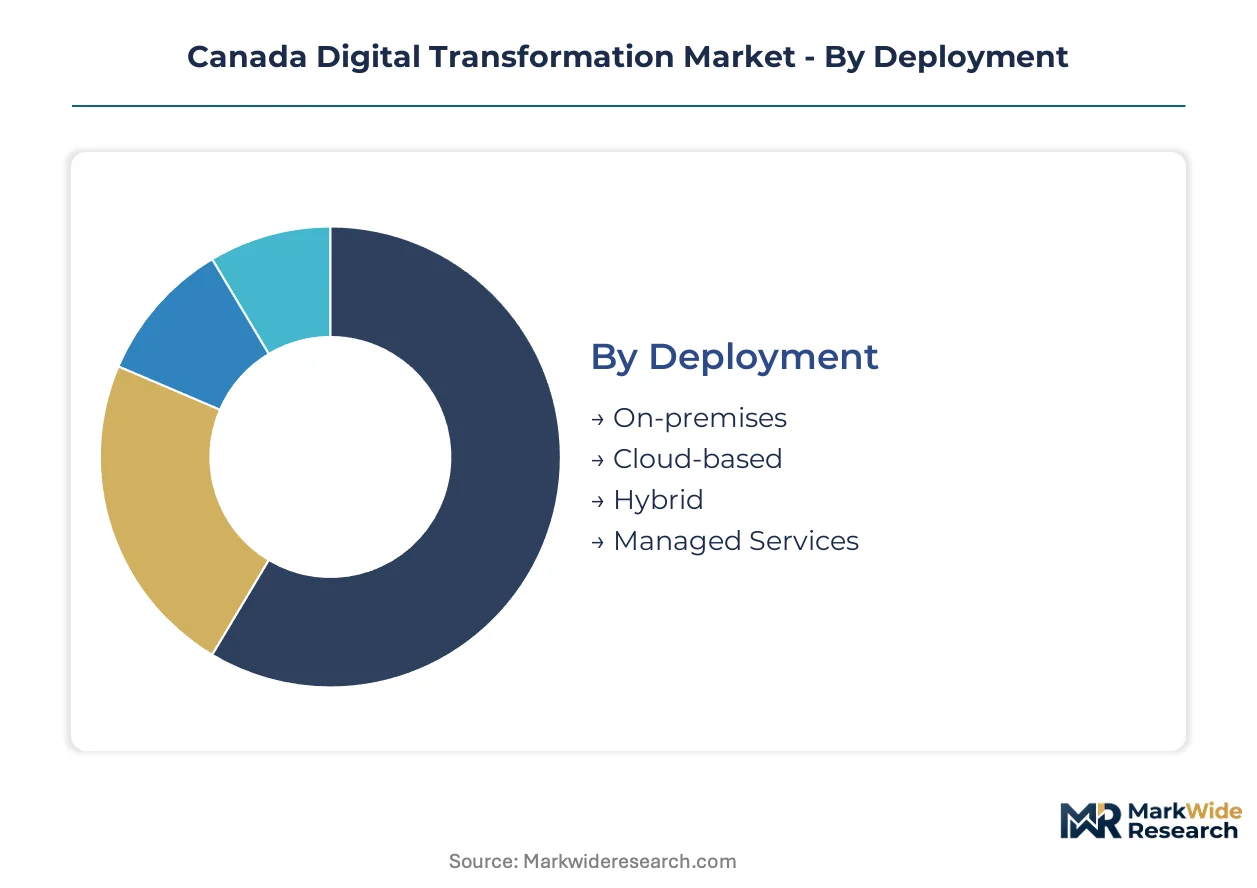
Segmentation reveals how Canadian procurement patterns diverge between sovereignty-driven public sector mandates and efficiency-seeking private enterprise. Understanding these splits enables vendors to calibrate compliance architecture against speed-to-deployment tradeoffs.
Deployment:
Domestic data residency requirements favor on-premises and hybrid configurations in federal and provincial contracts, while cloud-based models dominate export-facing private enterprises seeking elastic scale.
- On-premises:Hardware-resident infrastructure maintains complete jurisdictional control over data storage and processing. Federal agencies and Crown corporations mandate this configuration for classified workloads under Canadian Centre for Cyber Security guidelines.
- Cloud-based:Distributed computing resources delivered via subscription eliminate capital expenditure cycles. Ontario's financial services sector concentrates demand here as OSFI guidance permits public cloud for non-sensitive operations.
- Hybrid:Orchestrated workloads split between private data centers and public cloud nodes. Quebec healthcare providers favor this model to keep patient records provincial while leveraging cloud analytics.
- Managed Services:Third-party operational control of infrastructure and security monitoring. Atlantic Canada mid-market manufacturers adopt this to bypass scarce local Kubernetes expertise.
On-premises commands the established base. The steepest expansion runs through hybrid configurations bridging compliance and agility.
Technology:
Cost tiering separates mature infrastructure investments from emerging capability bets requiring specialized talent premiums.
- Artificial Intelligence:Machine learning pipelines for predictive analytics and natural language processing. Diagnostic imaging networks in Ontario and Alberta hospital systems drive clinical deployment under Health Canada validation protocols.
- Big Data Analytics:Distributed processing frameworks aggregating enterprise data lakes. Retail banking customer segmentation concentrates demand in Toronto's Bay Street corridor.
- Internet of Things:Sensor networks capturing operational telemetry from physical assets. Saskatchewan potash mining operations deploy edge-connected extraction monitoring.
- Blockchain:Distributed ledger architectures for transaction immutability and supply chain provenance. Alberta energy trading platforms pilot smart contract settlement.
Big Data Analytics commands the established base. The steepest expansion runs through Artificial Intelligence as algorithmic accountability regulations mature.
End User:
Application intensity varies by sector digital maturity and regulatory pressure exposure.
- Healthcare Providers:Hospital systems and provincial health authorities modernizing electronic health record infrastructure. Ontario Health's interoperability mandates accelerate procurement.
- Financial Institutions:Banks, insurers, and credit unions migrating core banking platforms. OSFI operational resilience guidelines compress transformation timelines.
- Retail Industry:Omnichannel commerce platforms and inventory optimization systems. Toronto-Waterloo corridor direct-to-consumer brands lead adoption.
- Telecommunication:Network operators virtualizing infrastructure and deploying edge computing. 5G rollout investments in British Columbia and Quebec drive systems integration.
Financial Institutions commands the established base. The steepest expansion runs through Healthcare Providers as federal AI guidance clarifies procurement pathways.
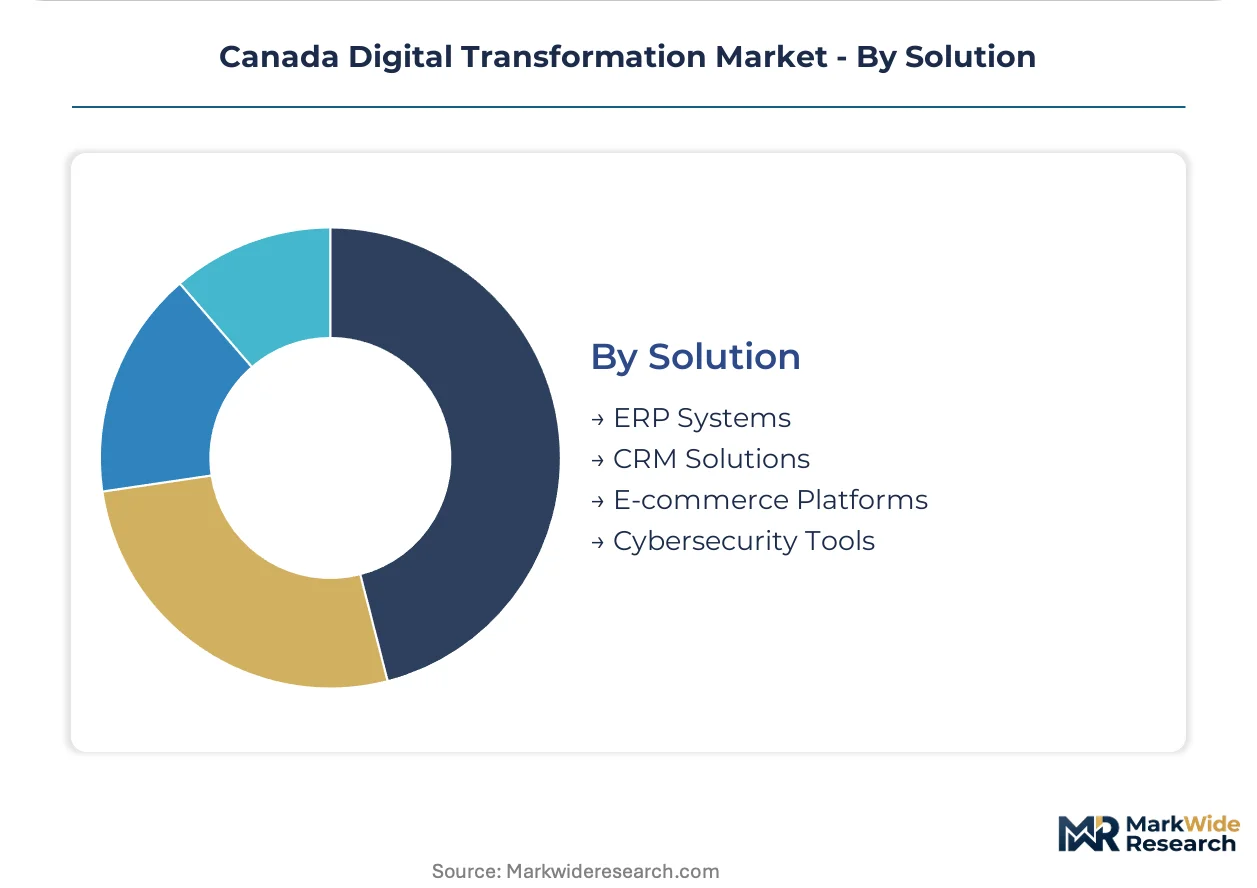
Solution:
Customer type segmentation distinguishes between operational backbone systems and revenue-facing engagement platforms.
- ERP Systems:Integrated financial, supply chain, and human resource management platforms. Federal Shared Services Canada consolidation mandates sustain demand.
- CRM Solutions:Customer relationship management and sales force automation. Quebec professional services firms prioritize francophone localization capabilities.
- E-commerce Platforms:Digital storefront and payment processing infrastructure. Vancouver direct-to-consumer exporters drive cross-border transaction volume.
- Cybersecurity Tools:Threat detection, identity management, and breach response systems. Mandatory disclosure requirements under federal privacy legislation elevate procurement priority.
ERP Systems commands the established base. The steepest expansion runs through Cybersecurity Tools as breach notification obligations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure deployment concentrates in Ontario's Toronto-Waterloo technology corridor, where enterprise software and cybersecurity investments dominate procurement budgets. Federal data sovereignty mandates and Health Canada's AI guidance compress vendor qualification timelines while elevating compliance thresholds across provincial markets.
Ontario
Financial services modernization and hospital system electronic health record upgrades drive demand concentration in the Toronto-Waterloo corridor. The Office of the Privacy Commissioner enforces breach notification protocols that elevate cybersecurity procurement priority. Toronto's Bay Street banking cluster accelerates core platform migration under OSFI operational resilience guidelines.
Quebec
Healthcare providers favor hybrid cloud configurations to maintain provincial patient record sovereignty while leveraging cloud analytics capabilities. The Digital Charter Implementation Act proposals tighten consent mechanisms for francophone consumer data processing. Montreal's enterprise software sector specializes in compliance-integrated digital service bundles for regulated industries.
British Columbia
Telecommunications infrastructure virtualization and 5G edge computing investments concentrate demand among network operators. The Canadian Centre for Cyber Security mandates critical infrastructure protection standards for cross-border data flows. Vancouver's direct-to-consumer exporter cluster drives cross-border e-commerce platform procurement.
Alberta
Resource extraction firms exhibit fastest uptake of consolidated managed service contracts bundling cloud migration and compliance monitoring. Provincial energy regulators align with federal cloud adoption frameworks for operational technology security. Calgary's mid-market manufacturing sector adopts subscription-based infrastructure provisioning to bypass scarce Kubernetes expertise.
Atlantic Canada
Halifax and Moncton enterprise markets show lagging cloud adoption relative to central Canada, creating first-mover service provider openings. Federal procurement policies mandate API-first architectures that accelerate middleware investments in underpenetrated regions. Moncton's cybersecurity talent pipeline supports managed security service expansion into provincial government contracts.
Canada Digital Transformation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Canadian digital transformation market. Hyperscale cloud providers anchor public sector contracts through domestic data residency certifications, while telecommunications-integrated vendors differentiate through bundled service offerings. Strategic consolidation centers on hybrid cloud orchestration capabilities and sovereign infrastructure deployment. Competitive moves emphasize vertical integration into managed security operations and geographic expansion into Atlantic Canada's underpenetrated markets.
Among telecommunications-integrated service providers, Telus Corporation and Bell Canada occupy positions bridging network infrastructure with enterprise digital transformation delivery. IBM Corporation exemplifies the hybrid cloud orchestration archetype for regulated industries navigating multi-jurisdictional compliance complexity. Microsoft Corporation anchors public sector procurement through Azure sovereignty certifications satisfying federal data localization mandates.
| Leading Market Players |
|---|
| Telus Corporation |
| Accenture PLC |
| IBM Corporation |
| Google LLC |
| Oracle Corporation |
| Microsoft Corporation |
| Cisco Systems |
| Bell Canada |
| Telefonaktiebolaget LM Ericsson |
| Others |
Pricing and Supply Chain Analysis
Subscription-based capacity reservation contracts now dominate enterprise digital transformation procurement in Canada, locking in multi-year cloud infrastructure access while capping price escalation exposure for buyers navigating federal data sovereignty mandates. These arrangements bind hyperscale providers to domestic data residency commitments under Privacy Commissioner guidelines, converting compliance overhead into predictable operational expenditure.
Pricing Analysis
The Digital Charter Implementation Act dictates the pricing tier structure across Canadian digital transformation markets, elevating algorithmic accountability certification costs for AI-enabled solutions. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-cloud certified deployments from basic commercial configurations, with Health Canada validation protocols commanding substantial premiums for healthcare applications. Cost compression in mid-market SaaS tiers is intensifying because managed service providers consolidate cybersecurity and compliance monitoring into bundled offerings. Resource extraction firms in Alberta exhibit lowest price sensitivity due to operational technology security requirements, while Atlantic Canada mid-market manufacturers demonstrate acute sensitivity to per-seat licensing costs.
Supply Chain Analysis
The United States and Ireland anchor hyperscale cloud infrastructure supply for Canadian enterprise markets, with domestic data centers in Toronto, Montreal, and Vancouver providing jurisdictional compliance layers. Semiconductor components for edge computing devices draw from Taiwan and South Korea, while specialized AI accelerators feed from NVIDIA's supply network. Single-source vulnerability concentrates in domestic telecommunications-integrated service providers controlling last-mile connectivity. Distribution runs through channel partners certified under federal cloud adoption frameworks, with systems integrators in the Toronto-Waterloo corridor managing complex hybrid orchestration deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's digital transformation market exhibits cyclical recovery characteristics as federal cloud-first procurement policies and Health Canada AI guidance compress replacement cycles for legacy infrastructure. OSFI operational resilience deadlines for financial institutions accelerate this cyclical upswing.
For Market Incumbents: Secure Azure sovereignty certifications and Canadian Centre for Cyber Security assessments to defend public sector contract access against emerging domestic cloud providers. Invest in backward integration into managed security operations centers to capture recurring revenue streams as breach notification obligations tighten under federal privacy legislation. For New Entrants and Emerging Players: Health Canada AI device certification fast-tracks open procurement pathways for hospital system predictive analytics vendors lacking established incumbent relationships. Atlantic Canada enterprise markets show lagging cloud adoption relative to central Canada, creating first-mover openings for managed service providers bundling migration and compliance monitoring. Target provincial government contracts through Moncton's cybersecurity talent pipeline. For Investors and Strategic Acquirers: Hybrid cloud orchestration specialists with established federal procurement relationships represent prime acquisition targets as consolidation accelerates around sovereign infrastructure deployment capabilities. Monitor forthcoming provincial health data interoperability mandates as inflection indicators for hospital system electronic health record upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Azure Sovereignty Certification | Microsoft's domestic data residency credentials satisfy federal procurement requirements under Privacy Commissioner guidelines. |
| Hybrid Cloud Orchestration Acquisition | IBM's regulated industry expertise addresses multi-jurisdictional compliance complexity in Quebec healthcare markets. |
| 5G-IoT Edge Computing Bundle | Telus leverages telecommunications infrastructure to differentiate manufacturing and resource extraction vertical offerings. |
| AI Medical Device Validation | Diagnostic imaging vendors embed continuous learning safeguards responding to Health Canada algorithmic transparency requirements. |
| Atlantic Canada Geographic Expansion | Halifax and Moncton underpenetration creates first-mover managed security service openings in provincial government contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cloud architects, federal procurement officers, hospital IT directors, and cybersecurity operations leads; and secondary validation against Canadian Centre for Cyber Security guidelines, Health Canada AI device guidance documents, OSFI operational resilience bulletins, and provincial health authority interoperability mandates. Bottom-up deployment estimates triangulated against top-down federal and provincial budget allocation disclosures.
Across the projection horizon, the analytical framework modeled segmentation across deployment configuration, technology capability maturity, end-user industry digital maturity, and solution category integration complexity. CAGRs derived from elasticity-adjusted adoption curves incorporating regulatory enforcement timeline uncertainty. Forecast inputs included federal cloud adoption framework implementation pace and provincial health data interoperability mandate sequencing.
Underlying assumptions cover steady regulatory enforcement intensity and stable hyperscale provider domestic infrastructure investment, with deviation risk concentrated in Digital Charter Implementation Act passage timing and provincial health authority certification protocol harmonization. Recalibration cycles align with material shifts in federal procurement policy and Health Canada AI guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Digital Transformation in Healthcare Market
Digital Transformation
Digital Transformation in Supply Chain Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Retail Digital Transformation Market
Digital Transformation
Thailand Digital Transformation Market
Digital Transformation
Italy Digital Transformation Market
Digital Transformation
Digital Transformation Consulting Market
Digital Transformation
Japan Digital Transformation Market
Digital Transformation
Digital Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
Global Design Thinking Market
Digital Transformation
Global Network Transformation Market
Digital Transformation
ASEAN Digital Transformation Market