
 SQL Server Transformation Market | 2026-2036
SQL Server Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
SQL Server Transformation Market Outlook
The shift from single-source vendor relationships to multi-cloud sourcing strategies is recalibrating how enterprises procure SQL Server transformation services. Microsoft Corporation leverages its native platform ownership to anchor hybrid deployment roadmaps for large enterprises. Amazon Web Services Inc. competes through specialized migration tooling that reduces cutover risk during cloud transitions. IBM Corporation differentiates via consulting-led engagements that bundle mainframe legacy modernization with SQL Server replatforming.
SQL Server transformation encompasses the architectural migration, schema conversion, data pipeline reconstruction, and performance optimization of Microsoft SQL Server environments across on-premises, cloud, and hybrid topologies, typically involving T-SQL refactoring, compatibility level upgrades, and integration with Azure Data Factory or Synapse Analytics. The primary purpose is to eliminate technical debt, enable elastic compute scaling, and satisfy real-time analytics requirements. Cloud deployment models now capture the fastest expansion as lift-and-shift gives way to containerized and serverless re-architecture. Migration services command premium pricing due to complexity and downtime sensitivity, while optimization services represent a recurring revenue layer as performance tuning becomes continuous rather than episodic.
ISO 27001 certification requirements shape vendor selection criteria for financial and healthcare end users undergoing SQL Server transformation, while the EU AI Act introduces algorithmic accountability obligations for automated decision systems running on transformed data estates. In the United States, HIPAA security rules and state-level privacy statutes such as the California Consumer Privacy Act constrain how patient and consumer data migrate between SQL Server instances. Stakeholders must monitor evolving encryption standards and residency mandates as these determine which deployment architectures remain compliant across jurisdictions.
Market Dynamics
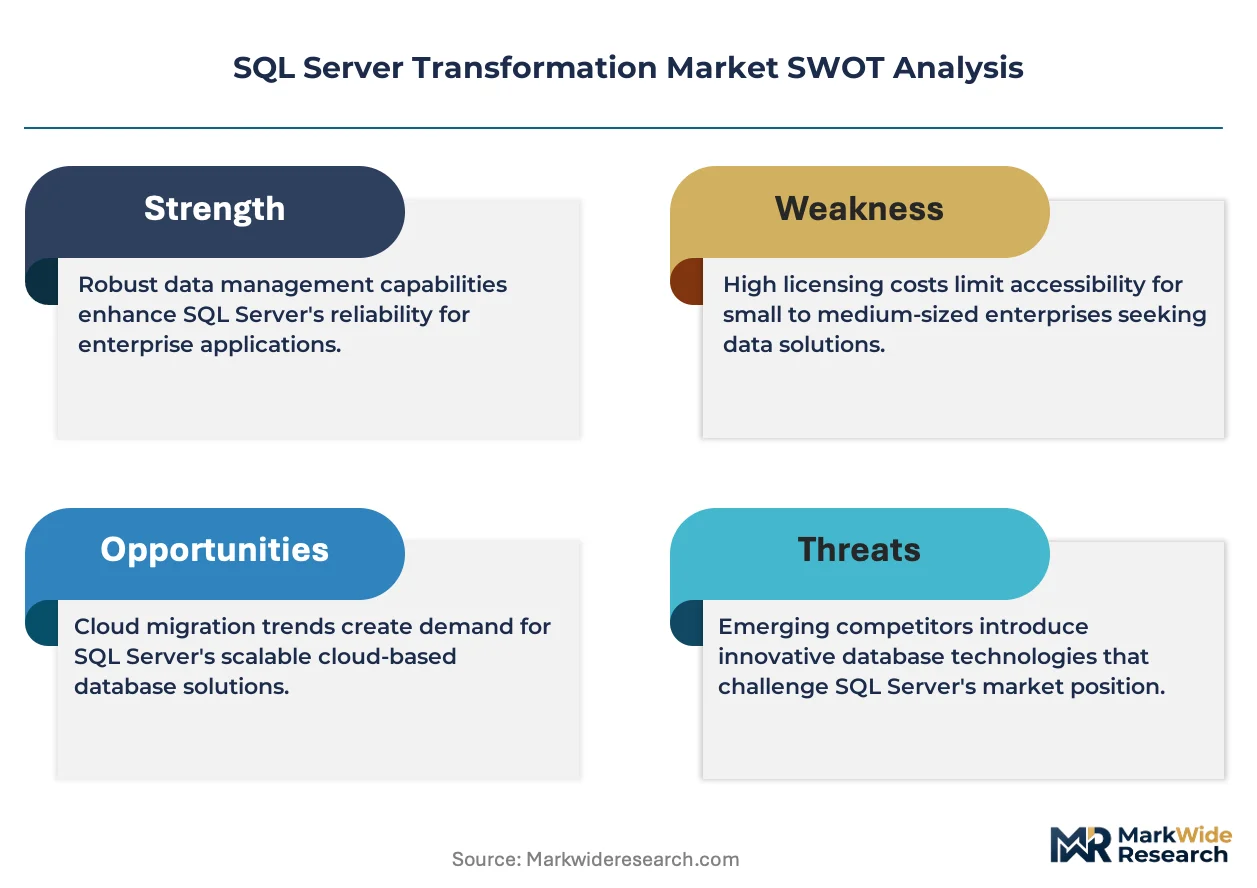
Multi-cloud sourcing strategies are recalibrating how enterprises procure SQL Server transformation services, as vendor lock-in risks collide with demands for elastic compute and real-time analytics capabilities.
Growth Catalysts
- HIPAA Security Rule:Healthcare providers in the United States must modernize SQL Server estates to satisfy encryption and audit requirements during patient data migrations, creating sustained demand for compliant transformation services.
- Containerization:Kubernetes-orchestrated SQL Server deployments enable granular scaling that lift-and-shift migrations cannot achieve, accelerating replatforming investments among SaaS providers.
- Germany:Industrial manufacturers in Baden-Württemberg and Bavaria are consolidating fragmented SQL Server instances to support Industry 4.0 analytics pipelines, driving schema standardization projects.
Market Restraints
- T-SQL Refactoring Costs:Legacy stored procedures and proprietary extensions require manual recoding for cloud-native compatibility, inflating migration budgets beyond initial estimates.
- Specialized Talent Scarcity:Certified SQL Server architects with Azure Data Factory and Synapse Analytics expertise command premium rates, constraining project velocity for mid-market enterprises.
- EU AI Act:Algorithmic accountability obligations for automated decision systems complicate data estate transformations, requiring additional governance layers that extend deployment timelines.
Strategic Opportunities
- India:Domestic IT services firms and multinational captives in Bengaluru and Hyderabad are modernizing legacy SQL Server 2008/2012 installations, creating underpenetrated demand for automated schema conversion tooling.
- ISO 27001 Certification:Vendors bundling information security management certification with transformation services capture premium positioning in financial services procurement evaluations.
- Serverless Convergence:Integration of Azure SQL Database serverless tier with event-driven architectures enables consumption-based pricing that displaces provisioned capacity models.
Industry Challenges
- Cutover Risk Management:Financial services firms face regulatory scrutiny over downtime windows during production SQL Server migrations, requiring zero-downtime synchronization tooling that few vendors have perfected.
- Compatibility Level Conflicts:Applications dependent on deprecated T-SQL features fail silently after version upgrades, necessitating exhaustive regression testing that compresses project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SQL Server Transformation Market |
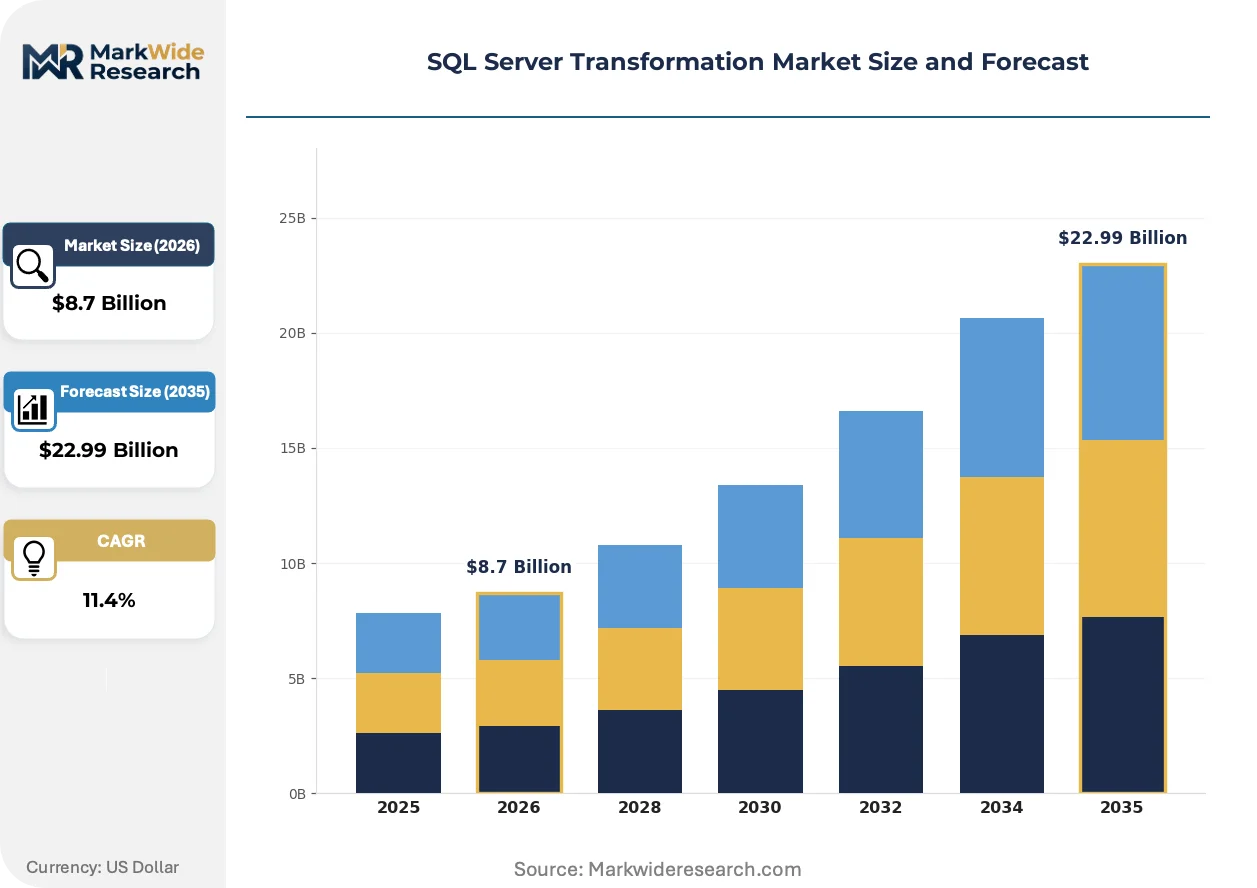
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud, Hybrid, Managed Database Type: Relational, NoSQL, NewSQL, Distributed Service Type: Consulting, Migration, Support, Optimization End User Sector: Finance, Retail, Healthcare, Education |
| Companies Covered | Accenture, IBM Corporation, Microsoft Corporation, SAP SE, Google Cloud (Alphabet Inc.), Amazon Web Services Inc., Infosys Limited, Teradata Corporation, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SQL Server Transformation Market Strategic Shifts
Distributed data architectures and automated governance frameworks are displacing centralized warehouse models, while procurement patterns favor consumption-based pricing over perpetual licensing commitments.
Database virtualization technology is decentralizing SQL Server estate management by abstracting compute from storage layers. Large retailers with seasonal demand spikes are adopting this approach fastest, spinning read replicas across regions without schema replication. The technology is decentralizing vendor relationships as enterprises mix Azure, AWS, and Google Cloud SQL instances within unified query layers.
GDPR data residency mandates are forcing architectural redesigns for multinational SQL Server deployments. Organizations must maintain physically separated instances across European jurisdictions, fragmenting previously consolidated estates. Financial services firms in Frankfurt and Amsterdam are responding with region-locked Azure SQL Managed Instances that prevent cross-border data flows.
Buyer committees now mandate proof-of-concept milestones before full SQL Server transformation contracts execute. Systems integrators are unbundling assessment phases from implementation, selling diagnostic engagements separately. This pattern is most pronounced in United States healthcare, where HIPAA business associate agreements require vendor qualification before patient data exposure.
SQL Server Transformation Market Segmentation
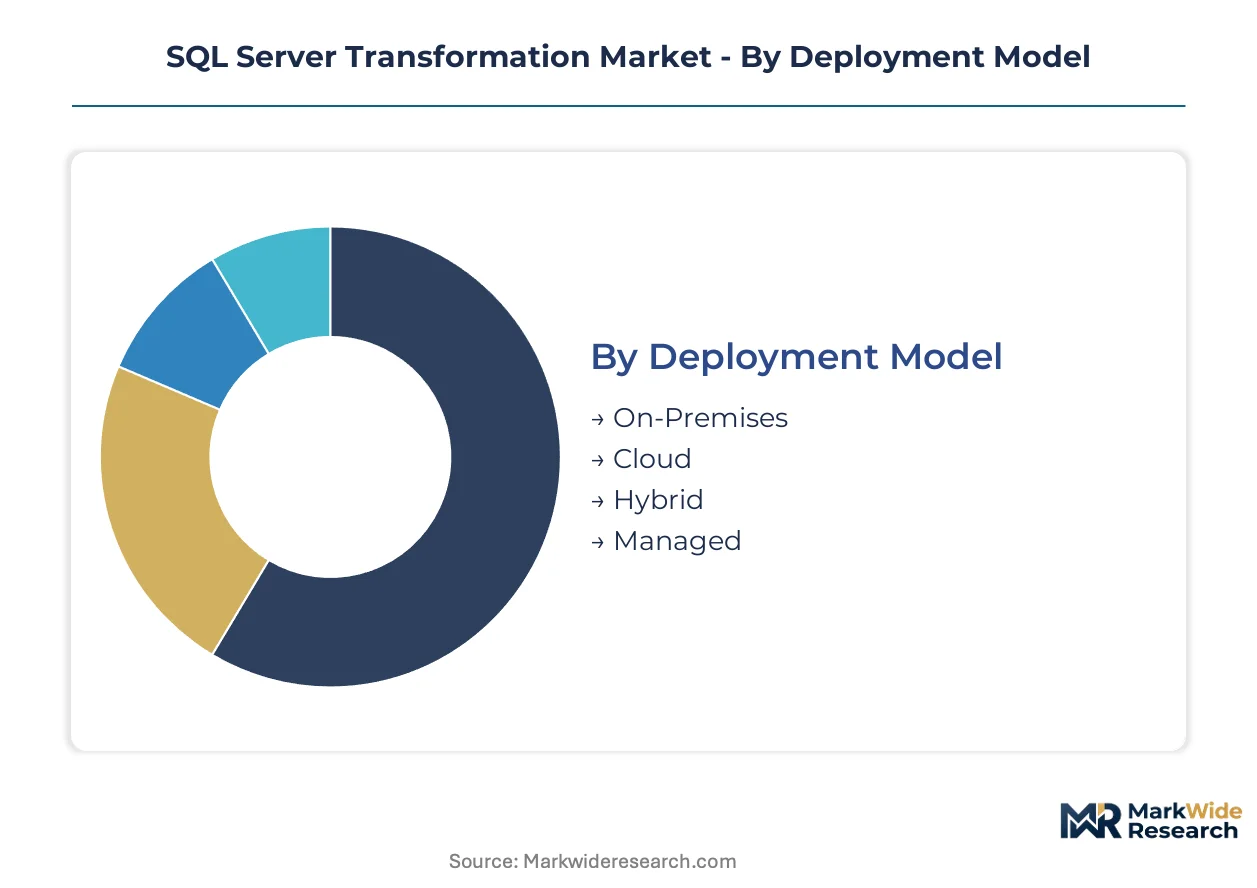
Segmentation in SQL Server transformation services reveals how procurement priorities diverge across infrastructure maturity levels. Enterprises select deployment architectures and service bundles based on regulatory exposure, technical debt load, and elasticity requirements rather than uniform feature comparisons.
Deployment Model:
The customization-vs-standardization spectrum runs from fully managed environments with minimal configuration control to self-managed on-premises installations requiring extensive in-house expertise.
- Cloud:Fully managed SQL Server instances on Azure, AWS, or Google Cloud eliminate hardware procurement cycles and enable automatic patching. Financial services firms in New York and London concentrate demand here as HIPAA and GDPR audit trails integrate natively with cloud logging services.
- Hybrid:Split workloads between on-premises SQL Server and cloud-managed instances, governed by Azure Arc or AWS Outposts policy engines. German automotive suppliers in Stuttgart and Munich favor this architecture to satisfy GDPR data residency while accessing elastic compute for simulation workloads.
- On-Premises:Self-managed SQL Server installations on owned hardware with full administrative control.
- Managed:Third-party operated SQL Server estates where the vendor assumes patching, backup, and availability responsibilities.
Most installed capacity flows through Cloud deployments. Expansion is steepest in Hybrid configurations.
Database Type:
Cost tier differentiation separates legacy relational workloads from specialized architectures requiring premium engineering investment.
- Relational:Traditional row-based SQL Server tables with ACID transaction guarantees and T-SQL query interfaces. Retail payment processors and healthcare claims systems in the United States maintain concentration here due to decades of stored procedure investment.
- Distributed:Sharded SQL Server deployments spanning multiple nodes with federated query coordination. Indian IT services firms in Bengaluru adopt this architecture for multi-tenant SaaS platforms serving global clients.
- NoSQL:Document and key-value stores integrated alongside SQL Server through PolyBase or external tables.
- NewSQL:Distributed SQL engines combining horizontal scalability with ACID semantics.
Relational retains the largest installed base. Distributed architectures are climbing the fastest among cloud-native enterprises.
Service Type:
Application maturity determines whether buyers need foundational migration support or continuous optimization engagement.
- Migration:End-to-end relocation of SQL Server workloads between platforms, encompassing schema conversion, data movement, and cutover orchestration. United States healthcare providers undergoing HIPAA-mandated encryption upgrades drive concentrated demand for zero-downtime migration tooling.
- Optimization:Continuous performance tuning, index management, and query plan analysis delivered as recurring engagements. SaaS providers with seasonal demand volatility purchase these services to right-size provisioned capacity.
- Consulting:Advisory engagements for architecture design, compliance roadmap development, and vendor selection.
- Support:Break-fix and maintenance services for operational SQL Server estates.
Migration commands the largest project values. Optimization is gaining share fastest as consumption-based pricing models spread.
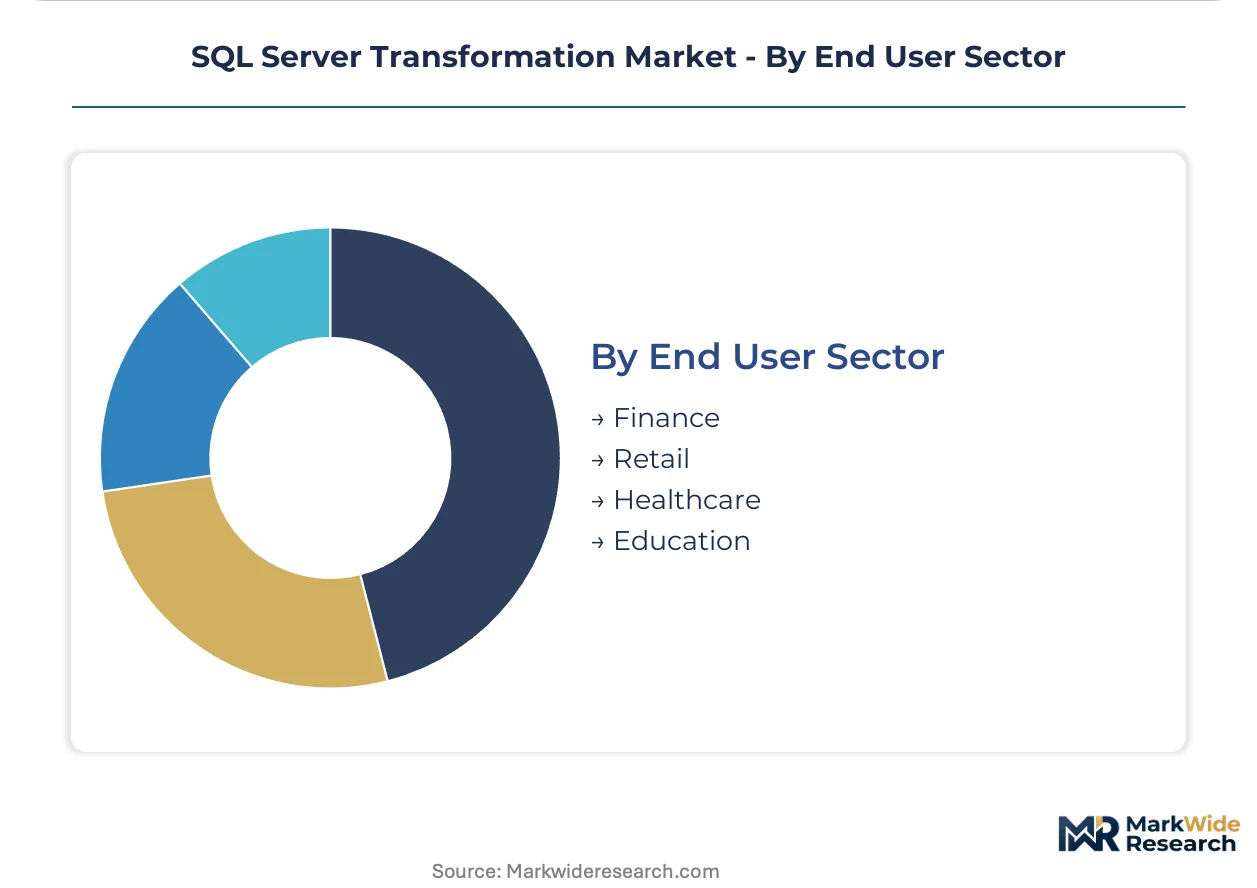
End User Sector:
Customer type segmentation reflects divergent regulatory pressure and technical debt accumulation patterns across industries.
- Finance:Banks, insurers, and capital markets firms with stringent audit requirements and legacy mainframe-to-SQL Server migration backlogs. Frankfurt-based institutions navigate both GDPR and ECB guidance on cloud outsourcing.
- Healthcare:Hospital systems, payers, and life sciences companies bound by HIPAA Security Rule encryption mandates and FDA 21 CFR Part 11 validation requirements.
- Retail:Omnichannel merchants modernizing inventory and customer data platforms.
- Education:Universities and K-12 districts consolidating fragmented departmental SQL Server instances.
Finance contributes the largest contract values. Healthcare is expanding most quickly as HIPAA compliance deadlines accelerate estate modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance-cost differentials are redirecting SQL Server transformation procurement toward jurisdictions with harmonized data protection frameworks and established cloud infrastructure. Enterprises arbitrage between strict regulatory enforcement and operational flexibility when selecting transformation partners.
United States
Financial services firms in New York and healthcare systems across the Midwest drive concentrated demand for HIPAA-compliant migration services. The SEC's cybersecurity disclosure rules and state-level privacy statutes create layered compliance obligations. Chicago-based hospital networks are consolidating fragmented SQL Server 2012 estates to satisfy encryption mandates.
Germany
Industrial manufacturers in Baden-Württemberg and Bavaria require schema standardization for Industry 4.0 analytics pipelines. GDPR residency requirements and BSI IT-Grundschutz certifications shape vendor selection criteria. Stuttgart automotive suppliers are deploying hybrid architectures through Azure Arc to maintain sovereign data control.
India
Domestic IT services firms and multinational captives in Bengaluru and Hyderabad are modernizing legacy SQL Server 2008 installations at scale. RBI data localization guidelines and the Digital Personal Data Protection Act impose governance requirements. Telangana's HITEC City corridor is emerging as a hub for automated schema conversion tooling development.
United Kingdom
London-based financial institutions navigate post-Brexit regulatory divergence while replatforming core banking systems. FCA operational resilience requirements and UK GDPR continuity obligations extend project timelines. Edinburgh's fintech cluster is adopting containerized SQL Server deployments to meet recovery time objectives.
Japan
Tokyo-headquartered manufacturers and insurers are migrating from end-of-life SQL Server versions to cloud-managed instances. METI's data free flow with trust initiative and APPI privacy amendments influence architectural decisions. Osaka's pharmaceutical sector is investing in validated transformation pathways for FDA 21 CFR Part 11 compliance.
SQL Server Transformation Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized migration tooling and automated governance layers. The market structures around three archetypes: hyperscale cloud providers anchoring platform-native roadmaps, global systems integrators bundling consulting with implementation, and boutique specialists delivering zero-downtime cutover capabilities. Competitive dynamics center on strategic partnerships between cloud platforms and services firms, alongside portfolio diversification into adjacent data estate modernization.
Within the hyperscale tier, Microsoft Corporation and Amazon Web Services Inc. anchor platform-native positioning through native SQL Server compatibility and specialized migration tooling respectively. IBM Corporation exemplifies the consulting-led archetype, bundling mainframe legacy modernization with SQL Server replatforming engagements. Accenture occupies a position bridging implementation scale with industry-specific compliance expertise across financial services and healthcare verticals.
| Leading Market Players |
|---|
| Accenture |
| IBM Corporation |
| Microsoft Corporation |
| SAP SE |
| Google Cloud (Alphabet Inc.) |
| Amazon Web Services Inc. |
| Infosys Limited |
| Teradata Corporation |
| Oracle Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive integration of migration tooling with cloud platform roadmaps anchors pricing power for hyperscale providers while compressing margins for pure-play services firms. Microsoft Corporation and Amazon Web Services Inc. bundle transformation assessments with consumption commitments, eroding standalone consulting premiums.
Pricing Analysis
Direct-to-enterprise discounts on Azure SQL Database serverless tiers compress distributor margins for systems integrators reselling cloud capacity. Three-tier pricing structure across premium, standard, and economy levels separates zero-downtime migration guarantees from basic lift-and-shift tooling. Cost compression in mid-market segments intensifies as automated schema conversion tools displace manual refactoring. Healthcare providers bound by HIPAA business associate agreements exhibit lowest price sensitivity; mid-market retailers show highest.
Supply Chain Analysis
India's Digital Personal Data Protection Act and Germany's BSI IT-Grundschutz certification requirements reshape sourcing toward domestic delivery centers with sovereign data controls. Engineering talent concentrates in India, Germany, and the United States; specialized Kubernetes orchestration expertise remains scarcest. Cloud compute capacity feeds from hyperscale regions in Virginia, Frankfurt, and Mumbai. Single-source vulnerability runs through Azure Data Factory pipeline dependencies for automated ETL workflows. Distribution runs through direct enterprise sales teams and certified partner networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SQL Server transformation market functions as a regulatory compounder where HIPAA Security Rule encryption mandates and GDPR data residency requirements perpetually refresh modernization demand.
For Market Incumbents: Lock in recurring revenue by embedding continuous optimization services into Azure Arc and AWS Outposts management contracts. Defend against boutique zero-downtime specialists by acquiring automated cutover tooling capabilities. Prioritize ISO 27001 certification maintenance to sustain financial services procurement eligibility.
For New Entrants and Emerging Players: Begin with automated T-SQL refactoring tools targeting India's SQL Server 2008/2012 installed base in Bengaluru and Hyderabad. White-space opportunity concentrates in mid-market healthcare providers seeking HIPAA-compliant managed services without hyperscale lock-in. Go-to-market angle: consumption-based pricing with embedded compliance auditing.
For Investors and Strategic Acquirers: Roll-up economics work for specialized migration tooling vendors because fragmented schema conversion automation creates consolidation value. Long-term viability hinges on platform-agnostic positioning as multi-cloud sourcing becomes standard. Target acquisition archetype: zero-downtime synchronization specialists with proven financial services references. Signal to watch: EU AI Act enforcement triggering governance-layer investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure Arc unifies hybrid SQL Server management across on-premises and cloud estates for German automotive suppliers. |
| Acquisition of Specialist Firm | Automated schema conversion tooling addresses T-SQL refactoring bottlenecks constraining Indian IT services firms. |
| Strategic Partnership | Systems integrators unbundle assessment phases to satisfy United States healthcare buyer committee procurement patterns. |
| Product Launch | Serverless tier offerings displace provisioned capacity models for SaaS providers with seasonal demand volatility. |
| Geographic Expansion | Azure SQL Managed Instances in Frankfurt and Amsterdam satisfy GDPR residency mandates for financial services. |
Study Parameters
Coverage spans the United States, Germany, India, the United Kingdom, and Japan, with primary inputs from each market cluster. Primary interviews engaged cloud platform engineers, healthcare IT procurement officers, financial services data architects, and systems integrator delivery leads. Secondary validation drew from SEC filings of hyperscale providers, HIPAA enforcement action databases, EMA regulatory guidance documents, and customs records of database software imports. Bottom-up project pipeline analysis triangulated with top-down cloud infrastructure spend estimates.
Granularity-level modeling deployed deployment mode, database type, service type, and end-user sector dimensions at the country level. CAGRs were derived from weighted average of historical migration project completion rates and projected cloud consumption commitments. Industry-specific inputs included HIPAA compliance deadline schedules, SQL Server version end-of-life timelines, and hyperscale data center expansion announcements.
Several conditions sit outside the modeled scope, including unforeseen regulatory enforcement intensity shifts and breakthrough database virtualization technologies displacing traditional migration approaches. Forecasts reflect documented assumptions about cloud adoption elasticity and talent availability trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
MENA Digital Transformation Market
Digital Transformation
Contact Center Transformation Market
Digital Transformation
Japan Digital Transformation Market
Digital Transformation
Workspace Transformation Market
Digital Transformation
Netherlands Digital Transformation Market
Digital Transformation
India Digital Transformation Market
Digital Transformation
Brazil Digital Transformation Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Israel Digital Transformation Market
Digital Transformation
Workplace Transformation Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
ASEAN Digital Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Australia and New Zealand Digital Transformation Market
Digital Transformation
Thailand Digital Transformation Market