
 APAC Digital Transformation Market | 2026-2036
APAC Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Digital Transformation Market Insights
Banking and financial services is shifting toward real-time payment infrastructure and embedded finance platforms across Southeast Asia. Microsoft Corporation leverages its Azure sovereign cloud deployments to anchor government contracts in Australia and Singapore. SAP SE sustains dominance in ERP modernization for Japanese automotive suppliers. Amazon Web Services competes aggressively on price-performance for Indian fintech startups requiring elastic compute.
Digital transformation encompasses the systematic integration of cloud-native architectures, artificial intelligence pipelines, and IoT sensor networks to re-engineer operational workflows and customer interfaces. Cloud Computing and AI segments command the largest deployment budgets as enterprises replace legacy on-premises stacks with API-first infrastructure. Hybrid Cloud adoption outpaces Public Cloud in regulated industries where data residency requirements fragment workload placement. Managed Services margins expand fastest as skills shortages force enterprises to outsource platform operations rather than build in-house SRE teams.
Japan's METI enforces data free flow with trust principles that dictate cross-border architecture design for multinationals operating across Tokyo-Osaka corridors. China's MIIT cloud service licensing regime restricts foreign hyperscaler market access while accelerating domestic platform substitution. India's TRAI data localization consultations and Australia's Privacy Act reforms compel enterprises to resegment customer databases and audit supply chain software provenance. Stakeholders must weigh sovereign cloud mandates against interoperability costs when selecting regional deployment architectures.
Market Dynamics
China's MIIT cloud service licensing regime and Japan's METI data governance standards are fragmenting deployment architectures across the region, forcing multinationals to rebuild infrastructure around sovereign data corridors rather than unified global stacks.
Growth Catalysts
- India's PLI scheme for IT hardware:Domestic manufacturing incentives accelerate server and networking equipment localization, reducing import dependency for enterprise data centers.
- TRAI data localization consultations:India's telecom regulator mandates customer database resegmentation, creating demand for compliant cloud-native customer data platforms.
- Real-time payment infrastructure:Southeast Asian banking regulators drive embedded finance platform builds, requiring API-first core banking replacements.
Market Restraints
- Foreign hyperscaler licensing restrictions:China's MIIT regime limits market access for non-domestic cloud providers, compressing competitive options.
- Semiconductor supply concentration:Advanced GPU and AI accelerator availability concentrates with Taiwan and South Korean foundries, creating procurement bottlenecks.
- Cross-border data friction:Australia's Privacy Act reforms impose audit requirements on supply chain software provenance, extending procurement cycles.
Strategic Opportunities
- Vietnam and Indonesia enterprise underpenetration:Mid-market manufacturers in these markets lack legacy ERP entrenchment, enabling greenfield SaaS adoption.
- AI-IoT convergence in Japanese automotive:METI-funded smart factory initiatives create demand for unified edge-to-cloud pipelines in supplier networks.
- Australian sovereign cloud mandates:Government contracts now require in-country data residency, opening captive infrastructure buildouts.
Industry Challenges
- Site reliability engineering talent scarcity:Enterprises across Singapore and Australia compete for limited DevOps and platform engineering capabilities, inflating managed services dependency.
- Legacy mainframe integration complexity:Indian financial institutions face protracted timelines connecting COBOL cores to modern API gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Digital Transformation Market |
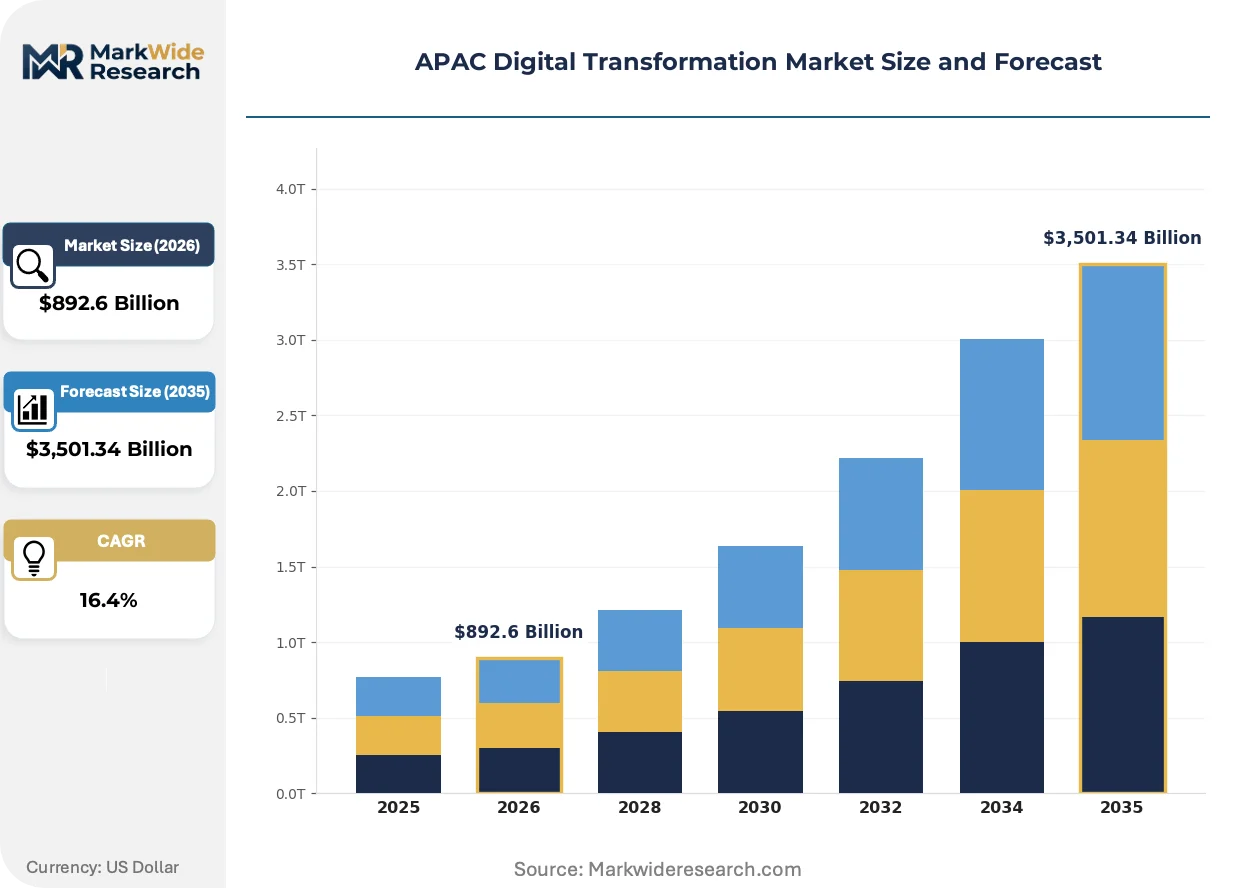
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $3,501.34 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, AI, IoT, Big Data Deployment Model: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud End User: Healthcare, Retail, Manufacturing, Education Service Type: Consulting, Integration, Support, Managed Services |
| Companies Covered | SAP SE, Amazon Web Services, Microsoft Corporation, Tata Consultancy Services, Huawei Technologies, IBM Corporation, Google LLC, Infosys, Oracle Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Digital Transformation Market Trends and Innovations
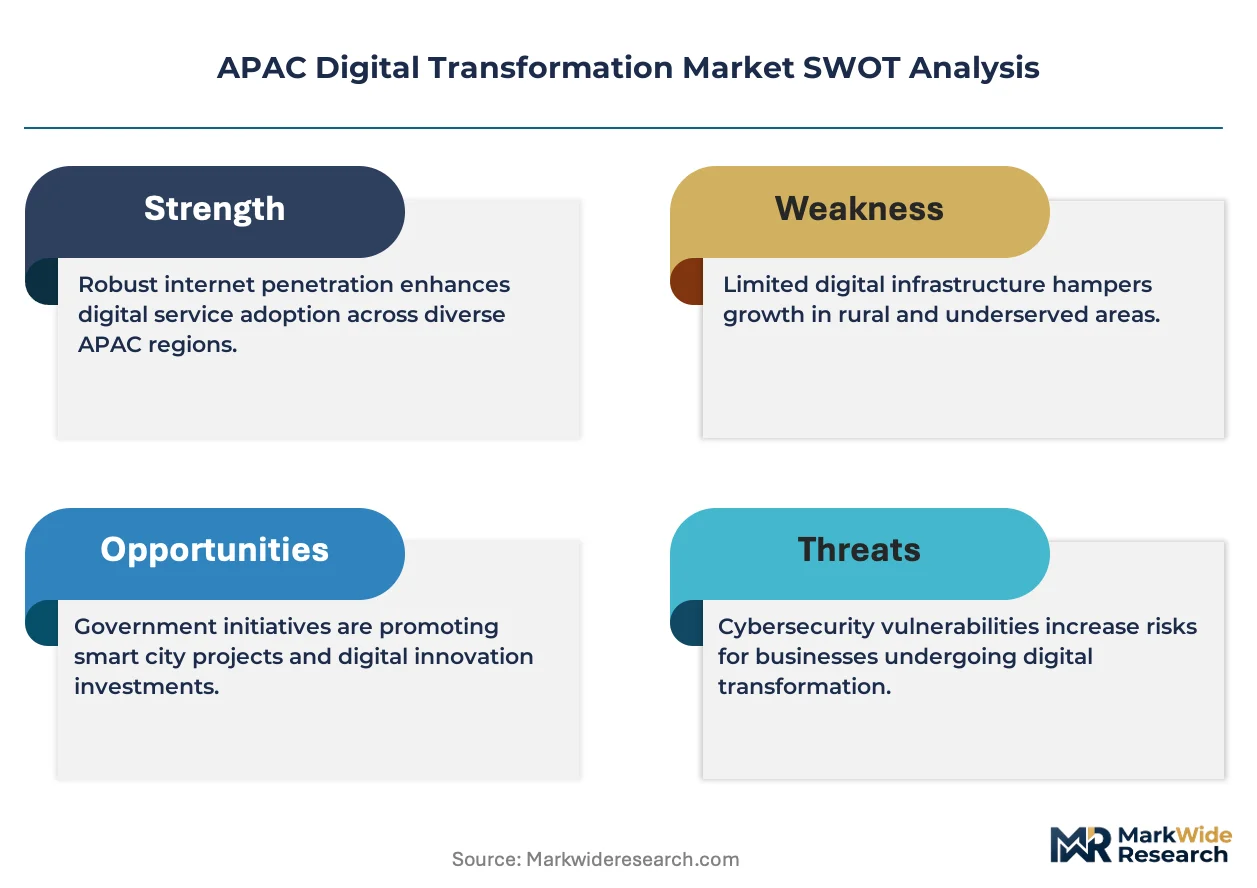
Edge computing architectures and sovereign cloud deployments are redrawing competitive boundaries, as regulatory data residency requirements override traditional cost-performance optimization in vendor selection.
Hybrid cloud orchestration platforms are expanding into regulated financial services workflows across Southeast Asia. Singaporean and Thai banks deploy these tools to maintain transaction data on-premises while bursting analytics workloads to external infrastructure. This bifurcation is compressing vendor consolidation timelines as institutions demand single-pane management across fragmented environments.
METI's data free flow with trust principles now govern cross-border architecture design for multinationals operating across Tokyo-Osaka corridors. Japanese automotive suppliers must certify data handling protocols to maintain supplier status, redirecting IT procurement toward compliance-validated platforms. Korean manufacturers with Japan exposure are adopting parallel certification tracks to preserve market access.
Subscription-based platform engineering services displace perpetual license models among Australian public sector agencies. State governments in Victoria and New South Wales now procure through outcome-defined contracts rather than capital expenditure approvals. This behavioral shift is most visible in healthcare digitization programs, where operational expenditure budgets accommodate faster procurement cycles than traditional infrastructure tenders permitted.
APAC Digital Transformation Market Segmentation
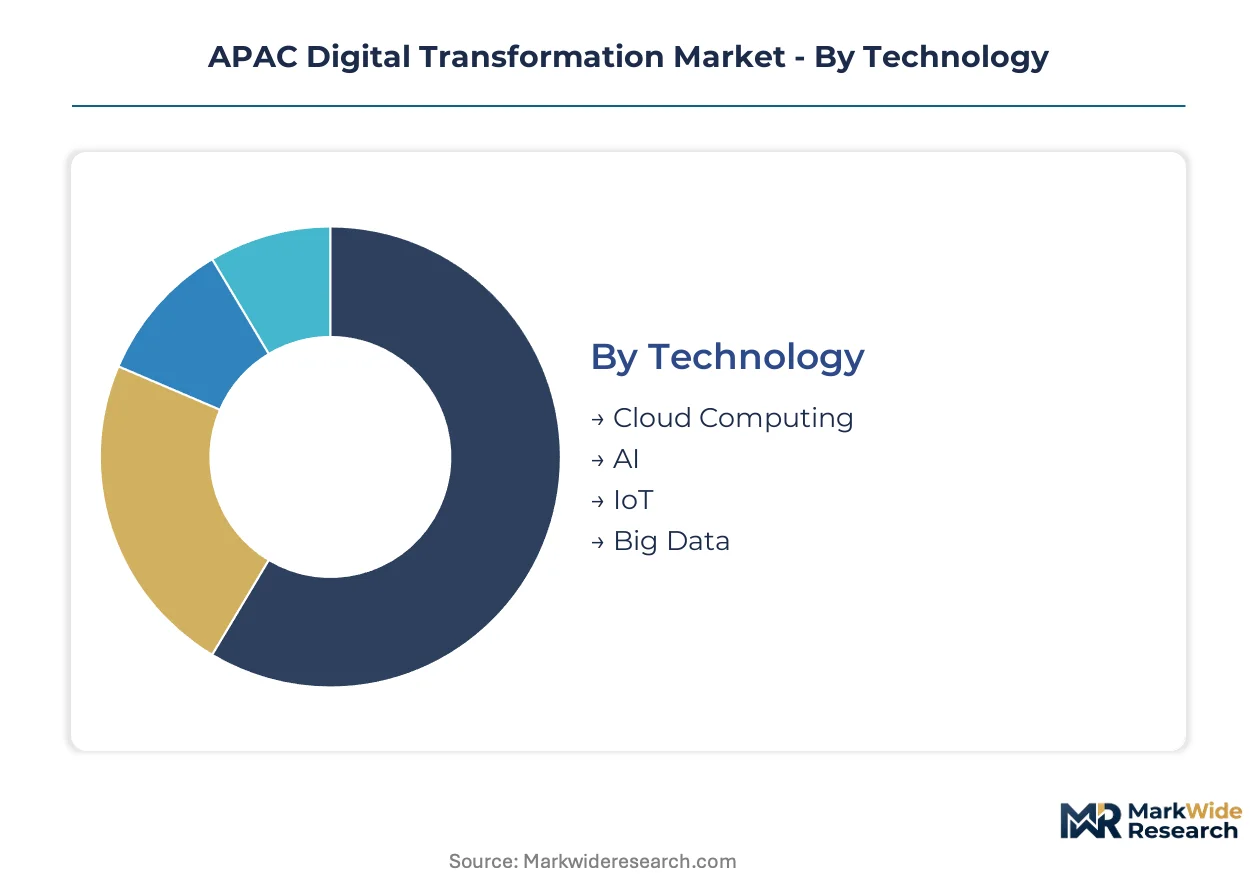
Technology selection in APAC digital transformation is bifurcating between compliance-driven sovereign infrastructure and performance-optimized elastic platforms. Deployment architecture decisions now precede vendor selection, as data residency mandates from China's MIIT and Japan's METI reshape procurement workflows across banking, automotive, and public sector verticals.
Technology:
Investment intensity separates buyers in this category, with regulated industries prioritizing audit-ready platforms over cost optimization.
- Cloud Computing:API-first infrastructure replaces legacy on-premises stacks across Indian enterprise software modernization and Australian public sector digitization programs. Banking regulators in Southeast Asia mandate real-time payment cores that burst analytics workloads to external infrastructure while retaining transaction data locally.
- AI:Machine learning pipelines automate document processing and predictive maintenance in Japanese automotive supplier networks. GPU and AI accelerator procurement concentrates with Taiwan and South Korean foundries, creating supply bottlenecks that extend deployment timelines for fintech startups.
- IoT:Sensor networks enable METI-funded smart factory initiatives across Tokyo-Osaka manufacturing corridors.
- Big Data:Customer data platforms resegment databases to comply with India's TRAI localization consultations.
Cloud Computing leads volumes today; AI is gaining share fastest.
Deployment Model:
Regulatory exposure determines architecture choice, with data sovereignty requirements fragmenting workload placement across national boundaries.
- Hybrid Cloud:Orchestration platforms maintain transaction data on-premises while bursting analytics to external infrastructure, compressing vendor consolidation timelines as Singaporean and Thai banks demand single-pane management. METI data free flow principles govern cross-border design for multinationals operating across Japanese corridors.
- Public Cloud:Elastic compute serves Indian fintech startups requiring rapid scaling, though China's MIIT licensing regime restricts foreign hyperscaler access and accelerates domestic platform substitution.
- Private Cloud:Captive infrastructure buildouts satisfy Australian sovereign cloud mandates for government contracts requiring in-country data residency.
- On-Premises:Legacy mainframe integration persists in Indian financial institutions connecting COBOL cores to modern API gateways.
Hybrid Cloud dominates procurement cycles; Private Cloud shows steepest expansion trajectory among regulated sectors.
End User:
Digital maturity gaps create divergent implementation timelines, with legacy-entrenched sectors facing protracted integration against greenfield adopters.
- Banking and Financial Services:Real-time payment infrastructure and embedded finance platforms accelerate across Southeast Asia, requiring API-first core banking replacements that comply with cross-border data friction from Australia's Privacy Act reforms.
- Manufacturing:Japanese automotive suppliers certify data handling protocols to METI standards, redirecting procurement toward compliance-validated platforms while Korean manufacturers adopt parallel certification tracks.
- Healthcare:Australian state governments in Victoria and New South Wales procure through outcome-defined subscription contracts rather than capital expenditure approvals.
- Retail:Omnichannel customer data platforms resegment databases under India's TRAI localization mandates.
Banking and Financial Services anchors current deployment value; Manufacturing is climbing the fastest as METI smart factory funding scales.
Service Type:
Skills availability shapes sourcing strategy, with platform engineering talent scarcity forcing outsourcing over in-house capability builds.
- Managed Services:Site reliability engineering talent scarcity across Singapore and Australia inflates dependency on outsourced platform operations rather than internal SRE team construction, expanding margins fastest as enterprises offload operational burden.
- Consulting:Strategy advisory guides sovereign cloud mandate navigation against interoperability cost trade-offs for regional deployment architectures.
- Integration:Legacy mainframe connectivity services bridge COBOL cores to modern API gateways in Indian financial institutions.
- Support:Outcome-defined contracts replace perpetual license models among Australian public sector agencies.
Managed Services leads revenue expansion; Consulting maintains highest attach rates to technology sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics reshape workload placement across APAC, with enterprises migrating infrastructure to jurisdictions offering clearer compliance pathways or domestic platform substitution incentives. Sovereign data mandates fragment unified global stacks into nationally bounded architectures.
China
Domestic cloud substitution accelerates as MIIT licensing restricts foreign hyperscaler access. State-backed providers capture enterprise workloads previously hosted on global platforms. Manufacturing clusters in Shenzhen and Shanghai pivot toward compliant ERP modernization.
India
PLI scheme incentives localize server and networking equipment production for enterprise data centers. TRAI data localization consultations force customer database resegmentation. Bengaluru and Hyderabad anchor fintech startup elastic compute demand.
Japan
METI data free flow principles govern cross-border architecture design for automotive suppliers. Smart factory funding drives edge-to-cloud pipeline deployment. Toyota-Osaka manufacturing corridors require certified data handling protocols.
Australia
Privacy Act reforms impose supply chain software provenance audits, extending procurement cycles. Sovereign cloud mandates for government contracts require in-country data residency. Victoria and New South Wales state governments adopt subscription-based platform engineering procurement.
Singapore
Banking regulators mandate real-time payment infrastructure with embedded finance platform builds. Hybrid cloud orchestration maintains transaction data locally while bursting analytics workloads externally. Financial services concentration drives API-first core banking replacement demand.
APAC Digital Transformation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated hyperscalers dominating elastic compute and fragmented system integrators capturing managed services expansion. The vendor base stratifies into three tiers: global cloud platforms with sovereign deployment capabilities, regional IT services firms with regulatory navigation expertise, and niche SaaS providers targeting vertical workflows. Competitive moves concentrate on strategic partnerships with domestic license holders and portfolio diversification into compliance-validated platform engineering.
Within the global cloud platform tier, Microsoft Corporation and Amazon Web Services anchor sovereign cloud deployment strategies across regulated APAC jurisdictions. SAP SE occupies a position exemplifying ERP modernization dominance in Japanese automotive supplier networks. Tata Consultancy Services represents the regional IT services archetype, capturing managed services margin expansion as enterprises outsource platform operations amid site reliability engineering talent scarcity.
| Leading Market Players |
|---|
| SAP SE |
| Amazon Web Services |
| Microsoft Corporation |
| Tata Consultancy Services |
| Huawei Technologies |
| IBM Corporation |
| Google LLC |
| Infosys |
| Oracle Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive sovereign cloud infrastructure anchors both supply positioning and pricing power for APAC digital transformation vendors, as MIIT licensing in China and METI data governance in Japan force multinationals to rebuild nationally bounded stacks rather than leverage unified global deployments. This fragmentation compels buyers to absorb premium costs for compliance-validated platforms while constraining vendor scale economies.
Pricing Analysis
Distributor margin compression runs through the channel as hyperscalers pursue direct sovereign cloud contracts with Australian government agencies and Singaporean banks. Subscription-based SaaS tiers dominate, with price differentiation resting on certification level (ISO 27001, SOC 2 Type II) and data residency guarantee granularity. Pricing pressure stems from aggressive price-performance competition among AWS, Microsoft Azure, and domestic Chinese providers for Indian fintech startup workloads. Mid-market manufacturers in Vietnam and Indonesia exhibit highest price sensitivity, while Japanese automotive suppliers prioritize audit-ready platforms over cost optimization.
Supply Chain Analysis
Regional distribution centers in Singapore and Sydney anchor hub-and-spoke patterns for cloud infrastructure hardware, with advanced GPU and AI accelerator supply concentrating in Taiwan and South Korea. Server and networking equipment production draws from China's domestic manufacturing incentives and India's PLI scheme localization. Single-source vulnerability in semiconductor foundry capacity creates procurement bottlenecks extending deployment timelines. Distribution runs through certified systems integrators with regulatory navigation expertise, particularly for METI-compliant data handling protocol certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC digital transformation constitutes a late-cycle quality story as banking regulators across Southeast Asia mandate real-time payment infrastructure with embedded finance specifications that privilege proven compliance track records over cost leadership.
For Market Incumbents: Anchor market position through sovereign cloud certification investments in Australia and Singapore, where government contracts now require in-country data residency. Defend against domestic Chinese cloud substitution by deepening API-first platform integration with Japanese automotive supplier networks. Prioritize site reliability engineering talent acquisition in Bengaluru and Hyderabad to capture managed services margin expansion. For New Entrants and Emerging Players: API-first core banking replacements offer technology-first wedge into Vietnam and Indonesia enterprise underpenetration, where mid-market manufacturers lack legacy ERP entrenchment. Target greenfield SaaS adoption in Indonesian manufacturing corridors with subscription pricing aligned to operational expenditure budgets. Pursue outcome-defined contracting models proven in Australian state government healthcare digitization programs. For Investors and Strategic Acquirers: Roll-up economics work for regional IT services firms with regulatory navigation expertise because sovereign data mandates fragment workload placement across national boundaries, creating acquisition opportunities for compliance-validated platform engineering capabilities. Monitor MIIT licensing regime enforcement intensity as inflection indicator for foreign hyperscaler market access compression versus domestic platform substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Deployment | Microsoft Azure and AWS anchor government contracts in Australia and Singapore through in-country data residency guarantees. |
| API-First Platform Integration | SAP SE sustains ERP modernization dominance by certifying data handling protocols to METI standards for Toyota-Osaka supplier networks. |
| Managed Services Expansion | Tata Consultancy Services captures margin growth as Singaporean and Australian enterprises outsource platform operations amid SRE talent scarcity. |
| Domestic Cloud Substitution | Huawei Technologies and state-backed Chinese providers capture enterprise workloads previously hosted on foreign hyperscaler platforms under MIIT restrictions. |
| Edge-to-Cloud Pipeline Buildout | METI-funded smart factory initiatives drive unified sensor network deployment across Japanese automotive supplier corridors. |
Research Methodology
Multiple input streams — primary interviews with CTOs and IT procurement officers at Southeast Asian banks, platform engineering leads at Indian fintech startups, and integration specialists serving Japanese automotive suppliers — were reconciled against hyperscaler capex disclosures, TRAI consultation documents, and METI smart factory funding announcements. Secondary validation drew from SEC filings of global cloud platforms, Australian Privacy Act reform drafts, and China's MIIT cloud service licensing registers. Bottom-up deployment volume estimates and top-down market sizing were triangulated to constrain forecast variance.
Cross-referencing historical adoption curves against panel input from regional IT services firms and sovereign cloud architects shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model (hybrid, public, private, on-premises), end-use vertical (banking, manufacturing, healthcare, retail), service type (managed services, consulting, integration), and regulatory cluster (MIIT-governed, METI-governed, TRAI-influenced, Privacy Act-compliant). CAGRs were derived from technology-specific penetration trajectories and compliance-driven procurement cycle compression.
The model holds under continued enforcement of data residency mandates and stable semiconductor foundry capacity; deviation in MIIT licensing escalation or Taiwan supply disruption would shift deployment timelines and vendor market access. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
UK Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
Thailand Digital Transformation Market
Digital Transformation
Innovation Management Market
Digital Transformation
Global Design Thinking Market
Digital Transformation
Israel Digital Transformation Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
Nigeria Digital Transformation Market
Digital Transformation
Italy Digital Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Workspace Transformation Market
Digital Transformation
Digital Transformation Market
Digital Transformation
Saudi Arabia Digital Transformation Market