
 Mexico Data Center Power Market | 2026-2036
Mexico Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Data Center Power Market Insights
Channel partnerships between equipment vendors and local engineering firms is fragmenting as hyperscale operators build direct procurement relationships with manufacturers. Schneider Electric SE leverages its Querétaro manufacturing footprint to sustain localized supply advantages for UPS and switchgear systems. Vertiv Holdings Co competes through thermal management integration with power distribution, while Eaton Corp PLC anchors its position in medium-voltage switchgear for large campus developments.
Mexico data center power encompasses electrical infrastructure engineered to deliver conditioned, uninterrupted electricity with specifications typically ranging from 480V three-phase distribution to redundant N+1 or 2N architectures for mission-critical loads. This infrastructure serves the fundamental purpose of eliminating downtime risk for server, storage, and networking equipment operating in controlled environments. Diesel generators retain structural dominance across the power source dimension due to immediate backup response requirements, though solar hybrid configurations gain traction in Baja California and northern states with favorable irradiance profiles. The hyperscale data center type commands the deepest capital commitment per site, while edge deployments proliferate in secondary cities where power capacity requirements sit below 1 MW.
CRE, Mexico's energy regulator, enforces interconnection standards that determine queue priority and cost allocation for data center loads above 5 MW. CFE, the national utility, operates under guidelines from SENER that shape wheeling agreements and backup power compliance for critical digital infrastructure. Stakeholders must monitor how forthcoming electricity market reforms affect long-term power purchase structures and on-site generation economics.
Market Dynamics
Hyperscale operators from cloud computing and digital services are compressing procurement cycles and demanding N+2 redundancy standards, forcing power infrastructure vendors to reconfigure delivery models and localize manufacturing footprints within Mexico's central corridor.
Growth Catalysts
- CRE Interconnection Queue Reform:Mexico's energy regulator has streamlined grid access priority for critical digital infrastructure loads above 5 MW, reducing connection timelines for Querétaro corridor developments.
- Hyperscale Facility Expansion:Cloud service providers are committing to multi-hundred-megawatt campus developments that anchor demand for medium-voltage switchgear and modular UPS architectures.
- Renewable Energy Certificate Mechanisms:SENER's clean energy credit frameworks enable data center operators to structure long-term power purchase agreements with solar and wind generators in Baja California and northern states.
Market Restraints
- Copper and Silicon Steel Input Volatility:Transformer and switchgear manufacturers face margin compression from commodity price swings in electrical steel laminations and copper busbar materials.
- CFE Grid Interconnection Bottlenecks:The national utility's transmission capacity constraints in Mexico City's fiber-rich zones create queue delays for facilities requiring immediate power delivery.
- Diesel Generator Carbon Intensity:Backup power compliance requirements lock operators into fossil-fuel dependency despite mounting Scope 1 emissions reporting obligations under evolving disclosure standards.
Strategic Opportunities
- Guadalajara Secondary Market Penetration:Jalisco's emerging tech hub presents sub-5 MW edge deployment opportunities with lower land costs and favorable CRE interconnection terms compared to saturated Mexico City zones.
- Lithium-Ion Battery Hybrid Integration:Converging electrochemical storage with traditional diesel rotary systems enables 15-minute ride-through capabilities that reduce generator runtime and fuel consumption.
- Direct Procurement Channel Development:Equipment vendors can bypass fragmented local engineering partnerships by establishing direct specification relationships with hyperscale engineering teams.
Industry Challenges
- Medium-Voltage Engineering Talent Scarcity:Mexico's technical institutes produce insufficient graduates with specialized training in 34.5 kV switchgear design and arc flash protection systems.
- Legacy 480V Infrastructure Retrofit Complexity:Aging facilities in Mexico City's established zones require phased power upgrades that disrupt tenant operations and complicate uptime guarantees.
- NOM-001 Certification Timeline Compression:Electrical equipment compliance testing through Mexico's national standards body creates 12-16 week delays that conflict with hyperscale construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Data Center Power Market |
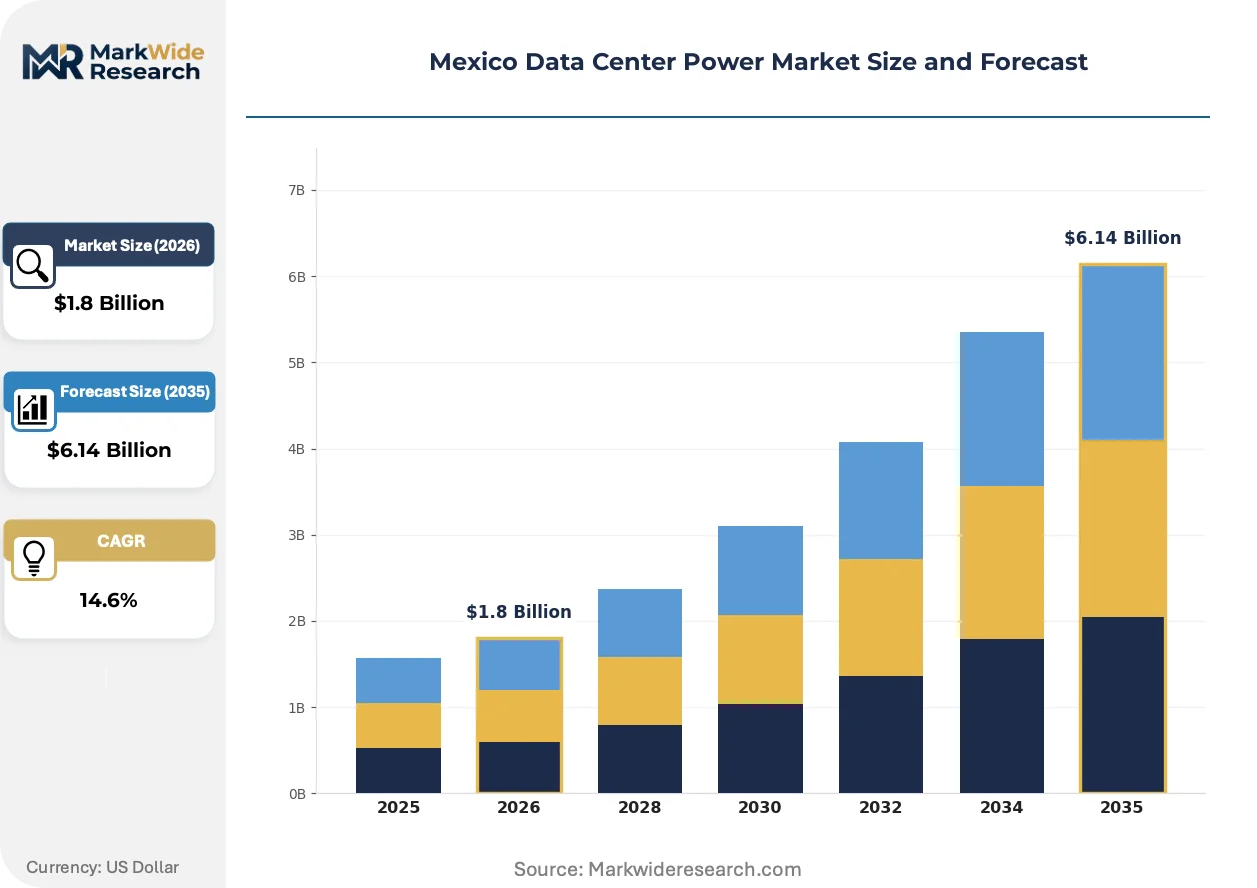
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Grid, Diesel Generators, Solar, Wind Data Center Type: Co-location, Hyperscale, Enterprise, Edge End User: Telecommunications, Financial Services, Healthcare, E-commerce Power Capacity: Below 1 MW, 1–5 MW, 5–10 MW, Above 10 MW |
| Companies Covered | Schneider Electric SE, Vertiv Holdings Co, Eaton Corp PLC, ABB Ltd, Generac Holdings Inc, GE Aerospace, Huawei Technologies, Legrand SA, Black Box, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Data Center Power Market Trends and Innovations
Power infrastructure across Mexican data centers is undergoing fundamental reconfiguration as thermal load densities rise and regulatory pressure intensifies on backup fuel choices. Three distinct vectors are compressing traditional design assumptions and reordering vendor priorities.
Modular busway power distribution with tap-off box flexibility is rendering obsolete traditional raised-floor PDU architectures in hyperscale halls. Cloud operators in Querétaro are specifying overhead busbar systems for 30-50 MW halls to enable rapid rack-level reconfiguration without floor penetration. This shift is compressing electrical infrastructure deployment timelines from 18 months to 9 months for comparable capacity.
CRE's forthcoming amendments to distributed generation interconnection standards are tightening on-site renewable integration requirements for loads above 10 MW. Industrial consequences include mandatory battery storage co-location and stricter power quality thresholds that favor inverter-based resources over rotating machinery. Northern Mexico facilities in Chihuahua and Sonora are responding with solar-plus-storage hybrid designs that reduce diesel runtime by 40-60 percent during grid outages.
Specification authority is migrating from local engineering firms to hyperscale internal design teams with standardized global templates. This disintermediation is collapsing the traditional vendor-distributor-contractor chain in favor of direct manufacturer relationships with centralized procurement functions. The pattern is most visible in central Mexico where Amazon Web Services, Microsoft, and Google operate captive engineering offices that issue binding equipment specifications to Schneider Electric's Querétaro facility and Vertiv's regional technical teams.
Mexico Data Center Power Market Segmentation
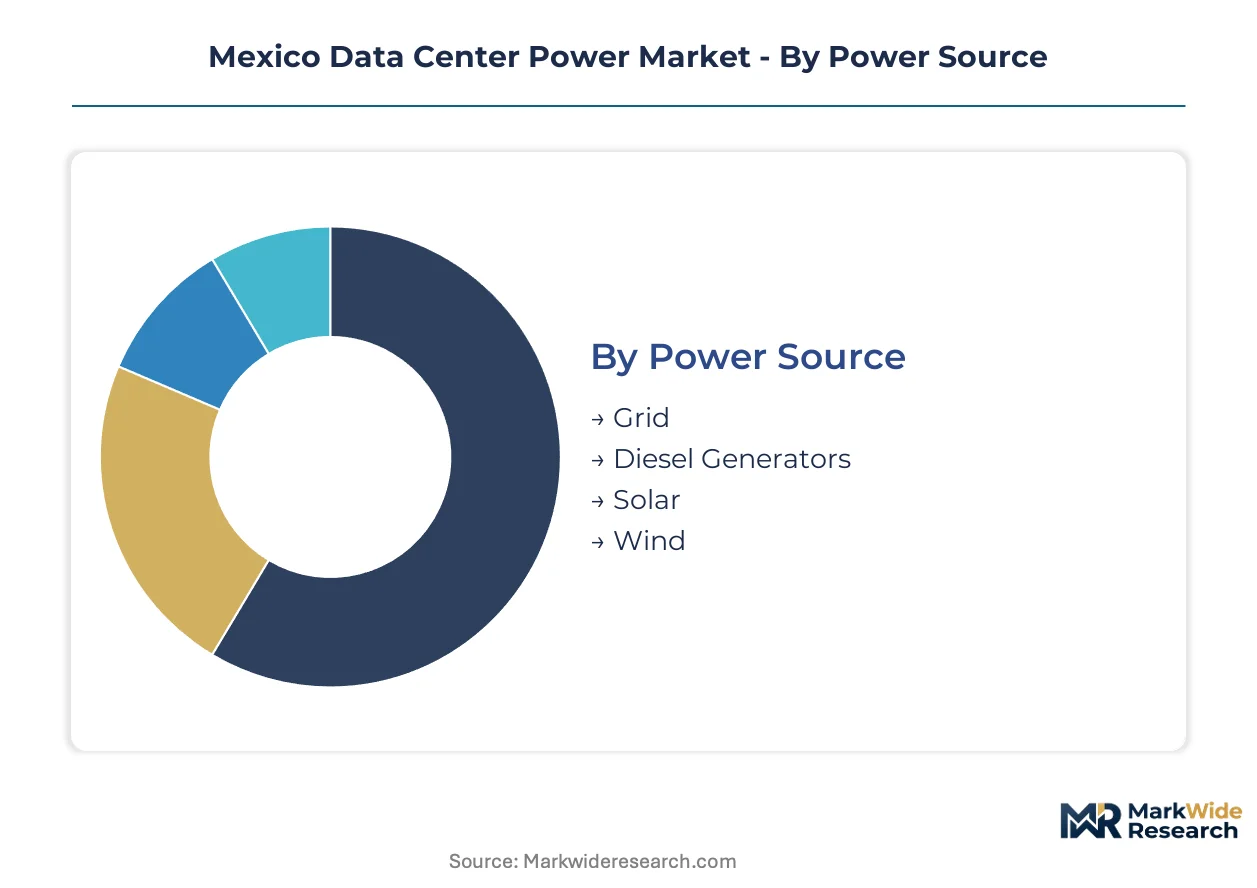
Segmentation of Mexico's data center power market reveals how procurement cycles, technical specifications, and regulatory exposure vary sharply across deployment archetypes. Understanding these divides enables equipment vendors to align manufacturing localization and channel strategies with the specific velocity of each segment.
Power Source:
Replacement and upgrade cycles stretch from 15-20 years for grid interconnection infrastructure to 3-5 years for solar hybrid configurations, creating divergent revenue recognition patterns for suppliers.
- Grid:Primary utility supply through CFE's transmission network delivers 480V three-phase distribution to facility substations. Mexico City's fiber-rich zones concentrate demand despite interconnection bottlenecks, while CRE's queue reforms accelerate access timelines for Querétaro corridor developments above 5 MW.
- Diesel Generators:Rotary backup systems provide immediate response capabilities with N+1 or 2N redundancy architectures for mission-critical loads. Structural dominance persists across all facility types due to compliance requirements, though Scope 1 emissions reporting obligations intensify pressure for runtime reduction strategies.
- Solar:Photovoltaic arrays integrated with battery storage enable 40-60 percent diesel runtime reduction during outages in Baja California and northern states with favorable irradiance profiles. SENER's renewable energy certificate mechanisms support long-term power purchase structures.
- Wind:Onshore turbine installations supply bulk renewable generation for campus-scale developments, with northern Mexico states capturing geographic advantages for grid-wheeling arrangements.
Diesel generators anchor the volume base while solar gains share at the steepest rate.
Data Center Type:
Capital intensity per megawatt installed separates hyperscale deployments from edge infrastructure by an order of magnitude, reshaping vendor engagement models.
- Hyperscale:Multi-hundred-megawatt campus developments specify medium-voltage switchgear and modular UPS architectures with N+2 redundancy standards. Cloud operators in Querétaro compress electrical infrastructure deployment timelines from 18 months to 9 months through overhead busbar systems.
- Edge:Sub-5 MW deployments proliferate in secondary cities including Guadalajara where lower land costs and favorable CRE interconnection terms support rapid provisioning. Power capacity requirements sit below 1 MW for distributed computing nodes serving latency-sensitive applications.
- Co-location:Multi-tenant facilities balance standardized power architectures with tenant-specific redundancy requirements, creating specification complexity for switchgear and UPS vendors.
- Enterprise:Captive data centers operated by large corporations maintain legacy 480V infrastructure requiring phased upgrade strategies that disrupt operations and complicate uptime guarantees.
Hyperscale facilities command the deepest capital commitment per site while edge deployments expand most quickly across secondary markets.
End User:
Uptime requirements and procurement authority concentration distinguish financial services from telecommunications operators.
- Financial Services:Banking and insurance institutions mandate 2N redundancy architectures with sub-15-second failover capabilities for trading and transaction processing systems. Mexico City concentrates demand due to proximity to financial district infrastructure.
- Telecommunications:Carrier-neutral facilities and network operator data centers prioritize power density for 5G core infrastructure and edge computing nodes. Querétaro's emerging corridor captures hyperscale cloud partnerships.
- Healthcare:Hospital systems and health insurers deploy localized data infrastructure for electronic medical records with backup power compliance tied to patient safety regulations.
- E-commerce:Online retail platforms drive demand for distributed edge capacity to support fulfillment logistics and real-time inventory systems across Mexican population centers.
Telecommunications anchors the volume base while financial services gains share at the steepest rate.
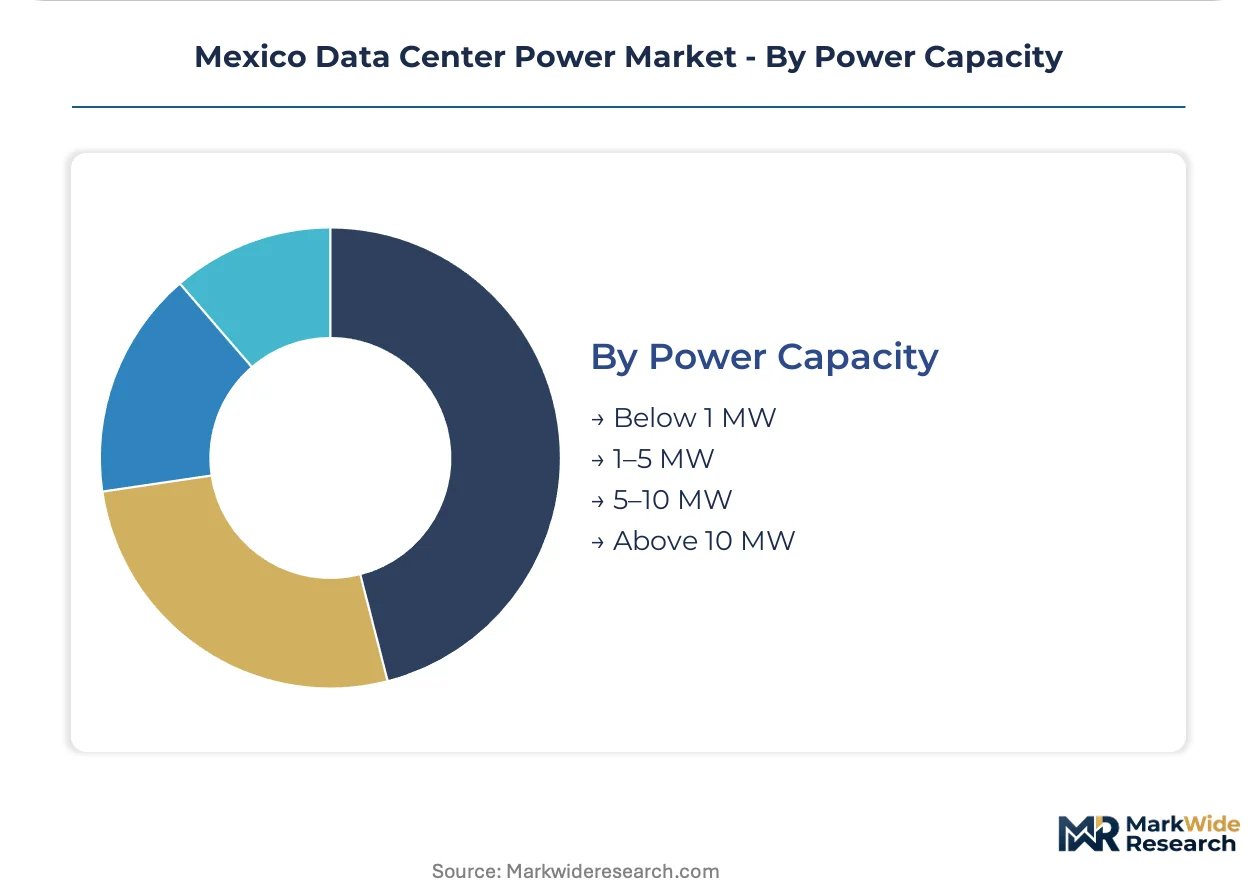
Power Capacity:
Regulatory thresholds at 5 MW and 10 MW create distinct compliance and interconnection cost structures that segment the market.
- Above 10 MW:Campus-scale developments trigger CRE's forthcoming distributed generation interconnection amendments requiring mandatory battery storage co-location and stricter power quality thresholds. Northern Mexico facilities respond with solar-plus-storage hybrid designs.
- 5–10 MW:Mid-scale facilities occupy a transitional zone where N+1 redundancy remains standard but operators evaluate N+2 upgrades to attract hyperscale tenant commitments.
- 1–5 MW:Enterprise and co-location facilities in this bracket face CFE grid interconnection bottlenecks in Mexico City's saturated zones, pushing development toward Querétaro and Guadalajara.
- Below 1 MW:Edge computing nodes and small enterprise deployments access simplified CRE interconnection terms with lower queue priority but faster approval timelines.
Above 10 MW deployments anchor the volume base while below 1 MW capacity tiers climb the fastest as edge infrastructure proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Querétaro commands pricing premiums 15-20% above Mexico City for power infrastructure due to CRE interconnection queue advantages, while Jalisco's Guadalajara corridor undercuts both markets on land and labor inputs for sub-5 MW edge deployments.
Querétaro Corridor
Hyperscale cloud operators anchor demand for medium-voltage switchgear and modular UPS architectures with N+2 redundancy standards. CRE's streamlined queue reforms reduce grid connection timelines for loads above 5 MW. The Bajío Region concentrates manufacturing-adjacent data infrastructure serving automotive and aerospace supply chains.
Mexico City Metro
Financial services institutions mandate 2N redundancy architectures with sub-15-second failover for trading systems. CFE transmission capacity constraints create interconnection bottlenecks in fiber-rich zones. The established Santa Fe and Tlalnepantla clusters face phased retrofit complexity for legacy 480V infrastructure.
Nuevo León
Monterrey's industrial base drives enterprise data center demand for captive power infrastructure. SENER guidelines shape wheeling agreements for facilities seeking backup power compliance. The Apodaca-Santa Catarina sub-corridor attracts co-location operators serving cross-border manufacturing.
Jalisco
Guadalajara's emerging tech hub presents sub-5 MW edge deployment opportunities with favorable CRE interconnection terms. Lower land costs support rapid provisioning for latency-sensitive applications. The Tlajomulco de Zúñiga technology park anchors distributed computing node expansion.
Northern Border States
Baja California and Sonora capture solar hybrid traction with favorable irradiance profiles reducing diesel runtime. SENER's renewable energy certificate mechanisms enable long-term power purchase structures. Mexicali and Hermosillo facilities deploy solar-plus-storage designs under forthcoming CRE distributed generation amendments.
Mexico Data Center Power Market Competitive Landscape
Integrated power infrastructure conglomerates and specialized thermal-electrical integration firms split the market between turnkey campus solutions and component-level optimization. The vendor base concentrates around three strategic archetypes: European-headquartered electrical equipment multinationals with localized manufacturing, North American power quality specialists with regional technical service networks, and Asian technology conglomerates with cost-optimized product portfolios. Competitive moves center on direct procurement channel development with hyperscale engineering teams and lithium-ion battery hybrid system integration.
Within the integrated infrastructure tier, Schneider Electric SE anchors European manufacturing localization through its Querétaro facility, while Vertiv Holdings Co occupies a position emphasizing thermal management convergence with power distribution. Eaton Corp PLC exemplifies the medium-voltage switchgear specialization archetype for large campus developments. These three companies represent distinct strategic postures: captive manufacturing proximity, integrated system architecture, and heavy electrical equipment depth.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Holdings Co |
| Eaton Corp PLC |
| ABB Ltd |
| Generac Holdings Inc |
| GE Aerospace |
| Huawei Technologies |
| Legrand SA |
| Black Box |
| Others |
Pricing and Supply Chain Analysis
The Laredo-Colombia freight corridor's escalating drayage costs amplify supply concentration effects in central Mexico, compressing margins for transformer manufacturers while hyperscale operators exploit procurement scale to extract configured-to-order premiums from stranded distributors.
Pricing Analysis
The customization-premium spread separates standard switchgear offerings from N+2 redundant configurations specified by Querétaro hyperscale campuses, with price differentiation anchored in copper busbar grade and UL certification tier. Project-based long-term offtake contracts dominate medium-voltage equipment procurement, though spot purchasing persists for diesel generator consumables. Pricing pressure stems from silicon steel lamination cost volatility eroding transformer margins. Edge deployment buyers in Guadalajara exhibit highest price sensitivity, while financial services operators in Mexico City accept premium positioning for sub-15-second failover guarantees.
Supply Chain Analysis
Supplier-financing facilities extended by Schneider Electric's Querétaro facility compress payment cycles for local engineering contractors, reshaping working capital dynamics across the procurement chain. Manufacturing concentration centers on Mexico, the United States, and China for switchgear assemblies, with copper cathode and electrical steel laminations as critical raw material dependencies. Single-source vulnerability for lithium-ion battery cells creates exposure to cathode chemistry transitions. Distribution runs through direct manufacturer relationships with hyperscale engineering teams, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's data center power market sits at a platform-economics inflection where specification authority migration from local engineering firms to hyperscale captive design teams restructures vendor interoperability requirements around standardized global templates.
For Market Incumbents: Insulate medium-voltage switchgear positions by deepening backward integration into copper busbar fabrication and securing NOM-001 certification pre-approval for modular UPS platforms. The threat of Asian cost-optimized entrants into sub-5 MW edge segments demands channel control reinforcement through direct specification relationships with hyperscale engineering offices in Querétaro.
For New Entrants and Emerging Players: Build out lithium-ion battery hybrid integration capabilities targeting the 1-5 MW enterprise retrofit segment in Mexico City's saturated zones, where legacy 480V infrastructure creates specification complexity incumbents underweight. Guadalajara's sub-5 MW edge corridor offers the most penetrable geography, with CRE interconnection advantages supporting rapid deployment timelines. A technical service partnership model with local engineering firms bypasses direct hyperscale procurement barriers.
For Investors and Strategic Acquirers: Specialized thermal-electrical integration firms with captive battery storage engineering talent represent the most defensible acquisition archetype as CRE's distributed generation amendments mandate co-location requirements. Long-term viability hinges on CRE interconnection queue positioning and SENER renewable energy certificate mechanism access. The signal to monitor is hyperscale procurement centralization velocity—accelerating direct manufacturer relationships compress distributor valuation multiples while elevating integrated solution providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Procurement Channel Development | Bypasses fragmented local engineering partnerships to capture hyperscale specification authority migration. |
| Lithium-Ion Battery Hybrid Integration | Enables 15-minute ride-through capabilities that reduce diesel runtime under CRE's forthcoming amendments. |
| Querétaro Manufacturing Localization | Compresses delivery timelines from 18 months to 9 months for overhead busbar systems. |
| NOM-001 Certification Pre-Approval Investment | Eliminates 12-16 week compliance delays that conflict with hyperscale construction schedules. |
| Guadalajara Edge Market Penetration | Exploits favorable CRE interconnection terms and lower land costs for sub-5 MW deployments. |
Research Methodology
A standing panel of data center engineering directors, CFE interconnection officers, CRE regulatory specialists, and medium-voltage switchgear procurement managers provided ongoing calibration across the study period. Primary interviews with hyperscale facility developers in Querétaro and edge computing operators in Guadalajara combined with secondary validation against SENER policy filings, CRE interconnection queue data, CFE transmission planning documents, and equipment vendor SEC disclosures. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates across power source and facility type segments.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning power source architecture, data center deployment type, end-user industry vertical, and regional regulatory cluster. CAGRs derived from installed capacity buildout trajectories and equipment replacement cycle analysis incorporated hyperscale capex commitment patterns and CRE queue reform implementation timelines as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Asian technology conglomerates would shift outcomes beyond modeled ranges. Macroeconomic deviation in copper and silicon steel input markets, regulatory acceleration of diesel generator carbon restrictions, or technological breakthrough in solid-state battery chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Global Data Center Rack and Enclosure Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
IT Infrastructure Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Germany Data Center Power Market