
 Mexico Data Center Market | 2026-2036
Mexico Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Data Center Market Insights
FERC-aligned cross-border energy frameworks is shifting the cost-of-entry calculus for foreign operators seeking Mexican grid connectivity. Amazon Web Services leverages its renewable power purchase agreements to sustain operations in Querétaro State. Microsoft Azure anchors its expansion strategy around direct CFE interconnection capacity. KIO Networks competes through localized fiber routes that bypass traditional carrier hotels in Mexico City.
A data center constitutes a dedicated facility housing servers, storage systems, and networking infrastructure with controlled environmental parameters—typically maintaining temperatures between 18°C and 27°C and achieving power usage effectiveness ratios below 1.5—for processing, storing, and distributing digital information across commercial and industrial applications. Colocation offerings dominate current revenue as enterprises divest owned facilities. Hyperscale deployments absorb the fastest capacity additions, driven by cloud service providers requiring contiguous megawatt-scale footprints. Managed hosting retains margin concentration among mid-market clients lacking internal IT operations.
CRE, Mexico's energy regulator, enforces interconnection standards that determine facility viability, while PROFECO monitors service-level compliance in consumer-facing hosting agreements. NOM-001-SEDE electrical standards shape equipment procurement and installation protocols for all new builds. Stakeholders must weigh CFE tariff restructuring against state-level fiscal incentives when siting capacity beyond the Mexico City-Querétaro axis.
Market Dynamics
CFE tariff restructuring is compressing operator margins while FERC-aligned cross-border energy frameworks enable renewable power procurement that reshapes facility siting economics across central Mexico.
Growth Catalysts
- Financial services expansion:Banks and insurers are divesting owned IT infrastructure and migrating to colocation facilities in Mexico City and Querétaro, creating sustained demand for Tier III+ certified capacity.
- NOM-001-SEDE electrical standards:Updated installation protocols are accelerating equipment modernization cycles and disqualifying legacy facilities that cannot achieve compliant power distribution architectures.
- Bajío corridor concentration:Hyperscale deployments cluster in Querétaro and Guanajuato where land costs and CFE industrial tariffs undercut Monterrey alternatives by double-digit percentages.
Market Restraints
- CFE tariff volatility:Industrial electricity rate uncertainty under the Horario de Verano framework prevents long-term power purchase agreements that hyperscale operators require for 15-year facility financing.
- Fiber route concentration:International connectivity depends on a limited number of submarine cable landings in Veracruz and landing stations controlled by dominant carrier hotels in Mexico City.
- Water scarcity in northern states:Cooling system design constraints intensify in Chihuahua and Nuevo León where aquifer depletion restricts evaporative cooling deployment for high-density compute.
Strategic Opportunities
- Yucatán Peninsula latency arbitrage:Submarine cable extensions to Mérida create positioning for Caribbean and Central American financial services traffic currently routed through Miami.
- CRE interconnection standard harmonization:Simplified grid connection protocols for renewable generators enable behind-the-meter solar and wind deployment that bypasses CFE tariff exposure.
- Edge computing for manufacturing:Automotive OEMs in Puebla and Aguascalientes require sub-10 millisecond latency for industrial IoT, creating distributed micro-facility demand outside traditional metro hubs.
Industry Challenges
- Certified operations talent scarcity:Uptime Institute and TIA-942 accredited facility managers command premium compensation that strains mid-market operator payroll structures.
- Legacy copper network integration:Enterprise clients in secondary cities maintain ISDN and T1 dependencies that complicate hybrid cloud connectivity architecture design.
- PROFECO service-level enforcement:Consumer-facing hosting agreements face intensified audit scrutiny that extends contract negotiation timelines and elevates legal compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Data Center Market |
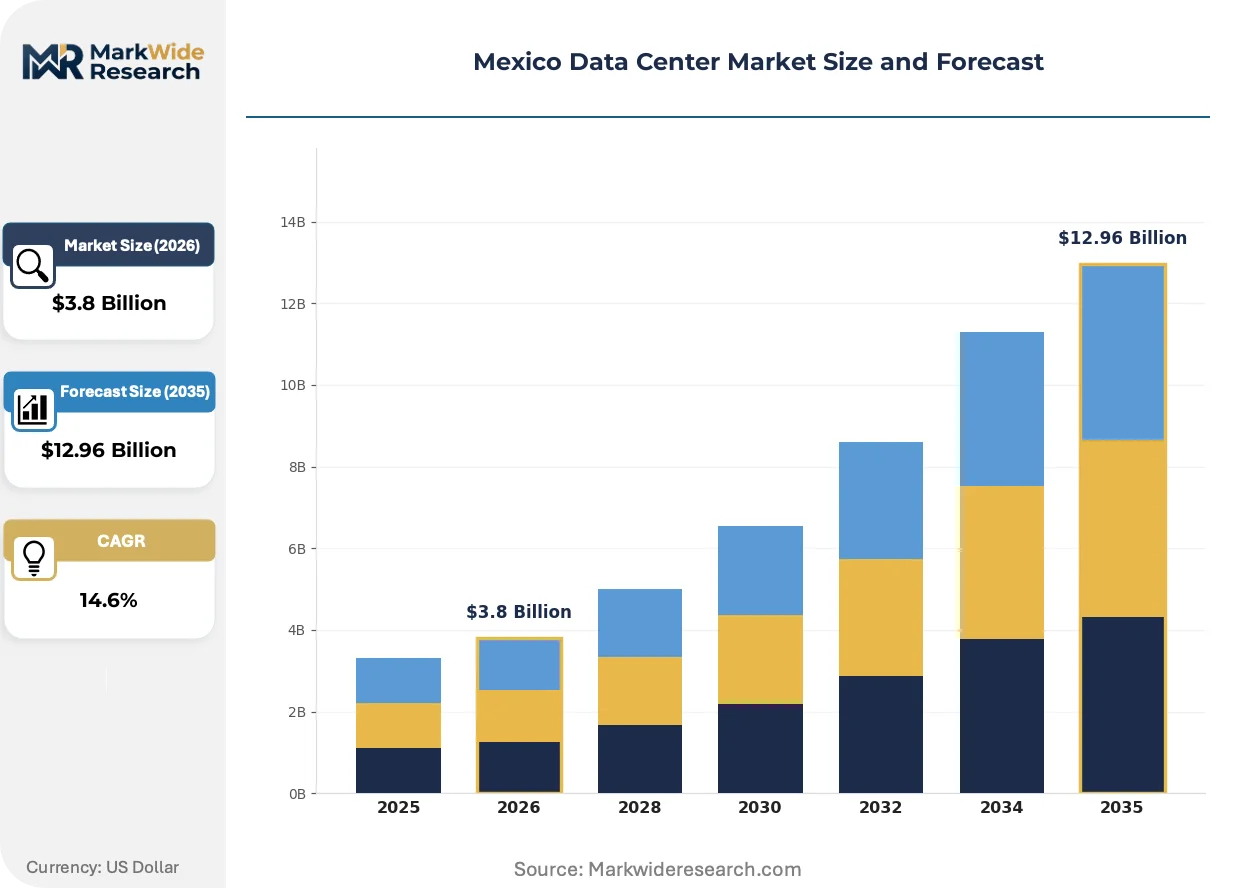
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Hyperscale, Managed Hosting, Dedicated Servers Technology: Cooling Systems, Power Management, Networking Equipment, Security Solutions End User: BFSI, Telecom, Retail, Healthcare Service Type: Infrastructure as a Service, Backup Solutions, Disaster Recovery, Cloud Services |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Equinix, KIO Networks, CloudHQ, Ascenty, Telmex, Odata, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Data Center Market Trends and Innovations
Liquid cooling deployment is accelerating rack density thresholds while regulatory pressure on energy consumption forces architectural reconsideration of facility thermal management across the Mexican central plateau.
Direct-to-chip liquid cooling is electrifying high-performance compute deployment in Querétaro State. Hyperscale operators are adopting cold plate and immersion systems for AI training clusters exceeding 50kW per rack. This thermal architecture is compressing facility footprint requirements and enabling campus-style expansion on constrained land parcels.
CRE enforcement of interconnection queue transparency is altering generator contracting patterns for data center loads. The regulator's mandated disclosure of grid connection timelines forces developers to secure renewable energy certificates before breaking ground. Colocation providers in Mexico City are responding by pre-leasing capacity contingent on confirmed CFE interconnection dates.
Enterprise procurement of managed hosting is fragmenting across workload-specific contracts rather than consolidated infrastructure agreements. Mid-market manufacturers in Guanajuato and San Luis Potosí are unbundling storage, compute, and network services to optimize unit economics. This pattern is most visible in the automotive supplier tier where IT outsourcing decisions follow plant-level operational autonomy rather than corporate standardization.
Mexico Data Center Market Segmentation
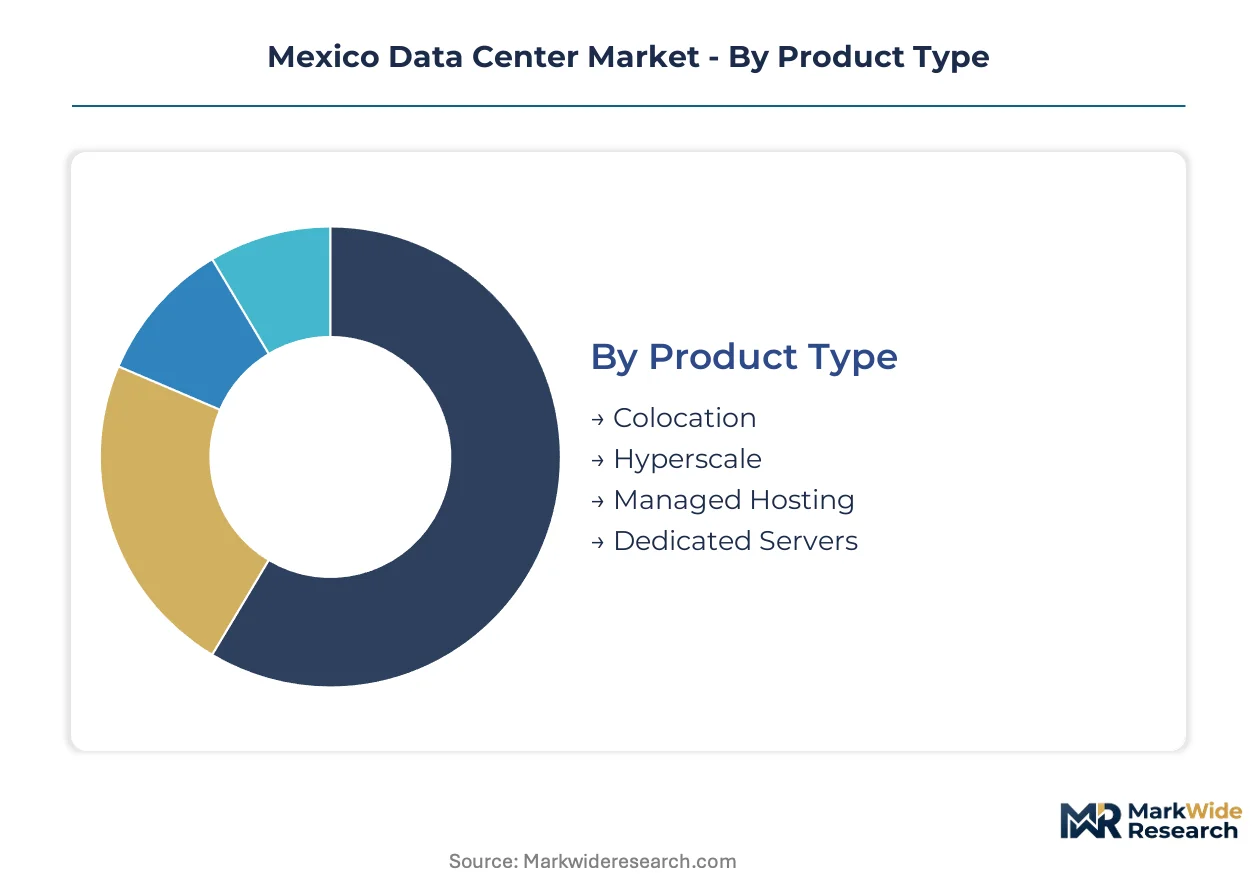
Mexico's data center segmentation reveals how facility economics and regulatory frameworks reshape procurement patterns across distinct operational models. Each category captures divergent upgrade cycles driven by CFE tariff volatility, NOM-001-SEDE compliance deadlines, and hyperscale expansion timelines.
Product Type:
Facility modernization cycles accelerate where legacy power distribution cannot meet CRE interconnection standards or NOM-001-SEDE installation protocols.
- Colocation:Third-party facility space with shared power and cooling infrastructure where enterprises lease rack, cage, or suite configurations. Financial services firms in Mexico City and Querétaro are divesting owned facilities and migrating to Tier III+ certified colocation space as CFE tariff uncertainty makes self-operated power economics untenable.
- Hyperscale:Single-tenant facilities exceeding 15 megawatts with contiguous megawatt-scale footprints designed for cloud service provider requirements. Amazon Web Services and Microsoft Azure are concentrating deployments in the Bajío corridor where Querétaro State land costs and industrial electricity tariffs undercut Monterrey alternatives.
- Managed Hosting:Fully outsourced IT infrastructure where providers own and operate servers, storage, and network equipment on behalf of clients. Mid-market manufacturers in Guanajuato and San Luis Potosí are unbundling services to optimize unit economics.
- Dedicated Servers:Single-tenant physical server deployments with exclusive resource allocation and root access. Gaming and streaming platforms in Mexico City require bare-metal performance for latency-sensitive workloads.
Colocation sits at the top of the volume ranking, with Hyperscale climbing the fastest.
Technology:
Equipment refresh decisions hinge on thermal density thresholds and CRE-mandated grid connection transparency for renewable generator contracting.
- Cooling Systems:Mechanical infrastructure maintaining 18°C to 27°C operating temperatures through air, liquid, or hybrid architectures. Direct-to-chip liquid cooling is electrifying high-performance compute deployment in Querétaro State for AI training clusters exceeding 50kW per rack.
- Power Management:Electrical distribution from substation to rack including UPS, switchgear, and PDUs achieving PUE ratios below 1.5. Updated NOM-001-SEDE protocols are accelerating equipment modernization cycles.
- Networking Equipment:Routers, switches, and optical transport enabling intra-facility and wide-area connectivity. KIO Networks competes through localized fiber routes that bypass traditional carrier hotels in Mexico City.
- Security Solutions:Physical access control, video surveillance, and cybersecurity infrastructure protecting facility and data assets. PROFECO service-level enforcement intensifies audit scrutiny for consumer-facing hosting agreements.
Power Management commands the largest installed base, though Cooling Systems is expanding most quickly as rack densities climb.
End User:
Vertical-specific compliance requirements and latency tolerances drive divergent facility specifications across Mexican states.
- BFSI:Banking, financial services, and insurance institutions requiring Tier III+ certification and sub-10 millisecond latency for trading platforms. Banks and insurers are divesting owned IT infrastructure and migrating to colocation facilities in Mexico City and Querétaro.
- Telecom:Mobile network operators and internet service providers hosting core network functions and edge caching infrastructure. 5G rollout is concentrating radio access network equipment in metro edge facilities.
- Retail:Omnichannel merchants processing e-commerce transactions and inventory management systems. Peak seasonal demand patterns require elastic capacity scaling.
- Healthcare:Hospital systems and insurers managing electronic health records and diagnostic imaging archives. Regulatory compliance for patient data residency shapes facility selection.
BFSI dominates current capacity absorption, with Telecom gaining share fastest as 5G edge requirements proliferate.
Service Type:
Workload-specific contracting fragments enterprise procurement away from consolidated infrastructure agreements toward unbundled service optimization.
- Infrastructure as a Service:Compute and storage resources delivered on-demand through virtualized platforms with utility-style billing. Automotive OEMs in Puebla and Aguascalientes require sub-10 millisecond latency for industrial IoT applications.
- Backup Solutions:Data protection through tape, disk, or cloud-based replication with defined recovery point objectives. Manufacturing suppliers follow plant-level operational autonomy rather than corporate standardization.
- Disaster Recovery:Secondary site infrastructure enabling business continuity with specified recovery time objectives. Yucatán Peninsula positioning targets Caribbean and Central American financial services traffic.
- Cloud Services:Integrated platform offerings spanning compute, storage, database, and application hosting. Microsoft Azure anchors expansion strategy around direct CFE interconnection capacity.
Infrastructure as a Service leads deployment volume, with Disaster Recovery showing the steepest expansion trajectory as regulatory pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified data center operations talent concentrates in Mexico City and Querétaro, anchoring facility management expertise for the national market. This workforce distribution shapes where Tier III+ certified capacity expands and where hyperscale operators site training-dependent operations.
Mexico City Metro
Financial services divestment of owned IT infrastructure and 5G edge caching requirements drive sustained demand. CFE tariff restructuring under the Horario de Verano framework complicates long-term power contracting for new builds. Carrier hotels in the capital control international fiber connectivity, though KIO Networks deploys localized routes that bypass these concentration points.
Bajío Region
Hyperscale deployments from Amazon Web Services and Microsoft Azure concentrate in Querétaro and Guanajuato where land costs undercut northern alternatives. CRE interconnection standards enforce grid connection transparency that shapes generator contracting timelines. Direct-to-chip liquid cooling enables AI training clusters exceeding 50kW per rack on constrained land parcels.
Nuevo León
Monterrey's industrial base generates enterprise colocation demand from automotive and aerospace suppliers. Water scarcity restricts evaporative cooling deployment for high-density compute, forcing alternative thermal architectures. The state's manufacturing corridor maintains legacy copper network dependencies that complicate hybrid cloud connectivity.
Yucatán Peninsula
Submarine cable extensions to Mérida create positioning for Caribbean and Central American financial services traffic currently routed through Miami. PROFECO service-level enforcement intensifies audit scrutiny for consumer-facing hosting agreements. Disaster recovery site selection targets this geography for geographic diversity from central Mexico seismic zones.
Mexico Data Center Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Mexico's data center market. The vendor base spans multinational cloud hyperscalers, regional colocation providers, and carrier-affiliated operators with fiber network assets. Three strategic archetypes dominate: renewable-powered hyperscale campus developers, interconnection-centric colocation platforms, and telecom-integrated edge facility operators. Capacity pre-leasing contingent on confirmed CFE interconnection dates and direct renewable power purchase agreements represent the dominant competitive moves.
Among hyperscale cloud operators, Amazon Web Services, Microsoft Azure, and Google Cloud exemplify the renewable-powered campus archetype. These operators anchor their Mexico strategies around direct CFE interconnection capacity and power purchase agreements that bypass tariff volatility. Regional specialists including KIO Networks occupy positions emphasizing localized fiber infrastructure and carrier hotel bypass architectures. Equinix represents the interconnection-centric platform model with metro-focused facility deployment.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Equinix |
| KIO Networks |
| CloudHQ |
| Ascenty |
| Telmex |
| Odata |
| Others |
Pricing and Supply Chain Analysis
Hyperscale operators' preference for unbundled compute, storage, and network procurement is forcing colocation providers to restructure service catalogs and compress margin structures across Mexico City and Querétaro.
Pricing Analysis
The bundled-versus-unbundled service split is fragmenting enterprise procurement patterns across the Mexican market. Pricing stratifies across premium Tier III+ certified facilities, standard Tier II deployments, and economy-grade legacy space with limited compliance documentation. Cost compression in standard-tier colocation is intensifying because mid-market manufacturers unbundle services to optimize unit economics. Financial services firms exhibit the lowest price sensitivity due to regulatory compliance mandates, while retail and gaming platforms drive the hardest per-unit negotiations.
Supply Chain Analysis
Critical cooling equipment supply rests on specialized producers in Germany, Japan, and the United States. Direct-to-chip liquid cooling components, high-efficiency UPS systems, and precision HVAC units feed from these concentrated manufacturing bases. Single-source vulnerability persists for sub-10 millisecond latency networking gear controlled by dominant carrier hotels. Distribution runs through authorized channel partners with CFE interconnection coordination capabilities, bypassing traditional IT distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential as liquid cooling adoption enables density premiums and CFE tariff restructuring accelerates facility modernization cycles.
For Market Incumbents: Acquire contiguous land parcels in Querétaro and Guanajuato before hyperscale campus development exhausts suitable sites. Secure renewable power purchase agreements that bypass CFE tariff volatility. Backward integration into captive fiber infrastructure neutralizes carrier hotel concentration risk. For New Entrants and Emerging Players: Capture edge computing demand from automotive OEMs in Puebla and Aguascalientes requiring sub-10 millisecond latency for industrial IoT. The Yucatán Peninsula disaster recovery segment remains penetrable due to geographic diversity from seismic zones. Lead with workload-specific managed hosting contracts rather than consolidated infrastructure agreements. For Investors and Strategic Acquirers: Asymmetric upside sits with regional colocation specialists holding CRE-confirmed interconnection dates and localized fiber routes. Long-term viability hinges on renewable energy certificate positioning and certified operations talent retention. Watch CFE tariff reform announcements as the primary inflection indicator for valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Power Purchase Agreement | AWS and Microsoft Azure leverage PPAs to bypass CFE tariff volatility in Querétaro. |
| Liquid Cooling Deployment | Direct-to-chip systems enable 50kW-plus AI training clusters on constrained Bajío land parcels. |
| Carrier Hotel Bypass Infrastructure | KIO Networks deploys localized fiber routes that circumvent Mexico City connectivity concentration. |
| Tier III+ Certification Investment | Financial services divestment mandates compliant capacity in Mexico City and Querétaro. |
| Edge Facility Micro-Deployment | Automotive OEMs in Puebla drive distributed compute demand outside traditional metro hubs. |
Research Methodology
Bottom-up hyperscale and colocation demand modeling reconciled against top-down CFE interconnection capacity tracking forms the analytical core of this study. Primary interviews with data center facility directors, CRE regulatory affairs leads, CFE grid planning officers, and enterprise IT procurement managers combined with secondary validation from CRE interconnection queue disclosures, CFE tariff filings, Uptime Institute certification databases, and hyperscaler capital expenditure reports. Triangulation across these sources ensures segment-level accuracy.
Input-output matrices map facility construction timelines, power procurement structures, and workload migration patterns across the projection horizon. Segmentation dimensions include product type, cooling technology tier, end-use vertical, and service delivery model. CAGRs derive from facility absorption rates, CFE industrial tariff trajectories, and hyperscale lease commencement schedules. Rack density thresholds and PUE improvement curves inform technology segment sizing.
CFE tariff reform implementation delays, CRE interconnection queue backlogs, and hyperscale lease cancellation clauses are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about power economics, regulatory enforcement intensity, and enterprise cloud migration velocity. A compact set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
Taiwan Data Center Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Rugged Servers Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Indonesia Data Center Physical Security Market
Data Center Infrastructure
Composable-Disaggregated Infrastructure Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Data Center Blade Server Market