
 China Data Center Power Market | 2026-2036
China Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
China Data Center Power Market Insights
Capital-intensity divergence between hyperscale builders and regional operators is bifurcating competitive dynamics across China's data center power sector. Huawei Technologies leverages integrated power-electronics manufacturing to control upstream component costs for self-built facilities. GDS Holdings Ltd anchors its position through wholesale colocation designs that sustain multi-megawatt deployment pipelines in tier-one cities. Schneider Electric SE competes by extending European high-efficiency UPS architectures into Chinese joint-venture production.
China data center power encompasses the generation, conditioning, backup, and distribution infrastructure that maintains continuous electrical supply to server halls, typically operating at voltages from 380V AC to 240V DC with power usage effectiveness targets below 1.3 for new builds. Its primary commercial purpose is to eliminate downtime risk while enabling density scaling beyond 30kW per rack in AI training facilities. Grid power and renewable energy segments dominate capital allocation as provincial utilities expand dedicated substation capacity for hyperscale campuses. Liquid cooling technology represents the fastest-growing structural category, with AI-driven management systems capturing expanding margin pools through predictive load-balancing software licenses.
MIIT enforces data center power-efficiency standards through PUE thresholds that shape facility design permits in eastern provinces, while GB standards govern electrical safety certification for UPS and switchgear equipment. The country's national energy regulator limits new coal-linked grid connections, pushing developers toward captive solar or storage-hybrid architectures. Stakeholders must monitor how provincial carbon-intensity quotas reshape site selection economics between coastal hubs and western renewable-rich zones.
Market Dynamics
MIIT-mandated PUE ceilings below 1.3 for new facilities are forcing wholesale redesign of power architectures across China's eastern seaboard, compressing legacy UPS deployment timelines and accelerating liquid cooling integration.
Growth Catalysts
- MIIT efficiency mandates:Binding PUE thresholds for new data center permits in Jiangsu and Zhejiang provinces are accelerating high-efficiency power electronics procurement.
- AI training clusters:Hyperscale demand for racks exceeding 30kW density is expanding dedicated substation capacity requirements across the Yangtze River Delta.
- Western renewable zones:Provincial carbon-intensity quotas are redirecting campus development toward Sichuan and Guizhou hydro-rich regions with captive solar hybrid designs.
Market Restraints
- Copper and rare earth volatility:Power distribution busway manufacturing faces input cost swings tied to concentrate supply from Inner Mongolia processing facilities.
- Grid connection queues:State Grid Corporation prioritization delays for 220kV substation builds are extending commissioning timelines in Beijing-Tianjin-Hebei.
- Legacy 380V AC lock-in:Existing server hall infrastructure constrains 240V DC distribution adoption despite efficiency gains.
Strategic Opportunities
- Greater Bay Area expansion:Shenzhen and Dongguan municipal incentives for green data centers are opening wholesale colocation pipelines with streamlined permitting.
- Storage-hybrid architectures:Lithium-ion and vanadium flow battery integration with grid-tied UPS systems creates new margin pools in peak-shaving services.
- Predictive load-balancing software:AI-driven power management licenses represent untapped recurring revenue streams for infrastructure vendors.
Industry Challenges
- Thermal-fluid engineering scarcity:Liquid cooling deployment pipelines face bottlenecks from limited domestic expertise in two-phase immersion system design.
- GB standards certification lag:NMPA-adjacent equipment approval timelines for imported switchgear stretch 8-14 months, delaying international vendor market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Data Center Power Market |
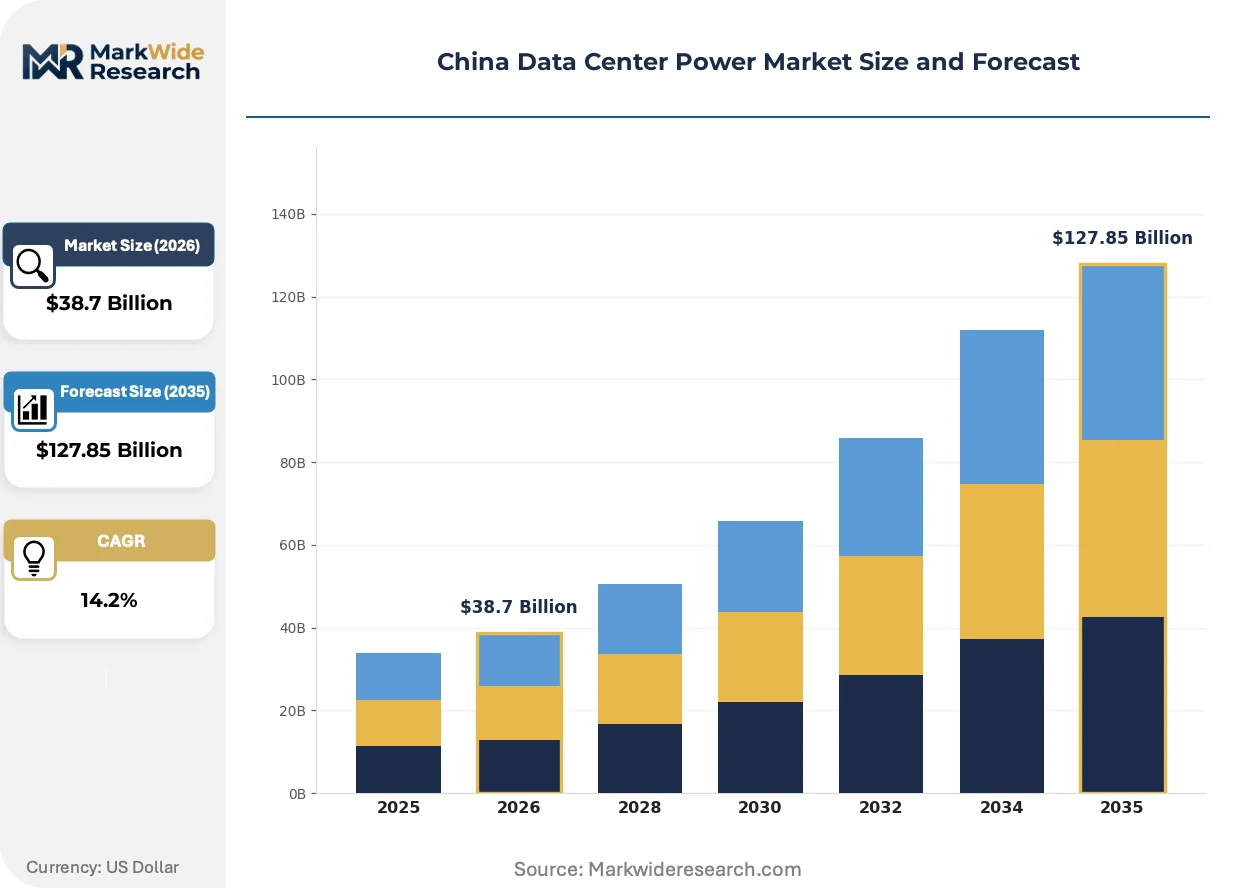
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Grid Power, Diesel Generators, Renewable Energy, UPS End User: Cloud Service Providers, Telecom Companies, Enterprises, Colocation Facilities Service Type: Managed Services, Infrastructure Services, Consulting, Professional Services Technology: Modular Systems, Liquid Cooling, AI-Driven Management, Smart Grid |
| Companies Covered | Huawei Technologies, GDS Holdings Ltd, China Telecom, China Mobile, Alibaba Cloud, Tencent Cloud, Schneider Electric SE, Eaton Corporation, Vertiv Holdings Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Data Center Power Market Trends and Innovations
Power electronics packaging and control intelligence are converging to compress footprint while elevating efficiency thresholds, redefining procurement criteria for hyperscale operators.
Silicon carbide (SiC) power modules are replacing silicon IGBTs in high-frequency UPS inverters, cutting switching losses by half. Cloud service providers in the Greater Bay Area are specifying SiC-based architectures for 2025-2026 delivery windows. The technology is miniaturizing rack-level power distribution units from 6U to 2U form factors.
MIIT's 2024 revised Data Center Energy Efficiency Management Regulations impose real-time PUE monitoring and annual disclosure requirements for facilities exceeding 5,000 standard racks. Operators in Jiangsu and Zhejiang must retrofit legacy halls or face permit non-renewal. Tier-two cities are responding by clustering developments near hydroelectric sources to offset grid carbon intensity.
Buyers are unbundling long-term maintenance from initial equipment contracts, favoring multi-vendor service marketplaces with uptime-guarantee pricing. State-owned enterprises and regional colocation providers are driving this shift, replacing single-source OEM service lock-in. The procurement pattern is most visible in Beijing-Tianjin-Hebei, where asset-light operators dominate new capacity additions.
China Data Center Power Market Segmentation
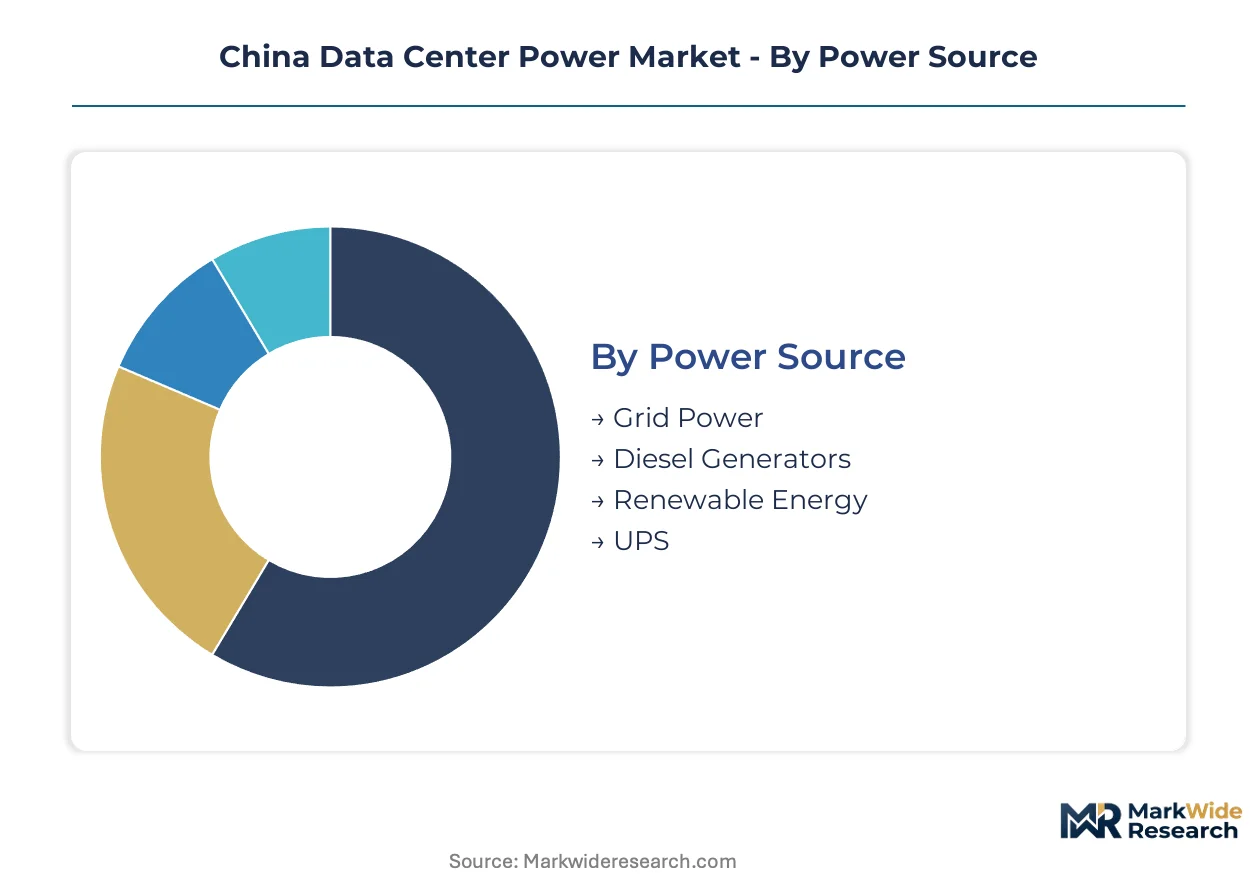
Segmentation in China's data center power market reveals how regulatory pressure and density requirements reshape procurement patterns across infrastructure tiers. Understanding these divisions clarifies where capital flows concentrate and which technology categories face accelerated replacement cycles.
Power Source:
Grid connections dominate eastern seaboard deployments, while western provinces attract renewable-hybrid investments through carbon-intensity quotas.
- Grid Power:State Grid Corporation and Southern Power Grid deliver 220kV-500kV dedicated substations to hyperscale campuses. Beijing-Tianjin-Hebei and Yangtze River Delta operators face connection queue delays as MIIT PUE enforcement intensifies.
- Renewable Energy:Captive solar and hydroelectric sourcing in Sichuan and Guizhou satisfies provincial carbon quotas. Developers pair photovoltaic arrays with lithium-ion storage to offset grid dependency during peak training loads.
- Diesel Generators:Backup systems remain mandatory for tier-three uptime certification despite emissions scrutiny. Inner Mongolia processing constraints create rare earth magnet supply volatility for generator manufacturing.
- UPS:Double-conversion and line-interactive architectures condition power for sub-20ms transfer requirements. Silicon carbide inverter modules are displacing silicon IGBTs in new 2025-2026 procurement specifications.
Grid Power commands the established base. The steepest expansion runs through Renewable Energy.
End User:
Customer scale determines whether facilities deploy captive engineering teams or outsource infrastructure lifecycle management entirely.
- Cloud Service Providers:Alibaba Cloud, Tencent Cloud, and Baidu AI Cloud drive 30kW-plus rack densities requiring liquid-cooled power distribution. Their self-built campuses in Greater Bay Area municipalities capture streamlined green data center permitting.
- Colocation Facilities:GDS Holdings and regional operators wholesale megawatt blocks to enterprises lacking capital for hyperscale construction. Wholesale designs sustain multi-megawatt deployment pipelines in tier-one cities with constrained land availability.
- Telecom Companies:China Mobile, China Telecom, and China Unicom operate edge facilities with 5-15kW rack averages. Their national backbone requirements prioritize 380V AC compatibility over 240V DC efficiency gains.
- Enterprises:State-owned banks and manufacturers maintain captive data halls with legacy UPS refresh cycles. Financial services compliance mandates 99.999% uptime guarantees that prolong diesel generator dependency.
Cloud Service Providers absorb the dominant share of new substation capacity. The fastest volume gains are occurring in Colocation Facilities.
Service Type:
Procurement unbundling is separating equipment ownership from operational responsibility across state-owned and private operators.
- Infrastructure Services:Electrical and mechanical system installation with commissioning validation. Beijing-Tianjin-Hebei asset-light operators favor multi-vendor service marketplaces over single-source OEM lock-in.
- Managed Services:Remote monitoring, predictive maintenance, and uptime-guarantee pricing models. AI-driven power management licenses create recurring revenue streams for infrastructure vendors.
- Consulting:Site selection, PUE optimization, and GB standards compliance advisory. Western renewable zone development requires hydroelectric integration expertise scarce in coastal engineering firms.
- Professional Services:Training, documentation, and spare parts logistics for operational handover. Two-phase immersion liquid cooling deployment faces domestic thermal-fluid engineering bottlenecks.
Infrastructure Services anchor current procurement spending. Managed Services are climbing the fastest as operators shed in-house engineering headcount.
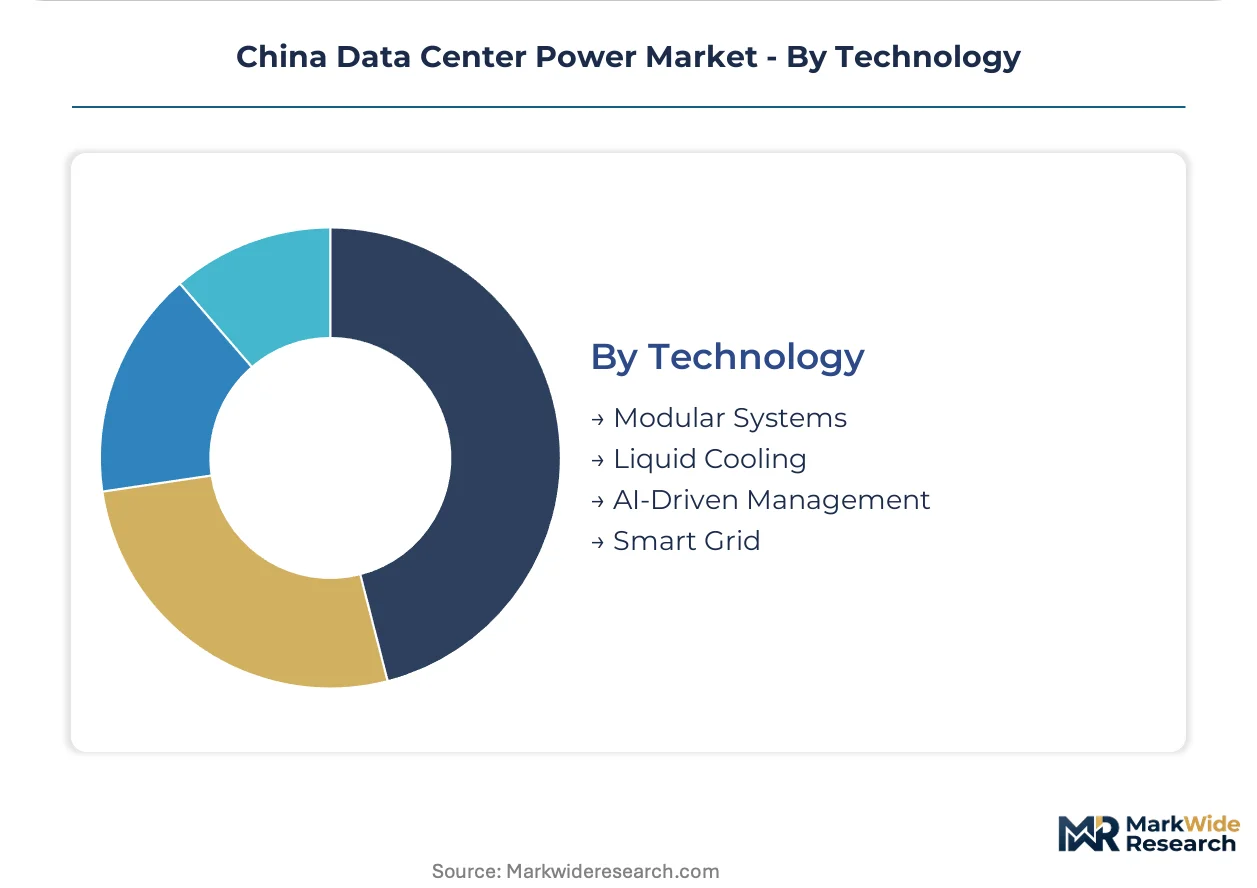
Technology:
Physical form factor and control intelligence are converging to compress footprint while elevating efficiency thresholds.
- Liquid Cooling:Two-phase immersion and direct-to-chip architectures enable 50kW-plus rack densities. AI training clusters in Jiangsu and Zhejiang are accelerating adoption ahead of MIIT permit deadlines.
- AI-Driven Management:Predictive load-balancing software optimizes power distribution across heterogeneous compute workloads. License-based recurring revenue models are displacing perpetual software sales.
- Modular Systems:Prefabricated power halls with integrated UPS, switchgear, and busway reduce field construction duration. Silicon carbide power modules miniaturize rack-level distribution units from 6U to 2U form factors.
- Smart Grid:Demand response interfaces with provincial utility dispatch centers for peak-shaving revenue. Storage-hybrid UPS integration creates margin pools in frequency regulation services.
Modular Systems retain the installed base advantage. Liquid Cooling is gaining share fastest as density requirements exceed air-cooled thermal limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in western renewable zones demonstrate highest price elasticity to grid-connection costs, while Beijing-Tianjin-Hebei operators absorb premium substation pricing to secure tier-one positioning.
Beijing-Tianjin-Hebei
Hyperscale cloud campuses and state-owned enterprise data halls drive concentrated substation demand across this northern corridor. MIIT enforces PUE ceilings below 1.3 for new facility permits, forcing legacy infrastructure redesign. Langfang and Zhangjiakou industrial clusters host expanding AI training campuses with dedicated 220kV grid connections.
Yangtze River Delta
Jiangsu and Zhejiang provinces absorb the dominant share of liquid-cooled power distribution procurement for 30kW-plus rack densities. Provincial carbon-intensity quotas under dual carbon goals redirect developers toward hydroelectric sourcing partnerships. Shanghai and Hangzhou metropolitan clusters concentrate colocation facility expansion with streamlined green data center municipal incentives.
Greater Bay Area
Shenzhen and Dongguan municipalities anchor wholesale colocation pipelines with streamlined permitting for green data center certifications. Southern Power Grid prioritization creates connection queue competition among cloud service providers. The Pearl River Delta cluster sustains multi-megawatt deployment pipelines despite constrained land availability.
Sichuan-Chongqing
Abundant hydroelectric capacity attracts hyperscale campus development seeking captive renewable sourcing. Provincial utilities expand dedicated substation capacity to serve westward migration of AI training workloads. Chengdu and Chongqing metropolitan zones concentrate storage-hybrid architecture deployments pairing photovoltaic arrays with lithium-ion systems.
Guizhou
Big data industry policy incentives position Guiyang and Anshun as alternative western hubs with favorable grid carbon intensity profiles. State Grid Corporation infrastructure investment lags coastal provinces, extending commissioning timelines for 220kV builds. The province clusters government and financial services data halls seeking compliance with national energy efficiency disclosure mandates.
China Data Center Power Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across China's data center power sector. Integrated electronics manufacturers control upstream component costs through captive supply chains, while European engineering groups extend high-efficiency architectures through joint-venture production. Three archetypes dominate: vertically integrated technology conglomerates, wholesale colocation specialists, and multinational infrastructure vendors. Competitive moves concentrate on silicon carbide module procurement partnerships and liquid cooling system integration alliances.
Within the integrated technology tier, Huawei Technologies exemplifies upstream cost control through in-house power-electronics manufacturing. GDS Holdings Ltd occupies a position as the wholesale colocation archetype, anchoring multi-megawatt deployment pipelines in tier-one cities with asset-light operational models. Schneider Electric SE represents the multinational infrastructure vendor pattern, extending European UPS architectures into Chinese production through joint-venture structures.
| Leading Market Players |
|---|
| Huawei Technologies |
| GDS Holdings Ltd |
| China Telecom |
| China Mobile |
| Alibaba Cloud |
| Tencent Cloud |
| Schneider Electric SE |
| Eaton Corporation |
| Vertiv Holdings Co |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide power module substitution for silicon IGBTs is redrawing procurement geography toward Inner Mongolia rare earth processing corridors while compressing inverter cost curves across Jiangsu and Zhejiang manufacturing zones. This material transition simultaneously elevates pricing leverage for integrated electronics manufacturers and exposes regional operators to concentrate supply volatility.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions now capture lifetime value exceeding initial equipment margins across Beijing-Tianjin-Hebei deployments. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with MIIT PUE compliance tiers acting as the primary differentiation driver. Cost compression in standard-grade UPS hardware is intensifying because of SiC module commoditization, while cloud service providers demonstrate lowest price sensitivity due to density-driven total cost of ownership calculations. Regional colocation operators absorb highest price elasticity as they compete for wholesale megawatt contracts with constrained capital structures.
Supply Chain Analysis
Container availability constraints through Shanghai and Shenzhen port complexes elevate inbound logistics costs for imported switchgear awaiting NMPA-adjacent GB standards certification. Manufacturing concentration centers on China, South Korea, and Germany for high-frequency power electronics, with rare earth magnet processing anchored in Inner Mongolia. Copper busway fabrication draws from Chilean concentrate and domestic smelting capacity, exposing distributors to commodity price swings. Single-source vulnerability runs through silicon carbide wafer supply from United States and Japanese substrate vendors. Distribution runs through State Grid Corporation procurement frameworks for grid-connected substations, while captive solar hybrid components flow via direct OEM relationships to western renewable zone developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's data center power sector functions as a defensive-moat market where MIIT regulatory entrenchment creates high barriers through binding PUE thresholds and equipment certification mandates that lock in incumbent relationships.
For Market Incumbents: Shield market position by deepening backward integration into silicon carbide module manufacturing and securing captive rare earth magnet supply from Inner Mongolia processing facilities. Cloud service provider self-build programs represent the primary substitution threat to wholesale colocation margins, requiring incumbents to anchor multi-year service contracts with uptime-guarantee pricing before hyperscale vertical integration accelerates. For New Entrants and Emerging Players: Managed services whitespace—where legacy OEMs under-serve predictive maintenance and AI-driven load optimization—offers the most penetrable entry vector. Target Sichuan and Guizhou storage-hybrid architecture deployments where provincial carbon quotas outpace established vendor coverage, and pursue consulting-led site selection advisory as the primary go-to-market angle to bypass equipment certification queues. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors asset-light service specialists with recurring revenue models over capital-intensive hardware manufacturers. Five-to-ten year viability hinges on software-defined power management licensing scale rather than equipment shipment volumes. Acquisition target archetype: regional managed services platforms with existing State Grid Corporation relationships. The signal to watch is MIIT permit approval velocity for liquid-cooled facilities exceeding 5,000 rack thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Module Manufacturing Scale-Up | Huawei Technologies and domestic semiconductor foundries compress inverter costs for 2025-2026 procurement windows. |
| Western Renewable Zone Joint Venture | Developers partner with Sichuan utilities to secure dedicated substation capacity for hydroelectric-sourced campuses. |
| AI-Driven Management Platform Launch | Infrastructure vendors license predictive load-balancing software to displace perpetual sales with recurring revenue. |
| Multi-Vendor Service Marketplace | Beijing-Tianjin-Hebei operators unbundle maintenance from OEM contracts to reduce single-source dependency. |
| GB Standards Certification Investment | International vendors accelerate NMPA-adjacent approval timelines to capture Jiangsu and Zhejiang retrofit demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center engineering directors, provincial utility planning officers, power electronics procurement leads, and MIIT regulatory compliance specialists. Secondary validation drew from MIIT energy efficiency filings, State Grid Corporation interconnection queue disclosures, hyperscaler capital expenditure reports, and GB standards certification databases. Bottom-up facility-level capacity tracking and top-down provincial energy consumption projections were triangulated to anchor segmentation outputs.
Across the projection horizon, the analytical framework modeled power source segmentation by grid connection type and renewable hybrid architecture, end user tiers by deployment scale and density requirements, service type by procurement bundling patterns, and technology adoption by cooling modality and control intelligence sophistication. CAGRs were derived from facility commissioning timelines, PUE compliance retrofit cycles, and AI training cluster expansion trajectories. Forecast inputs incorporated MIIT permit approval velocity, provincial carbon-intensity quota enforcement schedules, and silicon carbide module cost curves.
Material uncertainties — MIIT regulatory revision, rare earth export policy shifts, and State Grid Corporation prioritization algorithm changes — sit outside the modeled envelope. Forecasts reflect documented assumptions about PUE threshold stability and western renewable zone infrastructure investment continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
United States Data Center Server Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Norway Data Center Networking Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
Malaysia Data Center Market
Data Center Infrastructure
Netherlands Data Center Market