
 Los Angeles Data Center Market | 2026-2036
Los Angeles Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Los Angeles Data Center Market Insights
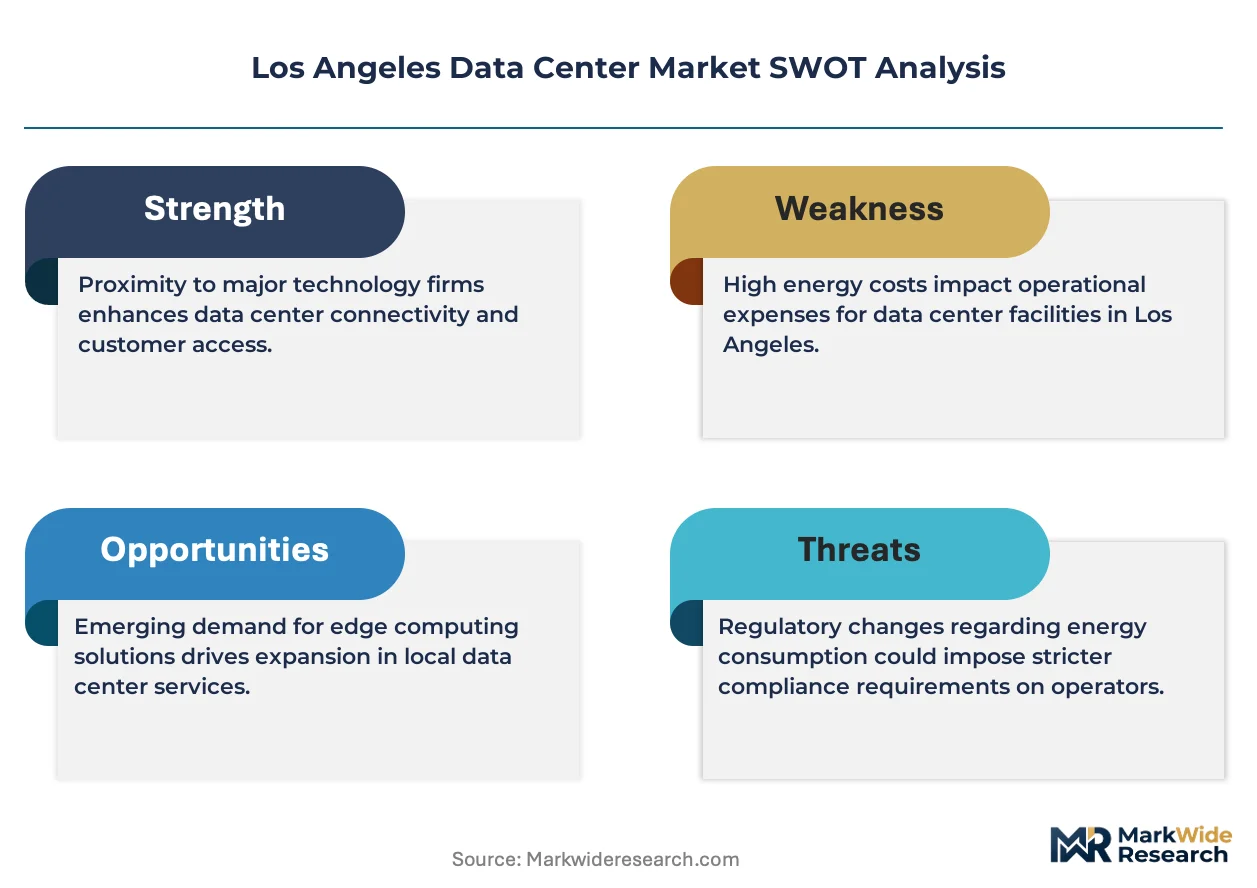
Buyer concentration among hyperscale cloud tenants is hardening across the Los Angeles basin. Digital Realty Trust leverages its downtown Los Angeles campus to anchor enterprise and media workloads. Equinix sustains cross-connect density at its One Wilshire and El Segundo facilities, competing for financial services latency arbitrage. CoreSite differentiates through its Santa Clara-adjacent peering ecosystem extended into the LA metro.
Los Angeles data centers constitute mission-critical facilities housing compute, storage, and network infrastructure within hardened physical shells with redundant power and precision environmental control, serving content delivery, financial transaction processing, and enterprise IT consolidation. Colocation and cloud services command the dominant revenue share as media and entertainment enterprises outsource capital-intensive infrastructure. Liquid-cooled deployments above 20 MW represent the fastest-expanding power rating segment, driven by GPU-intensive AI training clusters locating near California's film and visual effects studios.
California Energy Commission Title 24 standards and South Coast Air Quality Management District rules constrain diesel generator runtime and refrigerant selection, elevating capital costs for new ground-up construction. Los Angeles Department of Water and Power interconnection queues and CPUC demand response mandates shape site selection and backup power architecture decisions. Stakeholders must monitor water availability for evaporative cooling against persistent drought conditions and evolving reclaimed water regulations.
Market Dynamics
GPU-intensive AI training clusters are compressing site selection timelines across the Los Angeles basin, forcing developers to secure power commitments before finalizing cooling architectures. This acceleration favors operators with existing entitlements and substation access.
Growth Catalysts
- Title 24 Building Energy Codes:California's tightening power usage effectiveness requirements are pushing legacy facilities toward retrofit cycles, creating demand for modern colocation alternatives with compliant infrastructure.
- Visual Effects Rendering:Entertainment studios located from Burbank to Santa Monica are outsourcing render farms to local data centers to minimize latency for real-time collaboration with production teams.
- Financial Services Latency Arbitrage:Trading firms are establishing presence in El Segundo and downtown Los Angeles facilities to capture microsecond advantages on trans-Pacific fiber routes.
Market Restraints
- LADWP Interconnection Queues:Los Angeles Department of Water and Power substation upgrade timelines now extend 24-36 months for new loads above 10 MW, freezing greenfield development.
- Reclaimed Water Access:Persistent drought conditions and evolving municipal regulations restrict evaporative cooling water availability, forcing mechanical-only designs with higher capital intensity.
- SCAQMD Diesel Runtime Limits:South Coast Air Quality Management District emergency generator testing restrictions compress backup power architecture options and elevate compliance costs.
Strategic Opportunities
- Irvine Spectrum Expansion:Underserved enterprise demand in Orange County's technology corridor offers first-mover advantage for operators securing power outside the congested 405 core.
- Liquid Cooling Retrofit:Converting existing raised-floor facilities to direct-to-chip cooling captures AI training tenants without ground-up construction timelines.
- CPUC Demand Response Aggregation:Battery-backed facilities can monetize interruptible load programs, turning grid constraints into revenue streams.
Industry Challenges
- Electrical Trade Labor Scarcity:Specialized high-voltage technicians command premium wages and extended scheduling, stretching commissioning timelines for hyperscale deployments.
- Integrated System Commissioning:Coordinating mechanical, electrical, and fire suppression testing across multiple subcontractors creates handoff failures and certificate of occupancy delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Los Angeles Data Center Market |
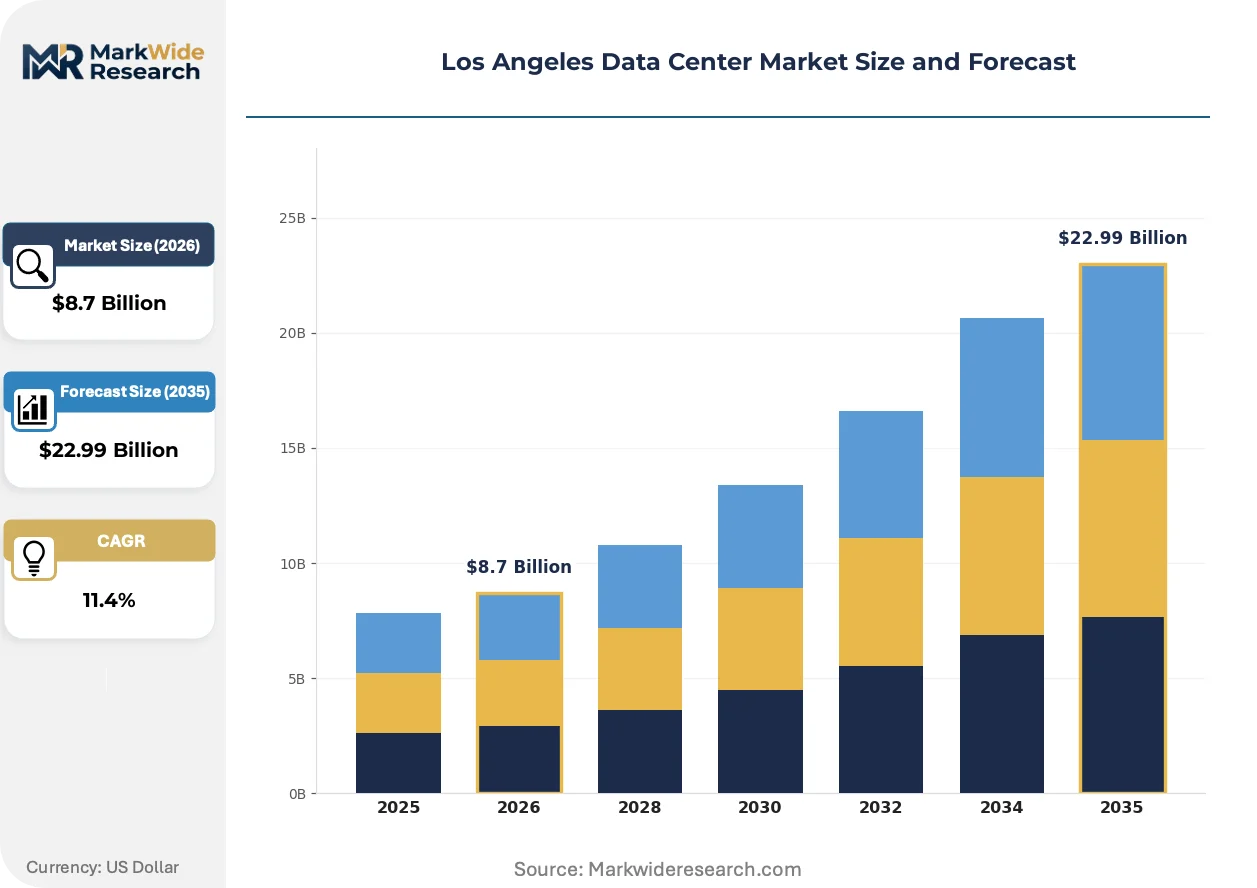
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Cloud Services, Managed Hosting, Disaster Recovery Power Rating: 1-5 MW, 5-10 MW, 10-20 MW, 20+ MW Cooling Technology: Air-Cooled, Liquid-Cooled, In-Row Cooling, Free Cooling Industry Vertical: Finance, Media, E-Commerce, Telecommunications |
| Companies Covered | Digital Realty Trust, Equinix, CoreSite, DataBank, Prime Data Centers, STACK Infrastructure, Cogent Communications, Aligned Data Centers, Vantage Data Centers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Los Angeles Data Center Market Trends and Innovations
Cooling architecture decisions now precede site selection in Los Angeles, reversing traditional development sequences. Operators are engineering for heat densities that exceed current tenant requirements to future-proof against AI workload evolution.
Direct liquid cooling is decentralizing thermal management responsibility from facility operators to server manufacturers. Dell and Super Micro are shipping rack-scale systems with integrated coolant distribution units, reducing dependence on centralized plant infrastructure. Media and entertainment tenants with render-intensive workloads are adopting these systems fastest, compressing facility design cycles from 18 months to 9 months.
California Energy Commission Title 24 standards now mandate hourly energy modeling for data center projects exceeding 500 kW, elevating mechanical engineering costs. Developers must demonstrate compliance through whole-building simulation rather than prescriptive checklists. New construction in the El Segundo corridor is responding with dedicated energy modeling teams embedded in project development.
Content delivery networks are unbundling storage from compute in their Los Angeles procurement, awarding separate contracts to specialized providers. Streaming platforms now source object storage from Sacramento-adjacent facilities while maintaining compute at 405-corridor nodes. This bifurcation is most pronounced among studios with substantial archival libraries and episodic release schedules.
Los Angeles Data Center Market Segmentation
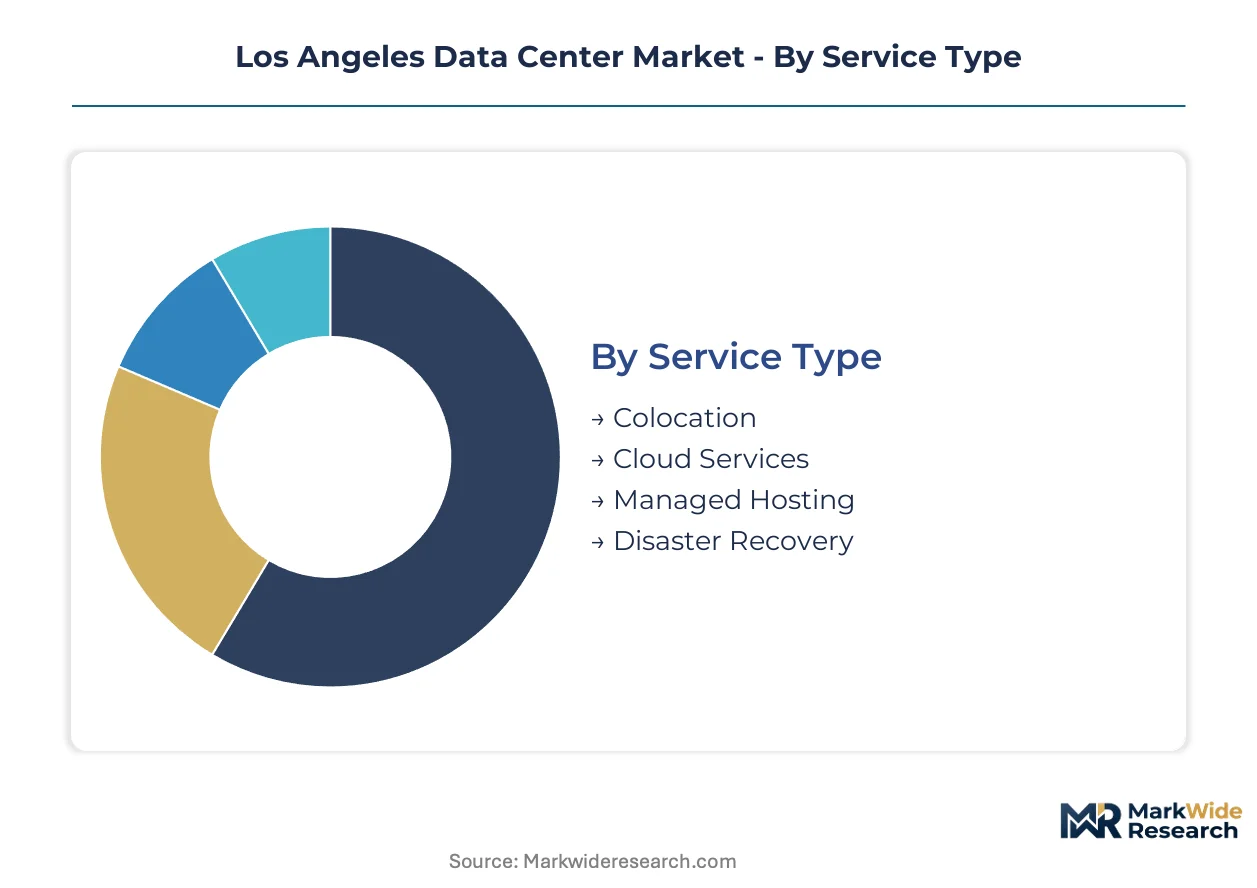
Los Angeles data center segmentation reveals distinct procurement patterns across service tiers and infrastructure scales. Media and entertainment tenants prioritize latency-sensitive colocation near production studios, while hyperscale cloud deployments drive power density requirements upward.
Service Type:
Standalone outsourcing contracts dominate enterprise procurement, with embedded hybrid architectures gaining traction among studios requiring burst capacity.
- Colocation:Physical space and power provisioning with tenant-supplied equipment. Demand concentrates in El Segundo and downtown Los Angeles facilities serving media enterprises with sub-10ms latency requirements to Burbank production campuses.
- Cloud Services:Virtualized compute and storage delivered via hyperscale platforms. Financial services firms along the 405 corridor are migrating core workloads here to access GPU instances without capital deployment.
- Managed Hosting:Operator-owned equipment with full operational management. E-commerce platforms favor this model for seasonal scaling without staffing data center operations teams.
- Disaster Recovery:Secondary site replication and failover orchestration. Healthcare and financial compliance mandates are expanding Sacramento-adjacent deployments for geographic separation from primary Los Angeles infrastructure.
Volume placements concentrate in Colocation; the faster expansion belongs to Cloud Services.
Power Rating:
Facility scale determines cooling architecture viability and substation access requirements, with cost tiers separating enterprise from hyperscale deployments.
- 20+ MW:Campus-scale deployments with dedicated substations and liquid-cooled infrastructure. AI training clusters from visual effects studios are compressing site selection timelines for this tier across the El Segundo-Irvine corridor.
- 10-20 MW:Hyperscale-ready facilities with N+1 redundancy and flexible white space configurations. Cloud providers are pre-leasing this capacity ahead of LADWP interconnection completion to secure 405-corridor positioning.
- 5-10 MW:Mid-market deployments serving regional enterprise consolidation. Title 24 compliance costs are pushing this tier toward retrofit of existing facilities rather than ground-up construction.
- 1-5 MW:Edge and enterprise satellite deployments. Retail and professional services tenants are expanding this segment fastest in Orange County's underserved Irvine Spectrum submarket.
Deployment volumes cluster in 10-20 MW facilities; 20+ MW installations are climbing the fastest as GPU density requirements escalate.
Cooling Technology:
Application-driven thermal architecture selection now precedes site commitment, reversing traditional development sequences for high-density workloads.
- Liquid-Cooled:Direct-to-chip and immersion systems for 50+ kW rack densities. Media rendering farms are adopting Dell and Super Micro integrated coolant distribution units to compress facility design cycles.
- Air-Cooled:Traditional raised-floor with perimeter CRAC units. Legacy enterprise tenants maintain this architecture for predictable 5-10 kW rack densities in existing downtown Los Angeles facilities.
- In-Row Cooling:Proximate cooling modules aligned with server rows. Financial services latency arbitrage deployments favor this for rapid commissioning without centralized plant construction.
- Free Cooling:Economizer-based systems leveraging ambient air temperature. Coastal El Segundo sites exploit marine layer conditions to reduce mechanical cooling hours and Title 24 compliance costs.
Installed base concentrates in Air-Cooled infrastructure; Liquid-Cooled deployments are gaining share fastest among AI training tenants.
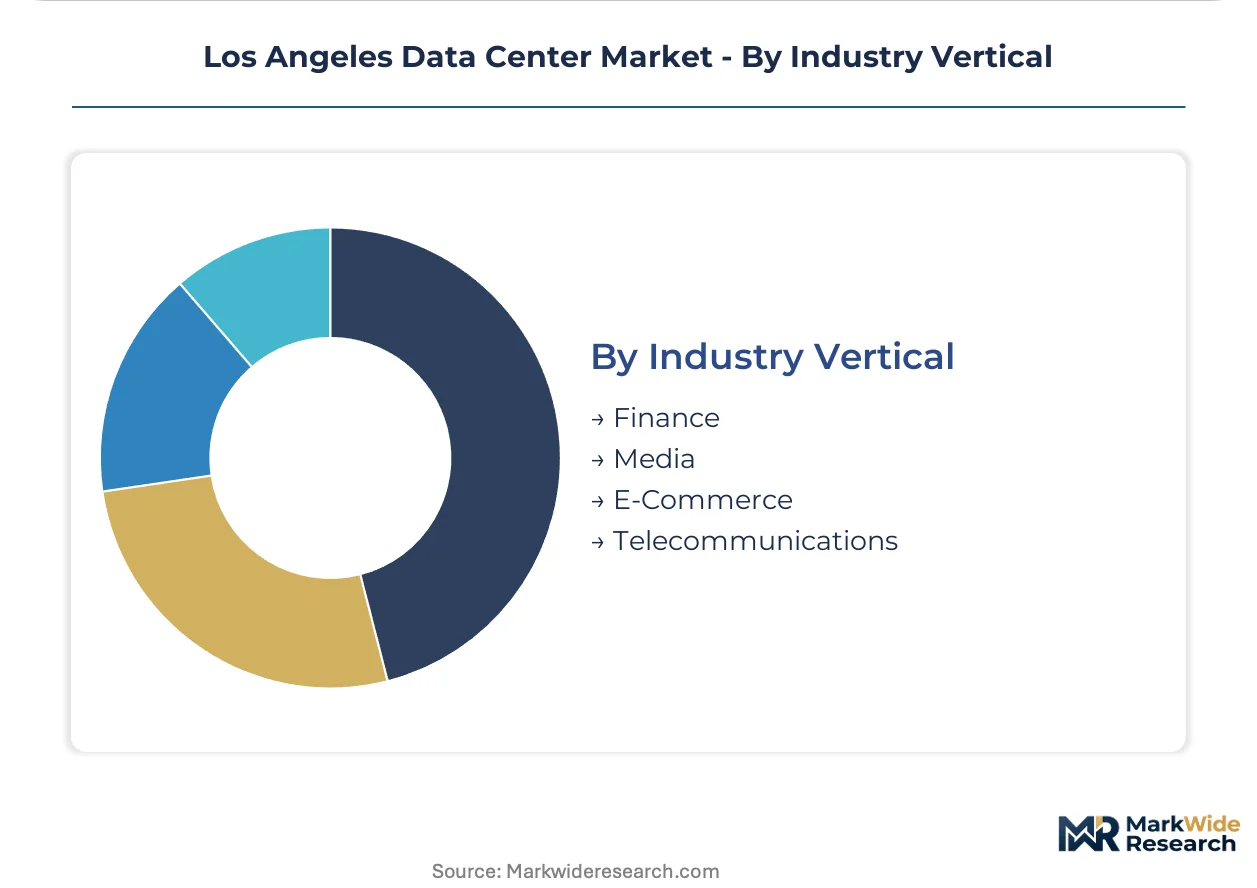
Industry Vertical:
Customer type determines redundancy tier, interconnect requirements, and geographic clustering within the Los Angeles basin.
- Media:Visual effects rendering, content delivery, and archival storage. Studios from Santa Monica to Burbank are outsourcing burst render capacity to minimize on-premise infrastructure capital.
- Finance:Low-latency trading infrastructure and compliance data retention. Trans-Pacific fiber proximity drives clustering in downtown Los Angeles and El Segundo for microsecond arbitrage advantages.
- E-Commerce:Transaction processing and customer data platforms. Peak season volatility is expanding demand for flexible colocation contracts with rapid scaling provisions.
- Telecommunications:Network aggregation points and edge computing nodes. 5G infrastructure densification is expanding this vertical's footprint across Orange County submarkets.
Revenue concentration sits with Media tenants; Finance verticals are expanding most quickly as trading firms establish Los Angeles presence for Pacific Rim market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Entertainment studios and hyperscale cloud tenants concentrate demand along Southern California's coastal corridor, with power interconnection constraints redistributing development toward peripheral sub-markets.
Downtown Los Angeles
Financial services firms and content delivery networks drive leasing in the central business district, where trans-Pacific fiber proximity enables latency arbitrage. Los Angeles Department of Water and Power interconnection queues now extend 36 months for new loads above 10 MW. One Wilshire and surrounding facilities anchor the densest cross-connect ecosystem in the western United States.
El Segundo
Visual effects studios from Santa Monica to Burbank outsource render capacity here to minimize latency for real-time production collaboration. California Energy Commission Title 24 standards mandate hourly energy modeling for projects exceeding 500 kW. Marine layer conditions support free cooling economizers that reduce mechanical cooling hours and compliance costs.
Irvine Spectrum
Underserved enterprise demand in Orange County's technology corridor attracts first-mover operators securing power outside the congested 405 core. South Coast Air Quality Management District diesel runtime limits compress backup power architecture options. DataBank and STACK Infrastructure have secured entitlements for campus-scale deployments in this sub-market.
Santa Clara-Adjacent Peering Ecosystem
CoreSite extends its northern California peering density into the Los Angeles metro through interconnection with Silicon Valley networks. CPUC demand response mandates shape site selection and backup power architecture decisions. This positioning captures cloud providers requiring seamless workload portability between northern and southern California nodes.
Los Angeles Data Center Market Competitive Landscape
Established operators occupy the standard tier; emerging entrants pursue liquid-cooled retrofit opportunities and Orange County greenfield development. The vendor base concentrates among real estate investment trusts with existing substation access and entitlement portfolios. Three archetypes dominate: hyperscale-anchored campus developers, interconnection-dense urban operators, and specialized AI-training infrastructure providers. Competitive intensity centers on pre-leasing capacity ahead of LADWP interconnection completion and securing reclaimed water access for evaporative cooling.
Among REIT-structured operators, Digital Realty Trust, Equinix, and CoreSite anchor distinct positioning vectors. Digital Realty Trust leverages its downtown Los Angeles campus for enterprise and media workload consolidation. Equinix sustains cross-connect density at One Wilshire and El Segundo facilities, competing for financial services latency requirements. CoreSite differentiates through Santa Clara-adjacent peering ecosystem extension into the metro, capturing cloud providers needing northern-southern California interconnectivity.
| Leading Market Players |
|---|
| Digital Realty Trust |
| Equinix |
| CoreSite |
| DataBank |
| Prime Data Centers |
| STACK Infrastructure |
| Cogent Communications |
| Aligned Data Centers |
| Vantage Data Centers |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud tenant concentration across the El Segundo-Irvine corridor enforces contract-based long-term offtake structures, locking in power commitments 24-36 months ahead of interconnection completion and compressing spot-market liquidity for residual capacity.
Pricing Analysis
Volume commitments dominate margin structures, with hyperscale pre-leasing of 10-20 MW blocks securing below-market rates while mid-market 5-10 MW tenants absorb Title 24 compliance premiums. Price differentiation rests on power density tier and LADWP interconnection queue position, with liquid-cooled 20+ MW deployments commanding scarcity premiums. Cost compression in air-cooled legacy facilities is intensifying because GPU-intensive AI tenants are displacing traditional enterprise workloads. Financial services latency arbitrage buyers exhibit lowest price sensitivity; retail and professional services satellite deployments in Orange County remain most price-elastic.
Supply Chain Analysis
UL 2743 certification for battery energy storage systems and EPA Tier 4 Final generator compliance gate equipment procurement timelines, stretching commissioning schedules for operators lacking pre-qualified vendor pools. Geographic supply concentration centers on China for switchgear and power distribution units, South Korea for lithium-ion battery cells, and domestic US sources for specialized electrical trade labor. Raw material dependencies include copper busbar, refrigerants constrained by SCAQMD rules, and reclaimed water for evaporative cooling. Single-source vulnerability permeates high-voltage technician availability. Distribution runs through EPC contractors with established LADWP relationships, subordinating equipment vendors to construction channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Los Angeles data center development operates as a supply-constrained market where LADWP interconnection queues extending 24-36 months prop pricing power for operators with existing substation access and entitlement portfolios.
For Market Incumbents: Anchor defensive positioning through accelerated pre-leasing of 10-20 MW capacity ahead of interconnection completion, securing tenant commitments before greenfield competitors achieve substation access. Invest in direct liquid cooling retrofit capabilities to capture AI training tenant demand without ground-up construction timelines. Vertical integration into electrical trade labor pools mitigates commissioning delays that threaten certificate of occupancy schedules. For New Entrants and Emerging Players: Orange County enterprise tenants represent the most penetrable buyer archetype, with underserved Irvine Spectrum demand offering first-mover advantage outside the congested 405 core. Liquid-cooled retrofit of existing raised-floor facilities captures GPU-intensive workloads without LADWP queue exposure. A go-to-market angle emphasizing CPUC demand response aggregation monetizes grid constraints into revenue streams unavailable to legacy operators. For Investors and Strategic Acquirers: The window for entry favors operators with secured power entitlements and substation access in the El Segundo-Irvine corridor, as these assets compound in scarcity value across the projection horizon. Acquisition targets should display existing LADWP interconnection agreements or approved CPUC demand response participation. The signal to watch is LADWP queue acceleration announcements, which would compress scarcity premiums and redistribute competitive advantage toward development execution speed rather than entitlement positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Substation Access Securement | Pre-approved LADWP interconnection agreements eliminate 24-36 month queue exposure for campus-scale deployments. |
| Liquid Cooling Retrofit Program | Direct-to-chip conversion captures AI training tenants without Title 24 ground-up construction timelines. |
| Demand Response Aggregation | CPUC interruptible load programs transform grid constraints into recurring revenue streams for battery-backed facilities. |
| Reclaimed Water Supply Contract | Municipal water access agreements secure evaporative cooling viability against persistent drought regulation. |
| Cross-Connect Density Expansion | One Wilshire and El Segundo fiber proximity sustains financial services latency arbitrage premiums. |
Research Methodology
Document review covered LADWP interconnection queue filings, CPUC demand response program data, and California Energy Commission Title 24 compliance records, complemented by interviews with data center development executives, electrical engineering contractors, hyperscale cloud procurement officers, and South Coast Air Quality Management District regulatory staff. Secondary validation drew from SEC REIT filings, municipal water authority reclaimed water allocation reports, and fiber route maps from trans-Pacific cable consortia. Bottom-up tenant demand modeling and top-down infrastructure capacity assessments were triangulated against operator-reported utilization metrics.
Historical leasing velocity was cross-referenced against panel input from colocation sales directors and cloud platform infrastructure planners to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include service type, power rating tier, cooling technology architecture, and industry vertical with latency sensitivity scoring. CAGRs were derived from power commitment timelines and tenant expansion patterns. Forecast inputs incorporated LADWP infrastructure investment schedules and SCAQMD regulatory amendment trajectories.
Revisions become necessary when LADWP interconnection queue timelines compress or expand materially, SCAQMD diesel runtime restrictions tighten beyond current rulemaking, or reclaimed water regulations shift access priorities. A model refresh is warranted upon material change in California Energy Commission building energy code adoption schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Data Center Rack Solutions Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
United Kingdom Data Center Physical Security Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
New Zealand Data Center Rack Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
UAE Data Center Server Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
Netherlands Data Center Power Market