
 China Data Center Market | 2026-2036
China Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
China Data Center Market Analysis
Modular prefabrication is hardening as the dominant procurement model for hyperscale buyers across China's data center landscape. GDS Holdings leverages its captive land-bank strategy to secure power allocation in tier-one municipalities ahead of competitors. Chindata Group specializes in hyper-density campus designs that anchor wholesale demand from cloud tenants. Huawei Cloud extends its integrated power-electronics stack to control total cost of ownership for self-built facilities.
A data center constitutes a dedicated facility housing computing infrastructure, storage systems, and network equipment with controlled environmental parameters including power usage effectiveness below 1.4 and tier III or IV redundancy standards, designed to process, store, and distribute digital information for enterprise and consumer applications. Colocation deployment leads in revenue contribution as enterprises outsource capital-intensive facility ownership while retaining operational control. Edge computing within the technology dimension represents the fastest structural expansion, driven by latency requirements for autonomous systems and industrial IoT in manufacturing zones. Managed services under service type commands the deepest margin pool through multi-year operational contracts with government and telecom operators.
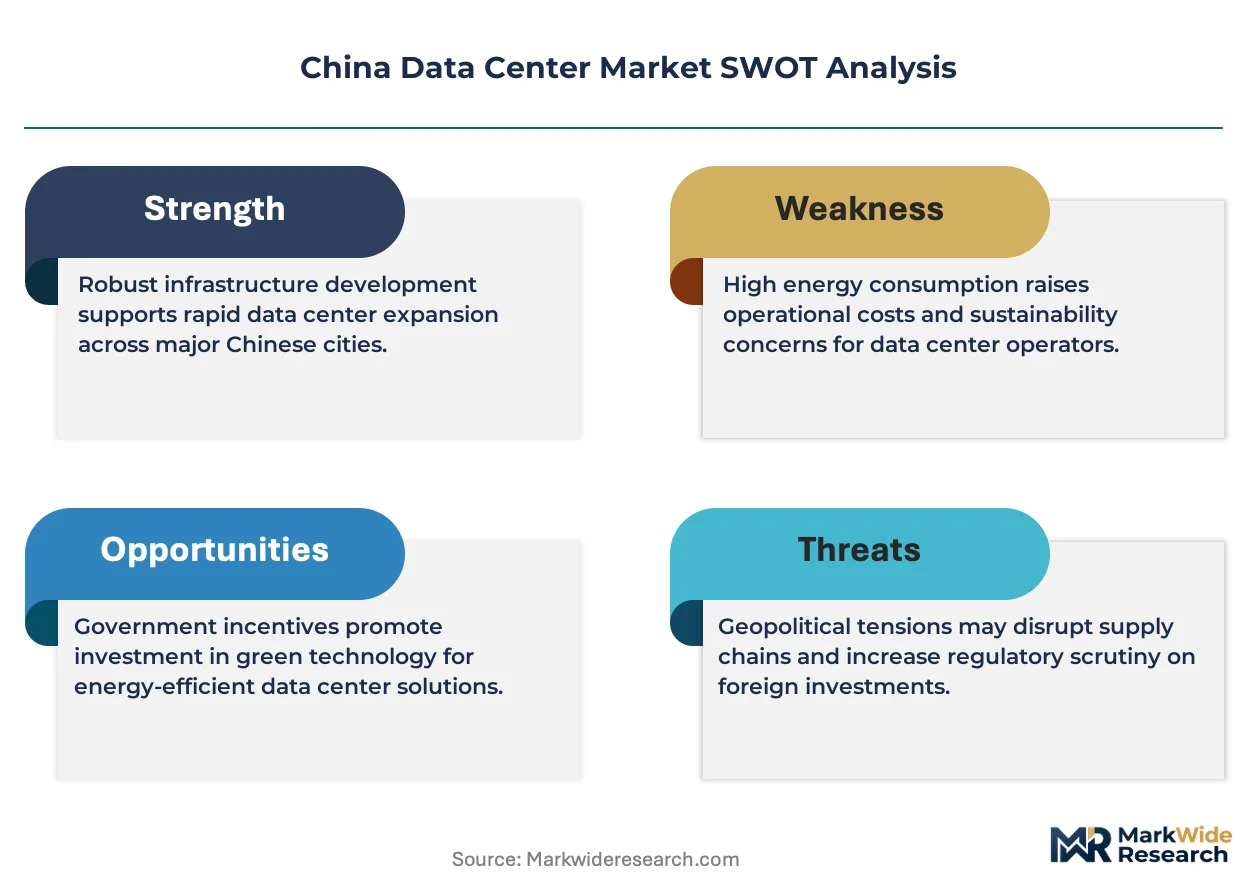
MIIT enforces national green data center standards that mandate power usage effectiveness thresholds and renewable energy sourcing ratios, directly shaping facility design and location decisions for new builds. GB standards from SAMR specify fire suppression, electromagnetic compatibility, and structural resilience requirements that filter market access for equipment suppliers and construction firms. Stakeholders must monitor how provincial carbon-intensity quotas interact with municipal land-use restrictions to determine viable expansion corridors.
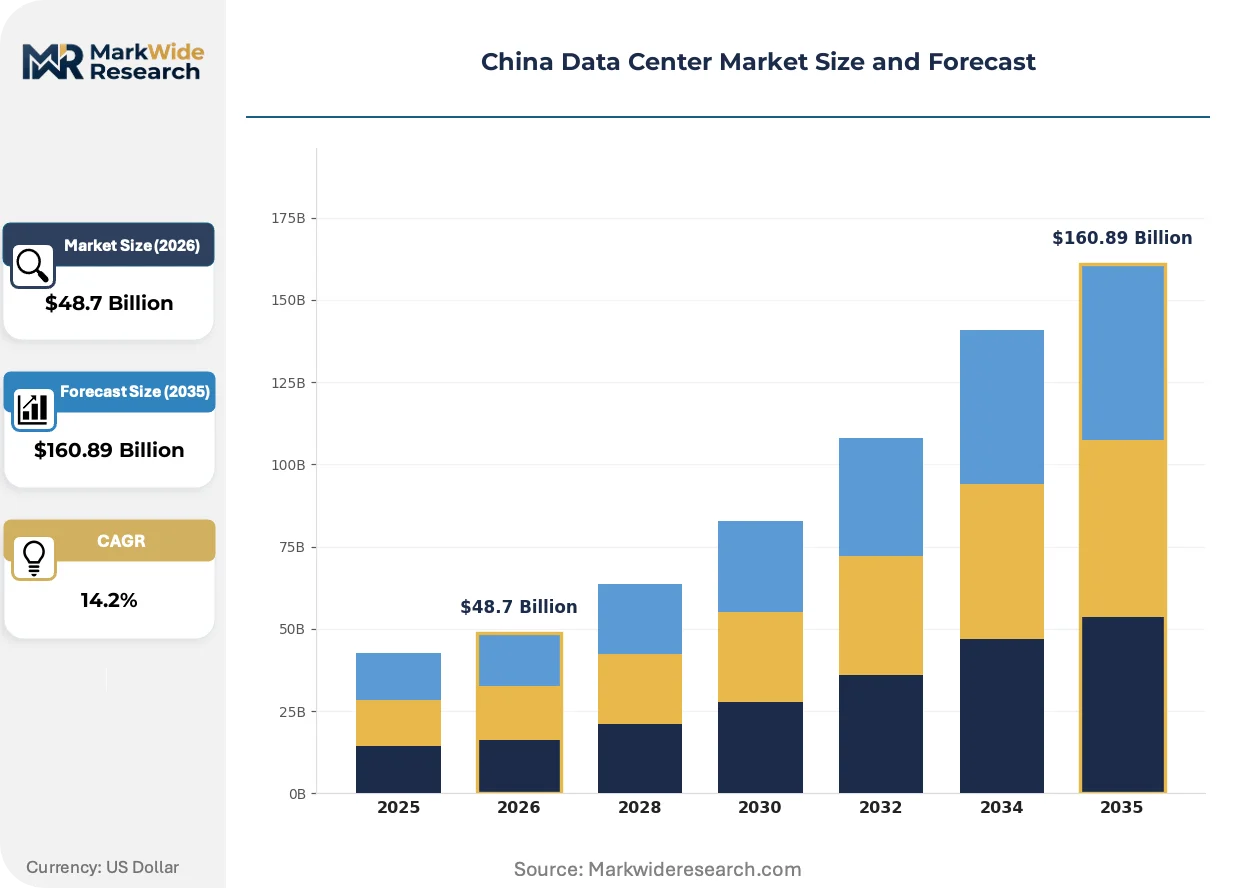
Market Dynamics
Modular prefabrication is compressing construction timelines for hyperscale facilities while MIIT's green data center standards force simultaneous efficiency upgrades, creating a dual-pressure environment where power allocation access determines competitive position.
Growth Catalysts
- Financial services cloud expansion:Banks and insurers are migrating core systems to hyperscale facilities, requiring tier III redundancy and sub-10ms latency to trading centers.
- MIIT efficiency mandates:Power usage effectiveness thresholds below 1.4 are accelerating liquid cooling adoption and renewable energy sourcing ratios in new builds.
- Beijing-Tianjin-Hebei corridor concentration:State-planned data center clusters in this corridor receive prioritized grid interconnection and land-use approvals.
Market Restraints
- Power allocation scarcity:Municipal governments in Shanghai and Shenzhen cap total data center power draw, forcing queue-based expansion timelines.
- Silicon supply concentration:Advanced AI chip procurement depends on concentrated overseas foundry capacity, creating input volatility for GPU-heavy facilities.
- GB fire suppression standards:SAMR-mandated gas-based systems add capex and maintenance complexity that slows brownfield retrofits.
Strategic Opportunities
- Western China renewable corridors:Inner Mongolia and Gansu offer stranded wind and solar resources with lower carbon-intensity quotas for facility operators.
- Edge-to-core convergence:Manufacturing IoT in Guangdong and Jiangsu is driving micro-data center deployment for sub-5ms autonomous system requirements.
- Dual carbon goal incentives:Provincial governments offer land-price discounts and tax holidays for facilities achieving 100% renewable power matching.
Industry Challenges
- Liquid cooling engineering shortage:Facility operators struggle to recruit thermal engineers capable of designing immersion systems for 50kW-plus rack densities.
- Legacy facility retrofit complexity:Air-cooled data centers built before 2020 face prohibitive costs to meet MIIT's revised PUE thresholds without full reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Data Center Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Colocation, Cloud, Hybrid Service Type: Managed Services, Infrastructure as a Service, Platform as a Service, Disaster Recovery Technology: Virtualization, Edge Computing, AI Integration, Renewable Energy Solutions End User: Telecommunications, IT Services, Government, Financial Institutions |
| Companies Covered | GDS Holdings, China Mobile, Alibaba Cloud, Baidu, Chindata Group, China Telecom, Huawei Cloud, VNET Group, Tencent, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Data Center Market Emerging Trajectories
Artificial intelligence training workloads are restructuring power and cooling specifications across facility design, while regulatory pressure on carbon intensity forces technology choices that prioritize efficiency over legacy reliability architectures.
Immersion cooling is rewriting thermal management economics for high-density AI clusters. Hyperscale operators in the Yangtze River Delta are piloting single-phase dielectric fluid systems for 100kW racks. This compression of cooling infrastructure footprint is enabling facility operators to reclaim 15-20% of white space for additional compute capacity.
MIIT's 2024 green data center assessment protocol tightens renewable energy sourcing requirements and mandates real-time carbon monitoring. Facility operators must now contract directly with provincial grid companies for guaranteed clean power percentages. Wholesale tenants in the Greater Bay Area are rewriting lease terms to include renewable energy certificates as standard contract riders.
Build-to-suit contracts are displacing speculative colocation for cloud service providers. Enterprise buyers in financial services now require dedicated power substations and customized security zones rather than shared white space. This preference for single-tenant facilities is most visible in Beijing's Tongzhou sub-center, where state-owned banks dominate pre-leasing activity.
China Data Center Market Segmentation
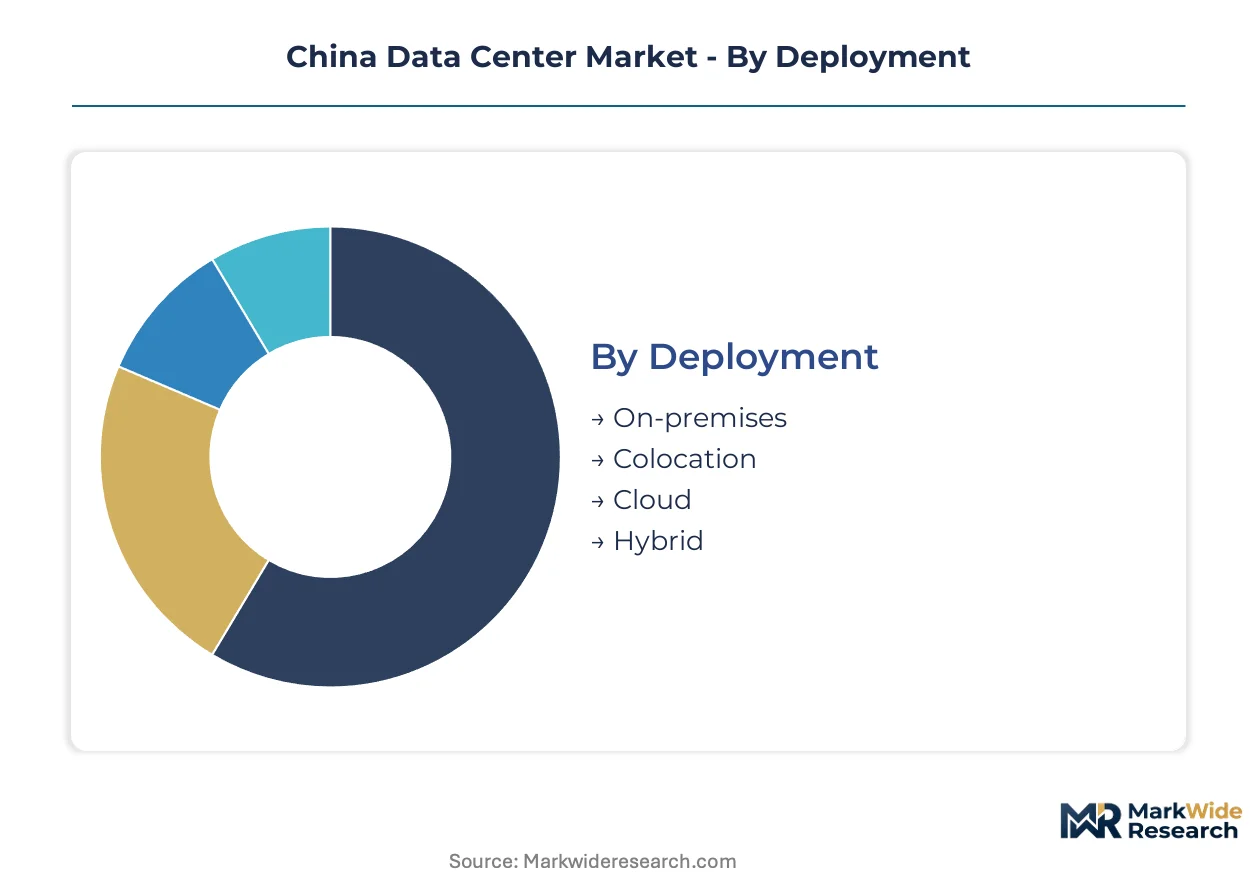
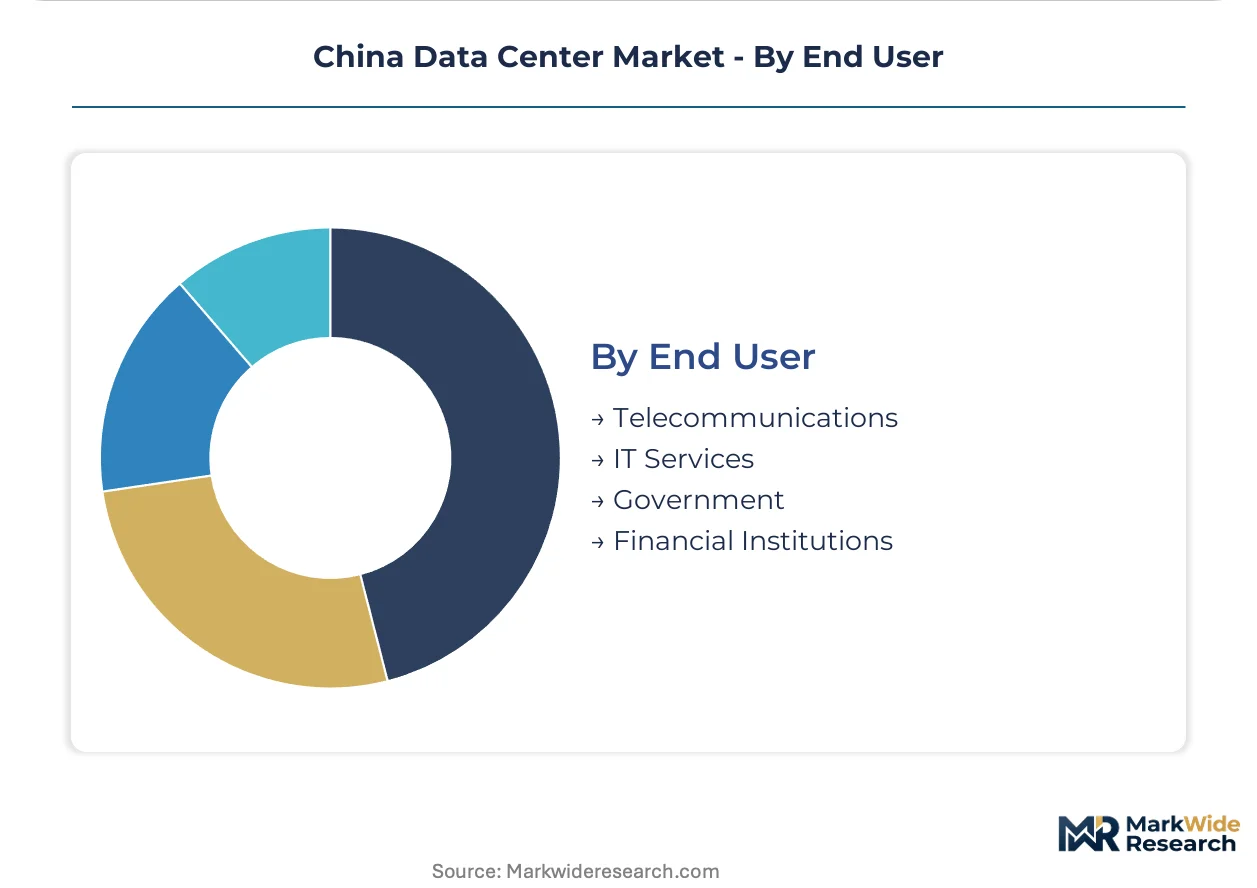
China's data center segmentation reflects divergent capital deployment strategies across ownership models, service layers, and infrastructure technologies. MIIT's efficiency mandates and provincial carbon quotas reshape which segments absorb incremental investment versus face retrofit pressure.
Deployment:
Standalone ownership structures dominate capital allocation in tier-one municipalities, while embedded multi-tenant arrangements expand in supply-constrained regions.
- Colocation:Third-party facilities provide power, cooling, and physical security while tenants retain server control. Financial institutions in Shanghai's Yangtze River Delta hub drive pre-leasing for tier III facilities with sub-10ms latency to trading centers.
- Cloud:Hyperscale providers operate dedicated campuses with captive substations and customized security zones. State-owned banks in Beijing's Tongzhou sub-center dominate build-to-suit contracting for single-tenant configurations.
- On-premises:Enterprise-owned facilities maintain full operational sovereignty over legacy core systems. Government and defense agencies mandate this model for classified data under national security protocols.
- Hybrid:Workload orchestration across private infrastructure and public cloud resources. Manufacturing enterprises in Guangdong deploy this architecture for burst capacity during production peaks.
Volume placements concentrate in Colocation; the faster expansion belongs to Cloud.
Service Type:
Margin depth varies sharply across operational responsibility boundaries, with full-stack management commanding premium pricing against commodity infrastructure rental.
- Managed Services:Comprehensive operational outsourcing spanning monitoring, maintenance, and optimization. Multi-year contracts with MIIT and provincial telecom operators lock in recurring revenue streams with 3-5 year tenors.
- Disaster Recovery:Secondary site replication and failover orchestration for business continuity. Financial institutions in the Greater Bay Area mandate synchronous replication with sub-15 minute recovery point objectives.
- Infrastructure as a Service:Virtualized compute and storage resources provisioned on demand. SME adoption accelerates in western China renewable corridors where power costs compress unit economics.
- Platform as a Service:Development environments and middleware stacks abstracting infrastructure management. AI training startups in the Yangtze River Delta cluster around GPU-optimized PaaS offerings.
Revenue concentration sits with Managed Services; Disaster Recovery claims the steepest expansion trajectory.
Technology:
Integration depth spans from software abstraction layers through physical infrastructure transformation, with thermal and power innovations reshaping facility economics.
- Edge Computing:Distributed micro-facilities processing data proximate to generation points. Autonomous systems and industrial IoT in Jiangsu manufacturing zones demand sub-5ms latency that only edge architectures deliver.
- Renewable Energy Solutions:Direct power purchase agreements and on-site generation for carbon intensity compliance. Inner Mongolia and Gansu facilities leverage stranded wind resources to meet MIIT's green data center assessment protocols.
- Virtualization:Software-defined resource abstraction maximizing hardware utilization. Legacy enterprise data centers deploy this layer to defer capital replacement while improving effective capacity.
- AI Integration:Automated workload placement, predictive maintenance, and thermal optimization. Hyperscale operators pilot single-phase immersion cooling for 100kW AI training racks in the Yangtze River Delta.
Deployment scale favors Virtualization; AI Integration is climbing the fastest.
End User:
Customer concentration and procurement sophistication determine contract structures, with regulated industries demanding bespoke compliance architectures.
- Financial Institutions:Banks, insurers, and securities firms with stringent latency and redundancy requirements. Core system migration to hyperscale facilities accelerates tier III construction in Beijing-Tianjin-Hebei corridor clusters.
- Government:Central and provincial agencies with data sovereignty and security mandates. MIIT's green standards and SAMR fire suppression requirements filter supplier access for state-funded projects.
- Telecommunications:Mobile and fixed-line operators with captive tower and fiber infrastructure. 5G network densification drives edge micro-data center deployment across tier-two and tier-three cities.
- IT Services:Systems integrators and managed service providers reselling capacity to downstream clients. This segment absorbs wholesale colocation space for multi-tenant redistribution.
Contract value aggregates in Financial Institutions; Government procurement is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's data center production concentrates in coastal tier-one municipalities while consumption spreads across interior provinces seeking lower power costs. This geographic split shapes investment flows and regulatory responses.
Beijing-Tianjin-Hebei Corridor
State-owned banks and securities firms drive hyperscale demand for tier III facilities with sub-10ms latency to trading centers. MIIT's green data center assessment protocol mandates real-time carbon monitoring and direct renewable power contracting. Tongzhou sub-center anchors pre-leasing activity where build-to-suit contracts displace speculative colocation.
Yangtze River Delta
AI training workloads from fintech and autonomous vehicle developers compress power density requirements upward. SAMR-enforced GB fire suppression standards filter equipment supplier access for new builds. Shanghai municipal caps on total data center power draw force queue-based expansion timelines despite intense demand.
Greater Bay Area
Wholesale tenants rewrite lease terms to include renewable energy certificates as standard contract riders under provincial dual carbon goal incentives. Manufacturing IoT in Guangdong drives micro-data center deployment for sub-5ms autonomous system requirements. Shenzhen's land-use restrictions prioritize facilities achieving 100% renewable power matching.
Western China Renewable Corridors
Inner Mongolia and Gansu offer stranded wind and solar resources with lower carbon-intensity quotas for facility operators. Provincial governments extend land-price discounts and tax holidays for clean power-matched construction. Hyperscale operators pilot single-phase immersion cooling for 100kW racks in these lower-cost environments.
Sichuan-Chongqing
Telecom operators densify edge infrastructure for 5G network expansion across tier-two and tier-three cities. MEE provincial carbon quotas interact with municipal land-use restrictions to determine viable expansion corridors. Chongqing's manufacturing base absorbs burst capacity through hybrid cloud architectures during production peaks.
China Data Center Market Vendor Landscape
The competitive structure tilts toward state-affiliated telecom operators and hyperscale cloud platforms with captive infrastructure arms. Tier-one municipalities concentrate capacity ownership among five to seven dominant players with prioritized grid interconnection access. Strategic archetypes include land-bank specialists securing power allocation ahead of competitors, hyper-density campus designers anchoring wholesale demand, and integrated power-electronics stack providers controlling total cost of ownership. Capacity expansion and build-to-suit contracting constitute the dominant competitive moves.
Among China-based operators, GDS Holdings, Chindata Group, and Huawei Cloud occupy distinct archetype positions within this concentrated structure. GDS Holdings exemplifies the land-bank specialist model through captive land acquisition in supply-constrained municipalities. Chindata Group represents hyper-density campus design for wholesale cloud tenant anchoring. Huawei Cloud sits within the integrated infrastructure provider tier, extending power-electronics control across self-built facility footprints. These three anchors illustrate how power allocation access and thermal engineering capability determine competitive position under MIIT's tightening efficiency mandates.
| Leading Market Players |
|---|
| GDS Holdings |
| China Mobile |
| Alibaba Cloud |
| Baidu |
| Chindata Group |
| China Telecom |
| Huawei Cloud |
| VNET Group |
| Tencent |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed telecom operators and private-equity-rolled-up hyperscale specialists anchor supply-side concentration in China's data center landscape, translating captive power allocation access into pricing discipline across tier-one municipalities. Their prioritized grid interconnection rights compress competitive bidding dynamics while MIIT's efficiency mandates force cost pass-through negotiations with wholesale tenants.
Pricing Analysis
Cost-down pressure on hyperscale rack rates accelerates because municipal power caps in Shanghai and Shenzhen constrain expansion timelines against surging cloud demand. Three-tier pricing structure across premium, standard, and economy levels separates build-to-suit single-tenant configurations from multi-tenant colocation and wholesale anchor deals. Price differentiation rests on PUE certification tier and renewable energy matching percentage under MIIT's green assessment protocol. Financial institutions show least price sensitivity given latency mandates to trading centers, while SME adopters of western China IaaS offerings drive hardest bargain on per-kW rates.
Supply Chain Analysis
GB fire suppression certification from SAMR gates equipment supplier access for new builds and brownfield retrofits alike. Server and switch hardware concentrates in China, Taiwan, and South Korea; diesel generators and precision cooling systems draw from European and Japanese manufacturers. Supply chain risk centers on single-source vulnerability for advanced AI accelerators tethered to concentrated overseas foundry capacity. Distribution runs through direct procurement by hyperscale operators and systems integrators serving enterprise colocation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power allocation scarcity across Beijing, Shanghai, and Shenzhen props facility pricing despite aggressive expansion targets from cloud service providers. This supply-constrained structure rewards early movers with captive land-bank positions and prioritized grid access.
For Market Incumbents: Cement land-bank reserves in tier-one municipalities ahead of municipal power draw caps tightening further. Defend tenant relationships through build-to-suit contracting for financial services clients demanding dedicated substations and customized security zones. Prioritize liquid cooling engineering recruitment to meet MIIT's revised PUE thresholds without full facility reconstruction.
For New Entrants and Emerging Players: The price-point gap between premium Yangtze River Delta hyperscale facilities and economy-tier western China renewable corridors offers entry leverage. Target Inner Mongolia and Gansu for stranded wind and solar resources with provincial land-price discounts and tax holidays. Lead with immersion-cooled designs for AI training workloads that incumbent air-cooled facilities cannot retrofit economically.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hyper-density campus specialists with wholesale cloud tenant anchoring in supply-constrained eastern hubs. Long-term viability hinges on power allocation access and thermal engineering capability across the analysis window. Watch for MIIT carbon-intensity quota tightening as inflection signal forcing legacy facility obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Direct renewable contracting with provincial grid companies secures MIIT green data center certification. |
| Liquid Cooling Infrastructure Deployment | Immersion systems for 100kW AI racks reclaim white space while meeting PUE thresholds below 1.4. |
| Edge Micro-Facility Rollout | Sub-5ms latency coverage in Jiangsu and Guangdong manufacturing zones captures autonomous system demand. |
| Build-to-Suit Contracting Expansion | Single-tenant configurations for state-owned banks in Tongzhou sub-center displace speculative colocation. |
| Western China Campus Development | Inner Mongolia and Gansu facilities leverage stranded renewables for carbon-intensity quota compliance. |
Methodological Framework
Multi-period observation of MIIT green data center certifications, municipal power allocation queues, and hyperscale capex disclosures anchored the trend analysis, supplemented by interviews with facility operators, thermal engineering contractors, provincial telecom procurement leads, and cloud platform infrastructure heads. Secondary validation drew from MIIT policy circulars, SAMR GB standard publications, provincial grid company power purchase agreement registries, and listed operator financial disclosures. Bottom-up tenant demand modeling and top-down capacity installation tracking were triangulated against regulatory filing timelines.
The input-output matrix framed deployment type, service tier, technology integration depth, and end-user vertical as segmentation dimensions across the modeling period. CAGRs were derived from installed base evolution and revenue-per-kW trajectory analysis. Forecast inputs incorporated AI training workload density requirements, liquid cooling adoption curves, and provincial dual carbon incentive program participation rates.
Inputs from provincial grid companies and hyperscale operator procurement teams were available through the study window; gaps in real-time carbon monitoring system deployment data introduce uncertainty bands around MIIT compliance timeline assumptions. Forecasts reflect documented assumptions on power allocation queue progression and renewable energy certificate market liquidity. A model refresh is warranted upon material change in MIIT PUE threshold enforcement or municipal land-use restriction relaxation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
Asia-Pacific Virtual Desktop Infrastructure Market
Data Center Infrastructure
Switzerland Data Center Construction Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Canada Data Center Power Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
France Data Center Server Market