
 Global Scalable Software Defined Networking Market | 2026-2036
Global Scalable Software Defined Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scalable Software Defined Networking Market Foresight
The EU AI Act is expanding the compliance burden for enterprises processing sensitive data across distributed networks, forcing infrastructure investments in programmable architectures that can enforce granular policy controls. Cisco Systems Inc. leverages its installed base of enterprise routing equipment to embed SDN controllers directly into existing customer footprints. Huawei Technologies Co. Ltd. anchors its position through integrated silicon-to-software stacks that reduce dependency on third-party chip vendors. Arista Networks Inc. specializes in high-throughput data center fabrics that appeal to cloud operators requiring sub-microsecond latency guarantees.
Scalable Software Defined Networking refers to network architectures that decouple control plane intelligence from data plane forwarding hardware, enabling centralized orchestration of traffic flows across heterogeneous infrastructure through open protocols such as OpenFlow or REST APIs. These systems typically support programmable forwarding tables exceeding one million entries and sub-50-millisecond failover intervals, serving primarily to automate provisioning, optimize bandwidth utilization, and enforce security policies across multi-vendor environments. Cloud-based deployment leads in absolute spending as enterprises migrate network management away from capital-intensive on-premises controllers, while edge deployment represents the fastest-expanding configuration due to latency requirements from industrial IoT and autonomous systems. Network automation commands the largest solution-type margin pool because recurring software subscriptions generate predictable revenue streams distinct from one-time hardware sales.
The Federal Communications Commission in the United States, the European Telecommunications Standards Institute, and China's Ministry of Industry and Information Technology each shape market access through spectrum allocation, interoperability mandates, and cybersecurity certification requirements that vendors must satisfy before commercial deployment. The EU Cybersecurity Act and NIS2 Directive impose baseline security standards on critical network infrastructure operators, directly stimulating procurement of SDN platforms with built-in encryption and segmentation capabilities. Stakeholders must monitor how divergent national approaches to data sovereignty and supply chain provenance rules fragment certification requirements and reshape vendor competitive positioning.
Market Dynamics
The decoupling of control plane intelligence from data plane hardware is restructuring procurement priorities, as federal zero-trust mandates in the United States and GDPR enforcement in Europe force enterprises toward programmable architectures with embedded policy enforcement.
Growth Catalysts
- EU AI Act compliance:Enterprises processing sensitive data across distributed networks must deploy granular policy controls, directly accelerating SDN controller procurement for automated governance enforcement.
- Hyperscale data center construction:Cloud service providers in the United States are expanding distributed infrastructure, requiring centralized orchestration platforms that manage heterogeneous equipment at scale.
- Industrial IoT latency requirements:Edge deployment configurations are expanding fastest as autonomous systems and manufacturing automation demand sub-50-millisecond failover intervals.
Market Restraints
- Silicon supply concentration:Dependency on third-party chip vendors for programmable forwarding tables creates vulnerability, with integrated silicon-to-software stacks remaining limited to select suppliers.
- Certification fragmentation:Divergent national approaches to data sovereignty and supply chain provenance rules in the United States, European Union, and China multiply compliance costs for vendors.
- Legacy protocol entrenchment:Existing network infrastructure running proprietary management interfaces resists migration to open protocols such as OpenFlow, extending replacement cycles.
Strategic Opportunities
- Network automation subscriptions:Recurring software revenue models distinct from one-time hardware sales offer margin expansion as enterprises migrate from capital-intensive on-premises controllers.
- India digital infrastructure:TRAI spectrum allocation and national broadband initiatives are creating demand for scalable orchestration in underpenetrated telecommunications markets.
- Convergence with zero-trust security:Integration of SDN controllers with encryption and microsegmentation capabilities addresses NIS2 Directive requirements for critical infrastructure operators.
Industry Challenges
- Control plane engineering talent scarcity:Shortage of specialists capable of programming forwarding tables exceeding one million entries and optimizing sub-microsecond latency constrains deployment velocity.
- Multi-vendor integration complexity:Heterogeneous environments combining equipment from different suppliers require custom API development, extending implementation timelines.
- Federal certification timelines:FCC cybersecurity certification requirements for commercial deployment create bottlenecks that delay revenue recognition for new platform releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scalable Software Defined Networking Market |
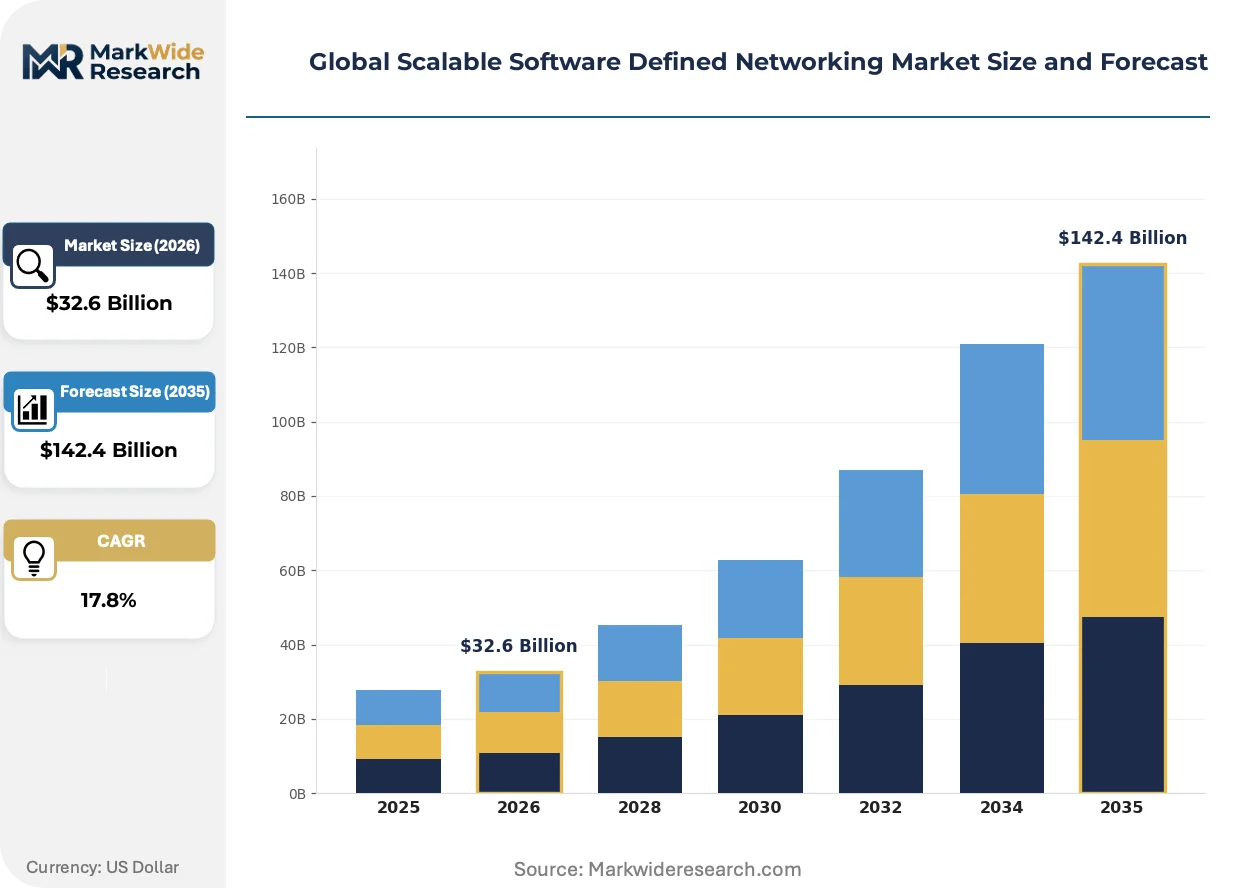
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $142.4 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Solution Type: Network Virtualization, Traffic Engineering, Security Management, Network Automation, Analytics Use Case: Data Center Interconnect, WAN Optimization, Campus Network Management, IoT Connectivity End User Industry: Telecommunications, Banking & Finance, Government Agencies, Educational Institutions |
| Companies Covered | Hewlett Packard Enterprise Co., Huawei Technologies Co. Ltd., Cisco Systems Inc., Dell Technologies Inc., Nokia Corp., VMware Inc., Arista Networks Inc., Ciena Corp., Juniper Networks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scalable Software Defined Networking Market Shifts & Advancements
Intent-based networking systems are replacing manual CLI configuration, compressing provisioning cycles from weeks to minutes while embedding compliance verification directly into change workflows.
Artificial intelligence-driven traffic engineering is automating bandwidth allocation across multi-tenant data center fabrics. Cloud operators requiring guaranteed throughput for latency-sensitive workloads are deploying these systems fastest. The technology is automating capacity planning decisions previously requiring dedicated network operations teams.
The EU Cybersecurity Act baseline standards are mandating encryption capabilities for critical network infrastructure procurement. European telecommunications operators must now specify built-in segmentation in RFPs. Equipment vendors are responding by embedding hardware security modules directly into controller architectures.
Consumption-based licensing models are displacing perpetual software purchases across enterprise accounts. Systems integrators and managed service providers are capturing this shift through subscription resale arrangements. This pattern is most visible in United States federal contracting, where GSA schedule holders now lead SDN procurement.
Global Scalable Software Defined Networking Market Segmentation
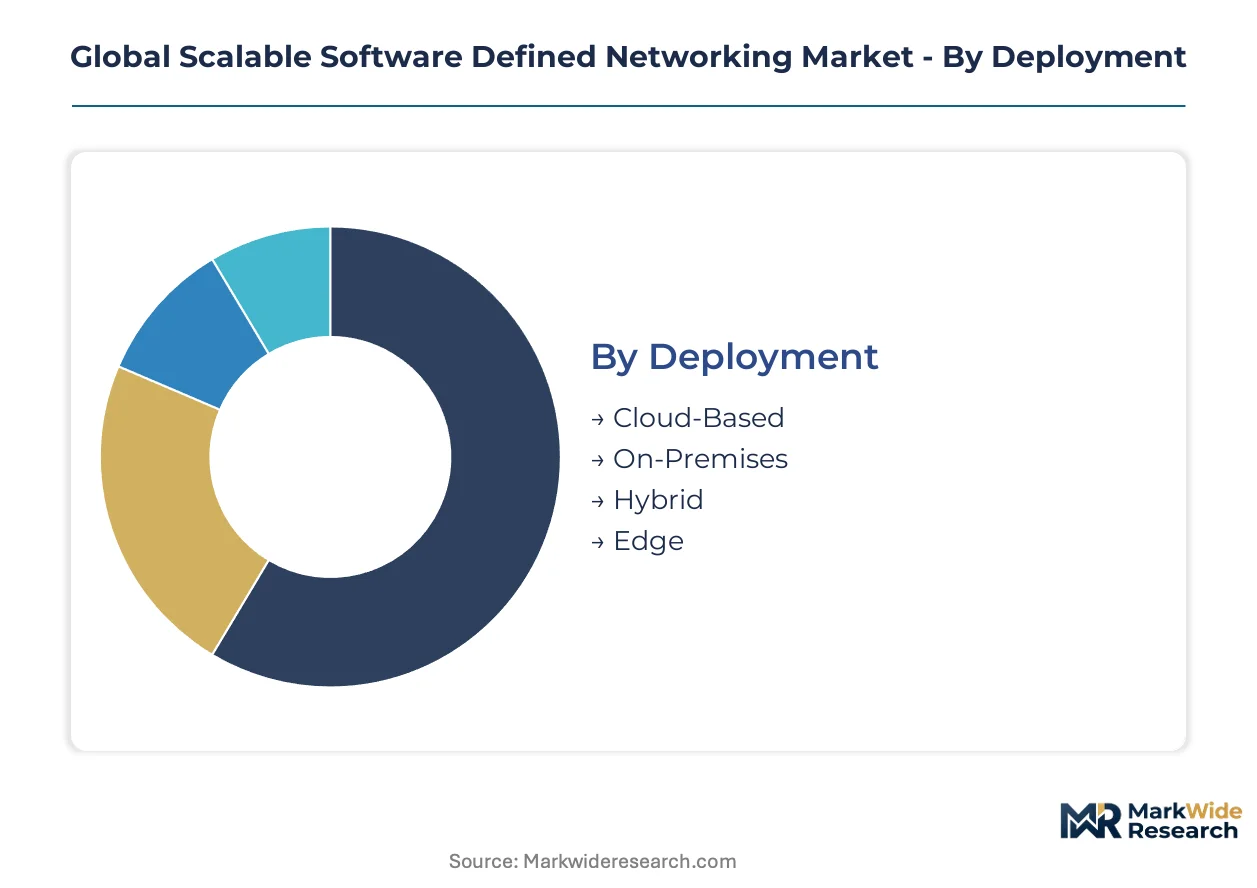
SDN procurement patterns diverge sharply across deployment models and solution architectures, with upgrade cycles varying from 18-month cloud refresh intervals to decade-long on-premises infrastructure holds. Understanding these segment boundaries enables vendors to calibrate pricing, support, and channel strategies to specific replacement rhythms and capability requirements.
Deployment:
Replacement cycles range from perpetual-license on-premises hardware to consumption-metered cloud instances, creating distinct margin profiles and customer lock-in mechanisms across each configuration.
- Cloud-Based:Multi-tenant controller platforms deliver centralized orchestration through subscription licensing, eliminating capital expenditure for hardware controllers. Hyperscale operators in the United States dominate procurement, driven by federal zero-trust mandates requiring programmable policy enforcement across distributed infrastructure. Volume placements concentrate in Cloud-Based; the faster expansion belongs to Edge.
- Edge:Distributed controller nodes deploy within 50 kilometers of data sources to guarantee sub-50-millisecond failover for autonomous systems and industrial automation. Manufacturing clusters in Germany and automotive testing facilities in Japan are expanding deployments fastest due to EU AI Act compliance requirements for localized data governance.
- On-Premises:Dedicated controller appliances remain entrenched in banking and defense sectors with air-gapped security requirements.
- Hybrid:Split-control architectures allow policy orchestration across cloud and on-premises domains for enterprises navigating phased migration timelines.
Procurement volumes favor Cloud-Based configurations; Edge deployments are climbing the fastest as latency-sensitive workloads proliferate.
Solution Type:
Margin structures vary from one-time hardware sales to recurring software subscriptions, with automation platforms capturing the most predictable revenue streams.
- Network Automation:Intent-based systems compress provisioning cycles from weeks to minutes through API-driven configuration management. Cloud service providers and managed service providers in the United States are the primary adopters, seeking to reduce operational headcount while embedding compliance verification into change workflows. Revenue concentration sits with Network Automation; Analytics is gaining share fastest.
- Security Management:Microsegmentation and encryption capabilities integrate directly with SDN controllers to satisfy NIS2 Directive requirements for European critical infrastructure operators. Telecommunications providers in France and Germany are mandating these features in procurement specifications following EU Cybersecurity Act baseline standards.
- Network Virtualization:Overlay networks abstract physical infrastructure to enable multi-tenant data center fabrics.
- Traffic Engineering:AI-driven bandwidth allocation optimizes throughput for latency-sensitive workloads across shared infrastructure.
- Analytics:Telemetry platforms providing real-time visibility into flow patterns and anomaly detection.
Subscription revenue concentrates in Network Automation; Analytics is expanding most quickly as observability requirements intensify.
Use Case:
Application-specific requirements dictate controller scalability thresholds, with data center interconnect demanding million-entry forwarding tables while campus deployments prioritize policy granularity over raw throughput.
- Data Center Interconnect:High-throughput fabrics connecting geographically distributed facilities require sub-microsecond latency guarantees and programmable forwarding tables exceeding one million entries. Cloud operators in the United States and content delivery networks in the Netherlands are the primary deployers, driven by hyperscale construction and GDPR-mandated data residency controls. Deployment scale centers on Data Center Interconnect; IoT Connectivity is expanding fastest.
- WAN Optimization:Software-defined WAN controllers aggregate multiple transport links and apply application-aware routing policies across branch networks. Financial services firms in Singapore and retail chains in the United Kingdom are consolidating MPLS contracts into broadband-based alternatives with centralized policy management.
- Campus Network Management:Unified access layer control for enterprise wireless and wired infrastructure across distributed office locations.
- IoT Connectivity:Lightweight controller instances managing massive device populations with intermittent connectivity patterns.
Controller shipments concentrate in Data Center Interconnect; IoT Connectivity shows the steepest expansion trajectory as industrial sensor networks proliferate.
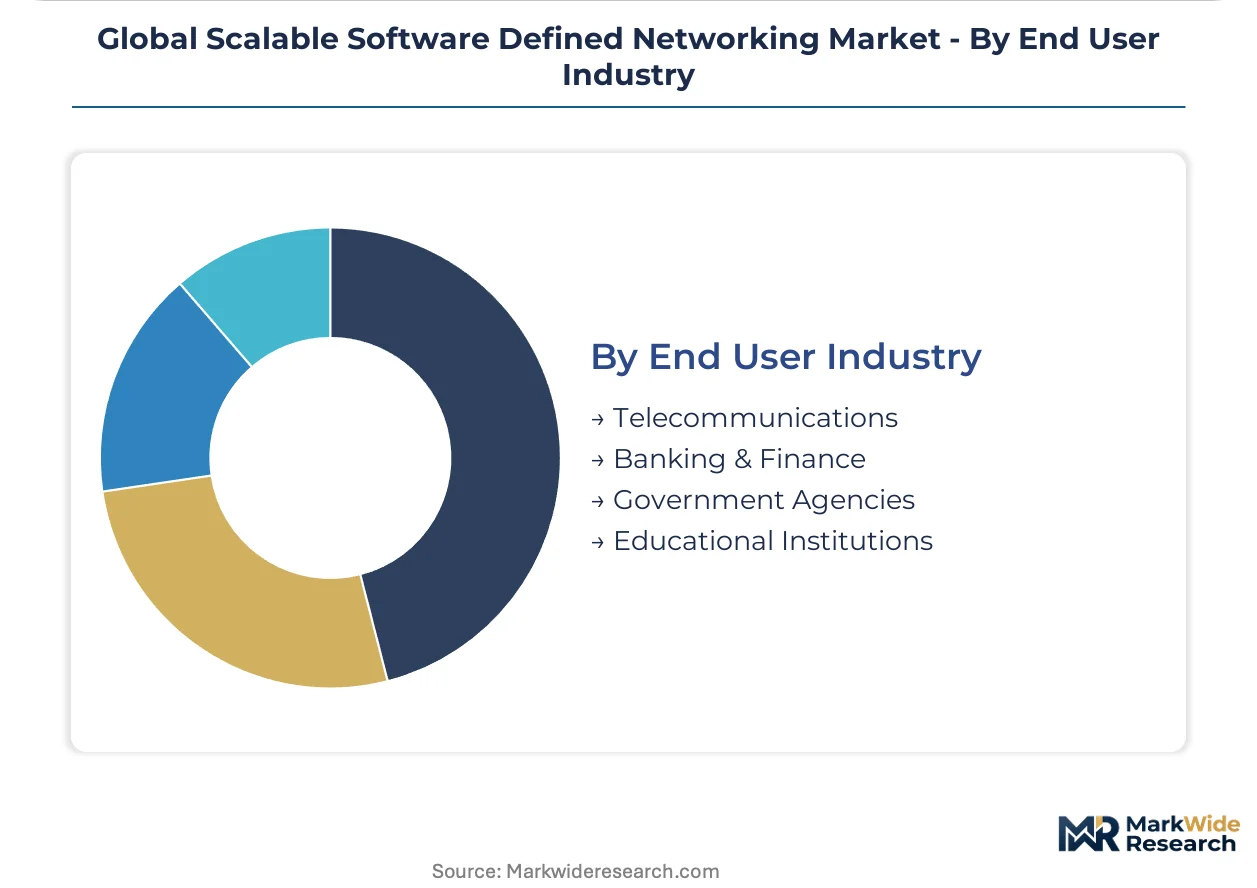
End User Industry:
Procurement authority and budget cycles vary dramatically, with telecommunications carriers negotiating multi-year framework agreements while educational institutions rely on grant-funded episodic purchases.
- Telecommunications:National carriers require carrier-grade controller platforms with five-nines availability and seamless integration with existing OSS/BSS systems. TRAI spectrum allocation in India and national broadband initiatives are stimulating demand for scalable orchestration in underpenetrated markets. Contract value concentrates in Telecommunications; Government Agencies are expanding procurement fastest.
- Banking & Finance:Real-time payment networks and trading infrastructure demand deterministic latency with hardware security module integration for cryptographic operations. Swiss banks and Singaporean financial exchanges are specifying these capabilities in RFPs following tightening operational risk regulations.
- Government Agencies:Federal zero-trust mandates in the United States and NIS2 Directive compliance in Europe are accelerating procurement of encryption-capable controllers with embedded segmentation.
- Educational Institutions:Research universities deploy programmable testbeds for network science experimentation and multi-tenant campus infrastructure.
Annual contract value concentrates in Telecommunications; Government Agencies are gaining share fastest as cybersecurity mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bangalore concentrate controller manufacturing capacity alongside hyperscale data center clusters. Tax incentives for semiconductor packaging in Penang and Dublin are pulling supply chain investment away from traditional hubs.
United States
Federal zero-trust mandates and hyperscale construction in Ashburn, Virginia, and Prineville, Oregon, drive procurement volume. The FCC cybersecurity certification requirements create deployment bottlenecks for new platform releases. Silicon Valley controller engineering teams are expanding to meet sub-microsecond latency specifications for cloud operators.
Germany
Industrial IoT automation in Stuttgart and Munich manufacturing corridors demands edge-deployed controllers with localized data governance. The EU Cybersecurity Act and NIS2 Directive mandate encryption capabilities in telecommunications RFPs. Frankfurt data center interconnect fabrics are expanding to satisfy GDPR-mandated data residency controls.
China
National broadband initiatives and MIIT spectrum allocation stimulate carrier-grade orchestration demand. The Ministry of Industry and Information Technology imposes cybersecurity certification requirements that reshape vendor competitive positioning. Shenzhen integrated silicon-to-software stacks reduce dependency on foreign chip suppliers for programmable forwarding tables.
India
TRAI spectrum allocation and national broadband initiatives create demand for scalable orchestration in underpenetrated telecommunications markets. The country's national digital infrastructure programs prioritize domestic controller deployment. Bangalore and Hyderabad cloud corridors are attracting hyperscale investment requiring centralized traffic management platforms.
Japan
Automotive testing facilities in Toyota City and Yokohama require sub-50-millisecond failover for autonomous systems validation. METI industrial policy supports programmable network architectures for manufacturing automation. Tokyo financial exchanges specify deterministic latency with hardware security module integration for trading infrastructure.
Global Scalable Software Defined Networking Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the controller architecture landscape. The vendor base spans integrated silicon-to-software stack providers, enterprise routing incumbents, and cloud-native fabric specialists. Three archetypes dominate: diversified technology conglomerates with installed base leverage, networking pure-plays with data center specialization, and telecommunications equipment vendors with carrier-grade reliability credentials. Competitive moves concentrate on strategic partnerships for multi-vendor integration and portfolio diversification into adjacent security management domains.
Within the diversified technology tier, Cisco Systems Inc. and Dell Technologies Inc. occupy positions anchored by enterprise hardware footprints. Huawei Technologies Co. Ltd. exemplifies the integrated stack archetype through captive silicon capabilities. Arista Networks Inc. sits within the cloud-native specialization tier alongside VMware Inc., representing pure-play controller architecture focus.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise Co. |
| Huawei Technologies Co. Ltd. |
| Cisco Systems Inc. |
| Dell Technologies Inc. |
| Nokia Corp. |
| VMware Inc. |
| Arista Networks Inc. |
| Ciena Corp. |
| Juniper Networks Inc. |
| Others |
Supply & Pricing Matrix
Silicon wafer costs for programmable forwarding chips cascade through controller manufacturing tiers, with captive fabrication in Shenzhen commanding premium positioning against merchant-sourced alternatives subject to MIIT export certification delays.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to SDN controllers qualifying for FCC cybersecurity certification under expedited review tracks, while spot inventory from non-certified suppliers trades at discounts. Subscription licensing for cloud-based orchestration platforms stratifies across enterprise, mid-market, and service provider tiers based on forwarding table capacity and API call volume entitlements. Pricing pressure stems from hyperscale operators consolidating procurement through framework agreements that extract volume concessions. Government agencies exhibit lowest price sensitivity due to zero-trust mandate compliance deadlines, while educational institutions face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements from United States federal procurement mandates force qualification of alternative controller suppliers beyond dominant Asian manufacturing bases, extending vendor onboarding timelines. Controller production concentrates in China, Taiwan, and Malaysia, with assembly drawing from Penang semiconductor packaging clusters and Bangalore firmware development centers. Merchant silicon dependencies for programmable switching ASICs rest on TSMC and Samsung foundry capacity allocation decisions. Single-source vulnerability concentrates in advanced node fabrication for sub-microsecond latency chips. Distribution runs through direct OEM channels for hyperscale accounts and systems integrator resale for enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act creates a cost-of-compliance moat where encryption-capable controller architectures become mandatory for sensitive data processing, advantaging vendors with pre-certified security modules over retrofit-dependent competitors.
For Market Incumbents: Deploy intent-based networking roadmaps to compress customer provisioning cycles from weeks to minutes, embedding automated compliance verification that locks out point-solution entrants. Deepen silicon-to-software integration to reduce merchant chip dependency as tariff exposure on Taiwanese foundry output intensifies. Capture recurring automation subscription revenue through managed service provider channel programs that displace capital-intensive hardware refresh cycles.
For New Entrants and Emerging Players: Capture edge deployment white space in German automotive testing corridors and Japanese manufacturing automation clusters where localized data governance requirements favor nimble compliance positioning. Target Indian telecommunications infrastructure under TRAI spectrum allocation programs as the most penetrable geography given national broadband initiative scale. Pursue cloud-native controller architectures with API-first integration to bypass entrenched CLI-dependent incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated silicon-to-software specialists with captive supply chains in Shenzhen and Bangalore as tariff volatility pressures merchant-chip-dependent competitors. Long-term viability centers on five-to-ten year federal zero-trust mandate compliance windows sustaining encryption-capable controller demand. Monitor FCC cybersecurity certification queue lengths as inflection indicator for vendor revenue recognition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding SDN controllers with zero-trust security modules satisfies NIS2 Directive procurement requirements for European critical infrastructure operators. |
| Strategic Partnership | Systems integrator alliances capture consumption-based licensing shifts visible in United States federal GSA schedule contracting patterns. |
| Geographic Expansion | Controller engineering presence in Silicon Valley addresses sub-microsecond latency specifications demanded by Ashburn and Prineville hyperscale operators. |
| Product Launch | Intent-based networking systems displace manual CLI configuration, compressing provisioning cycles while embedding EU AI Act compliance verification. |
| Acquisition of Specialist Firm | Analytics platform targets address observability requirements intensifying across cloud operator multi-tenant fabric management. |
Research Methodology
Document review covered SEC filings from networking equipment vendors, hyperscaler capital expenditure disclosures, and EU regulatory impact assessments, complemented by interviews with network engineering directors at cloud service providers, telecommunications procurement leads, federal IT contracting officers, and systems integrator practice heads. Secondary validation drew from FCC certification databases, ETSI interoperability specifications, and TRAI spectrum allocation records. Bottom-up segmentation modeling triangulated against top-down market sizing from infrastructure investment tracking.
Cross-referencing historical deployment velocity against expert panel input shaped the analytical framework across deployment models, solution architectures, and end-user industries. Segmentation dimensions modeled include cloud versus edge versus on-premises configurations, network automation versus security management versus analytics solution types, and telecommunications versus government agency verticals. CAGRs were derived from install base replacement cycle analysis and greenfield infrastructure buildout trajectories. Forecast inputs incorporated hyperscale data center construction pipelines and EU Cybersecurity Act implementation timelines.
The model holds under stable regulatory certification timelines and continued hyperscale infrastructure investment; deviation in FCC queue processing speeds or MIIT export control expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Data Deduplication Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
Software Defined Video Networking Market
Data Center and Networking
Internet Protocol Version 6 (IPv6) Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
Dedicated Internet Access Market