
 Global Mobile Content Delivery Network Market | 2026-2036
Global Mobile Content Delivery Network Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Content Delivery Network Market Foresight
End-use demand is shifting decisively toward media and entertainment platforms as short-form video and live streaming consume disproportionate mobile bandwidth. Akamai Technologies leverages its massive edge server footprint to dominate latency-sensitive video delivery. Cloudflare differentiates through integrated security and performance stacks that reduce vendor complexity. Amazon Web Services sustains expansion via backward integration into cloud compute and storage tiers that lock in enterprise workloads.
A mobile content delivery network distributes cached digital assets through geographically dispersed proxy servers optimized for cellular network topology, typically operating at sub-50 millisecond latency targets to ensure seamless playback on variable 4G and 5G connections. Its primary commercial purpose is to minimize origin server load while preserving quality of experience for subscribers on bandwidth-constrained or high-congestion wireless links. Cloud-based deployment models anchor the architecture given hyperscaler economies of scale and API-driven provisioning speed. Video streaming content types command the largest bandwidth allocation and infrastructure investment intensity. Edge computing segments within deployment models represent the fastest structural expansion as operators push computation toward radio access network boundaries.
FCC spectrum allocation rules in the United States, GDPR data localization mandates enforced by European regulators, and India's TRAI net neutrality framework collectively shape where providers must site infrastructure and how traffic routing architectures comply. ISO 27001 and IEC 62368-1 standards further constrain security and safety certifications for edge hardware deployments. Stakeholders must monitor evolving 5G standalone core rollouts and sovereign cloud requirements to calibrate capital deployment and partnership strategies.
Market Dynamics
5G standalone core rollouts are compressing latency requirements below 20 milliseconds, forcing CDN providers to relocate compute resources from centralized data centers toward radio access network edges. This topological shift demands entirely new capital deployment models and partnership structures with telecommunications operators.
Growth Catalysts
- India's Digital India initiative:Government-funded rural broadband expansion and mobile-first consumption patterns among 1.4 billion subscribers are accelerating edge infrastructure investment across tier-2 and tier-3 cities.
- EU AI Act data residency mandates:Strict localization requirements for AI training data are compelling hyperscalers to deploy sovereign edge nodes within European member states rather than routing traffic through centralized hubs.
- Short-form video bandwidth surge:Media and entertainment platforms now account for the largest share of mobile data consumption, driving disproportionate infrastructure investment in video-optimized caching layers.
Market Restraints
- Edge server hardware cost volatility:Specialized GPUs and AI accelerators required for intelligent caching face supply concentration risk from Taiwan-based foundries and memory suppliers.
- GDPR cross-border data friction:European regulators' strict interpretation of lawful data transfer mechanisms complicates multi-region content synchronization and increases compliance overhead.
- Terrestrial fiber backhaul limitations:Last-mile connectivity gaps in emerging markets constrain the theoretical performance gains of distributed edge architectures.
Strategic Opportunities
- Indonesia's underserved archipelago:Maritime geography and 17,000+ islands create natural demand for satellite-integrated mobile CDN nodes where submarine cable deployment remains uneconomical.
- Cloud-gaming latency requirements:Interactive streaming applications demand sub-10 millisecond response times that only hyper-local edge compute can deliver, opening premium service tiers.
- API-driven security convergence:Integrated DDoS mitigation and bot management bundled with content delivery is displacing standalone security vendor relationships in enterprise procurement.
Industry Challenges
- ISO 27001 certification timelines:Extended audit cycles for edge hardware deployments delay revenue recognition and complicate multi-tenant facility rollouts.
- Legacy CDN interoperability:Enterprises maintaining hybrid on-premise and cloud architectures face integration complexity when migrating workloads to mobile-optimized edge stacks.
- Specialized edge DevOps talent scarcity:Shortage of engineers proficient in Kubernetes orchestration across distributed radio access network environments constrains deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Content Delivery Network Market |
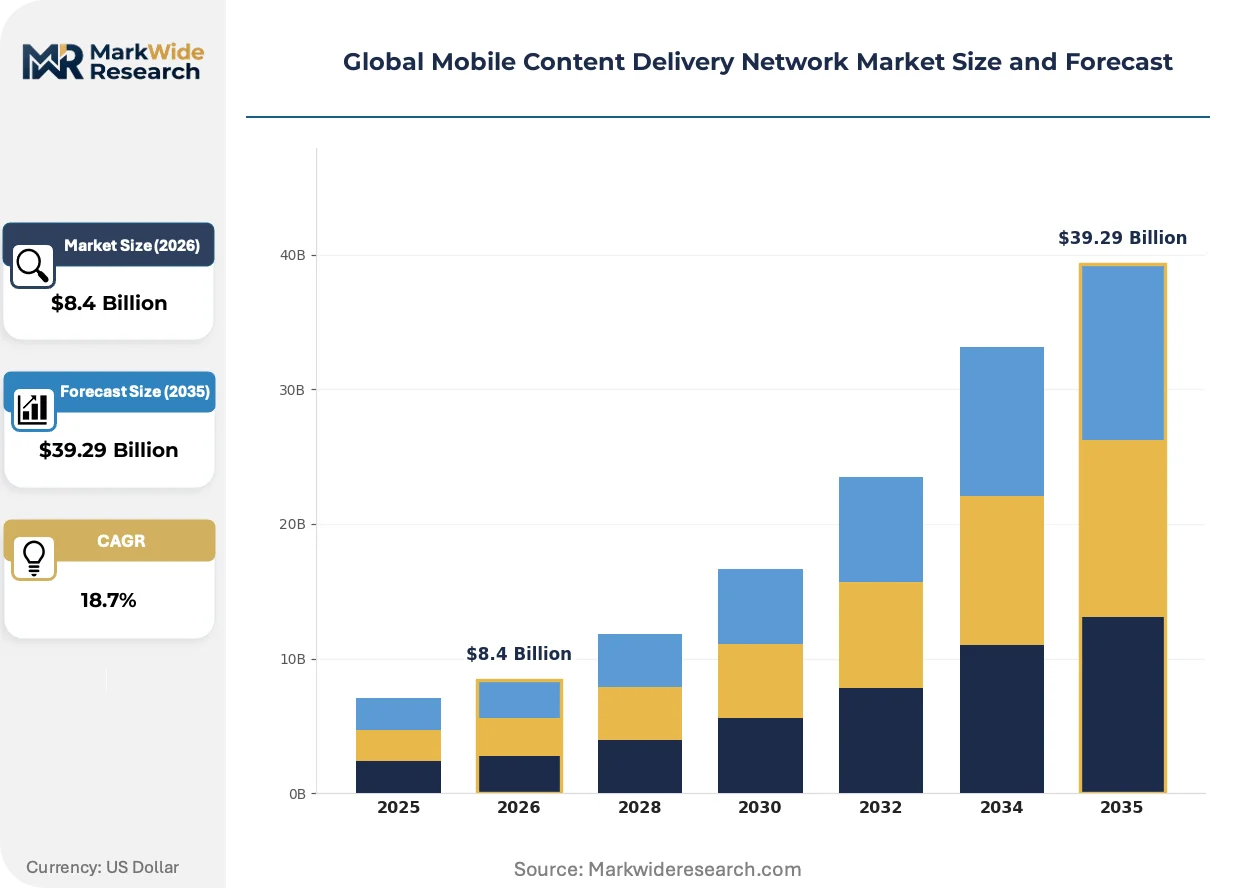
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid Solutions, Edge Computing Content Type: Video Streaming, Software Downloads, Web Content, Social Media Data, Gaming Content End User Industry: Telecommunication Providers, Media & Entertainment, E-Commerce Platforms, Online Education, Financial Services Service Offering: Bandwidth Optimization, Security & DDoS Protection, Analytics & Reporting, Load Balancing, API Acceleration |
| Companies Covered | Akamai Technologies, Amazon Web Services, Google Cloud, Microsoft Azure, Cloudflare, Fastly, Tencent Cloud, Edgio, AT&T, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Content Delivery Network Market Shifts & Advancements
Containerized micro-CDN architectures are fragmenting traditional monolithic delivery models, enabling telecommunications operators to deploy software-defined caching instances directly onto base station hardware. This convergence of cloud-native tooling with cellular infrastructure is compressing vendor consolidation timelines.
Serverless edge functions are modularizing how application logic executes across mobile CDN footprints. Gaming and financial services firms are deploying lightweight compute containers at thousands of Points of Presence simultaneously. The technology is modularizing the traditional split between content delivery and application hosting, collapsing two vendor categories into unified platforms.
The EU AI Act's risk-based classification system is mandating algorithmic transparency for content recommendation engines that traverse European networks. Industrial consequence includes mandatory documentation of training data provenance and human oversight protocols for automated content ranking. Video streaming platforms serving EU subscribers are responding by localizing inference workloads to GDPR-compliant edge nodes rather than centralized cloud regions.
Enterprise procurement of mobile CDN services is consolidating around outcome-based performance guarantees rather than bandwidth-commitment contracts. Chief information officers at retail and logistics firms are replacing multiple point-solution vendors with integrated security-performance stacks. This pattern is most visible in India, where digital-native enterprises prioritize API-driven provisioning speed over legacy procurement processes.
Global Mobile Content Delivery Network Market Segmentation
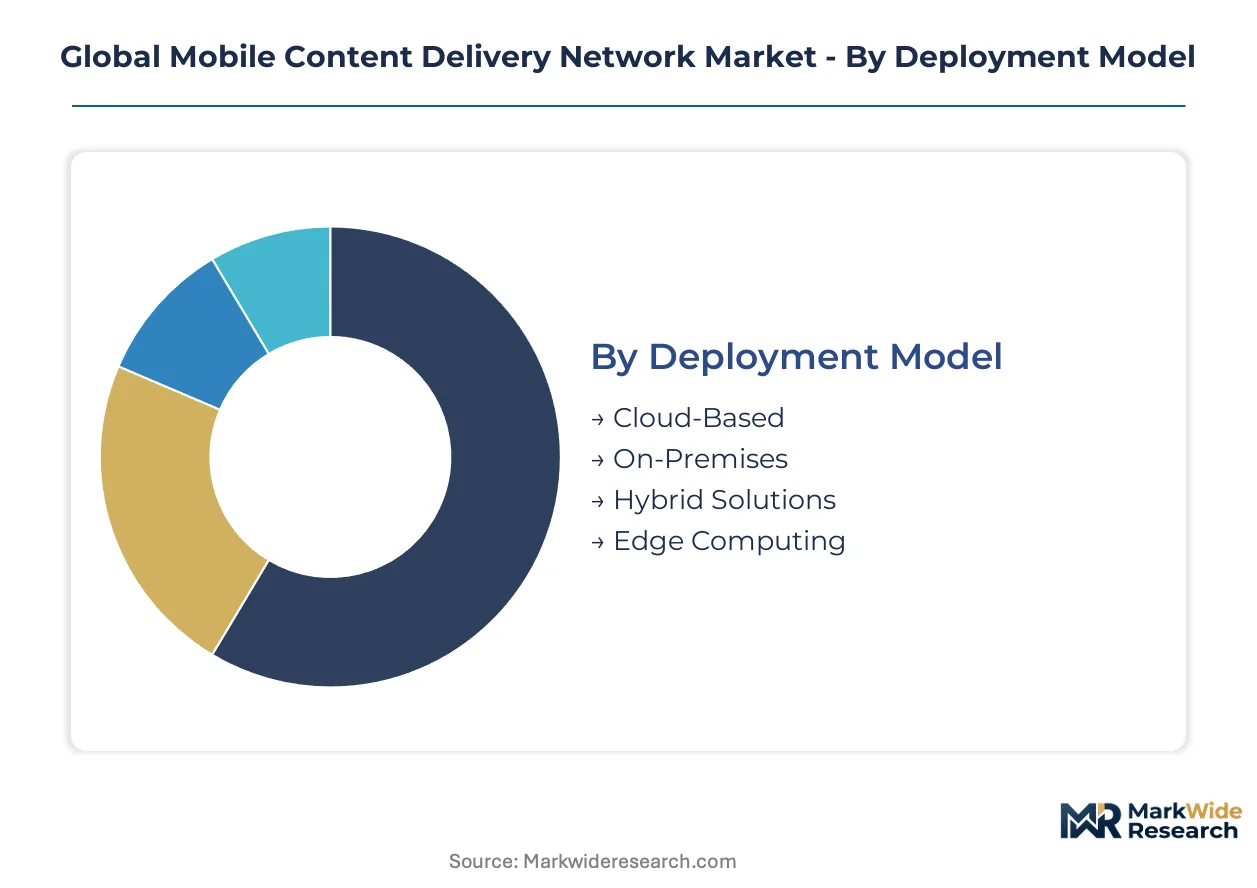
Segmentation in mobile CDN markets reveals how infrastructure investment aligns with latency requirements and data sovereignty pressures. Deployment topology, content characteristics, and service bundling each shape vendor positioning and capital allocation decisions across telecommunications ecosystems.
Deployment Model:
Supply concentration in cloud hyperscalers is fragmenting as telecommunications operators demand localized edge presence for sub-20 millisecond latency targets.
- Cloud-Based:Hyperscaler-managed infrastructure delivers elastic capacity provisioning through API-driven orchestration. Media and entertainment platforms in India concentrate demand here, driven by government digital initiatives requiring rapid scaling across tier-2 and tier-3 urban centers.
- Edge Computing:Compute resources deployed at radio access network boundaries enable sub-10 millisecond response times for interactive applications. Cloud-gaming studios and financial services firms in the EU are accelerating adoption, compelled by GDPR data residency mandates and the EU AI Act's risk-based classification system.
- Hybrid Solutions:Enterprises blend on-premise caching with cloud burst capacity to maintain sovereignty over sensitive workloads.
- On-Premises:Telecommunications operators deploy captive infrastructure to retain full control over subscriber data flows.
Cloud-Based deployment absorbs the bulk of installed capacity; Edge Computing is expanding most quickly.
Content Type:
Bandwidth intensity varies dramatically across content categories, with video-optimized caching layers commanding disproportionate infrastructure investment.
- Video Streaming:Adaptive bitrate delivery consumes the largest share of mobile network capacity through geographically dispersed proxy servers. Short-form platforms in Indonesia's archipelago drive specialized demand, where maritime geography necessitates satellite-integrated CDN nodes beyond submarine cable reach.
- Gaming Content:Interactive streaming requires deterministic latency below 10 milliseconds that only hyper-local edge compute can sustain. Cloud-gaming operators across Japan and South Korea are prioritizing this segment, responding to METI and MFDS guidelines on network performance standards.
- Software Downloads:Chunked distribution protocols optimize for intermittent connectivity on variable cellular links.
- Web Content:Static asset caching remains foundational to mobile browsing quality of experience.
- Social Media Data:Personalized feed delivery demands real-time inference at edge locations to comply with data localization requirements.
Video Streaming commands the greatest infrastructure deployment; Gaming Content is climbing the fastest as latency requirements compress.
End User Industry:
Procurement patterns diverge between infrastructure owners and application platforms, with API-driven provisioning speed displacing legacy vendor relationships.
- Telecommunication Providers:Network operators deploy mobile CDN infrastructure as a competitive differentiator for 5G standalone core services. India's TRAI net neutrality framework shapes how these providers architect traffic routing and edge node placement across subscriber-dense urban corridors.
- Media & Entertainment:Streaming platforms prioritize outcome-based performance guarantees over bandwidth-commitment contracts. EU-based video services are localizing inference workloads to GDPR-compliant edge nodes, responding to algorithmic transparency mandates under the EU AI Act.
- E-Commerce Platforms:Retail applications demand low-latency image delivery and personalized recommendation engines.
- Financial Services:Trading and mobile banking applications require deterministic response times and ISO 27001-certified edge deployments.
- Online Education:Live interactive streaming drives demand for synchronous content delivery across dispersed student populations.
Telecommunication Providers anchor current infrastructure deployment; Media & Entertainment is gaining share fastest as short-form video consumption surges.
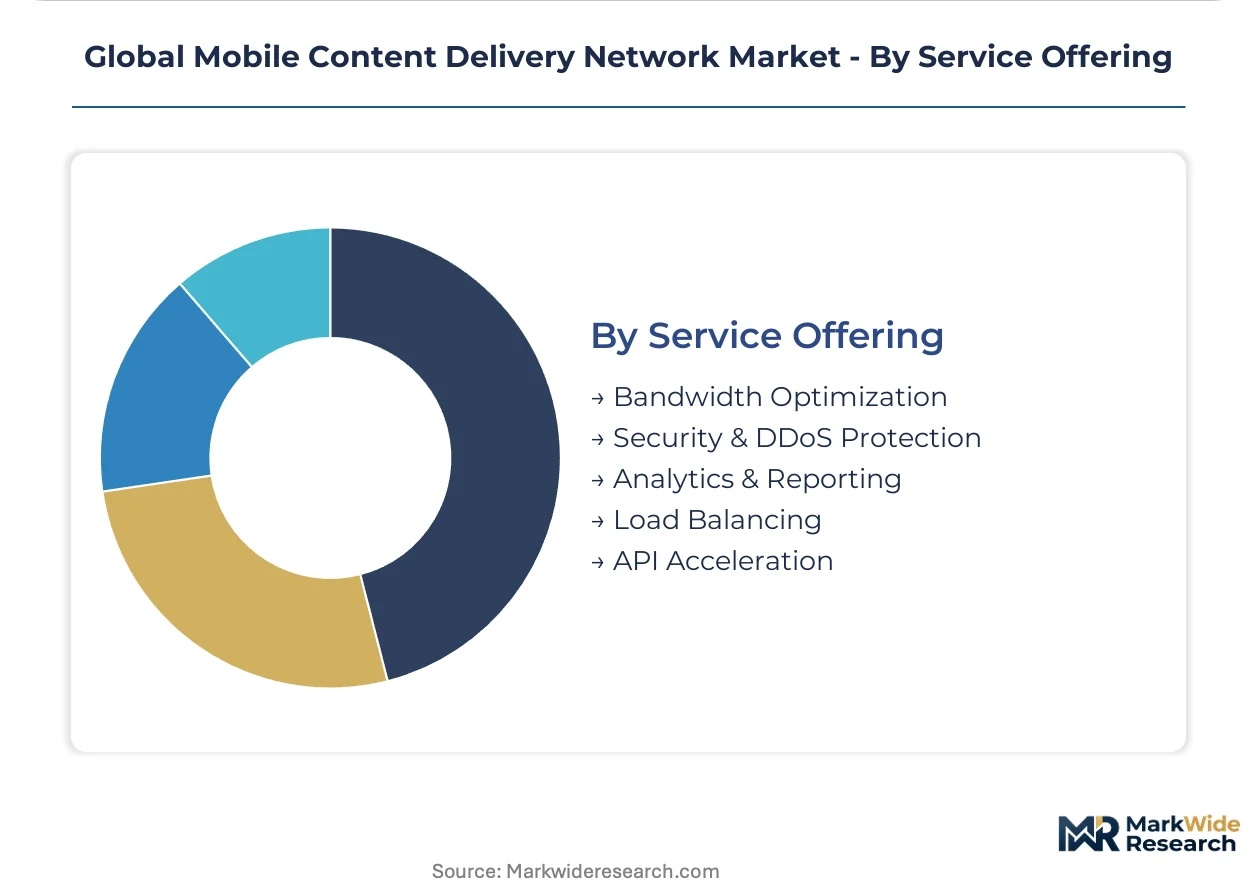
Service Offering:
Enterprise procurement is consolidating around integrated security-performance stacks that reduce vendor complexity and compliance overhead.
- Security & DDoS Protection:Integrated bot management and volumetric attack mitigation displace standalone security vendor relationships. Financial services firms in Singapore and Hong Kong prioritize this bundling, responding to central bank guidance on operational resilience for digital payment infrastructure.
- Bandwidth Optimization:Intelligent compression and protocol optimization preserve quality of experience on bandwidth-constrained wireless links. Telecommunications providers across Brazil's ANVISA-regulated health data corridors deploy these services to support telemedicine applications.
- Analytics & Reporting:Real-time telemetry on viewer experience and network conditions informs capacity planning decisions.
- Load Balancing:Traffic distribution across edge nodes ensures continuity during regional network congestion events.
- API Acceleration:Optimized routing for programmatic interfaces supports mobile application backend performance.
Security & DDoS Protection captures the largest service contract values; Bandwidth Optimization is expanding most quickly as emerging market 4G and 5G penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Edge infrastructure investment concentrates where mobile data consumption outpaces fixed-line capacity, creating divergent deployment economics across major economies. The United States and China anchor hyperscaler expansion, while India and Indonesia drive emerging market growth through government-funded connectivity programs.
United States
FCC spectrum allocation rules for 5G mid-band and millimeter-wave frequencies accelerate radio access network densification. Network operators deploy edge nodes to comply with latency requirements for cloud-gaming and autonomous vehicle applications. Seattle and San Francisco Bay Area clusters host hyperscaler engineering centers optimizing mobile CDN orchestration software.
Germany
Industrial automation and automotive telemetry generate demand for sub-20 millisecond edge compute within manufacturing corridors. GDPR data localization mandates and the EU AI Act's risk-based classification system compel sovereign cloud deployments. Bavaria's Munich-Stuttgart axis concentrates telecommunications R&D facilities developing 5G standalone core integration.
India
Digital India initiative funding drives rural broadband expansion across tier-2 and tier-3 cities where mobile-first consumption dominates. TRAI net neutrality frameworks shape traffic routing architectures and edge node placement decisions. Bangalore and Hyderabad clusters anchor hyperscaler data center construction responding to government cloud-first procurement policies.
Indonesia
Maritime geography across 17,000 islands creates structural demand for satellite-integrated CDN nodes beyond submarine cable economics. Short-form video platforms drive disproportionate bandwidth consumption among 270 million mobile subscribers. Jakarta and Surabaya corridors concentrate telecommunications infrastructure investment while outer island provinces remain underserved.
Brazil
ANVISA-regulated health data corridors require localized edge processing for telemedicine and mobile diagnostic applications. 4G and 5G penetration deepening in São Paulo and Rio de Janeiro metro areas drives intelligent caching layer investment. São Paulo state's technology corridor anchors Latin American hyperscaler regional headquarters and edge compute deployment decisions.
Global Mobile Content Delivery Network Market Competitive Landscape
Top-tier vendors anchor hyperscale infrastructure deployment, while mid-tier specialists compete on latency-specific verticals. The market structures around three concentration tiers: cloud-native hyperscalers with backward integration into compute and storage, telecommunications operators with captive subscriber bases, and security-optimized challengers bundling DDoS mitigation with delivery. Strategic moves concentrate on M&A to acquire edge compute capabilities and strategic partnerships with 5G standalone core operators.
Among established infrastructure providers, Akamai Technologies, Amazon Web Services, and Cloudflare occupy distinct archetype positions. Akamai exemplifies the massive edge footprint incumbent leveraging decades of server deployment density. Amazon Web Services represents hyperscaler backward integration into cloud compute tiers that lock enterprise workloads. Cloudflare sits within the integrated security-performance challenger tier displacing standalone vendor relationships through API-driven bundling.
| Leading Market Players |
|---|
| Akamai Technologies |
| Amazon Web Services |
| Google Cloud |
| Microsoft Azure |
| Cloudflare |
| Fastly |
| Tencent Cloud |
| Edgio |
| AT&T |
| Others |
Supply & Pricing Matrix
Kubernetes-orchestration engineers concentrated in Bangalore and Hyderabad drive labor-cost differentials that widen pricing-tier spreads between hyperscaler-managed and operator-captive edge deployments. European GDPR compliance overhead and Taiwan-based GPU supply concentration further stratify procurement economics across cloud-based, edge computing, and hybrid solution tiers.
Pricing Analysis
Margin tightening in economy-tier edge computing reflects hyperscaler price competition for telecommunications operator contracts. Three-tier pricing structure across premium, standard, and economy levels dominates, with ISO 27001 certification and sub-10 millisecond latency guarantees as primary differentiation drivers. Cost compression accelerates as Indian digital infrastructure subsidies attract volume-seeking entrants. Telecommunications providers exhibit highest price sensitivity; financial services firms prioritize deterministic performance over unit economics.
Supply Chain Analysis
Edge server assembly workforce availability in Taiwan, South Korea, and Vietnam shapes manufacturing capacity allocation. Specialized AI accelerators and high-bandwidth memory modules draw from TSMC foundry output and Samsung HBM supply. Single-source vulnerability in Taiwan-based GPU packaging constrains deployment velocity for latency-critical gaming workloads. Distribution runs through hyperscaler direct-provision channels and telecommunications operator captive integration programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscaler backward integration into cloud compute tiers is compressing margins for standalone CDN specialists, forcing consolidation among undifferentiated mid-tier vendors. Market incumbents must anchor defensive positions through targeted capability acquisition.
For Market Incumbents: Anchor market position through backward integration into 5G standalone core partnerships with telecommunications operators in India and Indonesia. Prioritize ISO 27001 certification investment to defend against Cloudflare's security-performance bundling threat. Acquire Kubernetes-orchestration talent pools in Bangalore and Hyderabad to constrain deployment velocity for challengers. For New Entrants and Emerging Players: EU AI Act data residency mandates in Germany and France open a window for sovereign edge node deployment targeting GDPR-compliant inference workloads. Target Indonesia's underserved archipelago provinces where satellite-integrated CDN infrastructure remains underpenetrated. Lead with API-driven provisioning speed to displace legacy procurement relationships at Indian digital-native enterprises. For Investors and Strategic Acquirers: The window for entry favors telecommunications operators with captive subscriber bases and distributed radio access network real estate. Long-term viability hinges on 5G standalone core rollout synchronization and sovereign cloud requirement enforcement. Watch TRAI net neutrality framework evolution as inflection indicator for Indian infrastructure deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Compute Partnership with Telecom Operators | Secures sub-20 millisecond latency commitment through 5G standalone core integration. |
| Sovereign Cloud Node Deployment | Addresses EU AI Act and GDPR data residency mandates in member states. |
| API-Driven Security-Performance Bundling | Displaces standalone DDoS vendors through integrated bot management and delivery. |
| Containerized Micro-CDN Architecture | Enables software-defined caching deployment directly onto base station hardware. |
| Satellite-Integrated CDN Expansion | Reaches Indonesia's 17,000 islands beyond submarine cable economics. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, telecommunications operator 5G deployment timelines, and edge server shipment volumes anchored the trend analysis, supplemented by interviews with CTOs at streaming platforms, network engineering leads at telecommunications operators, procurement officers at financial services firms, and cloud infrastructure specialists. SEC filings, TRAI regulatory notices, EU AI Act implementation guidance, and hyperscaler regional expansion announcements provided secondary validation. Bottom-up capacity deployment modeling and top-down demand segmentation triangulated market sizing.
Segment-weighting across deployment model, content type, end user industry, and service offering dimensions structured the analytical framework. CAGRs derived from elasticity-adjusted demand projections and infrastructure investment cycle alignment. 5G standalone core rollout velocity and GDPR sovereign cloud requirement enforcement served as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for containerized micro-CDN architectures would alter the outlook. Forecasts reflect assumptions regarding spectrum allocation timelines and edge hardware cost trajectories. Material deviation in EU AI Act enforcement intensity or Taiwan-based foundry capacity allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Japan Data Center Server Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Saudi Arabia Data Center Networking Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Data Center Market
Data Center and Networking
Computer Servers Market
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
Broadband Network Gateway Market
Data Center and Networking
Global Storage Area Network (SAN) Switches Market
Data Center and Networking
Network As a Service (Naas) Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
MPLS-Based Core Network Market