
 Mexico Ceramic Tiles Market | 2026-2036
Mexico Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Ceramic Tiles Market Foresight
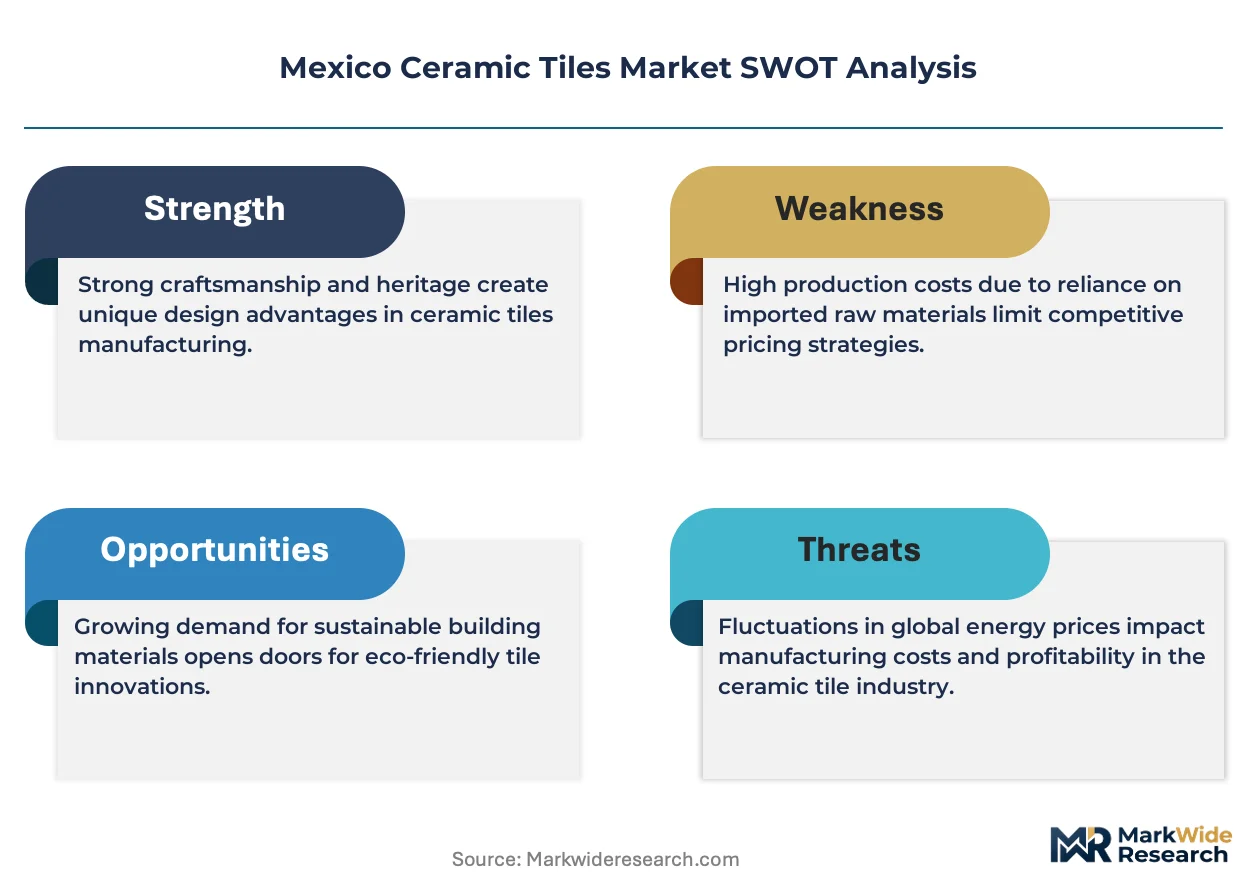
The premium and commodity tiers in Mexico ceramic tiles is decoupling along format size, surface technology, and distribution channel. Grupo Lamosa S.A.B. de C.V. leverages vertical integration from clay extraction through retail to dominate mid-market porcelain. Interceramic Inc. anchors its position through proprietary digital printing technology and designer showroom networks. Vitromex competes aggressively on price in standard formats through mass retail channels across northern Mexico.
Ceramic tiles are flat, fired clay products with water absorption rates typically below 0.5% for porcelain and 3-6% for standard ceramic, manufactured through single or double firing processes and used primarily for surfacing floors and walls in built environments. Glazed tiles occupy the largest volume share due to cost efficiency in residential mass housing, while polished porcelain commands the strongest margin pools in commercial and high-end residential projects. The application split tilts toward residential construction, though commercial retrofit activity in Mexico City's hospitality sector is expanding faster.
Mexico's NOM building standards and PROFECO consumer protection framework shape product labeling, slip resistance ratings, and import compliance requirements for ceramic surfacing materials. BIS-equivalent conformity assessment procedures for cross-border suppliers from Asia and Europe add certification layers that favor established distributors with testing laboratory relationships. Stakeholders must monitor whether upcoming revisions to federal construction codes will mandate recycled content thresholds or embodied carbon disclosures for building materials.
Market Dynamics
Large-format porcelain slabs are compressing the traditional ceramic tile value chain in Mexico, forcing manufacturers to retool kilns and distributors to reconfigure logistics networks around slab handling requirements.
Growth Catalysts
- NOM Energy Efficiency Standards:Tightening federal building codes in Mexico are mandating higher thermal performance from cladding materials, pulling specification-grade porcelain into residential envelopes that previously accepted standard ceramic.
- Bajío Industrial Corridor:Manufacturing facility construction across Guanajuato and Querétaro is generating concentrated demand for anti-slip commercial-grade flooring in food processing and automotive plants.
- Digital Inkjet Printing:Advanced surface decoration technology is collapsing the cost gap between natural stone aesthetics and manufactured tile, expanding addressable market into premium residential segments.
Market Restraints
- Natural Gas Price Volatility:Kiln firing costs in Mexico track Pemex pipeline tariffs and LNG import spot markets, compressing margins for energy-intensive porcelain production during price spikes.
- Import Concentration from China:Cross-border tile flows through Lázaro Cárdenas and Manzanillo create inventory risk when PROFECO anti-dumping investigations disrupt established supplier relationships.
- Slip Resistance Certification Gaps:NOM labeling requirements for wet-area applications lack harmonized testing protocols with ANSI standards, forcing dual certification costs for projects with US contractor involvement.
Strategic Opportunities
- Yucatán Peninsula Tourism:Resort construction in Cancún and Mérida remains underpenetrated by domestic slab producers, creating first-mover advantage for distributors establishing local fabrication partnerships.
- Recycled Content Mandates:Upcoming revisions to federal construction codes may establish post-industrial ceramic waste thresholds, rewarding manufacturers with captive quarry reclamation operations.
- Direct-to-Project Digital Platforms:Contractor procurement through specialized B2B marketplaces is bypassing traditional distributor markups in Mexico City's high-rise residential segment.
Industry Challenges
- Large-Format Installation Certification:The shortage of trained slab handlers and specialized thin-set applicators is delaying project completion and generating warranty disputes in high-end residential developments.
- Kiln Retrofit Capital Requirements:Transitioning from traditional press lines to continuous roller kilns capable of 1600mm+ formats demands capital commitments that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Ceramic Tiles Market |
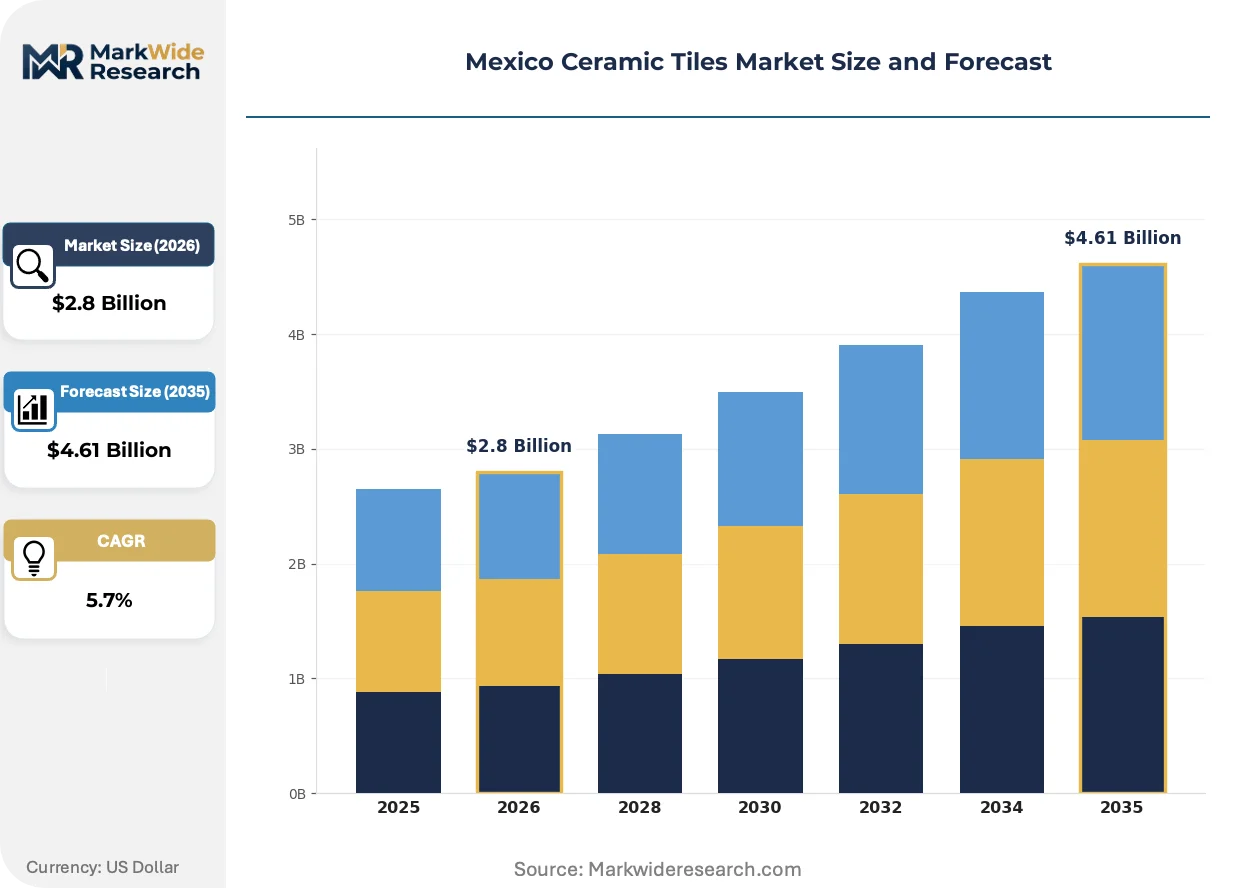
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Unglazed Tiles, Polished Tiles, Textured Tiles Application: Residential, Commercial, Industrial, Outdoor Material: Ceramic, Porcelain, Stoneware, Earthenware Design Style: Modern, Rustic, Vintage, Contemporary |
| Companies Covered | Grupo Lamosa S.A.B. de C.V., Interceramic Inc., Vitromex, Dal-Tile Corporation, Cesantoni S.A. de C.V., Porcelanosa Grupo, RAK Ceramics, Mohawk Industries, Pamesa Ceramica, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Ceramic Tiles Market Shifts & Advancements
Surface technology convergence and procurement digitization are fragmenting Mexico's historically consolidated tile distribution channels, creating parallel supply paths for commodity bulk and specification-grade projects.
Thin large-format porcelain panels are unifying flooring and wall cladding specifications in luxury residential towers across Polanco and Santa Fe. Developers specify single material systems to accelerate construction schedules and reduce subcontractor coordination. This unifying trend compresses the traditional separation between tile contractors and stone fabricators.
PROFECO's expanded surveillance of imported ceramic surfacing materials is tightening conformity assessment documentation requirements at Mexican ports. Distributors now maintain captive testing relationships with accredited laboratories to preempt customs delays. Northern border states with established US contractor networks face the steepest compliance cost increases.
Project developers in Jalisco and Nuevo León are consolidating purchase decisions through centralized procurement offices, displacing architect-driven specification with volume-based supplier contracts. This concentration shifts bargaining power toward distributors with national logistics footprints and away from regional showrooms. The trend is most visible in multi-tower residential developments where single-source cladding packages reduce variation risk.
Mexico Ceramic Tiles Market Segmentation
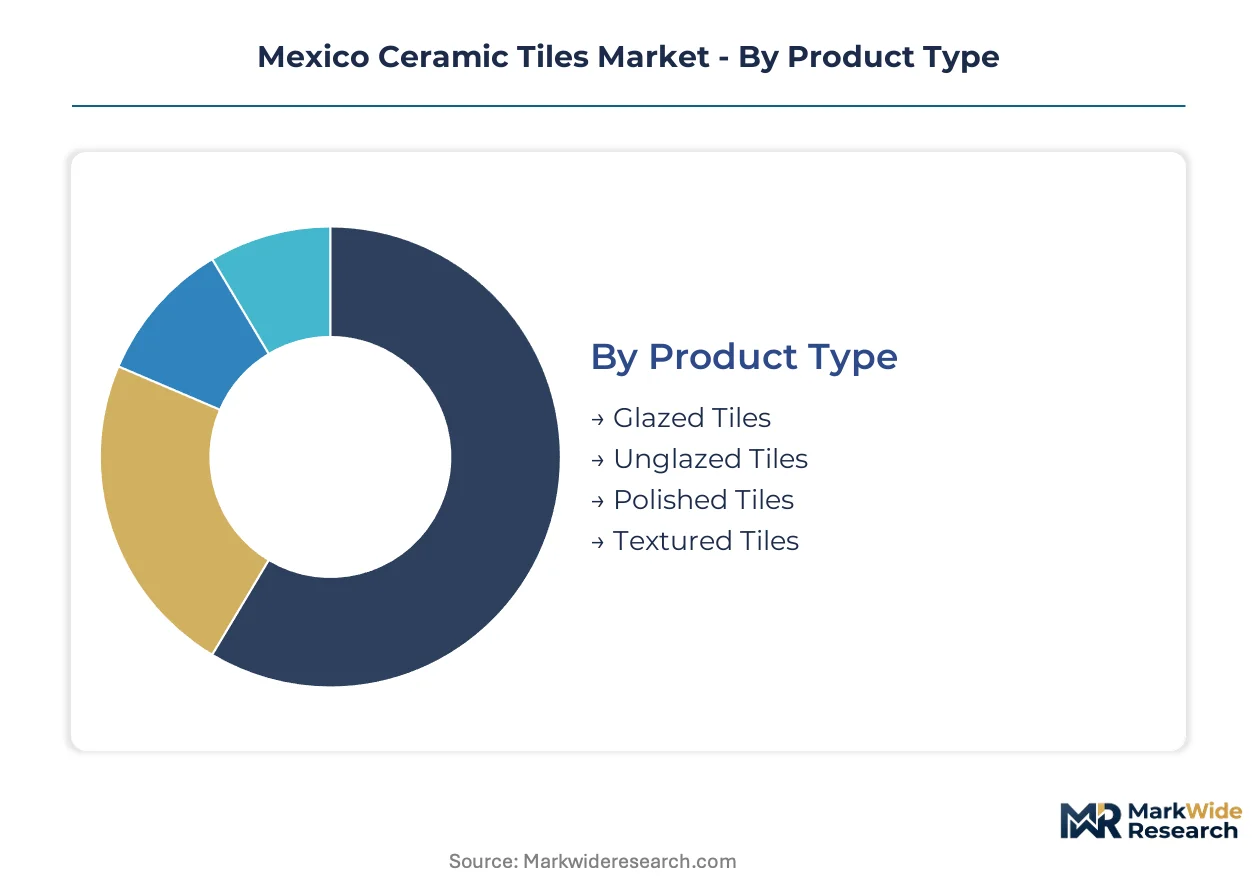
Product differentiation across surface technology and installation context determines margin capture in Mexico's ceramic tiles landscape. Specification-grade porcelain commands premium positioning in high-rise residential towers, while commodity ceramic serves mass housing through retail channels.
Product Type:
Glazed tiles function as standalone surfacing solutions with factory-applied glass coatings, while unpolished and textured variants embed into layered specification systems demanding specialized installation protocols.
- Glazed Tiles:Glass-coated ceramic surfaces fired at lower temperatures achieve water absorption rates of 3-6%, making them cost-efficient for residential mass housing across Jalisco and Nuevo León. Demand concentrates in retail channels serving self-build housing segments where moisture resistance requirements remain moderate.
- Polished Tiles:Porcelain tiles undergo mechanical polishing after firing to achieve mirror-finish surfaces with water absorption below 0.5%, commanding specification priority in Mexico City luxury residential towers. Polanco and Santa Fe developers specify these for lobby and amenity spaces where aesthetic differentiation drives unit premiums.
- Unglazed Tiles:Through-body porcelain maintains consistent color and slip resistance without surface coatings, serving commercial food processing facilities in the Bajío industrial corridor where abrasion resistance outweighs decorative priorities.
- Textured Tiles:Surface relief patterns enhance slip resistance for wet-area applications, finding specification in Cancún and Mérida resort construction where NOM safety standards mandate certified flooring for pool decks and spa environments.
Glazed tiles lead volumes today; polished tiles are gaining share fastest.
Application:
Cost-tier stratification separates specification-driven commercial projects from price-sensitive residential bulk procurement, with industrial flooring occupying a distinct technical-performance tier.
- Residential:Single-family and multi-family construction across Mexico City's metropolitan area absorbs the majority of standard-format ceramic, with Jalisco and Nuevo León showing accelerating demand for large-format porcelain slabs in luxury tower developments.
- Commercial:Hospitality retrofit activity in Mexico City and resort construction in the Yucatán Peninsula drive specification-grade porcelain for high-traffic surfaces, with procurement consolidating through centralized developer offices rather than architect-driven selection.
- Industrial:Automotive and food processing plants in Guanajuato and Querétaro specify anti-slip commercial-grade flooring with chemical resistance certifications, generating concentrated demand through engineering-procurement-construction contractors.
- Outdoor:Frost-resistant porcelain pavers serve northern Mexico climates and coastal resort environments, with PROFECO surveillance tightening conformity documentation for imported surfacing materials at Lázaro Cárdenas and Manzanillo ports.
Residential applications dominate current volumes; commercial retrofit activity shows the steepest expansion trajectory.
Material:
Volume concentration tilts toward ceramic and porcelain, with stoneware and earthenware occupying niche positions where traditional fabrication methods or specific thermal properties create defensible demand pockets.
- Ceramic:Standard ceramic tiles manufactured through single or double firing processes serve cost-sensitive residential segments, with Grupo Lamosa's vertical integration from clay extraction through retail maintaining mid-market dominance.
- Porcelain:High-density vitrified tiles fired above 1200°C achieve sub-0.5% water absorption, with digital inkjet printing technology collapsing the cost gap against natural stone and expanding addressable market into premium residential specifications.
- Stoneware:Intermediate density and water absorption characteristics position stoneware for commercial applications requiring moderate durability without full porcelain specification, particularly in northern Mexico retail and office environments.
- Earthenware:Traditional low-fired clay products with higher porosity serve decorative wall applications and heritage restoration projects, with artisanal production concentrated in specific regional craft centers rather than industrial manufacturing.
Ceramic leads volumes today; porcelain is climbing the fastest.
Design Style:
Customer-type segmentation separates developer-specified contemporary aesthetics from retail-driven traditional preferences, with regional taste variation across Mexico's construction corridors.
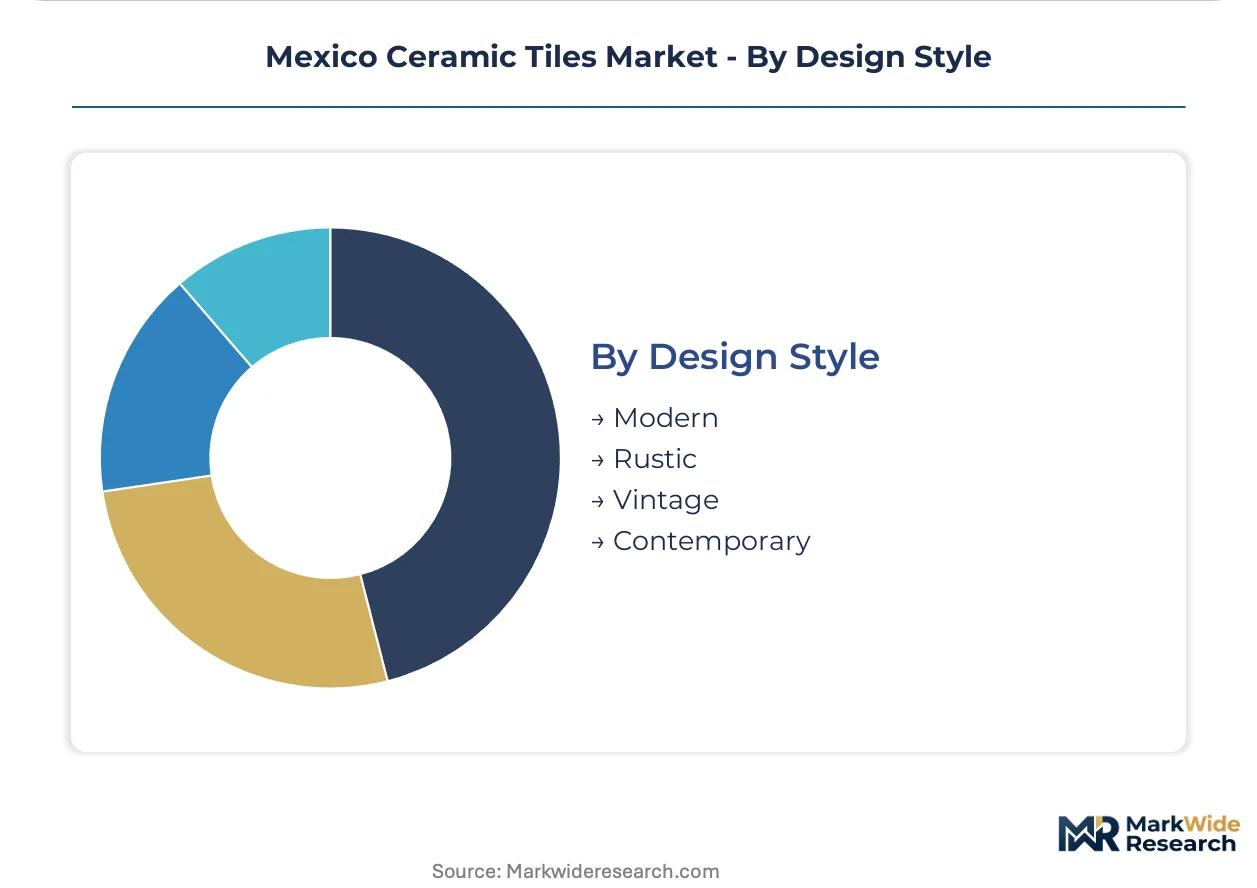
- Modern:Clean lines and minimal surface variation align with Mexico City high-rise residential specifications, where single-material cladding systems accelerate construction schedules and reduce subcontractor coordination complexity.
- Contemporary:Evolving interpretations of current trends incorporate large-format slabs and stone-look digital printing, dominating specification in Polanco and Santa Fe luxury towers where international design standards influence developer choices.
- Rustic:Terracotta-inspired surfaces and hand-finished textures serve regional residential preferences in central Mexican states, with distribution through traditional retail channels rather than project-direct procurement.
- Vintage:Reclaimed-wood and aged-stone aesthetics target hospitality and boutique commercial environments in Mexico City and Guadalajara, where designer showroom networks influence specification through material libraries and sample programs.
Modern styling leads volumes today; contemporary designs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled ceramic technicians and kiln operators concentrate in Jalisco and Nuevo León, anchoring Mexico's tile manufacturing workforce. This talent distribution shapes regional production advantages and supply chain configuration across the country.
Mexico City Metropolitan Area
Luxury residential tower construction in Polanco and Santa Fe absorbs specification-grade polished porcelain for lobby and amenity spaces. NOM energy efficiency standards for buildings mandate higher thermal performance from cladding materials. Developer procurement offices consolidate purchase decisions through centralized contracts, displacing architect-driven specification with volume-based supplier agreements.
Nuevo León
Monterrey's industrial base and cross-border contractor networks generate demand for large-format porcelain slabs in high-rise residential developments. PROFECO surveillance of imported materials creates compliance cost pressures for distributors serving US contractor relationships. The state's manufacturing corridor hosts fabrication partnerships targeting underpenetrated premium segments.
Jalisco
Guadalajara's construction market shows accelerating absorption of large-format porcelain in luxury residential projects. The state's clay extraction operations support vertical integration strategies from raw material through finished product. Regional retail channels serve self-build housing segments with cost-efficient glazed ceramic.
Bajío Region
Automotive and food processing facility construction across Guanajuato and Querétaro drives concentrated demand for anti-slip commercial-grade flooring. Engineering-procurement-construction contractors specify unglazed through-body porcelain where abrasion resistance outweighs decorative priorities. The industrial corridor's growth outpaces local supply capacity for technical-performance tiles.
Yucatán Peninsula
Resort construction in Cancún and Mérida remains underpenetrated by domestic slab producers, creating first-mover opportunities for distributors establishing local fabrication partnerships. NOM safety standards mandate certified slip-resistant flooring for pool decks and spa environments. Textured tiles find specification in hospitality wet-area applications where compliance documentation requirements have tightened.
Mexico Ceramic Tiles Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across Mexico's ceramic tiles landscape. The market structure tilts toward consolidation at the mid-tier, with three to five integrated manufacturers commanding disproportionate volume share against fragmented regional distributors. Strategic archetypes separate vertically integrated clay-to-retail operators, technology-differentiated specification houses, and price-competitive mass-market suppliers. Dominant competitive moves include kiln retrofit investments for large-format capacity and captive testing laboratory relationships to preempt customs delays.
Among Mexico-based integrated manufacturers, Grupo Lamosa S.A.B. de C.V. exemplifies the clay-to-retail archetype through captive quarry operations and national distribution networks. Interceramic Inc. occupies a position within the technology-differentiated tier, while Vitromex represents price-competitive positioning through mass retail channel concentration. These three anchors illustrate the strategic segmentation between integration depth, surface technology investment, and channel specialization that defines competitive positioning in the market.
| Leading Market Players |
|---|
| Grupo Lamosa S.A.B. de C.V. |
| Interceramic Inc. |
| Vitromex |
| Dal-Tile Corporation |
| Cesantoni S.A. de C.V. |
| Porcelanosa Grupo |
| RAK Ceramics |
| Mohawk Industries |
| Pamesa Ceramica |
| Others |
Supply & Pricing Matrix
Continuous roller kiln adoption for 1600mm+ porcelain formats simultaneously inflates capital requirements for Mexican manufacturers and concentrates production capacity among operators with balance sheet depth, compressing mid-tier competitors into subcontracting relationships or exit. This technology transition reshapes cost economics through energy intensity differentials while embedding supply-side concentration that amplifies pricing power for integrated producers with captive clay reserves.
Pricing Analysis
Installation service bundling versus unbundled material-only supply separates pricing architectures across Mexico's ceramic tiles landscape. Three-tier pricing structure across premium, standard, and economy levels stratifies by format size and surface technology, with polished porcelain in Mexico City luxury towers commanding substantial premiums over commodity glazed ceramic in Jalisco self-build segments. Cost compression in standard formats is intensifying because Chinese import flows through Lázaro Cárdenas pressure domestic manufacturers on price. Mass housing developers exhibit highest price sensitivity, while hospitality procurement offices in Cancún prioritize compliance documentation over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from engineering-procurement-construction contractors in the Bajío industrial corridor force distributors to qualify multiple slab suppliers, fragmenting procurement volumes and elevating compliance costs. Manufacturing concentration centers on Mexico, China, and Spain, with domestic production anchored in Jalisco and Nuevo León clay extraction zones. Raw material supply draws from regional feldspar deposits, imported ceramic pigments, and natural gas for kiln firing. Single-source vulnerability persists for digital inkjet printing heads sourced from European specialists. Distribution runs through project-direct channels for specification-grade porcelain and mass retail networks for commodity ceramic.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's ceramic tiles market functions as a regulatory compounder where NOM energy efficiency standard revisions mandate higher-performance cladding materials, pulling specification-grade porcelain into residential envelopes that previously accepted standard ceramic and expanding addressable market for compliant producers.
For Market Incumbents: Anticipate PROFECO anti-dumping investigation expansions by diversifying import sourcing beyond concentrated Chinese supplier relationships. Deepen backward integration into clay extraction and captive testing laboratory relationships to preempt customs delays at Lázaro Cárdenas and Manzanillo. Kiln retrofit investments for large-format capacity represent the critical defensive lever against technology-differentiated competitors. For New Entrants and Emerging Players: The mid-market price-point gap between Interceramic's designer showroom positioning and Vitromex's mass retail economy tier offers white-space opportunity for digital-native distributors. Target Yucatán Peninsula resort construction through local fabrication partnerships, as domestic slab producers remain underpenetrated in Cancún and Mérida. Pursue direct-to-project digital platforms bypassing traditional distributor markups in Mexico City's high-rise residential segment. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with established testing laboratory relationships but limited kiln capacity, offering consolidation platforms for backward integration. Long-term viability over the coming decade hinges on regulatory compliance infrastructure rather than pure manufacturing scale. Watch for NOM recycled content mandate announcements as the inflection signal favoring operators with captive quarry reclamation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Retrofit Investment | Continuous roller kiln adoption enables 1600mm+ format production for luxury residential specifications. |
| Captive Testing Laboratory Partnership | Accredited laboratory relationships preempt PROFECO customs delays at Mexican port facilities. |
| Local Fabrication Partnership | Yucatán Peninsula resort construction demands localized slab handling capabilities for competitive positioning. |
| Direct-to-Project Digital Platform | B2B marketplaces bypass traditional distributor markups in Mexico City's consolidated procurement offices. |
| Clay Extraction Backward Integration | Captive quarry operations secure raw material supply and enable recycled content mandate compliance. |
Research Methodology
Coverage spans Mexico's Bajío industrial corridor, Mexico City metropolitan area, Jalisco manufacturing zone, Nuevo León cross-border region, and Yucatán Peninsula tourism corridor, with primary inputs from each. The analysis combines primary interviews with ceramic plant managers, distributor procurement leads, EPC contractor specification engineers, hospitality developer procurement officers, and retail channel partners with secondary validation. Secondary sources include NOM regulatory filings, PROFECO surveillance reports, SEC 10-K disclosures from listed building materials companies, customs trade data through Lázaro Cárdenas and Manzanillo, and construction permit databases. Bottom-up project pipeline analysis triangulates against top-down macroeconomic construction forecasts.
Rate-of-change decomposition separates volume growth from value mix shift across the projection horizon. The analytical framework models segmentation across product type (glazed, polished, unglazed, textured), application (residential, commercial, industrial, outdoor), material (ceramic, porcelain, stoneware, earthenware), and design style (modern, contemporary, rustic, vintage), with regional adoption patterns as an additional dimension. CAGRs derive from regression analysis against construction starts, industrial facility investment, and tourism development pipelines. Industry-specific forecast inputs include natural gas price volatility scenarios and NOM regulatory revision timelines.
Caveats apply where Pemex pipeline tariff spikes, PROFECO anti-dumping investigation escalations, or NOM recycled content mandate implementations could materially shift the outlook. Deviation in natural gas pricing or federal construction code revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Fire Clay Market
Ceramics
US Kaolin Market
Ceramics
Ceramic Frit Glass Market
Ceramics
Diatomite Market
Ceramics
North America Barium Carbonate Market
Ceramics
Ceramic Kilns Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Mullite Market
Ceramics
North America Activated Alumina Market
Ceramics
Cordierite Market
Ceramics
Egypt Ceramic Tiles Market
Ceramics
Titanium Carbide Market
Ceramics
Potassium Silicate Market
Ceramics
High Purity Mullite Powder Market
Ceramics
East Africa Ceramic Tiles Market