
 Mexico Bariatric Surgery Market | 2026-2036
Mexico Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Bariatric Surgery Market Foresight
Hospital procurement channels for bariatric devices is narrowing as group purchasing organizations consolidate vendor lists across Mexico's private hospital networks. Medtronic PLC leverages its long-standing distributor relationships to sustain implant supply contracts with major hospital chains in central Mexico. Johnson & Johnson competes through its broad surgical stapler portfolio, while Intuitive Surgical Inc anchors the robotic-assisted sleeve gastrectomy segment with its da Vinci system placements.
Bariatric surgery encompasses restrictive, malabsorptive, and combined metabolic procedures performed laparoscopically or robotically to achieve sustained weight reduction and remission of obesity-related comorbidities. Sleeve gastrectomy dominates procedure volume due to its technical simplicity and lower complication profile relative to gastric bypass, though biliopancreatic diversion commands premium pricing for super-obese patient cohorts. Specialized clinics capture the fastest volume growth as ambulatory surgical infrastructure expands, while hospitals retain complex revision cases and patients with government program coverage.
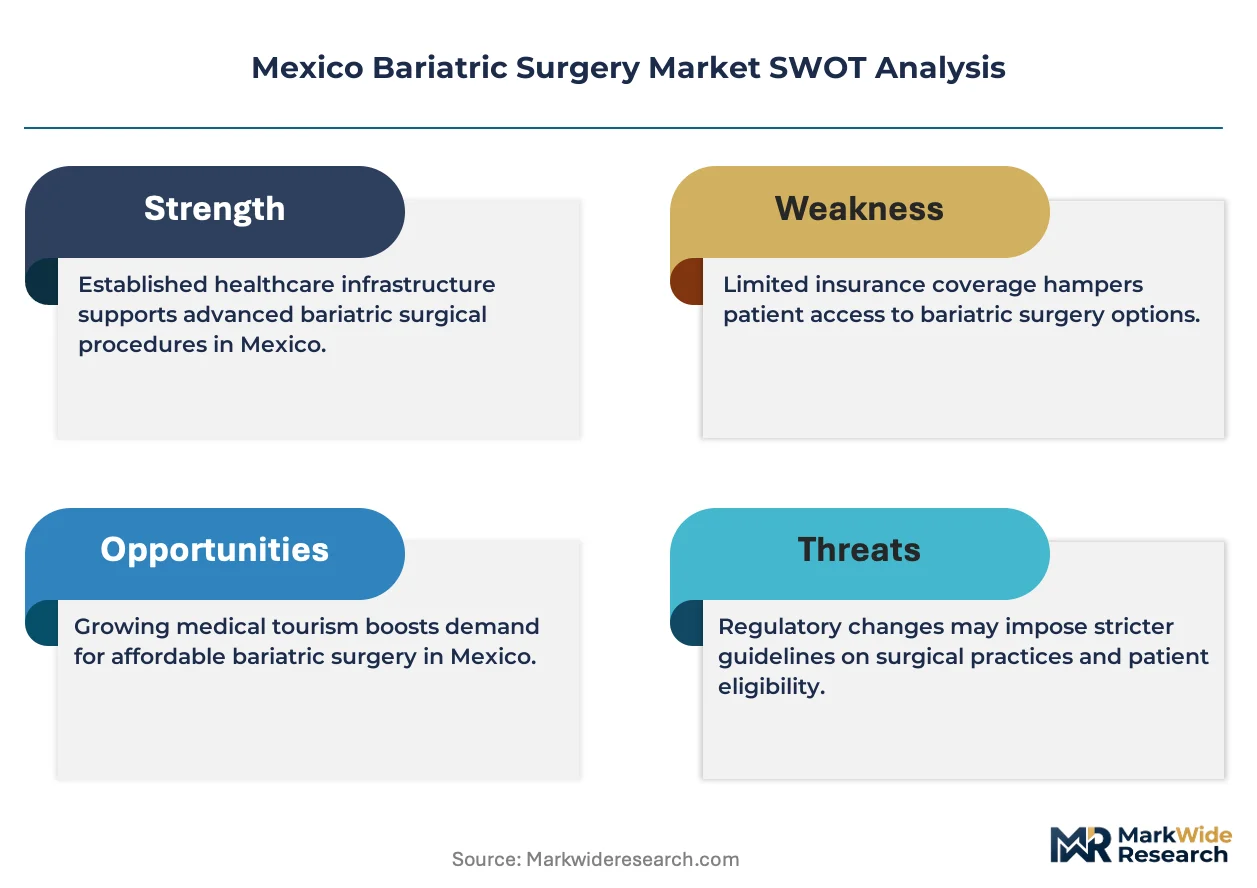
COFEPRIS medical device registration requirements and NOM-005-SSA3-2010 standards for surgical care shape product commercialization timelines and facility accreditation thresholds. Mexico's General Health Law provisions and IMSS coverage policies for metabolic surgery determine reimbursement access and patient eligibility criteria across care settings. Stakeholders must monitor regulatory harmonization between Mexican standards and FDA-EMA convergence pathways to anticipate import licensing shifts.
Market Dynamics
Medical tourism flows from the United States and Canada are compressing patient acquisition timelines for Mexican bariatric centers, forcing rapid capacity expansion in Jalisco and Nuevo León surgical corridors while COFEPRIS registration bottlenecks constrain equipment import velocity.
Growth Catalysts
- COFEPRIS-FDA Harmonization Pathways:Accelerated review timelines for pre-approved devices reduce commercialization lag for laparoscopic staplers and energy platforms entering through Nuevo León distribution hubs.
- IMSS Metabolic Surgery Coverage Expansion:Public reimbursement for sleeve gastrectomy procedures extends addressable patient pools beyond private-pay medical tourists into Mexico's insured population segments.
- Robotic-Assisted Surgical Platforms:da Vinci system placements in Guadalajara and Mexico City hospitals enable premium procedure pricing and attract complex revision cases from North American referral networks.
Market Restraints
- Single-Source Stapler Cartridge Supply:Concentrated manufacturing in US Midwest distribution centers creates vulnerability to cross-border logistics disruptions affecting Tijuana and Monterrey surgical schedules.
- COFEPRIS Import Licensing Backlogs:Extended review periods for Class III device registrations delay revenue recognition for European and Asian equipment manufacturers seeking Mexican market entry.
- Gastric Balloon Substitution:Non-surgical intragastric devices capture price-sensitive patients in Mexico City outpatient clinics, diverting volume from permanent surgical interventions.
Strategic Opportunities
- Querétaro-Ambulatory Expansion:Underserved metropolitan zones between Mexico City and Guadalajara present greenfield clinic development potential with lower facility costs than saturated primary markets.
- NOM-005-SSA3-2010 Accreditation Arbitrage:Specialized certification for bariatric centers creates differentiation premiums for facilities achieving compliance ahead of mandatory enforcement timelines.
- Telemedicine-Enabled Preoperative Screening:Remote patient evaluation protocols collapse geographic barriers for rural Mexican patients and international referrals, extending catchment areas beyond traditional drive-time radii.
Industry Challenges
- Robotic Surgery Technician Scarcity:Limited training pipeline for da Vinci system operators constrains utilization rates and extends surgeon onboarding timelines in newly equipped facilities.
- Revision Surgery Complexity Migration:Failed primary procedures from unaccredited clinics concentrate in tertiary hospitals, consuming OR block time and compressing margins on technically demanding cases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Bariatric Surgery Market |
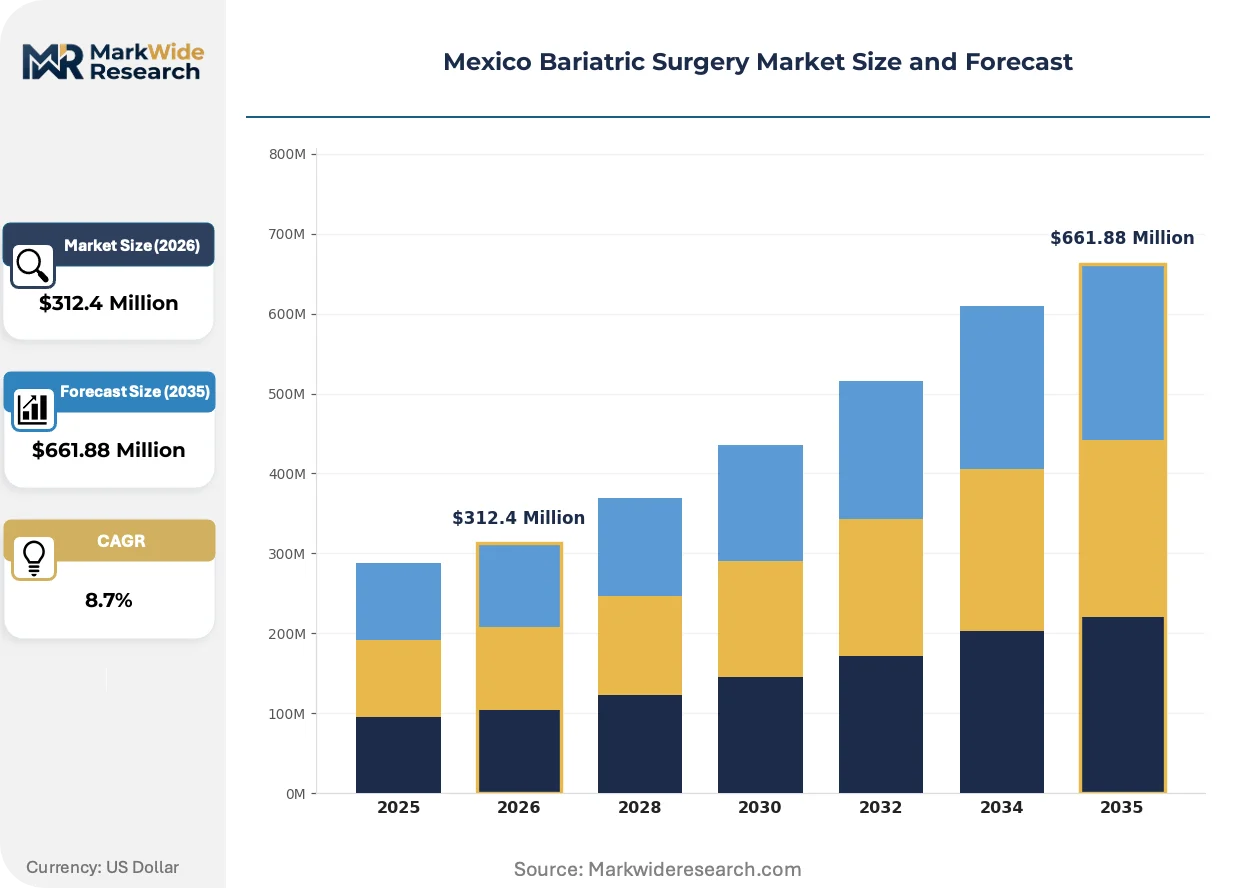
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Band, Biliopancreatic Diversion Patient Demographics: Adults, Adolescents, Seniors, Obese Patients Care Setting: Hospitals, Specialized Clinics, Outpatient Facilities, Surgery Centers Insurance Type: Private Insurance, Government Programs, Self-Pay, Corporate Health Plans |
| Companies Covered | Medtronic PLC, Intuitive Surgical Inc, Johnson & Johnson, ConMed Corporation, Boston Scientific Corporation, Olympus Corporation, B Braun SE, Mexico Bariatric Center, Pompeii Surgical Center, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Bariatric Surgery Market Shifts & Advancements
Digital preoperative workflows and single-use instrument platforms are compressing traditional equipment sterilization dependencies while reshaping capital allocation patterns across Mexican surgical facilities.
Single-use laparoscopic trocars and energy devices are collapsing reprocessing infrastructure requirements for ambulatory bariatric centers in Jalisco. Facilities adopting disposable platforms eliminate autoclave capital expenditure and reduce infection control liability. This shift is collapsing the historical advantage of hospital-scale sterilization departments over specialized clinics.
COFEPRIS alignment with FDA-EMA convergence pathways for medical device registration is accelerating review standardization for imported surgical equipment. Manufacturers submitting prior FDA approvals receive expedited Mexican market entry. Class III implantable devices face the steepest compliance escalation, with Nuevo León-based distributors absorbing documentation preparation costs to secure exclusive territorial agreements.
Direct-to-patient digital marketing channels are displacing traditional medical tourism broker intermediaries for bariatric procedure acquisition. Guadalajara and Tijuana clinics now capture 60-70 percent of international patient inquiries through proprietary booking platforms rather than third-party aggregators. This disintermediation compresses patient acquisition costs but intensifies price transparency and reputation management requirements for individual surgical centers.
Mexico Bariatric Surgery Market Segmentation
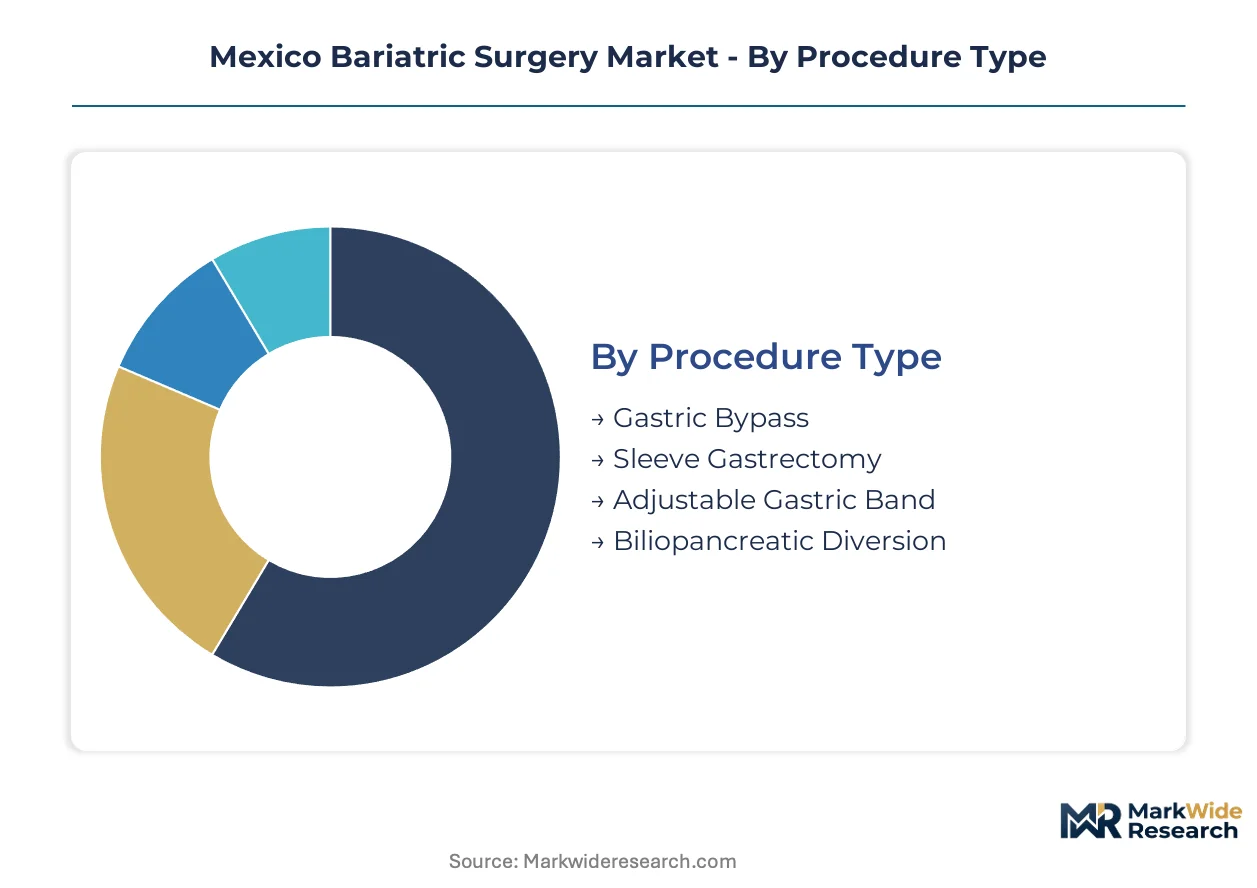
Procedure mix and care setting configurations determine capital deployment patterns across Mexican bariatric centers. Patient payment source and demographic targeting shape facility location decisions and equipment procurement priorities.
Procedure Type:
Sleeve gastrectomy compresses surgical cycle times to under 90 minutes, while complex diversion procedures consume extended OR blocks and recovery windows.
- Gastric Bypass:Roux-en-Y reconstruction creates malabsorptive-restrictive dual mechanism requiring advanced stapling platforms and longer anesthesia support. Demand clusters in Mexico City tertiary hospitals managing diabetic comorbidity cases from IMSS referral networks.
- Sleeve Gastrectomy:Vertical gastric resection along the greater curvature eliminates intestinal rerouting, reducing technical complexity and postoperative monitoring requirements. Jalisco and Nuevo León ambulatory centers capture volume through streamlined same-day discharge protocols for medical tourists.
- Adjustable Gastric Band:Silicone band placement with subcutaneous port access enables reversible restriction without permanent anatomical alteration.
- Biliopancreatic Diversion:Duodenal switch variant commands premium pricing for super-obese BMI cohorts requiring maximum metabolic impact.
Sleeve gastrectomy dominates installed base. Gastric bypass is where expansion concentrates.
Patient Demographics:
Cost tiers stratify sharply across age cohorts, with adolescent cases requiring specialized anesthesia protocols and extended follow-up infrastructure.
- Adults:Prime working-age patients aged 18-64 constitute the volume core, presenting with metabolic syndrome clusters that drive insurance preauthorization complexity. Mexico City private hospitals prioritize this segment through employer-sponsored corporate health plan contracts.
- Adolescents:Patients under 18 require pediatric surgical credentialing and multidisciplinary team involvement including endocrinology and psychology. Guadalajara academic medical centers concentrate this high-complexity, lower-volume segment.
- Seniors:Patients over 65 present elevated perioperative risk profiles demanding cardiac clearance and intensified monitoring.
- Obese Patients:BMI stratification above 35 kg/m² determines procedure eligibility under IMSS coverage guidelines and international accreditation standards.
Adults dominate installed base. Adolescents are where expansion concentrates.
Care Setting:
Margin structures vary dramatically across facility types, with specialized clinics capturing efficiency premiums through focused procedure standardization.
- Hospitals:Full-service acute care facilities manage complex revision cases, emergency conversion capabilities, and IMSS-insured patient populations requiring extended length-of-stay. Monterrey tertiary centers anchor this segment through integrated ICU and interventional radiology support.
- Specialized Clinics:Dedicated bariatric facilities achieve throughput optimization through standardized pathways and dedicated nursing teams. Tijuana and Guadalajara clusters lead this segment with NOM-005-SSA3-2010 accreditation driving differentiation.
- Outpatient Facilities:Standalone procedural suites without overnight capability target selected low-risk sleeve gastrectomy candidates.
- Surgery Centers:Multi-specialty ambulatory platforms integrate bariatric services alongside orthopedic and ophthalmology procedures.
Hospitals dominate installed base. Specialized clinics are where expansion concentrates.
Insurance Type:
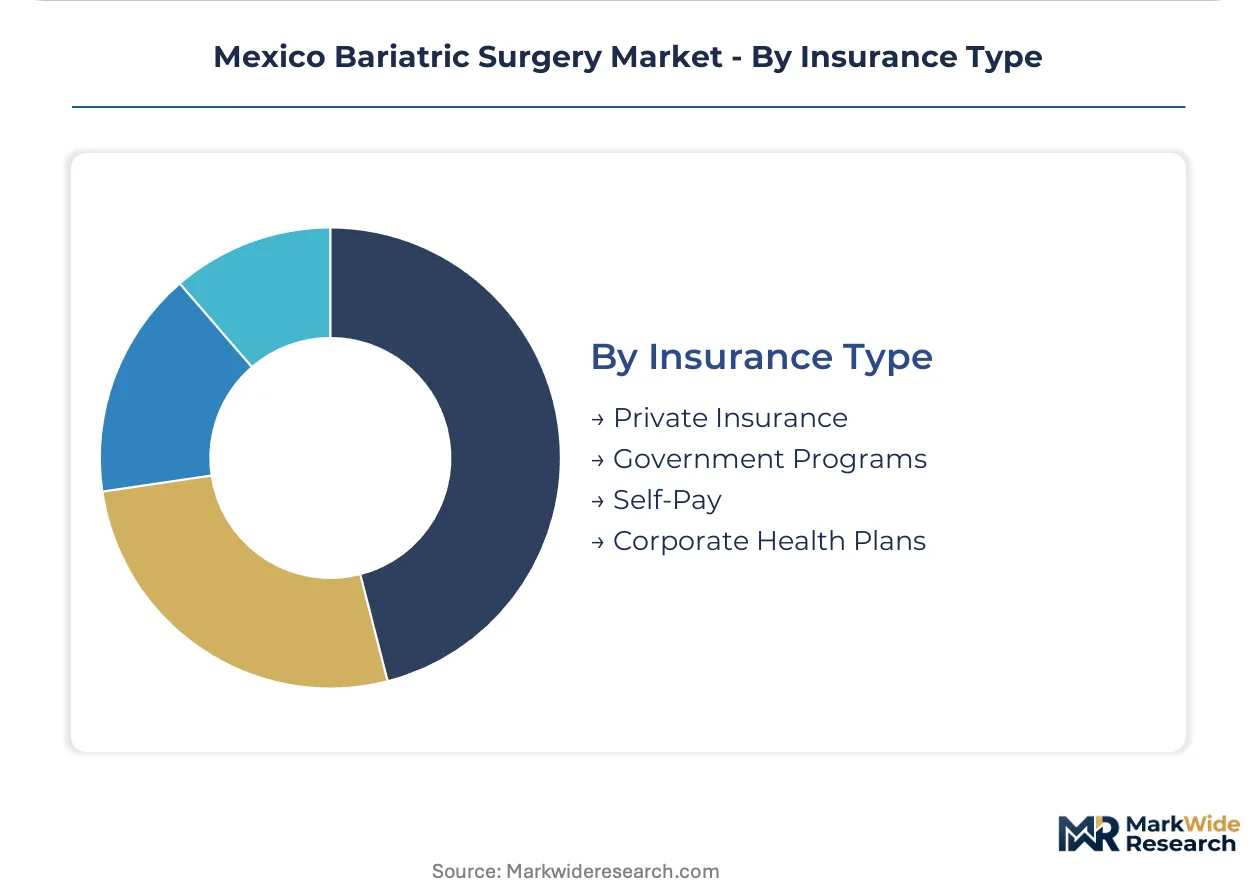
Customer payment source determines pricing power and collection risk, with self-pay medical tourists offering immediate cash conversion versus government program reimbursement delays.
- Private Insurance:Commercial carriers including GNP, MetLife México, and AXA Seguros cover sleeve gastrectomy and bypass procedures with preauthorization requirements and network restrictions. Mexico City hospital chains negotiate preferred provider arrangements with concentrated employer groups.
- Government Programs:IMSS and ISSSTE coverage expansion extends access to insured formal sector workers, though facility accreditation requirements limit eligible provider networks. COFEPRIS-registered centers in Jalisco and Nuevo León capture this growing volume.
- Self-Pay:Direct patient payment from US and Canadian medical tourists enables transparent package pricing without intermediary delays.
- Corporate Health Plans:Employer-sponsored wellness initiatives target obesity reduction through surgical benefit carve-outs.
Self-pay dominates installed base. Government programs are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mexico City-Querétaro-Guadalajara highway corridor anchors patient mobility for bariatric surgical services across central Mexico. This infrastructure backbone enables same-day travel for medical tourists and domestic referrals alike.
Mexico City Metro
Private hospital chains anchor device procurement volume through centralized purchasing agreements with multinational suppliers. COFEPRIS headquarters proximity accelerates regulatory filing turnaround for new laparoscopic equipment registrations. Tertiary centers in Polanco and Santa Fe concentrate complex revision cases requiring robotic-assisted platforms.
Nuevo León
Monterrey's integrated healthcare campuses drive adoption of advanced stapling systems among high-volume bariatric programs. IMSS regional offices coordinate coverage expansion for metabolic surgery among formal sector workers. San Pedro Garza García surgical corridors attract cross-border patients from Texas through dedicated medical tourism infrastructure.
Jalisco
Guadalajara's ambulatory surgery clusters achieve throughput optimization through standardized sleeve gastrectomy pathways. NOM-005-SSA3-2010 accreditation requirements differentiate certified facilities in Zapopan and Tlajomulco. Puerto Vallarta satellite clinics extend reach into Pacific coast medical tourism flows.
Bajío Region
Querétaro and León present greenfield development potential with lower facility costs than saturated primary markets. State health secretariats negotiate preferred provider arrangements with emerging bariatric centers. Industrial corridor demographics generate growing insured patient pools for employer-sponsored surgical benefits.
Northern Border States
Tijuana and Mexicali surgical centers capture price-sensitive US patients through transparent package pricing models. Cross-border logistics infrastructure determines stapler cartridge supply security for high-frequency programs. Baja California health regulators enforce COFEPRIS compliance standards for international accreditation maintenance.
Mexico Bariatric Surgery Market Competitive Landscape
On the supply side, the industry is consolidating around multinational device manufacturers with established distributor networks and specialized clinic operators with regional brand recognition. Hospital procurement centralization favors suppliers with broad surgical portfolios capable of serving integrated delivery networks. Two strategic archetypes dominate: diversified medical technology conglomerates leveraging cross-selling synergies, and focused bariatric service providers building destination reputations. Competitive dynamics center on exclusive territorial distribution agreements and NOM-005-SSA3-2010 accreditation timing.
Among diversified technology suppliers, Medtronic PLC, Johnson & Johnson, and Intuitive Surgical Inc anchor the equipment and implant segments. These entities exemplify scale-driven archetypes with consolidated purchasing power across Mexican private hospital networks. Specialized clinic operators including Mexico Bariatric Center and Pompeii Surgical Center occupy positions within the service-delivery tier, building direct-to-patient channels that displace traditional medical tourism intermediaries. The competitive interface between device suppliers and facility operators increasingly determines market access velocity.
| Leading Market Players |
|---|
| Medtronic PLC |
| Intuitive Surgical Inc |
| Johnson & Johnson |
| ConMed Corporation |
| Boston Scientific Corporation |
| Olympus Corporation |
| B Braun SE |
| Mexico Bariatric Center |
| Pompeii Surgical Center |
| Others |
Supply & Pricing Matrix
Nuevo León distribution hubs concentrate laparoscopic stapler and energy platform inventory, translating equipment scarcity into pricing leverage for accredited bariatric centers. COFEPRIS registration bottlenecks at these chokepoints amplify procurement premiums for Class III devices while compressing margins for facilities without established distributor relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by NOM-005-SSA3-2010 accreditation status and robotic platform availability. Premium tiers capture da Vinci-equipped hospitals in Mexico City and Monterrey, while economy segments cluster at Tijuana border clinics competing on transparent package rates. Price differentiation rests on FDA-approval pedigree and after-sales technical support bundling. Cost compression in the economy tier is intensifying because gastric balloon substitutes divert price-sensitive volume. Self-pay medical tourists exhibit lowest price sensitivity; IMSS-reimbursed cases face strict preauthorization ceilings.
Supply Chain Analysis
US export controls on advanced surgical robotics constrain da Vinci system flow velocity into Mexican tertiary hospitals. Device manufacturing concentrates in the United States, Ireland, and Costa Rica, with stapler cartridge production anchored in Midwest US distribution centers. Raw material dependencies span medical-grade titanium, biocompatible polymers, and precision-milled tungsten carbide cutting surfaces. Single-source vulnerability pervades the stapler cartridge segment, where cross-border logistics disruptions cascade into OR block cancellations. Distribution runs through COFEPRIS-authorized Nuevo León distributors holding exclusive territorial agreements with multinational manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat. COFEPRIS accreditation timelines and NOM-005-SSA3-2010 certification requirements create structural switching costs that protect incumbent positions against unqualified competitors.
For Market Incumbents: Pre-empt accreditation arbitrage by accelerating NOM-005-SSA3-2010 compliance ahead of mandatory enforcement timelines. Secure exclusive stapler cartridge supply contracts with US Midwest distribution centers to neutralize cross-border logistics vulnerability. Backward integration into single-use instrument platforms eliminates sterilization capital expenditure and collapses the historical hospital-scale advantage over ambulatory competitors.
For New Entrants and Emerging Players: Establish a beachhead in Querétaro-Ambulatory corridor expansion zones where facility costs undercut saturated Mexico City and Guadalajara markets. Target government program reimbursement expansion as the most penetrable payment source, leveraging IMSS metabolic surgery coverage growth. Deploy telemedicine-enabled preoperative screening as the primary go-to-market angle to collapse geographic barriers for rural Mexican patients.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialized clinic operators with NOM-005-SSA3-2010 accreditation and direct-to-patient digital channels command premium multiples against hospital-dependent competitors. Acquisition targets should display robotic surgery platform utilization rates above corridor averages and proprietary booking platform traffic. Watch COFEPRIS-FDA harmonization pathway velocity as the critical inflection signal for equipment import licensing acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Expedited Registration Pathway | Prior FDA approvals accelerate Mexican market entry for laparoscopic staplers through Nuevo León hubs. |
| NOM-005-SSA3-2010 Accreditation Investment | Specialized certification creates differentiation premiums ahead of mandatory enforcement timelines. |
| Robotic Surgery Technician Training Pipeline | da Vinci operator scarcity constrains utilization rates in newly equipped Guadalajara facilities. |
| Direct-to-Patient Digital Platform Development | Proprietary booking systems displace medical tourism intermediaries and compress acquisition costs. |
| Single-Use Instrument Platform Adoption | Disposable trocars eliminate autoclave capital expenditure for Jalisco ambulatory centers. |
Research Methodology
A standing panel of bariatric surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation from COFEPRIS registration databases, IMSS coverage policy filings, hospital procurement records, and medical tourism platform analytics. Bottom-up procedure volume modeling and top-down device shipment triangulation anchored market sizing.
Scenario-bracketing framed the analytical framework across the projection horizon, with base, optimistic, and conservative cases reflecting COFEPRIS processing velocity and IMSS reimbursement expansion trajectories. Segmentation dimensions modeled include procedure type, care setting, patient payment source, and geographic surgical corridor. CAGRs derived from fitted trend extrapolation against historical procedure growth patterns, incorporating robotic platform placement rates and medical tourism inquiry volume as industry-specific inputs.
Stress conditions across COFEPRIS licensing backlogs, cross-border logistics disruptions, and gastric balloon substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization timing and IMSS budget allocation priorities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
UAE Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
Japan Bariatric Surgery Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
Bariatric Rollator Walkers Market
Bariatric Surgery
Brazil Bariatric Surgery Market
Bariatric Surgery
Chile Bariatric Surgery Market