
 Japan Bariatric Surgery Market | 2026-2036
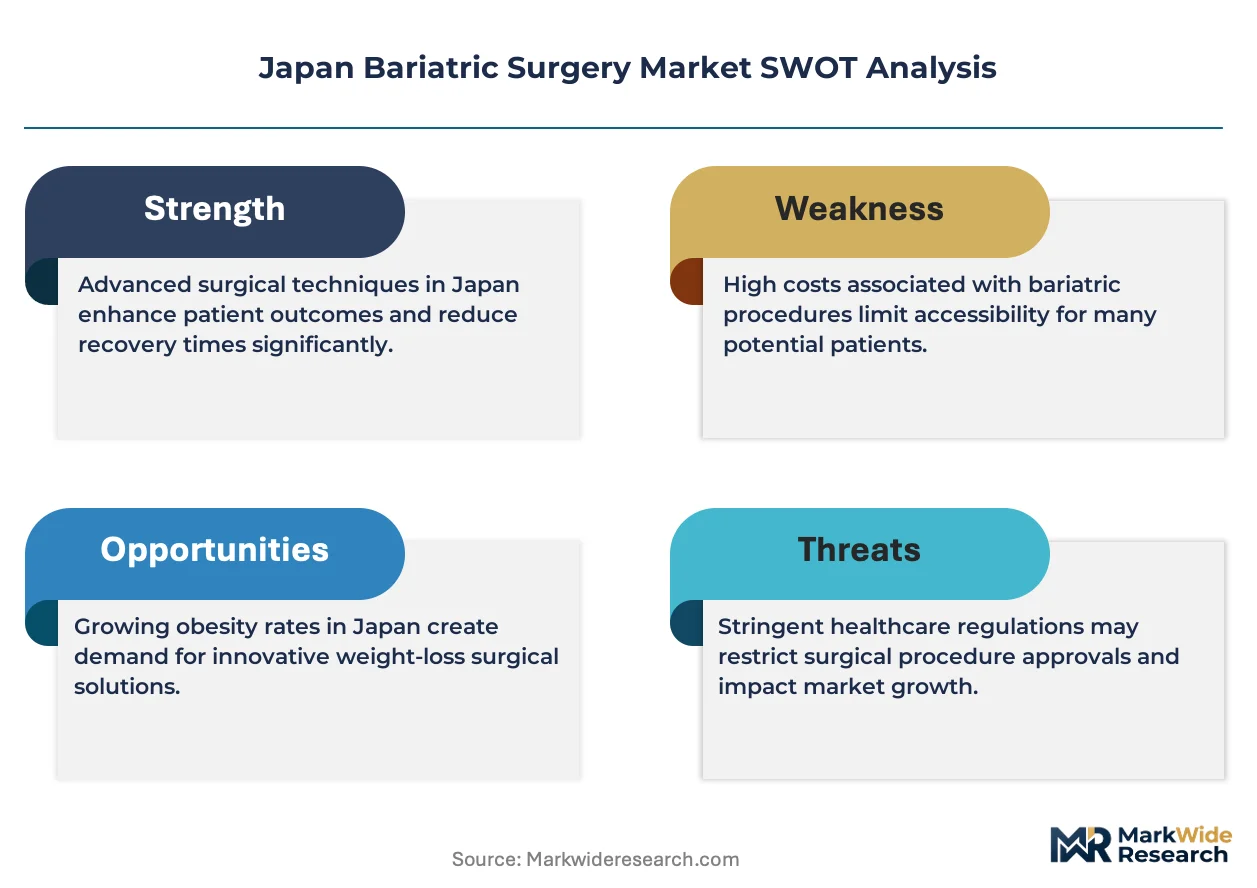
Japan Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Bariatric Surgery Market Foresight
Buyer concentration among Japan's hospital networks is restructuring access patterns for bariatric device procurement. Johnson & Johnson leverages its broad surgical portfolio to sustain relationships with major university hospitals. Medtronic PLC anchors its position through energy device specialization in minimally invasive metabolic procedures. Olympus Corporation competes on integrated visualization systems that support laparoscopic sleeve gastrectomy workflows.
Bariatric surgery encompasses restrictive and malabsorptive procedures that alter gastrointestinal anatomy to achieve sustained weight reduction, typically requiring stapling devices calibrated to tissue thickness parameters between 1.0 and 2.5 mm. Sleeve gastrectomy now dominates procedure volumes while gastric bypass retains preference for patients with severe gastroesophageal reflux disease. Surgical staplers command the largest device margin pool, though intragastric balloons are gaining traction in outpatient clinic settings. Energy devices differentiate vendors through vessel-sealing reliability in high-BMI patients.
PMDA device approval pathways and MHLW reimbursement listings shape market access timelines for novel bariatric technologies in Japan. METI industrial standards for medical device manufacturing influence domestic production decisions and import substitution strategies. Stakeholders must monitor how PMDA's evolving software-as-medical-device framework applies to robotic-assisted bariatric platforms.
Market Dynamics
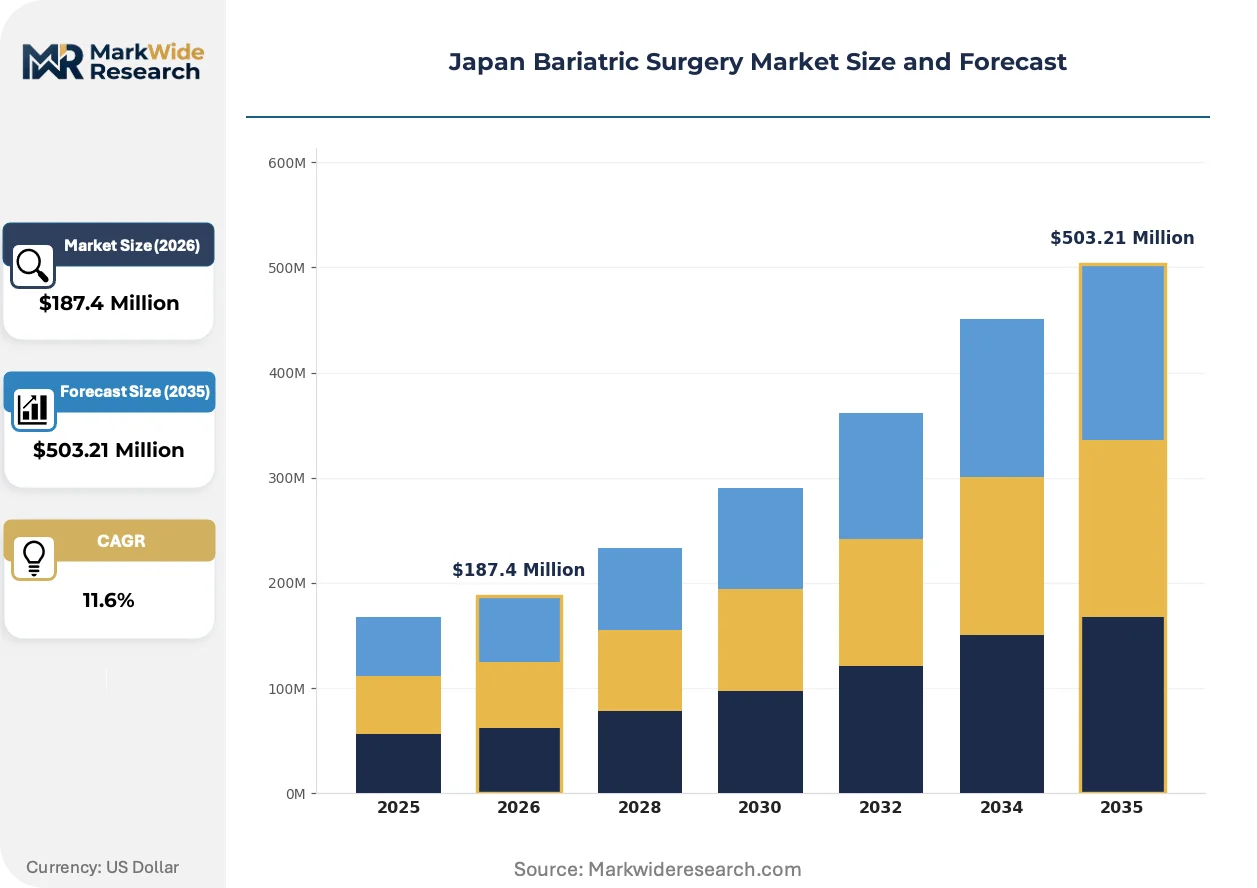
Japan's bariatric surgery sector is restructuring around MHLW reimbursement revisions that now authorize metabolic procedures for type 2 diabetes patients, converting previously elective interventions into covered treatments and expanding addressable procedure volumes across university hospital networks.
Growth Catalysts
- Type 2 diabetes comorbidity coverage:MHLW reimbursement policy revisions have reclassified sleeve gastrectomy as a covered intervention for diabetic patients, eliminating out-of-pocket cost barriers that previously constrained demand.
- Tokyo-Osaka hospital network expansion:Major metropolitan medical centers are establishing dedicated metabolic surgery departments with specialized bariatric surgical teams and integrated care pathways.
- Laparoscopic technique maturation:Minimally invasive approaches now dominate procedure volumes, reducing recovery timelines and enabling same-day discharge protocols that expand hospital throughput capacity.
Market Restraints
- PMDA device approval timelines:Novel bariatric technologies face extended premarket review cycles that delay commercialization of next-generation stapling systems and robotic platforms by domestic and foreign manufacturers alike.
- Specialized surgeon scarcity:Japan's limited fellowship-trained bariatric surgeons concentrate in designated academic medical centers, creating procedural bottlenecks outside major urban corridors.
- Cultural weight stigma:Persistent social attitudes toward obesity treatment limit patient self-referral rates and delay surgical consultation until comorbidities advance to severe stages.
Strategic Opportunities
- Kansai region penetration:Osaka, Kyoto, and Kobe metropolitan areas present underdeveloped bariatric capacity relative to Tokyo, offering first-mover advantages for device vendors establishing distribution partnerships.
- Outpatient intragastric balloon clinics:Ambulatory endoscopy centers are adopting non-surgical weight management devices, creating alternative revenue streams outside traditional hospital procurement channels.
- METI medical device manufacturing incentives:Industrial policy supports domestic production of surgical staplers and energy devices, reducing import dependency and shortening supply lead times for Japanese hospital networks.
Industry Challenges
- Robotic platform integration complexity:University hospitals face substantial capital expenditure requirements and surgeon retraining demands when adopting computer-assisted surgical systems for metabolic procedures.
- Software-as-medical-device classification uncertainty:PMDA's evolving regulatory framework for AI-enabled surgical planning tools creates compliance timeline unpredictability for vendors developing next-generation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Bariatric Surgery Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Banding, Biliopancreatic Diversion Device Type: Intragastric Balloon, Gastric Band, Surgical Stapler, Energy Devices Patient Demographics: Adults, Adolescents, Seniors, Morbidly Obese End User: Hospitals, Clinics, Ambulatory Surgery Centers, Research Institutes |
| Companies Covered | Johnson & Johnson, Medtronic PLC, Intuitive Surgical, Olympus Corporation, EndoGastric Solutions Inc., GI Dynamics, ReShape Lifesciences Inc., TransEnterix, USGI Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Bariatric Surgery Market Shifts & Advancements
Japan's bariatric surgery landscape is converging around minimally invasive technique refinement, reimbursement-driven care model transformation, and procurement centralization within integrated hospital networks.
Robotic-assisted surgical platforms are absorbing capital investment priority from Tokyo's university hospitals seeking competitive differentiation through precision suturing capabilities and reduced operative variability. Kobe City Medical Center General Hospital and Osaka University Hospital have initiated da Vinci system deployments for complex revisional bariatric cases. This technology concentration is compressing manual laparoscopy margins at premium-tier institutions while community hospitals retain conventional instrumentation.
MHLW's 2024 reimbursement fee schedule revision introduced distinct procedure codes for metabolic surgery performed on diabetic patients, creating structural separation from cosmetic weight-loss interventions. The industrial consequence channels funding toward evidence-based comorbidity treatment and away from discretionary bariatric services. Kanto region hospitals have responded by reorganizing surgical departments around diabetes-centered care pathways rather than standalone obesity clinics.
Consolidated procurement within Japan's emerging hospital network alliances is displacing fragmented device purchasing across individual surgical departments. Tokyo Medical and Dental University Hospital alliance members now coordinate bariatric device tenders through centralized supply committees, compressing vendor negotiation cycles and standardizing instrumentation platforms across affiliated facilities. This behavioral shift is most visible in the University of Tokyo Hospital network's recent multi-year stapler supply agreements.
Japan Bariatric Surgery Market Segmentation
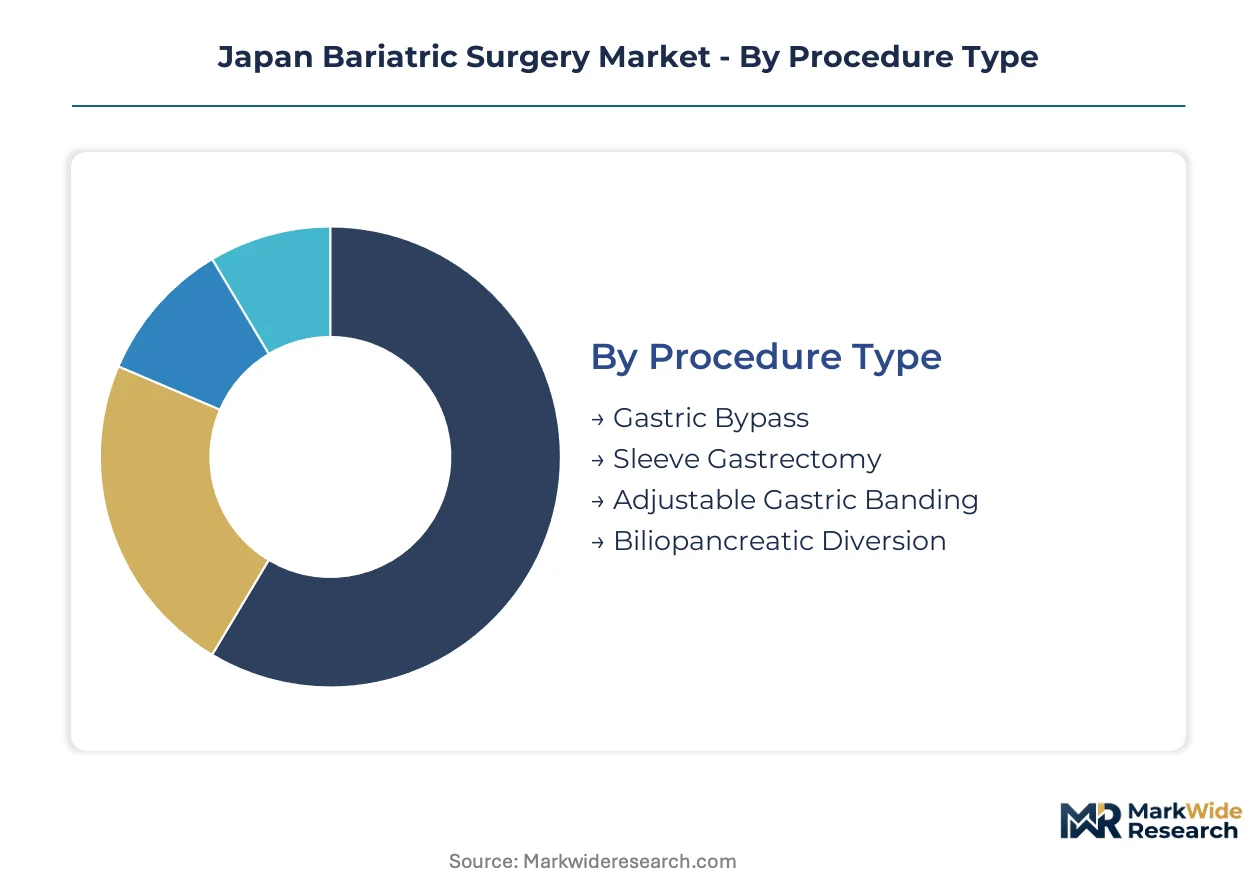
Japan's bariatric surgery market segments around reimbursement eligibility, surgical technique preference, and institutional procurement capacity. Understanding these divisions reveals where MHLW policy revisions and hospital network expansion are redirecting device demand and procedure volumes.
Procedure Type:
Surgical technique selection in Japan hinges on comorbidity profile and MHLW reimbursement classification, with metabolic indication coverage reshaping volume distribution across university hospitals.
- Sleeve Gastrectomy:This procedure removes approximately 80% of the stomach along the greater curvature, creating a tubular gastric remnant with preserved pyloric function. Tokyo Medical and Dental University Hospital and Osaka University Hospital have prioritized sleeve gastrectomy capacity expansion following MHLW's metabolic surgery reimbursement authorization, converting type 2 diabetes patients from pharmaceutical management to surgical intervention.
- Gastric Bypass:Roux-en-Y gastric bypass constructs a small gastric pouch with Roux limb reconstruction, achieving both restriction and malabsorption. Kobe City Medical Center General Hospital retains preference for this technique in patients with severe gastroesophageal reflux disease, where sleeve gastrectomy risks symptom exacerbation.
- Adjustable Gastric Banding:This purely restrictive approach employs an inflatable silicone band around the gastric cardia; declining utilization in Japan reflects MHLW reimbursement exclusion and long-term complication rates requiring band removal.
- Biliopancreatic Diversion:This malabsorptive-dominant procedure with duodenal switch modification achieves superior weight loss but demands intensive nutritional monitoring; limited to specialized metabolic surgery centers with dedicated bariatric nutrition teams.
Mature deployment sits with gastric bypass. Newer deployment is concentrated in sleeve gastrectomy.
Device Type:
Device procurement patterns in Japan follow hospital tier stratification, with university hospitals absorbing capital-intensive platforms while community facilities standardize on disposable instrumentation.
- Surgical Stapler:These devices deploy calibrated titanium staples in linear or circular configurations, with tissue thickness sensing between 1.0 and 2.5 mm determining staple height selection. University of Tokyo Hospital network's centralized procurement has compressed vendor margins through multi-year supply agreements, favoring manufacturers with integrated energy-sealing capabilities.
- Energy Devices:Advanced bipolar and ultrasonic systems achieve vessel sealing in high-BMI patients with reduced thermal spread. Medtronic PLC's specialized portfolio anchors procurement at designated metabolic surgery centers where vessel reliability directly impacts operative safety metrics.
- Intragastric Balloon:Endoscopically placed saline-filled or gas-filled spheres occupy gastric volume for temporary weight reduction; ambulatory endoscopy centers in Osaka and Kobe are adopting these devices for outpatient weight management outside MHLW reimbursement pathways.
- Gastric Band:Adjustable silicone bands with subcutaneous port systems for saline inflation; negligible current demand in Japan following procedure volume collapse and MHLW delisting from reimbursement schedules.
Stapler standardization dominates hospital procurement. Balloon deployment is climbing fastest in ambulatory settings.
Patient Demographics:
Patient segmentation in Japan reflects BMI thresholds for MHLW reimbursement eligibility and age-specific surgical risk stratification protocols at designated metabolic surgery centers.
- Adults:Patients aged 18-64 with BMI exceeding 35 kg/m² or BMI exceeding 30 kg/m² with type 2 diabetes constitute the primary reimbursed population; Kanto region hospitals have reorganized care pathways around this demographic following MHLW's metabolic surgery authorization.
- Morbidly Obese:Patients with BMI exceeding 40 kg/m² require specialized anesthesia protocols and extended monitoring; concentrated at Tokyo and Osaka academic medical centers with dedicated bariatric surgical teams and ICU capacity.
- Seniors:Patients over 65 face selective surgical candidacy based on cardiovascular risk assessment; limited procedure volumes reflect conservative patient selection and comorbidity burden.
- Adolescents:Patients under 18 with severe obesity and metabolic syndrome; minimal surgical intervention in Japan due to growth concerns and limited long-term outcome data supporting MHLW reimbursement expansion.
Adult metabolic indication patients anchor procedure volumes. Morbidly obese patients represent the steepest expansion trajectory as referral pathways mature.
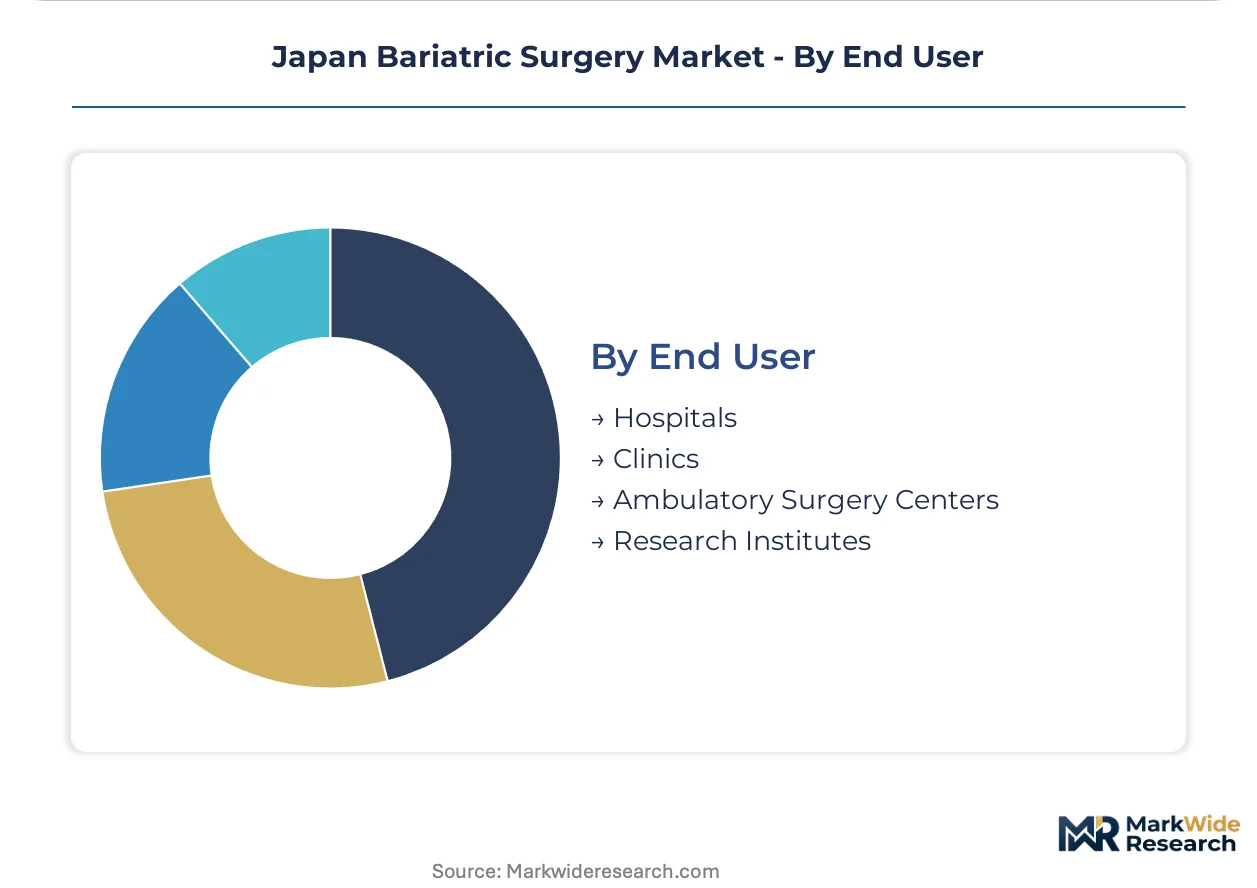
End User:
Institutional capacity for bariatric surgery in Japan concentrates in metropolitan hospital networks, with reimbursement authorization and surgeon availability determining where procedures occur.
- Hospitals:University hospitals and designated medical centers with fellowship-trained bariatric surgeons perform the majority of metabolic procedures; Tokyo-Osaka corridor institutions account for disproportionate volume given surgeon concentration and MHLW reimbursement facility designation.
- Ambulatory Surgery Centers:Freestanding surgical facilities with laparoscopic capability; limited bariatric procedure authorization in Japan due to anesthesia requirements and overnight observation protocols for metabolic surgery patients.
- Clinics:Outpatient endoscopy centers manage intragastric balloon placement and removal; Kansai region penetration lags Tokyo, offering expansion opportunity for device vendors establishing distribution partnerships.
- Research Institutes:Academic research hospitals conduct clinical trials for novel bariatric technologies; PMDA device approval pathways channel premarket evaluation through these institutions, delaying commercialization timelines.
Hospital networks control metabolic surgery volume. Clinic-based balloon services are gaining share fastest outside traditional procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metabolic surgery demand in Japan concentrates in the Tokyo-Osaka corridor, where MHLW reimbursement authorization and specialized surgeon availability have established dominant treatment capacity. Regional expansion now targets underpenetrated metropolitan zones with emerging hospital network infrastructure.
Kanto/Tokyo
University hospitals in Tokyo anchor Japan's bariatric procedure volume through diabetes-centered care pathways activated by MHLW's metabolic surgery reimbursement revision. PMDA device approval pathways channel novel stapling systems and robotic platforms through Tokyo Medical and Dental University Hospital and University of Tokyo Hospital network for premarket evaluation. The Tokyo Medical and Dental University Hospital alliance coordinates centralized device procurement across affiliated facilities, compressing vendor margins through multi-year supply agreements.
Kansai/Osaka
Osaka University Hospital and Kobe City Medical Center General Hospital are establishing dedicated metabolic surgery departments with da Vinci system deployments for complex revisional cases. METI medical device manufacturing incentives support domestic production of surgical staplers in the Osaka-Kobe industrial zone, reducing import dependency for regional hospital networks. Kansai region penetration lags Tokyo in outpatient intragastric balloon services, offering first-mover advantages for device vendors establishing distribution partnerships with ambulatory endoscopy centers.
Chubu/Nagoya
Nagoya's academic medical centers are expanding fellowship-trained bariatric surgeon capacity to capture metabolic surgery referrals from surrounding prefectures. MHLW facility designation requirements for metabolic procedure reimbursement favor designated medical centers with ICU capacity and specialized anesthesia protocols. The Nagoya University Hospital network is reorganizing surgical departments around diabetes-centered care pathways rather than standalone obesity clinics.
Kyushu
Fukuoka's university hospitals face procedural bottlenecks due to limited fellowship-trained bariatric surgeon concentration outside major urban corridors. PMDA's evolving software-as-medical-device framework creates compliance timeline unpredictability for regional hospitals evaluating AI-enabled surgical planning tools. Kyushu University Hospital maintains selective bariatric surgical candidacy based on cardiovascular risk assessment for patients over 65.
Hokkaido
Sapporo's medical institutions experience delayed surgical consultation due to persistent cultural weight stigma limiting patient self-referral rates. MHLW reimbursement revisions have not yet penetrated Hokkaido's hospital networks to the same degree as metropolitan Japan, constraining addressable procedure volumes. Hokkaido University Hospital serves as the primary metabolic surgery referral center for northern Japan with dedicated bariatric nutrition teams for malabsorptive-dominant procedures.
Japan Bariatric Surgery Market Competitive Landscape
American producers anchor one tier of Japan's bariatric device market; Japanese specialists hold integrated visualization and domestic manufacturing positions. The vendor base structures around three tiers: diversified surgical conglomerates with broad hospital relationships, energy device specialists with metabolic procedure focus, and domestic manufacturers leveraging METI industrial incentives. Strategic moves concentrate on robotic platform integration partnerships and consolidated procurement negotiations with emerging hospital network alliances.
Within the diversified surgical conglomerate tier, Johnson & Johnson and Medtronic PLC exemplify positioning through relationship depth with major university hospitals and specialization in vessel-sealing reliability. Among Japan-based manufacturers, Olympus Corporation occupies a position anchored on integrated visualization systems that support laparoscopic sleeve gastrectomy workflows. Intuitive Surgical represents the robotic-assisted surgical platform archetype, with deployments initiated at Kobe City Medical Center General Hospital and Osaka University Hospital for complex revisional cases.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic PLC |
| Intuitive Surgical |
| Olympus Corporation |
| EndoGastric Solutions Inc. |
| GI Dynamics |
| ReShape Lifesciences Inc. |
| TransEnterix |
| USGI Medical |
| Others |
Supply & Pricing Matrix
University hospital network procurement committees anchor pricing power in Japan's bariatric device market, compressing vendor margins through multi-year stapler supply agreements that favor manufacturers bundling energy-sealing capabilities.
Pricing Analysis
High-volume disposable staplers generate thin margins while capital-intensive robotic platforms retain premium pricing. Three-tier pricing structure across premium, standard, and economy levels separates da Vinci system deployments from manual laparoscopy and basic instrumentation. Cost compression in standard disposable tiers is intensifying because consolidated procurement within Tokyo Medical and Dental University Hospital alliance standardizes vendor selection. Community hospitals exhibit highest price sensitivity; university hospitals prioritize vessel-sealing reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Osaka and Tokyo operate hub-and-spoke patterns for device fulfillment to metabolic surgery departments. Domestic manufacturing draws from METI industrial incentives in the Osaka-Kobe industrial zone, while titanium staple components and advanced bipolar systems rely on US and European sources. Single-source vulnerability concentrates in specialized energy device subassemblies. Distribution runs through authorized medical device distributors with PMDA import licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PMDA device approval timelines and MHLW reimbursement listing requirements create substantial compliance costs that protect established vendors with regulatory affairs infrastructure and hospital network relationships.
For Market Incumbents: Cement market position by deepening surgeon training partnerships at Osaka University Hospital and Kobe City Medical Center General Hospital to lock in robotic platform adoption. Pursue backward integration into titanium staple component production through METI manufacturing incentives, reducing exposure to overseas supply disruptions. The priority lever sits with preemptive compliance investment for PMDA's evolving software-as-medical-device framework. For New Entrants and Emerging Players: Launch via ambulatory endoscopy center distribution partnerships in the underpenetrated Kansai region, where outpatient intragastric balloon services lag Tokyo penetration. Target clinic-based weight management channels outside traditional hospital procurement committees, where purchasing decisions fragment across individual physicians. The most penetrable segment comprises non-reimbursed balloon procedures bypassing MHLW authorization requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic manufacturers with PMDA approval infrastructure and existing hospital network contracts in Japan's Chubu and Kyushu regions, where metabolic surgery capacity expansion lags the Tokyo-Osaka corridor. Long-term viability hinges on positioning for MHLW reimbursement expansion into adolescent bariatric indications. Watch for PMDA software-as-medical-device guidance finalization as inflection indicator for AI-enabled surgical planning platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Pre-market Approval Pathway | Accelerates commercialization timelines for next-generation stapling systems at designated evaluation hospitals. |
| MHLW Reimbursement Strategy | Converts elective procedures into covered treatments, expanding addressable volumes among diabetic patient populations. |
| Hospital System Partnership | Secures multi-year supply agreements through centralized procurement committees at Tokyo university networks. |
| Software Companion Development | Addresses PMDA's evolving software-as-medical-device framework for robotic-assisted surgical platforms. |
| Surgeon Training Program | Builds fellowship pipeline capacity to alleviate specialized bariatric surgeon scarcity outside metropolitan corridors. |
Research Methodology
Multi-period observation of MHLW reimbursement fee schedule revisions, PMDA device approval timelines, and hospital network procurement patterns anchored the trend analysis, supplemented by interviews with bariatric surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from PMDA regulatory filings, MHLW reimbursement databases, hospital procurement records, and METI industrial policy documents. Bottom-up procedure volume estimates triangulated against top-down device shipment data.
Segment-weighting across procedure type, device category, patient demographic, and end-user institutional tier structured the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical reimbursement authorization impacts on procedure volume expansion. Forecast inputs incorporated surgeon supply constraints, MHLW facility designation requirements, and PMDA review cycle duration assumptions.
Regulatory guidance delays, reimbursement policy reversals, and supply chain disruptions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding MHLW metabolic surgery authorization permanence and PMDA software classification stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market
Bariatric Surgery
France Bariatric Surgery Market
Bariatric Surgery
Spain Bariatric Surgery Market
Bariatric Surgery
Chile Bariatric Surgery Market
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Devices Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
China Bariatric Surgery Market