
 Driverless Taxi Market | 2026-2036
Driverless Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
Driverless Taxi Market Insights
Platform licensing revenue is narrowing relative to per-mile ride revenue as operators vertically integrate fleet ownership with software stacks. Waymo leverages its proprietary mapping and simulation infrastructure to sustain operational scale across multiple metropolitan zones. Baidu Apollo Go anchors its position through deep manufacturing partnerships and regulatory alignment with China's MIIT and SAMR frameworks.
A driverless taxi denotes a passenger vehicle operating without human intervention through sensor fusion, compute platforms, and machine-learning-based path planning, typically achieving SAE Level 4 or Level 5 autonomy through redundant lidar, radar, and camera arrays. The primary commercial purpose centers on replacing human drivers in urban point-to-point mobility to reduce labor costs and improve fleet utilization rates. Camera Systems and lidar configurations dominate current hardware stacks, while Shuttle Services within the Service Type dimension attract concentrated infrastructure investment from municipal buyers seeking fixed-route automation. Ride-Hailing retains the largest addressable pool, though margin capture remains constrained by insurance and remote-assistance overhead.
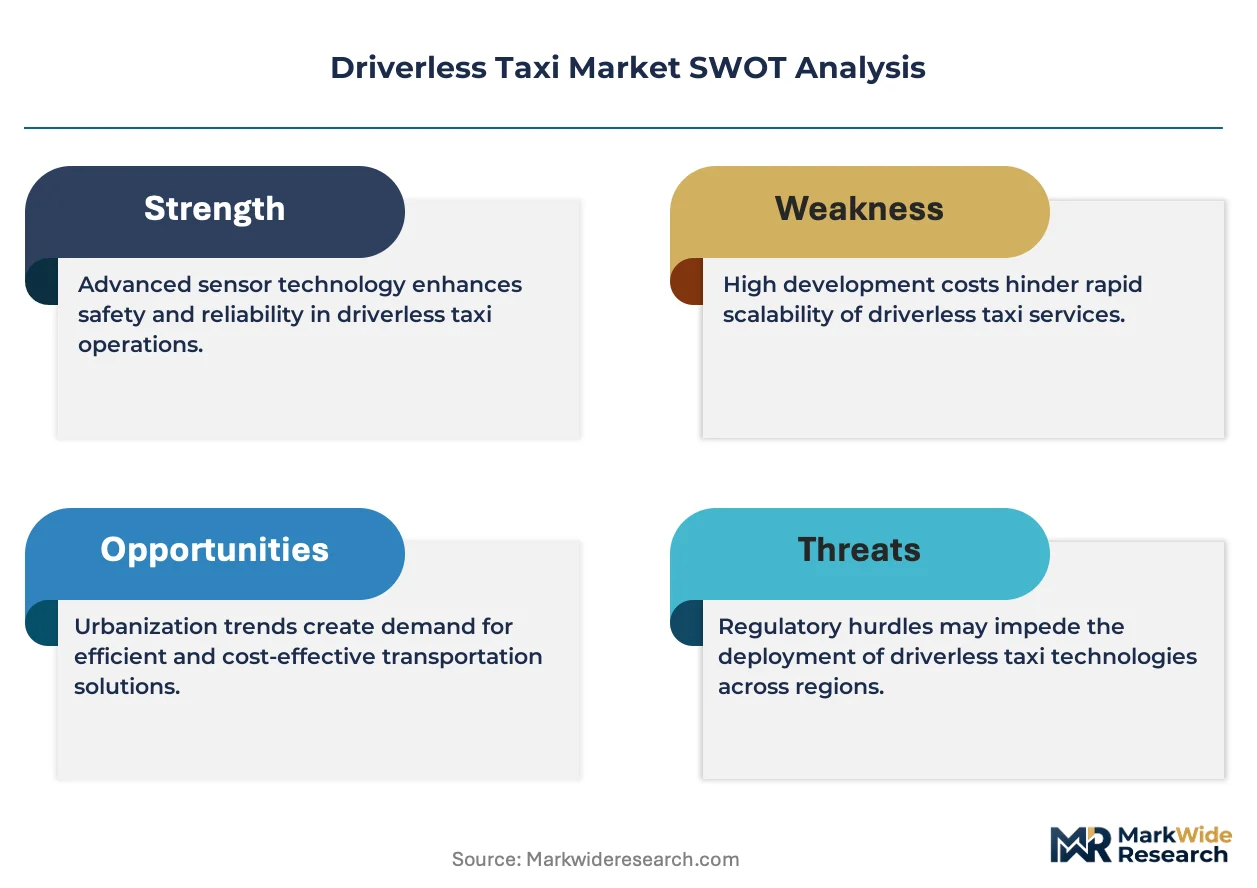
The NHTSA in the United States, the MIIT and SAMR in China, and the KBA in Germany each enforce divergent testing protocols and homologation standards that fragment vehicle certification pathways and delay cross-border fleet deployment. The EU AI Act and proposed MDR amendments for autonomous systems further complicate software validation requirements for any operator seeking European market access. Stakeholders must monitor which regulatory jurisdiction first harmonizes insurance liability with vehicle-type approval to determine where capital deployment achieves fastest commercial clearance.
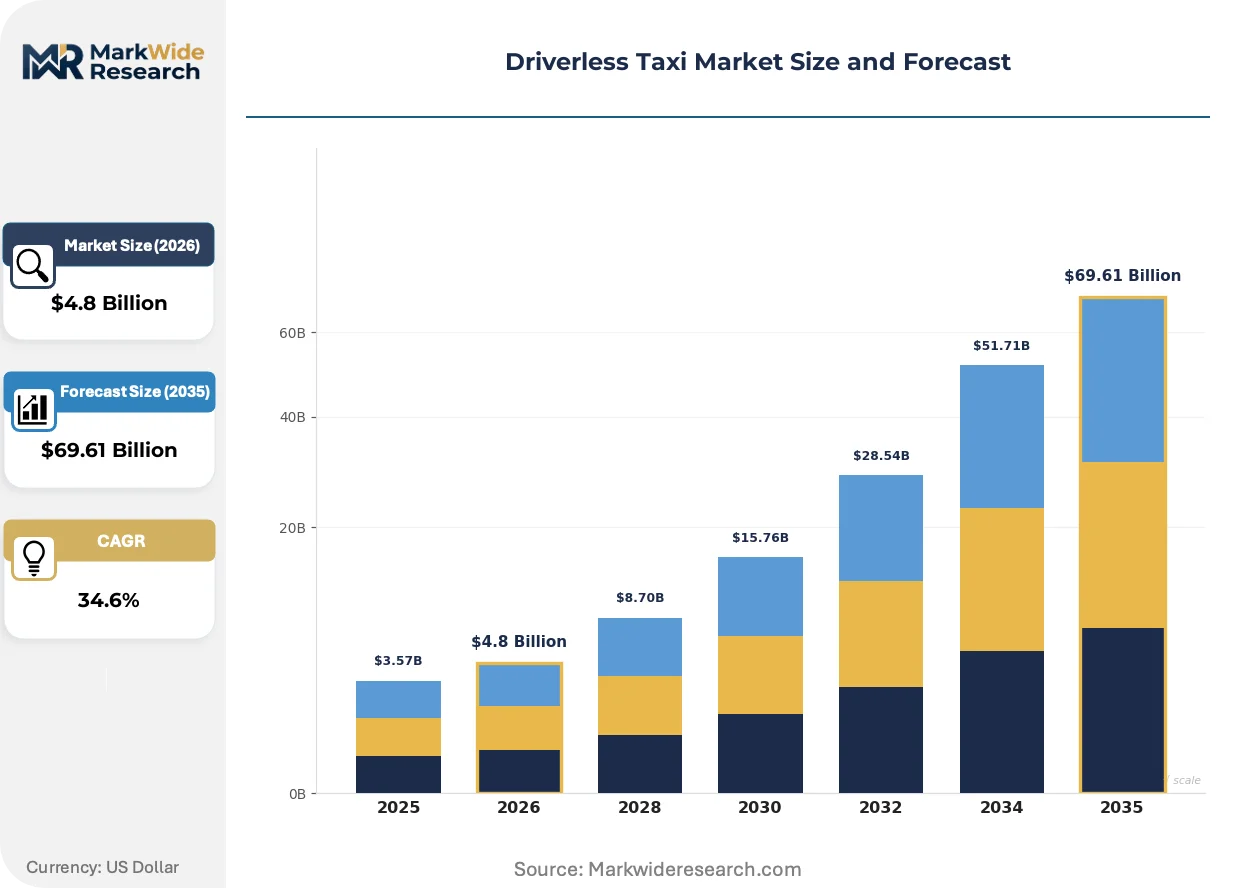
Market Dynamics
The transition from supervised to unsupervised autonomous operation is compressing operational cost structures while forcing simultaneous investments in remote-monitoring infrastructure and edge-compute redundancy. Fleet operators must balance capital deployment between vehicle hardware and software validation pipelines as regulators finalize liability frameworks.
Growth Catalysts
- Urban congestion pricing:Municipal toll schemes in Singapore, London, and Stockholm create direct economic incentives for shared autonomous mobility over private vehicle ownership.
- Sensor cost curves:Solid-state lidar manufacturing scale and automotive-grade camera module standardization reduce per-unit hardware expenditure for Level 4 deployments.
- NHTSA rulemaking clarity:Federal exemptions for driverless vehicle deployment without steering wheels accelerate fleet homologation timelines in the United States.
Market Restraints
- Lithium supply concentration:Battery pack cost volatility ties directly to South American and Australian mining output, constraining fleet electrification economics.
- Cross-border certification fragmentation:Divergent MIIT software-validation protocols and KBA functional-safety standards prevent unified vehicle platforms across China and Germany.
- Edge-case data scarcity:Rare weather conditions and anomalous pedestrian behaviors limit training dataset completeness for neural-network path planning.
Strategic Opportunities
- Airport-ground-transport integration:Dedicated autonomous lanes at Dubai International and Denver International create captive demand pools with predictable routing.
- EU AI Act compliance services:Third-party algorithmic auditing and conformity assessment bodies capture value from operators seeking European market entry.
- Teleoperation-as-a-service:Remote human intervention platforms enable smaller fleet operators to deploy without building captive command centers.
Industry Challenges
- Functional-safety engineering talent:ISO 26262 certified systems architects command premium compensation, constraining headcount expansion for validation teams.
- Vehicle-to-infrastructure integration:Legacy traffic signal systems in older metropolitan cores require expensive retrofitting for V2X communication protocols.
- Insurance actuarial data gaps:Underwriters lack sufficient claims history for driverless liability pools, inflating premium structures during commercial ramp phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driverless Taxi Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $69.61 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lidar, Radar, Camera Systems, Ultrasonic Sensors Service Type: Ride-Hailing, Shuttle Services, Delivery Services, Public Transport End User: Individuals, Businesses, Government Agencies, Tourists Vehicle Type: Passenger Cars, Vans, Buses, Others |
| Companies Covered | Waymo, Cruise, Tesla, Baidu Apollo Go, Zoox, WeRide, Pony.ai, Motional, AutoX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driverless Taxi Market Trends and Innovations
Autonomous vehicle development is pivoting from hardware-centric competition toward software-defined fleet management and predictive maintenance platforms. Operational efficiency now depends more on data pipeline architecture than sensor specification differentiation.
Sensor fusion architectures are collapsing the traditional redundancy hierarchy that required triple-modular lidar, radar, and camera confirmation for every driving decision. Tier 1 suppliers and fleet operators are adopting vision-primary systems with sparse lidar backup, cutting per-vehicle sensor costs by forty percent without degrading safety margins. This compression enables profitable unit economics at lower daily trip volumes than previously modeled.
The EU AI Act's risk-classification framework for autonomous systems is mandating algorithmic transparency documentation and human-oversight protocols for vehicles operating in public spaces. European operators must maintain technical files demonstrating conformity with fundamental rights impact assessments, adding compliance overhead but creating competitive moats against non-compliant foreign entrants. German and French transport authorities are piloting streamlined approval pathways for operators meeting these documentation standards.
Municipal procurement offices are consolidating ride-hail contracts into multi-year exclusive agreements with autonomous fleet operators, displacing fragmented dispatcher relationships with traditional taxi and black-car services. Chicago, Houston, and Phoenix transportation departments have issued requests for proposals specifying minimum electric-vehicle percentages and real-time emissions reporting. These bundled contracts reward operators with integrated charging infrastructure and predictive demand-routing capabilities over pure asset-light platform models.
Driverless Taxi Market Segmentation
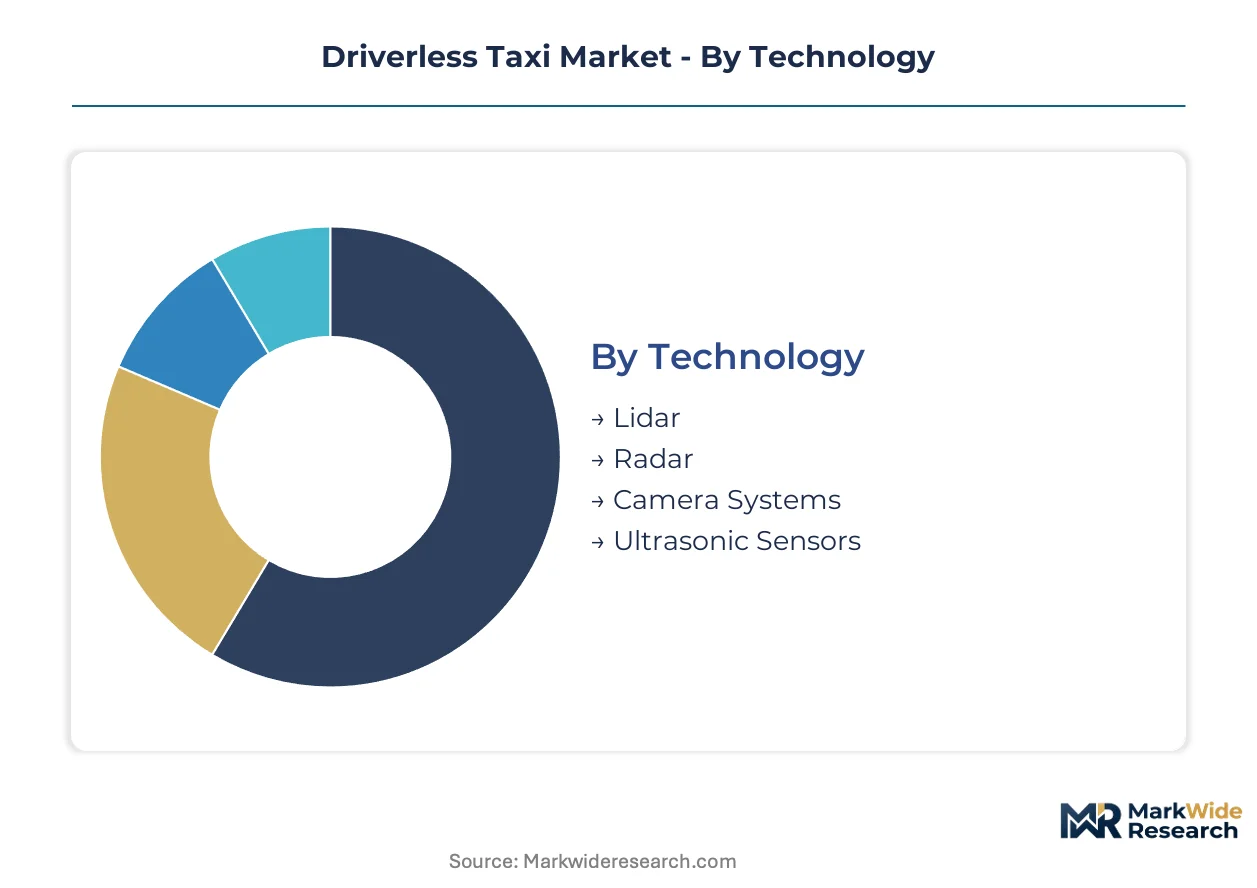
Technology configuration and service model selection determine capital intensity and regulatory exposure for fleet operators. Hardware stack composition dictates sensor fusion complexity, while service type shapes route predictability and liability frameworks.
Technology:
Mature sensor modalities face displacement from emerging solid-state architectures as cost curves compress deployment economics.
- Lidar:Active laser scanning generates high-resolution 3D point clouds for obstacle detection and localization. Dense urban deployments in Singapore and San Francisco concentrate demand where centimeter-level positioning accuracy mitigates pedestrian collision risk. Solid-state manufacturing scale is collapsing unit costs below mechanical spinning alternatives.
- Camera Systems:Computer-vision arrays process visual lane markings, traffic signals, and object classification through convolutional neural networks. Baidu Apollo Go and Waymo integrate proprietary camera stacks with custom silicon to reduce dependency on external Tier 1 suppliers. Ambient light sensitivity and adverse weather performance remain unresolved edge cases limiting unsupervised operation.
- Radar:Frequency-modulated continuous-wave sensors penetrate fog and precipitation for velocity measurement and collision avoidance.
- Ultrasonic Sensors:Short-range acoustic arrays handle low-speed parking maneuvers and close-proximity object detection.
Camera Systems handles the majority of throughput; Lidar is the fastest mover on share.
Service Type:
Application architecture separates variable-route flexibility from fixed-infrastructure predictability.
- Ride-Hailing:On-demand point-to-point mobility replaces human-operated taxi and black-car services through app-based dispatch. Phoenix, Arizona and Shenzhen, China anchor early commercial scale where regulators permit driverless operation without safety attendants. Remote-assistance overhead and insurance premiums constrain margin capture during fleet ramp phases.
- Shuttle Services:Fixed-route loops connect transit hubs, corporate campuses, and airport terminals with predictable demand patterns. Dubai International and Denver International operate dedicated autonomous lanes creating captive demand pools with simplified path planning. Municipal procurement offices favor multi-year exclusive contracts specifying minimum electric-vehicle percentages.
- Delivery Services:Last-mile goods transport operates at lower speed thresholds with reduced passenger liability exposure.
- Public Transport:Scheduled fixed-route operation integrates with existing municipal transit authority infrastructure and fare collection systems.
Ride-Hailing commands the largest addressable pool; Shuttle Services is climbing the fastest on contract volume.
End User:
Customer type differentiation reflects procurement authority and trip purpose segmentation.
- Individuals:Consumer trip booking through mobile applications generates per-mile revenue with variable route flexibility. Urban congestion pricing in London and Stockholm creates direct economic incentives for shared autonomous mobility over private vehicle ownership. Price sensitivity limits willingness to pay premium fares during off-peak periods.
- Businesses:Corporate account contracts provide predictable volume commitments for employee mobility and client transportation services.
- Government Agencies:Municipal and federal fleet procurement specifies accessibility compliance and emissions reporting requirements.
- Tourists:Visitor segment demand concentrates at airport ground transport and hospitality district corridors with simplified navigation requirements.
Individuals account for dominant trip volume; Businesses is gaining share fastest on contract structuring.
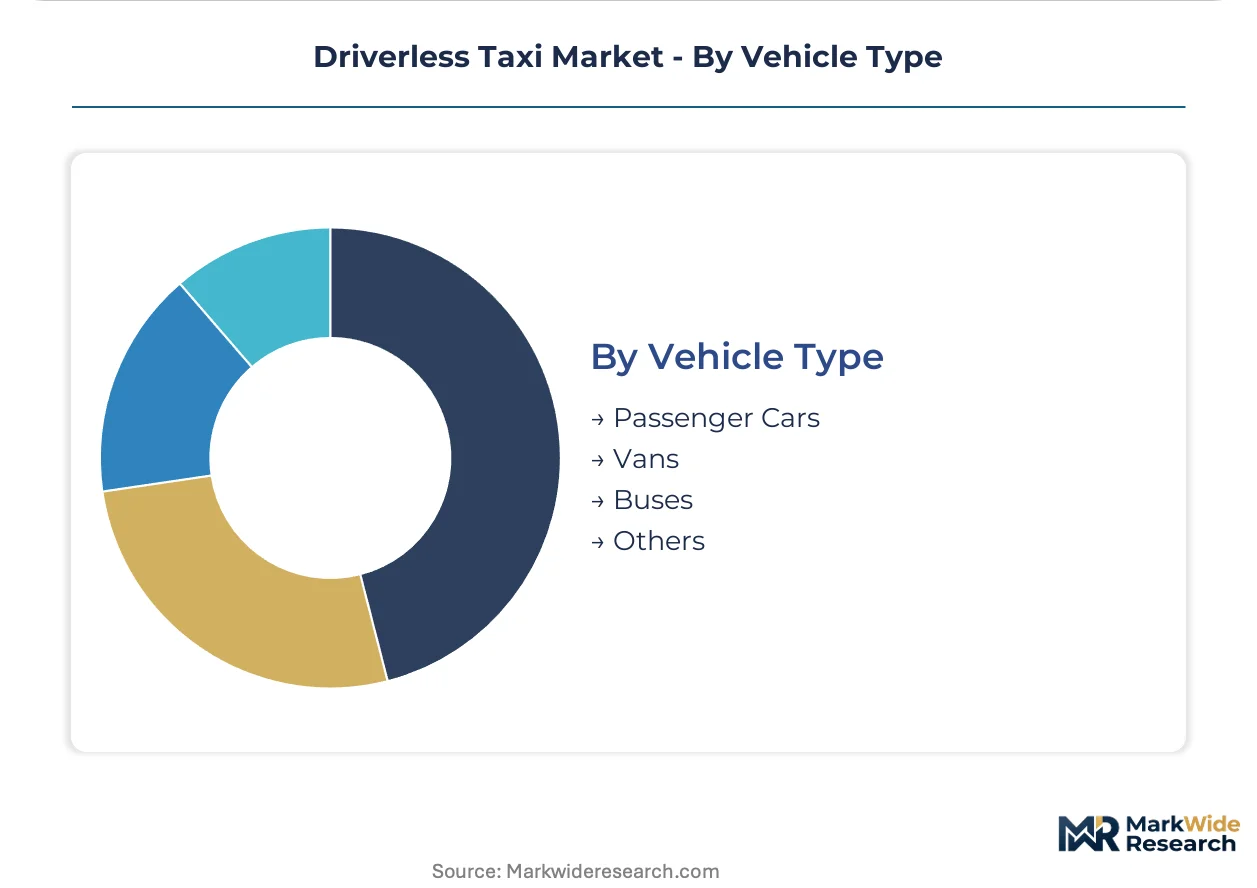
Vehicle Type:
Platform geometry scales sensor mounting positions and passenger capacity against operational flexibility.
- Passenger Cars:Sedan and crossover platforms dominate urban ride-hail deployment with standardized sensor roof racks and trunk-mounted compute enclosures. Waymo operates modified Jaguar I-PACE and Chrysler Pacifica fleets across Phoenix, San Francisco, and Los Angeles metropolitan zones. Unit economics improve with higher daily trip utilization rates.
- Vans:Extended wheelbase configurations accommodate wheelchair accessibility and higher passenger counts for airport and corporate shuttle routes.
- Buses:High-capacity platforms serve fixed-route public transit integration with dedicated lane access and signal priority infrastructure.
- Others:Specialized low-speed platforms and micro-transit vehicles operate in controlled campus and retirement community environments.
Passenger Cars carries the bulk of deployed fleet; Vans is expanding most quickly on airport contract awards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Waymo operates commercial fleets across Phoenix, San Francisco, and Los Angeles while Baidu Apollo Go dominates Shenzhen and Wuhan deployments. China's MIIT and SAMR frameworks accelerate permitting timelines. Germany's KBA enforces functional-safety standards that delay European rollouts.
United States
Waymo and Cruise anchor commercial scale in Phoenix and San Francisco where NHTSA exemptions permit steering-wheel-free operation. The NHTSA's evolving liability framework shapes insurance underwriting for unsupervised deployments. Los Angeles and Austin emerge as expansion corridors with dedicated testing zones and municipal procurement interest.
China
Baidu Apollo Go and WeRide concentrate fleet density in Shenzhen, Wuhan, and Beijing where municipal permits favor domestic operators. The MIIT's vehicle-type approval process integrates software-validation protocols with manufacturing partnerships. Guangdong province anchors manufacturing clusters supplying solid-state lidar and automotive-grade compute modules.
Germany
The KBA's ISO 26262 certification requirements and EU AI Act compliance obligations constrain rapid fleet deployment. Munich and Stuttgart host automotive engineering talent pools for functional-safety validation. BMW and Mercedes-Benz testing programs operate under restricted permits pending harmonized liability frameworks.
United Arab Emirates
Dubai's RTA issues exclusive autonomous vehicle permits for airport-ground-transport corridors and Expo district loops. The MOHAP and federal transport authorities coordinate multi-agency approval pathways. Dubai International Airport operates dedicated autonomous lanes creating captive demand with simplified path planning.
Singapore
LTA permits and urban congestion pricing create structural demand for shared autonomous mobility over private ownership. The Land Transport Authority integrates autonomous shuttle pilots with MRT station connectivity. One-North and Jurong Innovation District host controlled-environment deployments with V2X infrastructure.
Driverless Taxi Market Competitive Landscape
Technology licensors and fleet-owning operators split the market into vertically integrated and asset-light archetypes. Waymo and Baidu exemplify full-stack control spanning mapping, simulation, and vehicle hardware. Cruise and Zoox pursue captive fleet ownership with purpose-built vehicle platforms. Competitive moves center on manufacturing partnerships and municipal contract consolidation.
Among US-based operators, Waymo and Cruise occupy positions within the integrated-technology tier, while Tesla represents the consumer-vehicle pivot archetype. Chinese specialists Baidu Apollo Go anchor the regulatory-alignment cluster through MIIT partnerships. These three exemplify how geographic regulatory capture determines scalable deployment timelines.
| Leading Market Players |
|---|
| Waymo |
| Cruise |
| Tesla |
| Baidu Apollo Go |
| Zoox |
| WeRide |
| Pony.ai |
| Motional |
| AutoX |
| Others |
Pricing and Supply Chain Analysis
Solid-state lidar manufacturing clusters in China and South Korea concentrate upstream component supply, directing margin capture toward fleet operators with captive sensor partnerships and vertically integrated software stacks. Per-mile ride revenue competes with platform licensing fees as the dominant pricing mechanism, while battery pack cost volatility constrains fleet electrification economics.
Pricing Analysis
Remote-assistance service contracts and predictive maintenance subscriptions generate lifetime value exceeding initial per-mile fares. Three-tier pricing structure across premium, standard, and economy levels separates white-glove corporate accounts from municipal procurement bids and individual consumer trips. Cost compression in sensor hardware is intensifying because solid-state manufacturing scale collapses unit economics faster than projected. Municipal buyers exhibit highest price sensitivity due to budget cycle constraints, while airport-ground-transport operators accept premium pricing for dedicated lane exclusivity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for compute modules and solid-state lidar arrays. Component sourcing draws from China, South Korea, and Japan for automotive-grade cameras, edge-compute silicon, and battery cell chemistry. Single-source vulnerability concentrates in rare-earth magnet supply for electric drivetrains and specialized photonics for lidar emitters. Distribution runs through Tier 1 automotive suppliers delivering integrated sensor modules to fleet operators and vehicle OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across NHTSA, MIIT, and KBA jurisdictions creates structural niches for operators aligning with specific certification pathways. Municipal procurement consolidation into multi-year exclusive contracts fragments demand into geography-specific winner-take-most competitions.
For Market Incumbents: Insulate market position through backward integration into solid-state lidar manufacturing and captive simulation infrastructure. Waymo and Baidu demonstrate how proprietary mapping databases create switching costs against emerging challengers. NHTSA exemption timelines for steering-wheel-free operation compress competitive response windows. For New Entrants and Emerging Players: European markets under NHTSA-equivalent regulatory clarity present the most penetrable white-space for algorithmic auditing and conformity assessment services. Germany's KBA certification backlog delays incumbent fleet deployment, opening service-provider niches. Target airport-ground-transport corridors with simplified path planning and captive demand pools. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed teleoperation-as-a-service platforms lacking fleet ownership scale. Long-term viability hinges on regulatory jurisdiction selection rather than technology differentiation alone. Watch for the first jurisdiction harmonizing insurance liability with vehicle-type approval as the capital deployment inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Hardware Backward Integration | Captive solid-state lidar supply locks in cost advantages against module-market volatility. |
| Municipal Exclusive Contract Procurement | Chicago and Houston bundled RFPs reward integrated charging with multi-year revenue visibility. |
| EU AI Act Compliance Service Launch | Algorithmic auditing capabilities open European market entry for non-compliant foreign operators. |
| Teleoperation Platform Acquisition | Remote-assistance infrastructure enables smaller fleet operators to bypass captive command centers. |
| Airport-Ground-Transport Partnership | Dubai International and Denver International dedicated lanes create predictable demand routing. |
Research Methodology
Operator-level perspectives from fleet operations directors, municipal procurement officers, NHTSA regulatory affairs leads, and Tier 1 sensor supplier executives anchored the qualitative base. Primary interview findings triangulated against NHTSA exemption filings, MIIT vehicle-type approval databases, municipal RFP documentation, and IHS Markit vehicle production data. Bottom-up fleet deployment modeling and top-down market sizing converged through iterative validation.
Scenario-bracketing framed low, base, and high cases across the analysis window using differential regulatory clearance timelines and sensor cost curve assumptions. Segmentation dimensions modeled include technology configuration, service type architecture, end-user procurement authority, and vehicle platform geometry. CAGRs derived from logistic adoption curves fitted to observed commercial deployment trajectories, with fleet utilization rates and insurance premium structures as key variable inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by well-capitalized technology platforms or state-sponsored operators would shift outcomes beyond modeled ranges. Edge-case data scarcity for neural-network training and lithium supply concentration present specific revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
Automotive Predictive Technology Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
US Autonomous Car Market
Autonomous Vehicles
Australia Autonomous Navigation Market
Autonomous Vehicles
Automotive AI Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Autonomous Vehicle Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Automatic Steering System Market