
 South Korea Automotive Camera Market | 2026-2036
South Korea Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Automotive Camera Market Analytics
ADAS-grade resolution standards is redrawing procurement criteria across the South Korea automotive camera landscape. Continental AG leverages in-house sensor fusion capabilities to anchor premium front-camera contracts with domestic OEMs. Robert Bosch GmbH competes through sustained R&D intensity in night-vision algorithms tailored to Korean road conditions. Denso Corporation specializes in integrated modular assemblies that reduce wiring complexity for Seoul-based vehicle assembly plants.
An automotive camera is an electro-optical device comprising a CMOS or CCD image sensor, signal processor, and sealed housing rated for vibration, thermal cycling, and electromagnetic interference, designed to capture real-time visual data for driver assistance, parking guidance, and autonomous navigation systems. HD digital technology leads installation value as pixel density requirements climb for lane-keeping and pedestrian detection accuracy. Rearview cameras retain volume dominance due to regulatory mandate, while 360-degree camera systems capture the fastest expansion among passenger vehicle trims as surround-view becomes standard on mid-tier sedans and SUVs.
MFDS vehicle safety guidelines, KMVSS crashworthiness provisions, and ISO 26262 functional-safety standards collectively shape camera durability, image latency, and fail-operational requirements for Korean-market vehicles. MFDS oversight of component reliability testing creates compliance barriers that favor established Tier-1 suppliers with certified quality systems. Stakeholders must monitor how domestic OEMs reconcile export-market homologation demands with localized cost targets as electrified platforms multiply camera counts per vehicle.
Market Dynamics
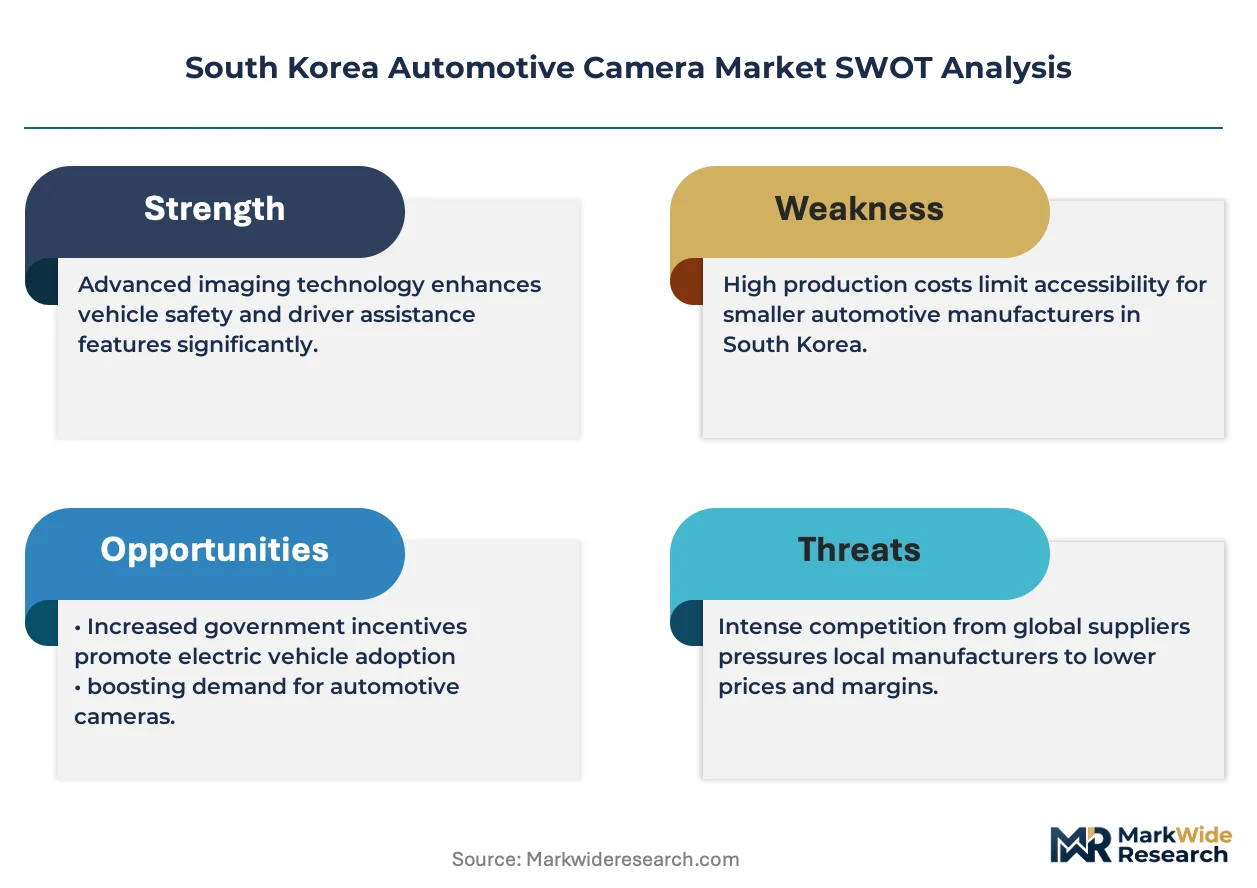
The South Korea automotive camera market pivots on MFDS enforcement of ISO 26262 functional-safety standards, which compels Tier-1 suppliers to reengineer image-processing pipelines for fail-operational redundancy as domestic OEMs scale electrified platforms.
Growth Catalysts
- KMVSS rearview mandate:Regulatory compliance drives baseline installation volumes across all passenger vehicle classes, ensuring minimum camera counts per platform regardless of trim level.
- Seoul metropolitan cluster concentration:Proximity of Hyundai-Kia headquarters, Tier-1 electronics vendors, and specialized testing laboratories compresses development cycles and accelerates prototype-to-production transitions.
- ADAS-grade CMOS sensors:Pixel density requirements for pedestrian detection and lane-keeping algorithms pull higher-resolution image sensors into mid-tier vehicle configurations.
Market Restraints
- Specialized semiconductor foundry concentration:Automotive-grade image sensor fabrication depends on a narrow supplier base in Taiwan and Japan, exposing Korean camera module assemblers to allocation volatility.
- MFDS reliability testing duration:Extended thermal cycling and electromagnetic interference certification timelines delay new product introductions by six to nine months relative to consumer electronics cycles.
- Silicon wafer input cost sensitivity:Camera module bill-of-materials remains vulnerable to 300mm wafer pricing swings that compress Tier-2 supplier margins.
Strategic Opportunities
- Gyeongsang-do manufacturing corridor:Underutilized assembly capacity in Busan-Ulsan industrial zones offers expansion space for camera module production serving export-bound Hyundai-Kia electrified platforms.
- Camera-to-radar sensor fusion:Convergence of optical imaging and millimeter-wave data streams creates white space for integrated perception modules in Level 2+ autonomous systems.
- MFDS connected-vehicle data governance:Emerging guidelines for over-the-air software updates and image data privacy establish first-mover advantage for suppliers with certified cybersecurity architectures.
Industry Challenges
- ISO 26262 ASIL-D functional-safety engineering:Scarcity of certified systems engineers in South Korea forces suppliers to recruit from semiconductor and aerospace sectors at premium compensation.
- Legacy vehicle electrical architecture integration:Retrofitting HD digital cameras into platforms designed for analog composite video requires custom signal conditioning hardware that fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Automotive Camera Market |
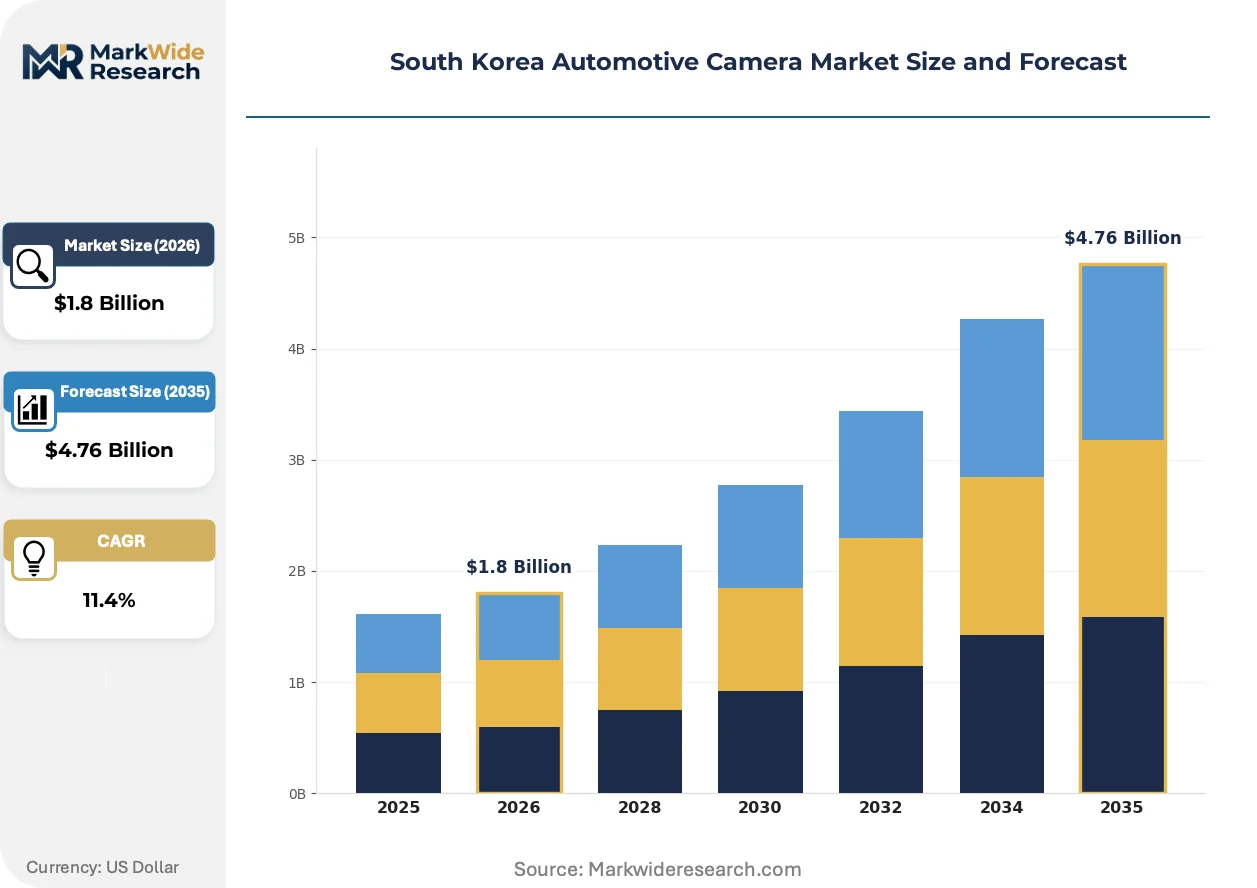
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camera Type: Rearview Camera, Front Camera, 360-Degree Camera, Night Vision Camera Technology: Infrared, HD, Digital, Analog Installation Type: OEM, Aftermarket, Integrated, Modular End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Fleet Operators |
| Companies Covered | Continental AG, Denso Corporation, Robert Bosch GmbH, Hella KGaA Hueck & Co., Valeo SA, Magna International Inc., Panasonic Corporation, Gentex Corporation, Garmin Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Automotive Camera Market Evolving Landscape
Component miniaturization and software-defined imaging architectures are compressing hardware footprints while expanding computational capability. Korean OEMs now specify camera modules that consolidate multiple sensing functions within single housing envelopes.
Automotive-grade CMOS image sensors with stacked backside-illuminated architectures is miniaturizing pixel pitch below 2.2 micrometers without sacrificing low-light sensitivity. Domestic Tier-1 suppliers adopt these dies for next-generation surround-view systems. The reduction in sensor die area enables slimmer housing profiles that integrate into side-mirror stalks and grille apertures.
MFDS alignment with United Nations Economic Commission for Europe (UNECE) R79 and R157 regulations for automatic lane-keeping and highway assist systems tightens image latency specifications to sub-100 milliseconds. Camera module vendors must redesign signal processing pipelines to meet synchronous deterministic output requirements. Front-camera assemblies for Hyundai Motor Group's electrified platforms face the most stringent compliance verification.
Fleet procurement departments at Korean mobility operators now specify camera durability metrics separately from vehicle platform sourcing. Rental and ride-hail companies negotiate direct service agreements with Tier-1 suppliers for replacement schedules and firmware maintenance. This disintermediation concentrates in Seoul-based fleet management firms operating battery-electric vehicle pools.
South Korea Automotive Camera Market Segmentation
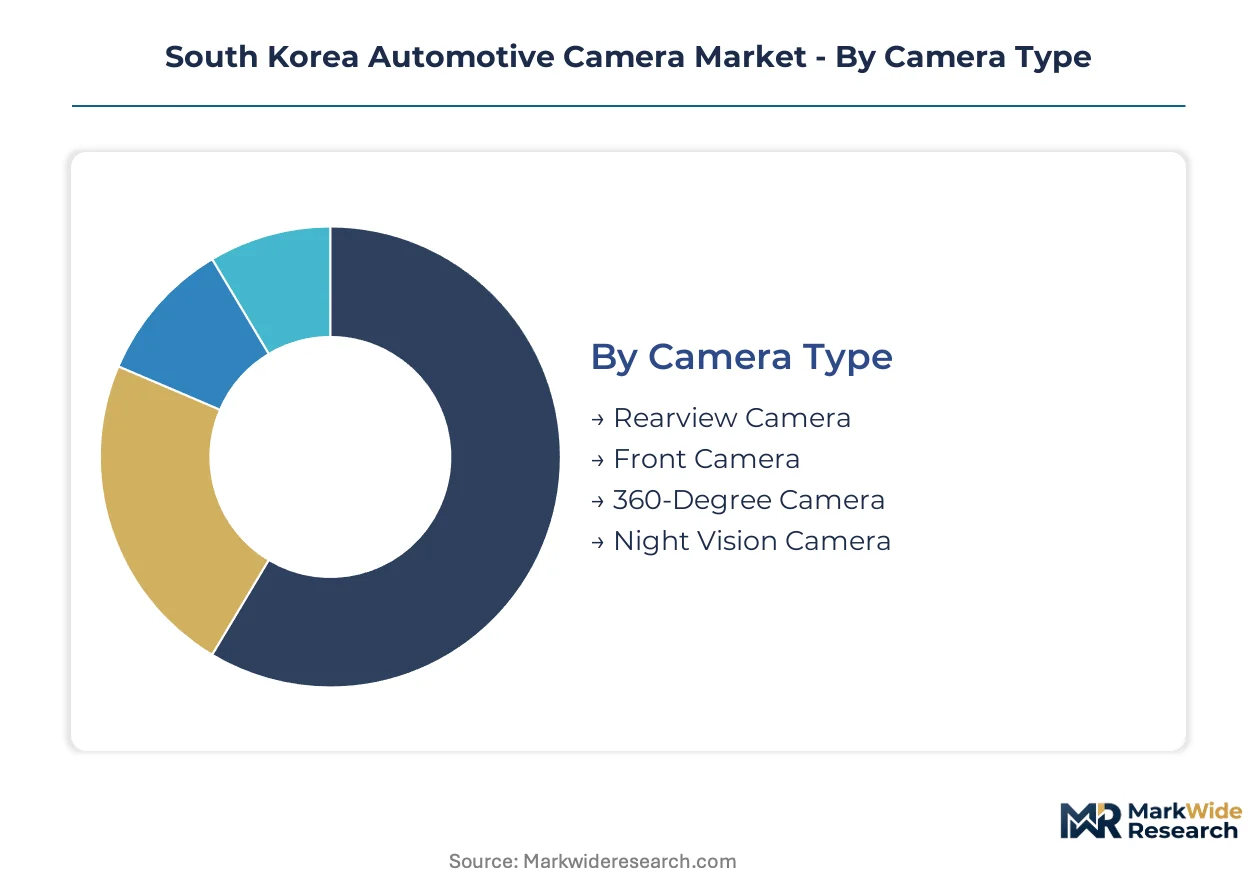
Camera configuration choices in South Korea reflect divergent OEM sourcing strategies for electrified platforms versus legacy internal-combustion vehicles. Segment boundaries blur as Hyundai-Kia consolidates multi-function modules that previously required discrete components.
Camera Type:
Rearview cameras face substitution pressure from 360-degree surround-view systems that incorporate overlapping rear-facing fields of view.
- Rearview Camera:Regulatory minimum specification under KMVSS mandates single-lens assemblies with 130-degree horizontal coverage. Seoul-based fleet operators specify extended warranty terms for rental vehicle pools where reverse-cycle frequency exceeds private ownership patterns.
- 360-Degree Camera:Four-sensor fusion architectures synthesize bird's-eye perspectives for parking assistance. Hyundai Motor Group's electrified SUV platforms in Gyeonggi-do assembly plants now specify these as standard above mid-tier trims, displacing discrete rearview units.
- Front Camera:Monocular and stereo configurations support adaptive cruise and lane-keeping functions. MFDS alignment with UNECE R79 drives sub-100-millisecond latency requirements.
- Night Vision Camera:Thermal imaging and near-infrared augmented sensors penetrate low-illumination driving conditions on unlit rural highways.
Rearview cameras anchor the volume base while 360-degree systems gain share at the steepest rate.
Technology:
Cost tier differentiation separates premium electrified platforms from economy vehicle specifications.
- HD:2-megapixel and above CMOS sensors with HDR processing enable pedestrian detection at 50-meter ranges. Busan-Ulsan corridor suppliers prioritize HD die procurement for export-bound Hyundai-Kia platforms facing EU and North American homologation.
- Digital:LVDS and GMSL2 serial interfaces transmit uncompressed video to central domain controllers. Seoul metropolitan cluster Tier-1 vendors specialize in digital signal conditioning ASICs that reduce electromagnetic interference in dense vehicle harnesses.
- Infrared:Active illumination at 850-nanometer wavelength extends detection range beyond visible-spectrum limitations.
- Analog:Composite video persists in legacy platform refreshes where electrical architecture renewal costs exceed camera upgrade benefits.
Digital interfaces dominate new platform engineering while analog retains residual share in cost-constrained refreshes.
Installation Type:
Customer type concentration splits between captive OEM supply and independent service channel demand.
- OEM:Factory-integrated modules undergo MFDS reliability testing for thermal cycling and vibration resistance. Hyundai-Kia's vertical control over Gyeongsang-do manufacturing corridors ensures specification alignment with electrified platform electrical architectures.
- Integrated:Multi-sensor housings consolidate front-facing cameras with radar and lidar perception elements. Seoul-based R&D facilities specialize in integrated module validation for Level 2+ autonomous systems.
- Modular:Discrete camera units permit field replacement without full perception stack recalibration.
- Aftermarket:Retrofit installations serve vehicle owners seeking parking assistance upgrades outside factory configurations.
OEM installation anchors procurement volume while integrated configurations climb fastest as sensor fusion architectures proliferate.
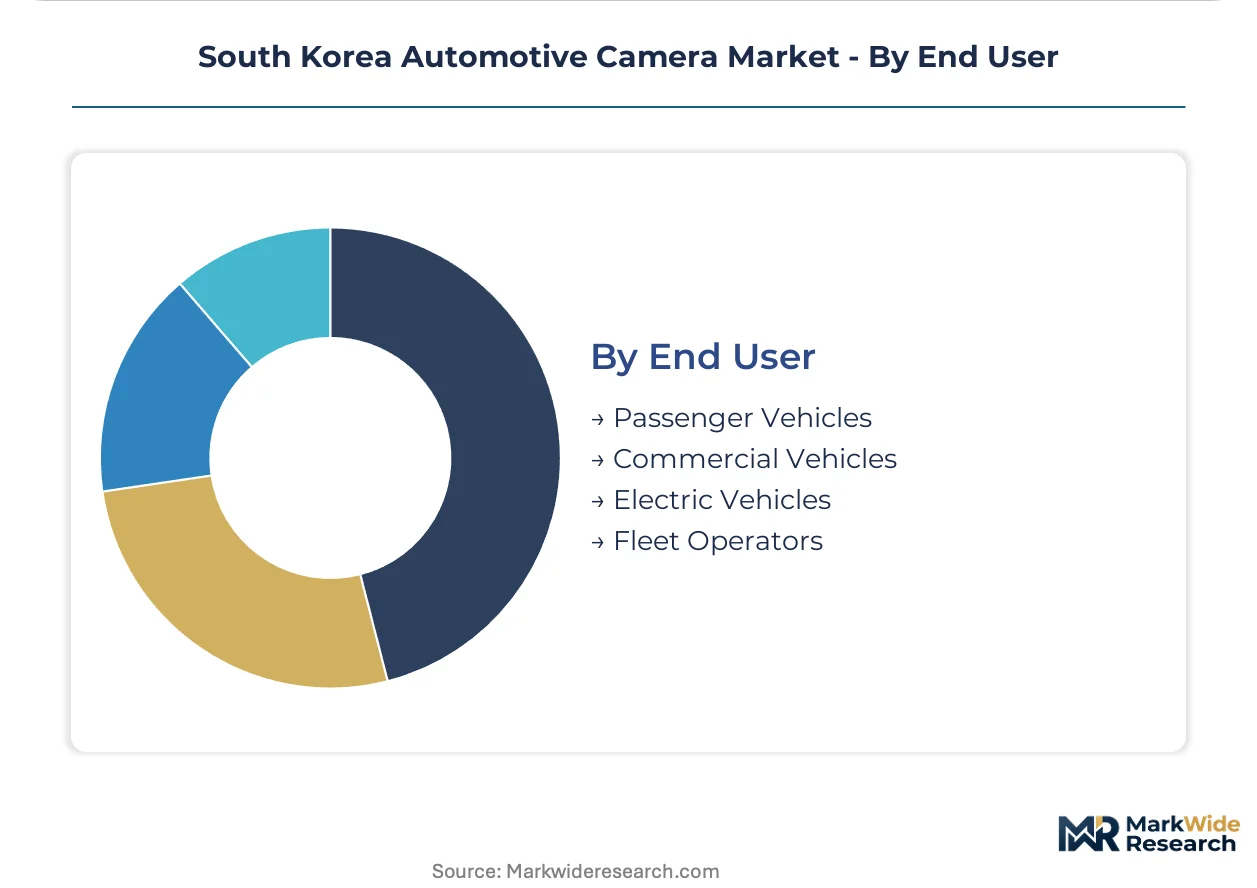
End User:
Application maturity varies sharply between mass-market passenger specifications and emerging fleet-managed electric vehicle pools.
- Passenger Vehicles:Private ownership configurations prioritize aesthetic integration and parking convenience over redundant sensing depth. Mid-tier sedans and SUVs in Seoul metropolitan area dealerships now specify 360-degree systems as competitive necessities.
- Electric Vehicles:Battery-electric platforms accommodate higher camera counts per vehicle due to simplified thermal management and expanded electrical budgets. Hyundai Ioniq and Kia EV series integrate eight to twelve camera modules for surround-view and automated parking functions.
- Commercial Vehicles:Heavy-duty trucks and buses specify reinforced housings for extended duty cycles on intercity routes.
- Fleet Operators:Rental and ride-hail companies negotiate direct service agreements with Tier-1 suppliers for firmware maintenance and replacement scheduling.
Passenger vehicle demand anchors volume while electric vehicle specifications expand most quickly through dedicated platform engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Camera module assembly concentrates in the Seoul Capital Area and Busan-Ulsan corridor, where Hyundai-Kia suppliers and Tier-1 electronics vendors co-locate manufacturing and R&D facilities. This geographic clustering compresses development cycles and accelerates prototype-to-production transitions for electrified platforms.
Seoul Capital Area
Hyundai Motor Group headquarters in Seoul and Kia Corporation in Gwangmyeong anchor procurement decisions for front-camera and surround-view systems. MFDS vehicle safety guidelines and ISO 26262 functional-safety standards shape durability and image latency requirements for Korean-market vehicles. Pangyo Techno Valley hosts specialized testing laboratories where Tier-1 suppliers validate electromagnetic interference resistance.
Busan-Ulsan
The Gyeongsang-do manufacturing corridor offers underutilized assembly capacity for camera module production serving export-bound Hyundai-Kia electrified platforms. KMVSS crashworthiness provisions govern component reliability testing that favors established suppliers with certified quality systems. Ulsan assembly plants integrate eight to twelve camera modules per battery-electric vehicle for automated parking functions.
Daegu-Gyeongbuk
Specialized semiconductor packaging facilities in this region support automotive-grade CMOS sensor integration for domestic Tier-2 suppliers. Extended thermal cycling certification timelines delay new product introductions by six to nine months relative to consumer electronics cycles. Daegu-based electronics vendors concentrate on signal conditioning ASICs that reduce electromagnetic interference in dense vehicle harnesses.
Daejeon-Sejong
Government research institutes in this administrative hub coordinate MFDS alignment with United Nations Economic Commission for Europe regulations for automatic lane-keeping systems. Sub-100-millisecond image latency specifications drive redesign of signal processing pipelines for synchronous deterministic output. Sejong-based policy coordination shapes connected-vehicle data governance for over-the-air software updates.
Gwangju-Honam
Emerging automotive electronics investment in this southwestern region targets aftermarket retrofit installations and modular camera units for field replacement. Fleet procurement departments at regional mobility operators negotiate direct service agreements with Tier-1 suppliers for firmware maintenance. Gwangju industrial zones attract camera module assembly for commercial vehicle specifications with reinforced housings.
South Korea Automotive Camera Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South Korea automotive camera market. The supplier base organizes into three tiers: multinational Tier-1 system integrators with certified quality systems, regional electronics specialists with signal processing expertise, and modular component vendors serving aftermarket channels. Dominant competitive moves include strategic partnerships for sensor fusion development and geographic expansion into underutilized manufacturing corridors.
Among Germany-based system integrators, Continental AG and Robert Bosch GmbH exemplify the technology leadership archetype through in-house capabilities. Denso Corporation represents the integrated modular assembly specialization that reduces wiring complexity for Seoul-based vehicle assembly plants.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Robert Bosch GmbH |
| Hella KGaA Hueck & Co. |
| Valeo SA |
| Magna International Inc. |
| Panasonic Corporation |
| Gentex Corporation |
| Garmin Ltd. |
| Others |
Value Network & Pricing Analysis
Six-month thermal cycling certification timelines compress inventory turns for Korean camera module assemblers, concentrating pricing power with Taiwan-based CMOS foundries while Tier-2 suppliers absorb silicon wafer volatility through thin margins.
Pricing Analysis
MFDS ISO 26262 certification tiers dictate the pricing tier structure across the South Korean automotive camera market. Three-tier pricing structure across premium ASIL-D, standard ASIL-B, and economy QM-grade certification levels separates front-camera assemblies for Hyundai-Kia electrified platforms from mid-tier surround-view configurations. Price differentiation hinges on pixel density specifications and electromagnetic interference shielding grade. Cost compression in standard-tier modules is intensifying because domestic OEMs consolidate multi-sensor housings that previously required discrete procurement. Fleet operators in Seoul demonstrate highest price sensitivity through direct service agreement negotiations, while export-bound platforms facing EU homologation tolerate premium tier pricing.
Supply Chain Analysis
Strait of Malacca transit underwrites just-in-time delivery schedules for automotive-grade CMOS image sensors bound for Busan-Ulsan assembly corridors. Taiwan and Japan anchor wafer fabrication capacity while South Korea and Vietnam host backend packaging and module integration. Raw material dependencies span 300mm silicon wafers, glass lens substrates, and halogen-free PCB laminates. Single-source vulnerability concentrates in stacked backside-illuminated sensor dies from TSMC-affiliated foundries. Distribution runs through captive OEM supply chains with Hyundai-Kia vertical integration, supplemented by Tier-1 vendor direct-to-plant logistics for modular replacement units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camera-to-domain controller software interfaces are consolidating around standardized middleware stacks, transforming component procurement into platform-ecosystem subscription economics as Hyundai-Kia electrified architectures proliferate.
For Market Incumbents: Secure backward integration into automotive-grade CMOS sensor procurement through long-term foundry capacity reservations, insulating margin structures from Taiwan allocation volatility. Deepen certification engineering benches in Seoul metropolitan cluster to compress MFDS reliability testing cycles. Defend against modular assembly specialists by anchoring front-camera contracts with integrated perception-stack roadmaps. For New Entrants and Emerging Players: Anchor in Gwangju-Honam aftermarket retrofit channels where fleet operators disintermediate OEM service networks for firmware maintenance contracts. Target commercial vehicle reinforced housing specifications as the most penetrable segment given lower certification barrier density. Pursue direct procurement relationships with Seoul-based mobility operators seeking camera durability metrics decoupled from vehicle platform sourcing. For Investors and Strategic Acquirers: Long-term, this sits as a sensor-fusion consolidation play because Level 2+ autonomous architectures collapse discrete camera, radar, and lidar procurement into integrated perception modules. Acquisition targets should exhibit certified cybersecurity architectures for MFDS connected-vehicle data governance. Watch for inflection when Gyeongsang-do manufacturing corridor utilization crosses threshold triggering capacity expansion announcements from Hyundai-Kia suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Hyundai-Kia consolidation of multi-function camera modules reduces discrete component counts across electrified SUV lines. |
| Software-Defined Vehicle Investment | Over-the-air firmware update capabilities shift camera module value toward recurring software revenue streams. |
| Geographic Manufacturing Footprint | Busan-Ulsan corridor expansion captures export-bound electrified platform demand with compressed logistics cycles. |
| Sensor Fusion Partnership | Camera-to-radar integration creates white space for integrated perception modules in Level 2+ autonomous systems. |
| Battery Supply Agreement | Electric vehicle platform electrical budgets accommodate higher camera counts per vehicle through simplified thermal management. |
Research Methodology
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and MFDS regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from KMVSS regulatory filings, vehicle production databases, IHS Markit registration data, and customs trade records for CMOS sensor imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic anchors.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions spanned camera type, technology interface, installation configuration, vehicle propulsion architecture, and regional production cluster. CAGRs derived from logistic growth curve fitting with electrified platform penetration rates and ADAS content-per-vehicle trajectories as primary demand drivers.
Decision-makers should treat outputs as directional under assumptions of sustained MFDS enforcement intensity and stable Taiwan-Japan semiconductor supply; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ISO 26262 ASIL-D engineering talent scarcity and legacy vehicle electrical architecture refresh cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Global Automotive Charge Air Cooler Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market
Automotive Electrical & Electronics
GCC Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market