
 Europe Automotive Display Market | 2026-2036
Europe Automotive Display Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Display Market Foresight
Project finance partnerships between display foundries and Tier 1 module integrators is reshaping competitive entry in the Europe Automotive Display Market. Robert Bosch GmbH leverages captive semiconductor sourcing to secure OLED supply commitments from LG Display Co. Ltd. Continental AG anchors its position through in-house production of curved glass bonding equipment. Samsung Display Co. Ltd. competes by extending its microLED pilot capacity near Slovakian automotive assembly corridors.
Automotive displays encompass TFT-LCD, OLED, and emerging microLED panels engineered for extreme temperature cycling, anti-glare readability, and functional safety certification under ISO 26262. These components consolidate instrumentation, navigation, and ADAS visualization into unified human-machine interfaces. Central Display modules command the widest installation footprint across European passenger vehicle platforms. OLED technology captures margin pools in luxury vehicle cockpits where contrast ratio and form-factor flexibility justify premium positioning. LCD sustains volume leadership in commercial vehicles where cost sensitivity and proven supply chains dominate procurement patterns.
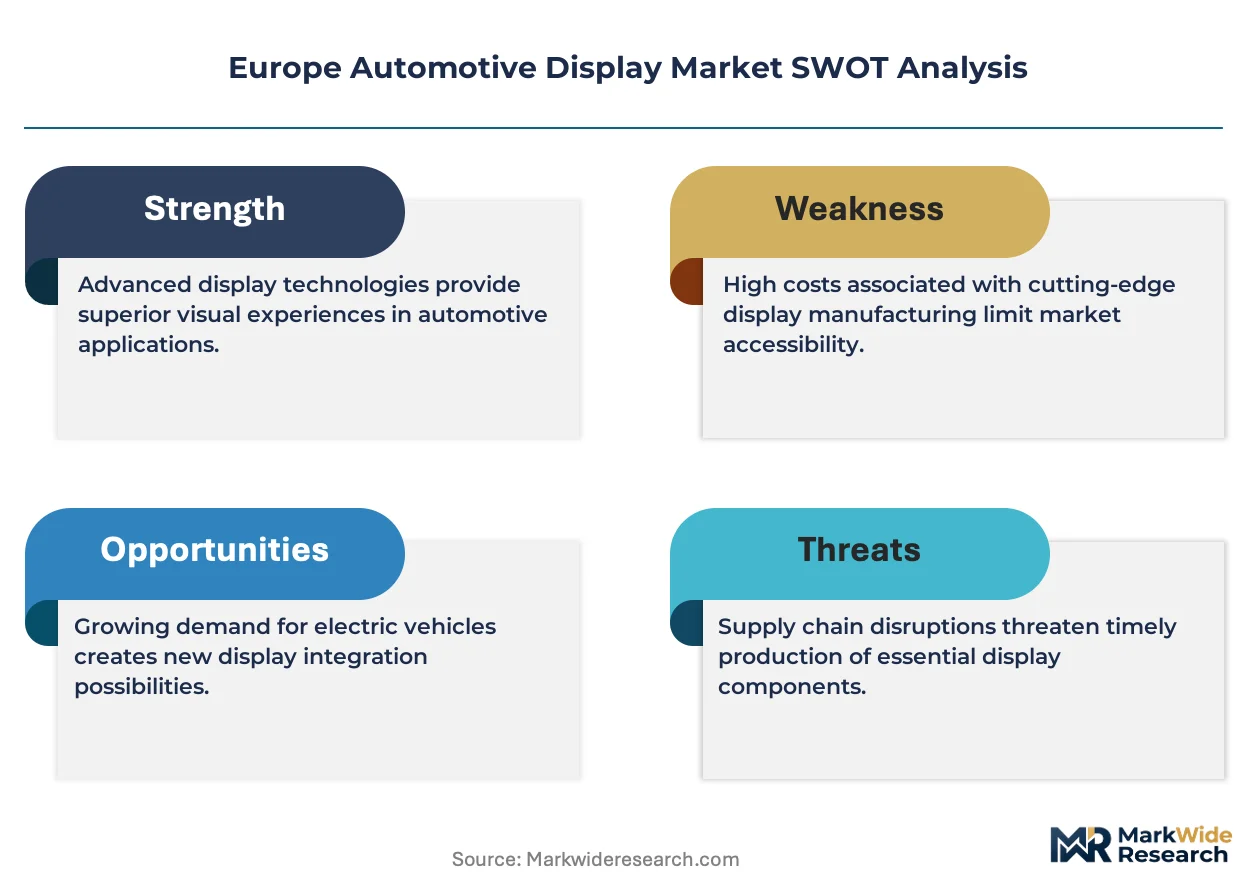
EU Green Deal carbon-border adjustments and REACH substance restrictions constrain display adhesive and backlighting chemistries available to manufacturers. EMA automotive electronics guidelines and CE marking requirements shape product validation timelines for aftermarket installation channels. Stakeholders must monitor Euro 7 final compliance deadlines and battery-electric vehicle platform consolidation plans to align display roadmap investments with OEM production schedules.
Market Dynamics
EU Green Deal carbon-border adjustments and Euro 7 emission standards are compressing instrument cluster and HUD architectures into integrated, energy-efficient modules, forcing Tier 1 suppliers to co-locate near German OEM headquarters.
Growth Catalysts
- Digital Cockpit Consolidation:European OEMs are merging instrumentation, navigation, and ADAS visualization into unified human-machine interfaces, expanding display module installation footprints across premium electric vehicle platforms.
- REACH Substance Restrictions:ECHA constraints on display adhesive and backlighting chemistries are accelerating substitution toward compliant material platforms, creating first-mover advantages for validated suppliers.
- OLED Form-Factor Flexibility:Curved and free-form display capabilities enable differentiated cabin aesthetics in luxury segments, justifying premium positioning against commodity LCD alternatives.
Market Restraints
- Semiconductor Supply Concentration:Captive OLED sourcing commitments and foundry capacity allocation favor vertically integrated Tier 1s, squeezing independent module integrators.
- Functional Safety Certification Burden:ISO 26262 ASIL compliance timelines extend product validation cycles, delaying revenue recognition for new display technologies.
- Input Cost Volatility:Rare earth elements in backlighting phosphors and indium tin oxide for transparent electrodes face price swings tied to concentrated upstream refining.
Strategic Opportunities
- MicroLED Pilot Scale-Up:Slovakian automotive assembly corridors offer proximity advantages for next-generation display capacity serving Central European OEM plants.
- Aftermarket Installation Channels:CE marking requirements under EMA automotive electronics guidelines create certified retrofit opportunities for legacy vehicle fleet upgrades.
- Battery-Electric Platform Consolidation:Dedicated BEV architectures eliminate legacy combustion-engine packaging constraints, enabling larger, curved display surfaces without thermal management trade-offs.
Industry Challenges
- Optical Bonding Skill Scarcity:Curved glass lamination expertise concentrates among equipment specialists, constraining in-house production ramp rates for aspirant module integrators.
- Multi-Regulatory Convergence:Simultaneous compliance with EU Green Deal carbon accounting, REACH substance restrictions, and Euro 7 energy efficiency mandates fragments engineering resources.
- Legacy System Integration:Hybrid ICE-BEV production lines require display modules compatible with both 12V and 48V electrical architectures, complicating BOM standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Display Market |
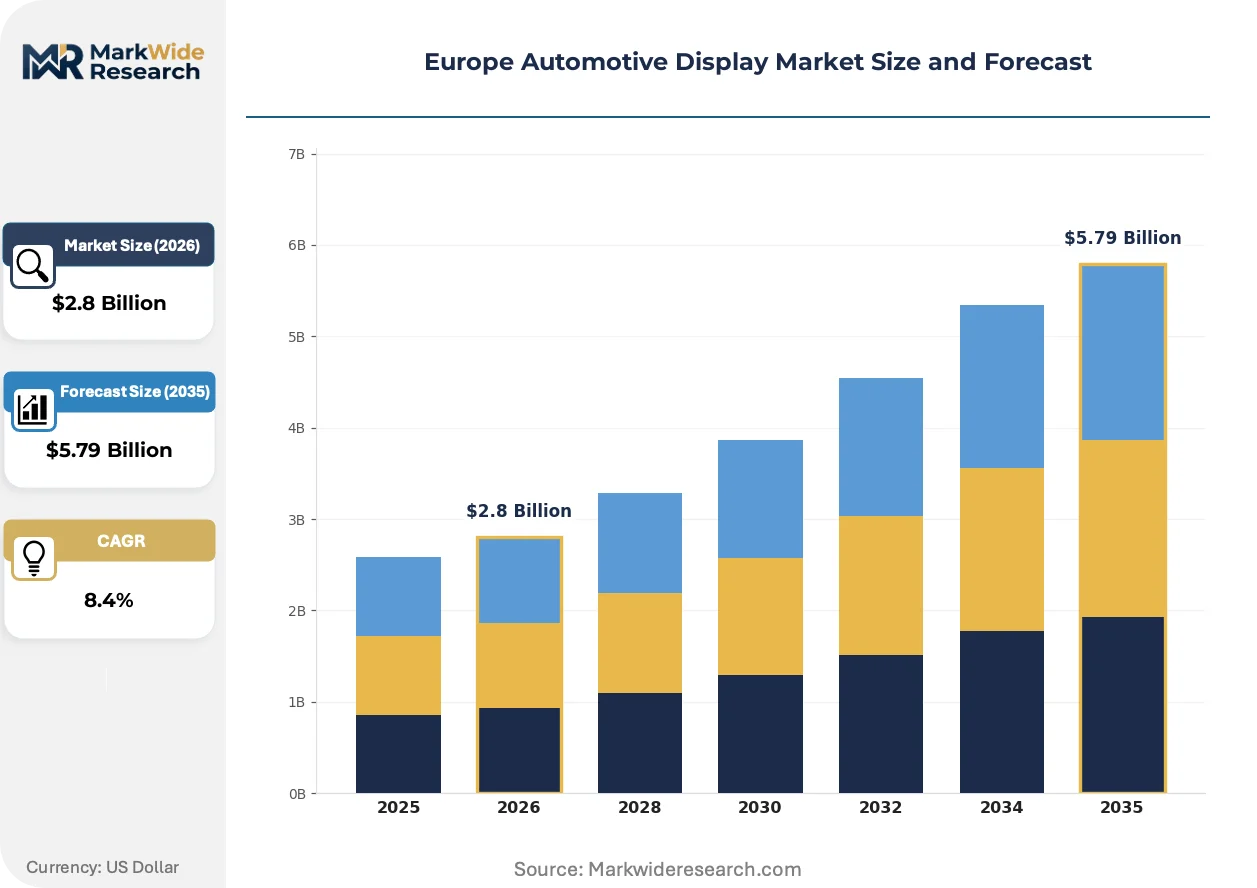
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instrument Cluster, Head-Up Display, Rear Seat Entertainment, Central Display Technology: LCD, OLED, LED, MicroLED End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Installation: Integrated, Standalone, OEM, Aftermarket |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Hyundai Mobis, Visteon Corporation, LG Display Co. Ltd., Samsung Display Co. Ltd., Magneti Marelli S.p.A., Panasonic Automotive Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Display Market Shifts & Advancements
Display technology roadmaps in European automotive are converging on three vectors: panel architecture simplification, regulatory chemistry substitution, and procurement model compression toward direct foundry relationships.
MicroLED backlighting is collapsing the distinction between emissive and transmissive display categories in automotive applications. Luxury OEMs are piloting microLED instrument clusters for extreme temperature cycling performance and anti-glare readability. This technology compression eliminates separate backlight unit supply chains, reducing module thickness and thermal management complexity.
EU Green Deal carbon-border adjustments are reshaping adhesive and optical film sourcing decisions for display manufacturers. Industrial consequence includes accelerated qualification of bio-based and recycled-content chemistries to avoid tariff exposure. Tier 1 module integrators serving German OEMs are most affected, responding with supply chain reconfiguration toward EU-sourced material platforms.
Buyer concentration among Volkswagen Group, BMW, and Mercedes-Benz is compressing procurement cycles toward annual framework agreements with volume commitments. Direct foundry relationships are displacing distributor-mediated component sourcing for strategic display technologies. This shift is most visible in Germany, where OEM headquarters proximity enables just-in-sequence module delivery to final assembly lines.
Europe Automotive Display Market Segmentation
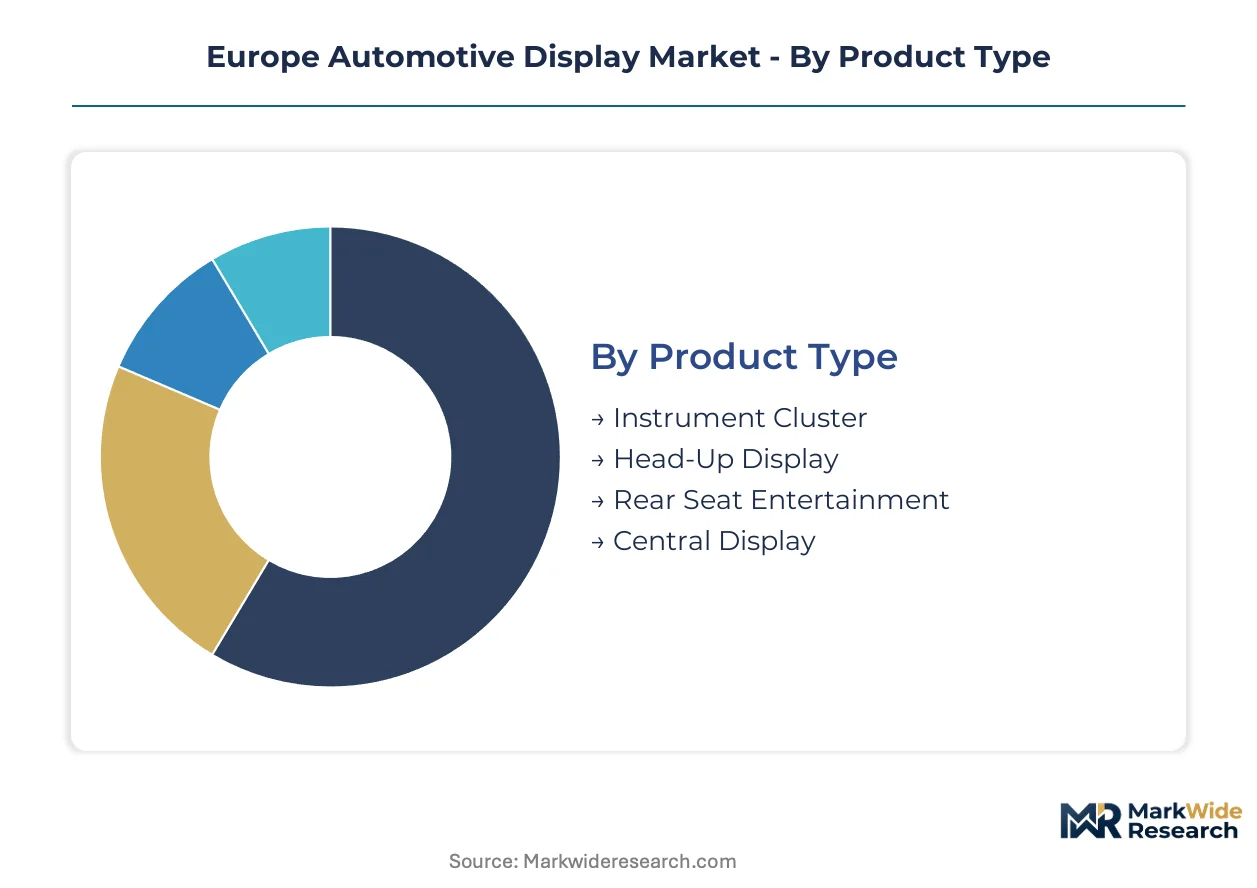
Display module specifications diverge sharply across European automotive applications, with thermal cycling requirements and functional safety certification under ISO 26262 creating distinct procurement tiers. Understanding these segment boundaries enables suppliers to align capacity investments with OEM platform roadmaps and regulatory validation timelines.
Product Type:
Application use case determines display size, brightness specifications, and integration complexity across European vehicle platforms.
- Central Display:These modules consolidate navigation, infotainment, and climate interfaces into unified touchscreen surfaces. Demand concentrates in German premium electric vehicle lines where Volkswagen Group and BMW are expanding screen real estate across ID. and Neue Klasse architectures. EU Green Deal energy efficiency mandates favor larger single displays over distributed button clusters.
- Instrument Cluster:Digital replacements for analog gauges require ASIL-B compliance for speedometer and warning indicator reliability. Procurement from Mercedes-Benz and Stellantis plants in Stuttgart and Turin emphasizes curved glass bonding capabilities for cockpit aesthetic differentiation.
- Head-Up Display:Windshield-projection systems demand precision optics and vibration resistance for ADAS overlay applications.
- Rear Seat Entertainment:Detachable and mounted screens serve luxury limousine configurations with lower volume throughput.
Central Display holds installed capacity. Head-Up Display is rotating up the share rankings.
Technology:
Cost tier and margin structure separate emissive from transmissive panel categories in European supply chains.
- LCD:Thin-film transistor liquid crystal displays dominate commercial vehicle procurement where cost sensitivity and proven supply chains outweigh contrast ratio requirements. Volume leadership persists in fleet van and truck applications across French and Italian OEM portfolios.
- OLED:Organic light-emitting diode panels enable curved form factors and superior black levels for luxury cockpit differentiation. LG Display and Samsung Display foundry commitments anchor supply to BMW and Mercedes-Benz flagship electric vehicle programs.
- LED:Direct-lit and edge-lit configurations serve mid-range passenger vehicle price points with simplified thermal management.
- MicroLED:Gallium nitride micro-emitter arrays pilot for extreme temperature cycling performance in next-generation instrument clusters.
LCD retains volume concentration. OLED is climbing the fastest in revenue contribution.
End User:
Customer type segmentation reflects divergent electrical architecture constraints and cabin packaging priorities across powertrain categories.
- Passenger Vehicles:C-segment and D-segment platforms drive standardized display module specifications across high-volume production lines. German and Czech assembly plants prioritize just-in-sequence delivery compatibility.
- Electric Vehicles:Dedicated battery-electric architectures eliminate legacy 12V distribution constraints, enabling larger curved surfaces without thermal trade-offs. Volkswagen Group MEB and PPE platforms specify integrated module footprints exceeding conventional ICE allowances.
- Luxury Vehicles:Low-volume, high-customization programs absorb premium panel costs for cabin differentiation.
- Commercial Vehicles:Fleet procurement emphasizes durability certification and replacement part availability over display sophistication.
Passenger Vehicles anchor unit demand. Electric Vehicles is gaining share fastest on a percentage basis.
Installation:
Channel configuration determines validation burden and margin capture for module integrators serving European OEMs.
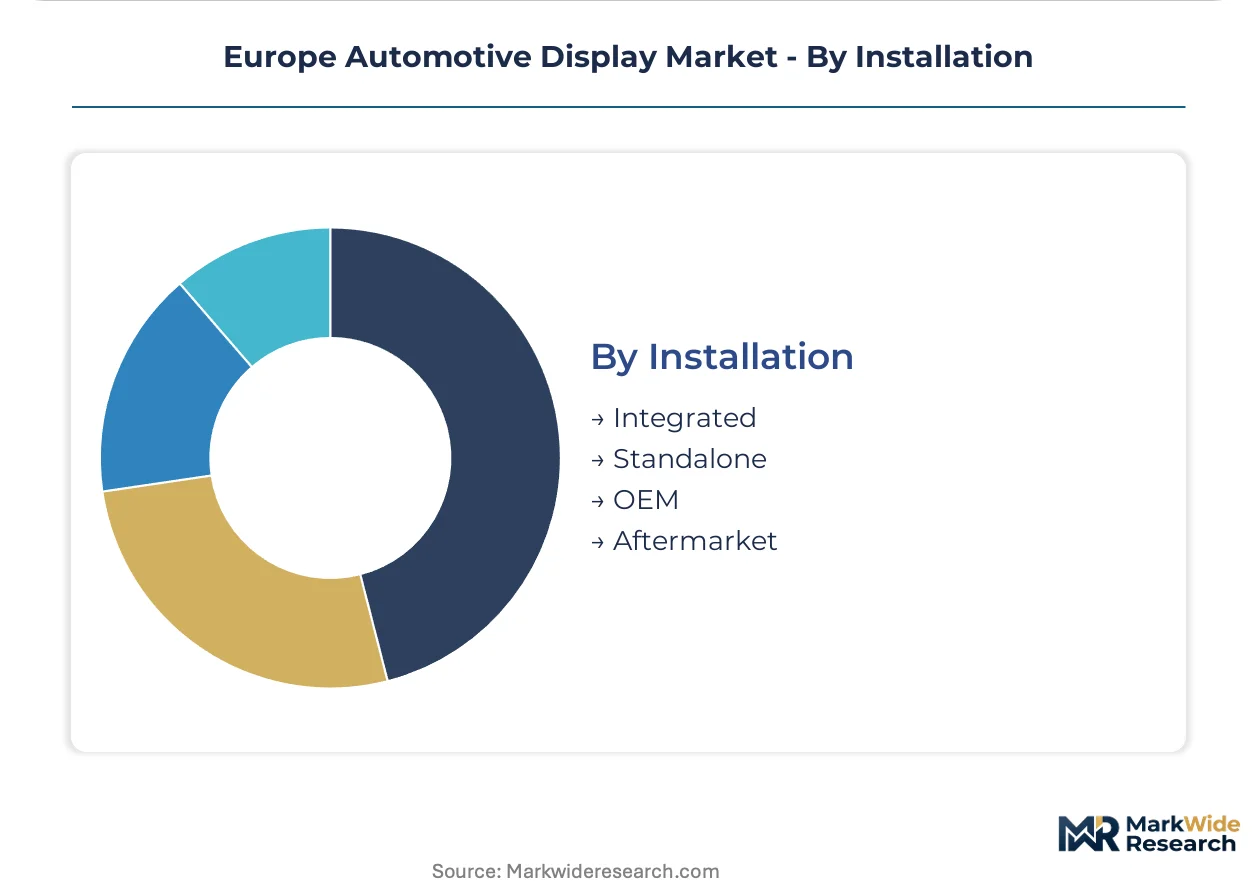
- OEM:Factory-installed modules undergo EMA automotive electronics guidelines validation and CE marking for type approval. Robert Bosch GmbH and Continental AG dominate this channel through direct foundry relationships and captive semiconductor sourcing.
- Integrated:Cockpit modules pre-assembled with HVAC and steering column components reduce final assembly line complexity. Tier 1 integrators near Wolfsburg and Munich coordinate just-in-sequence delivery to Volkswagen Group and BMW plants.
- Standalone:Discrete display units permit aftermarket replacement and upgrade pathways.
- Aftermarket:CE marking requirements under EMA guidelines create certified retrofit opportunities for legacy fleet upgrades.
OEM captures value concentration. Aftermarket is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon-border adjustments and Euro 7 emission standards are channeling display module investments toward jurisdictions with established OEM headquarters and REACH-compliant chemical supply chains. Tier 1 suppliers concentrate near German automotive clusters to synchronize just-in-sequence delivery with final assembly schedules.
Germany
Volkswagen Group, BMW, and Mercedes-Benz headquarters in Wolfsburg, Munich, and Stuttgart drive concentrated demand for curved OLED instrument clusters and integrated central displays. KBA type-approval requirements and CE marking protocols shape product validation timelines for factory-installed modules. Suppliers cluster along the A9 autobahn corridor connecting Bavarian assembly plants with Tier 1 module integrators.
France
Stellantis manufacturing in Sochaux and Mulhouse sustains procurement of ASIL-B certified digital instrument clusters for Peugeot and Citroën electric platforms. ANSM and CNIL guidance on connected vehicle data handling intersects with EMA automotive electronics guidelines for cockpit system validation. The Auvergne-Rhône-Alpes region hosts specialized optical bonding equipment suppliers serving curved glass lamination requirements.
Italy
Ferrari, Lamborghini, and Maserati low-volume luxury programs absorb premium OLED panel costs for cabin differentiation where contrast ratio justifies positioning above commodity alternatives. REACH substance restrictions on display adhesives accelerate qualification of bio-based chemistries among Lombardy-based material suppliers. Magneti Marelli S.p.A. anchors display module integration from its Turin operations corridor.
Czech Republic
Hyundai Motor Manufacturing Czech and Škoda Auto plants in Nošovice and Mladá Boleslav drive standardized central display specifications for high-volume C-segment and D-segment platforms. EU Green Deal energy efficiency mandates favor larger single displays over distributed button clusters in dedicated BEV architectures. Slovakian microLED pilot capacity near the border serves Central European OEM assembly networks.
United Kingdom
Jaguar Land Rover and BMW Mini operations in the Midlands and Oxfordshire sustain demand for premium cockpit modules with curved form-factor capabilities. EMA automotive electronics guidelines and post-Brexit UKCA marking requirements create parallel validation pathways for aftermarket installation channels. Southeast England technology corridors host software layer specialists for human-machine interface integration.
Europe Automotive Display Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated Tier 1 module integrators with captive semiconductor sourcing and direct foundry relationships. Two strategic archetypes dominate: German-headquartered system integrators with in-house production equipment and Korean display foundries extending pilot capacity near European automotive corridors. Competitive moves concentrate on securing OLED supply commitments through project finance partnerships and scaling curved glass bonding capabilities.
Within the integrated Tier 1 tier, Continental AG and Robert Bosch GmbH exemplify archetypes combining captive semiconductor sourcing with in-house production of critical bonding equipment. LG Display Co. Ltd. anchors the display foundry vector, securing supply commitments through proximity to German OEM headquarters. These three entities occupy positions spanning module integration, component supply, and direct OEM relationships without overlapping functional redundancy.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Hyundai Mobis |
| Visteon Corporation |
| LG Display Co. Ltd. |
| Samsung Display Co. Ltd. |
| Magneti Marelli S.p.A. |
| Panasonic Automotive Systems |
| Others |
Supply & Pricing Matrix
OLED foundry undercapacity in South Korea is compressing procurement timelines for European Tier 1 integrators while simultaneously elevating price premiums for ASIL-certified curved display modules. This utilization squeeze forces German OEM procurement offices toward annual volume commitments with direct foundry relationships, bypassing distributor intermediaries that previously absorbed price volatility.
Pricing Analysis
Certification level under ISO 26262 ASIL-B and CE marking creates the primary spread between premium curved OLED instrument clusters and commodity LCD central displays. Three-tier pricing structure across premium, standard, and economy levels stratifies by panel technology, with OLED commanding substantial premiums for form-factor flexibility in Mercedes-Benz and BMW flagship programs. Cost compression in commercial vehicle LCD procurement is intensifying because fleet buyers emphasize replacement part availability over display sophistication. Commercial vehicle fleet managers exhibit highest price sensitivity, while luxury OEM studios absorb premium positioning costs for cabin differentiation.
Supply Chain Analysis
Export-control restrictions on gallium nitride epitaxy equipment limit microLED pilot capacity expansion beyond Korean and Taiwanese foundry footprints. The European automotive display supply chain draws from South Korea for OLED panels, Taiwan for TFT-LCD driver ICs, and Germany for curved glass bonding equipment. Single-source vulnerability concentrates in indium tin oxide transparent electrodes and rare earth phosphors for backlighting units. Distribution runs through just-in-sequence module delivery corridors along the A9 autobahn connecting Bavarian assembly plants with Tier 1 integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon-border adjustments and Euro 7 energy efficiency mandates are compressing display architectures into integrated modules, creating a high-growth disruption window for suppliers with validated material platforms and captive semiconductor sourcing.
For Market Incumbents: Entrench position through backward integration into curved glass lamination equipment and captive OLED supply commitments with LG Display Co. Ltd. and Samsung Display Co. Ltd. Defend against emerging microLED entrants by accelerating ASIL-B certification timelines for next-generation instrument clusters. Priority lever rests on securing annual framework agreements with Volkswagen Group, BMW, and Mercedes-Benz procurement offices before competitor capacity ramps. For New Entrants and Emerging Players: Build out aftermarket CE-marked retrofit channels serving legacy ICE fleet upgrades, where validation burden is lower than OEM factory-install programs. Target Slovakian microLED pilot corridors for proximity to Central European OEM assembly networks. White-space penetration runs through certified standalone replacement modules for commercial vehicle durability requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Tier 1 module integrators with direct foundry relationships and in-house bonding equipment production. Long-term viability over the next decade hinges on positioning upstream of carbon-border adjustment exposure through EU-sourced adhesive and optical film qualification. Signal to monitor: Euro 7 final compliance deadline acceleration forcing display architecture consolidation faster than supplier capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Foundry Partnership | Secures OLED panel allocation from LG Display Co. Ltd. for BMW curved cluster programs. |
| Curved Glass Bonding Capacity | Enables Continental AG to deliver just-in-sequence modules to Volkswagen Group ID. platforms. |
| REACH-Compliant Chemistry Qualification | Positions suppliers ahead of ECHA adhesive restrictions for EU Green Deal tariff avoidance. |
| MicroLED Pilot Scale-Up | Samsung Display Co. Ltd. leverages Slovakian proximity to Hyundai Motor Manufacturing Czech. |
| Aftermarket CE Marking Investment | Creates certified retrofit pathways for legacy Stellantis and Jaguar Land Rover fleet upgrades. |
Research Methodology
A spread of perspectives from Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and EMA regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interviews with curved glass bonding equipment specialists and display adhesive formulators combined with secondary validation from KBA type-approval databases, ECHA REACH substance registrations, and vehicle production data from IHS Markit. Bottom-up module shipment estimates triangulated against top-down OEM platform content projections.
Demand-supply balance modeling across the projection horizon incorporated segmentation by propulsion architecture, vehicle class, panel technology tier, and regional production cluster. CAGRs derived from fitted growth curves applied to OEM platform rollout schedules and BEV adoption pathways. Industry-specific inputs included Euro 7 compliance timeline scenarios and carbon-border adjustment tariff exposure calculations for non-EU sourced chemistries.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Korean display foundries or accelerated Euro 7 enforcement by EU regulators would shift outcomes substantially. Material shifts in REACH substance restriction scope or carbon-border adjustment rate calibration would require updated forecast calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Digital Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
Automotive Rain Sensor Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
South Africa Automotive Electric Actuators Market
Automotive Electrical & Electronics
Middle East and Africa Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
Automotive E/ E Architecture Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
South Korea Electric Power Steering (EPS) Sensor Market