
 Japan X by Wire Systems Market | 2026-2036
Japan X by Wire Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Japan X by Wire Systems Market Insights
Modular bundling of brake-by-wire with steer-by-wire control modules is rebalancing procurement patterns across Japanese vehicle platforms. Nissan Motor leverages its integrated vehicle dynamics platform to sustain engineering partnerships with domestic tier-one suppliers. DENSO Corporation anchors the sensor-to-actuator signal chain through in-house production of motor control units. JTEKT Corporation specializes in redundant steering gear systems that compete on fail-operational performance for Level 3 autonomy.
Japan X by Wire Systems replace mechanical linkages with electronic control units, electric motors, and high-reliability wiring harnesses transmitting driver inputs as digital signals to actuators, typically operating on 12V or 48V architectures with ISO 26262 ASIL-D functional safety ratings. The primary purpose is to reduce vehicle weight, eliminate mechanical maintenance, and enable software-defined vehicle dynamics for autonomous operation. Copper Wires dominate current production volumes due to established shielding techniques and cost-efficient termination methods, while Fiber Optic Cables represent the fastest-expanding material category as bandwidth requirements surge for sensor fusion and real-time control loops. Control Systems applications command the deepest margin pools because firmware validation and cybersecurity certification create substantial barriers to supplier entry.
METI enforces type approval protocols for electronic steering and braking systems through designated technical standards that mandate redundancy validation and electromagnetic compatibility testing. JIS standards and PMDA-aligned functional safety guidelines shape product development timelines and qualification costs for domestic suppliers seeking OEM qualification. Stakeholders must monitor how METI's anticipated updates to autonomous vehicle safety frameworks will recalibrate certification requirements and supplier qualification thresholds.
Market Dynamics
Modular bundling of brake-by-wire with steer-by-wire control modules is compressing supplier qualification timelines and rebalancing procurement patterns across Japanese vehicle platforms. METI's updated safety standards for autonomous driving systems are compelling tier-one suppliers to redesign control interfaces and validation protocols.
Growth Catalysts
- Steer-by-wire architectures:Japanese OEMs are integrating redundant steering gear systems into next-generation electric vehicle platforms to enable software-defined vehicle dynamics.
- METI safety standards:Updated autonomous driving frameworks mandate fail-operational performance thresholds that accelerate replacement of mechanical linkages with electronic control units.
- Kanto corridor concentration:Engineering centers in Tokyo and Yokohama create supplier clustering effects that reduce development cycle times for X-by-wire validation.
Market Restraints
- Copper wire cost volatility:Raw material price swings for shielded copper conductors compress margin pools for wiring harness manufacturers serving volume platforms.
- ASIL-D certification friction:ISO 26262 functional safety validation creates 18-24 month qualification barriers that freeze out mid-tier suppliers from OEM sourcing lists.
- Mechanical linkage residual demand:Commercial vehicle segments in Japan's rural prefectures retain hydraulic steering systems due to service infrastructure lock-in.
Strategic Opportunities
- Fiber optic cable penetration:Bandwidth requirements for sensor fusion architectures create white space for optical signaling in premium electric vehicle platforms.
- Chubu manufacturing belt:Nagoya-centered automotive production offers underpenetrated demand for localized X-by-wire module assembly.
- 48V architecture migration:Convergence of mild-hybrid electrification with steer-by-wire actuation opens new specification tiers for motor control unit suppliers.
Industry Challenges
- Embedded software talent scarcity:Firmware validation for real-time control loops faces acute shortages of engineers with ISO 26262 competency certification.
- Legacy platform integration friction:Retrofitting electronic steering interfaces into existing vehicle architectures demands custom gateway development that extends program timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan X by Wire Systems Market |
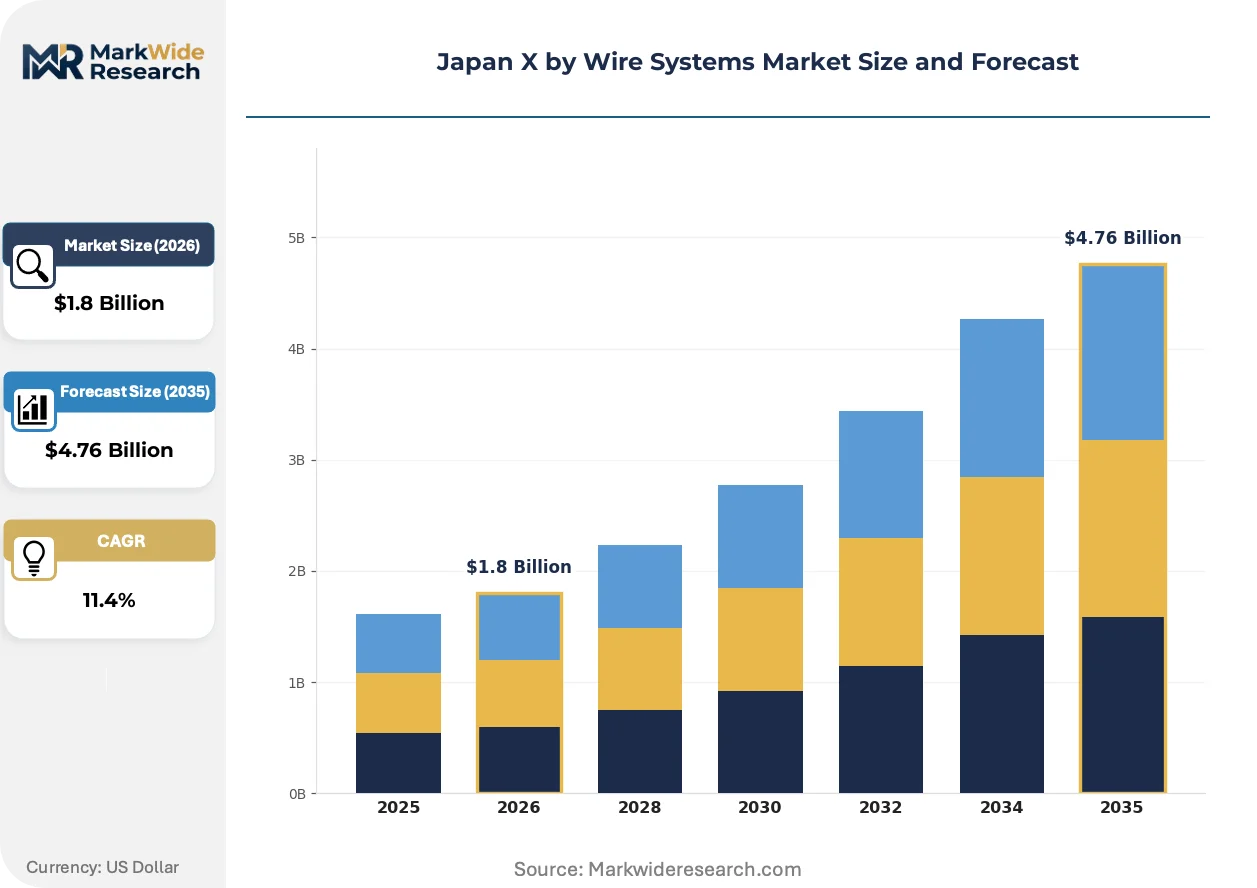
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Wires, Fiber Optic Cables, Aluminum Wires, Coaxial Cables Installation Type: Onshore, Underground, Overhead, Offshore End User: Telecommunications, Power Generation, Construction, Transportation Application: Data Transmission, Power Distribution, Signal Processing, Control Systems |
| Companies Covered | Nissan Motor, DENSO Corporation, Aisin Corporation, JTEKT Corporation, Robert Bosch, Continental AG, ZF Friedrichshafen AG, Infineon Technologies AG, Nexteer Automotive, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan X by Wire Systems Market Trends and Innovations
Digital signal transmission architectures are displacing mechanical control linkages across Japanese vehicle platforms. Three convergent developments are compressing supplier development cycles and redefining competitive positioning in the X-by-wire value chain.
Steer-by-wire systems with redundant torque sensors and brushless DC motors are electrifying the interface between driver input and road wheel actuation. Japanese OEMs are adopting these architectures in premium electric vehicle segments to eliminate steering column intrusion into cabin space. This electrification is compressing the traditional boundary between chassis engineering and embedded software development.
METI's anticipated updates to autonomous vehicle safety frameworks are recalibrating electromagnetic compatibility testing requirements for electronic steering modules. Suppliers must redesign shielding architectures to satisfy revised type approval protocols before platform integration. Domestic tier-one manufacturers are responding by co-locating validation laboratories with OEM engineering centers in the Kanto corridor.
Fleet procurement contracts for rental and mobility service operators are consolidating specification authority away from traditional dealer networks. These buyers now mandate unified X-by-wire control modules across mixed-vehicle fleets to simplify maintenance protocols. The shift is most visible in Tokyo's commercial fleet renewal programs, where standardization clauses override individual OEM preference.
Japan X by Wire Systems Market Segmentation
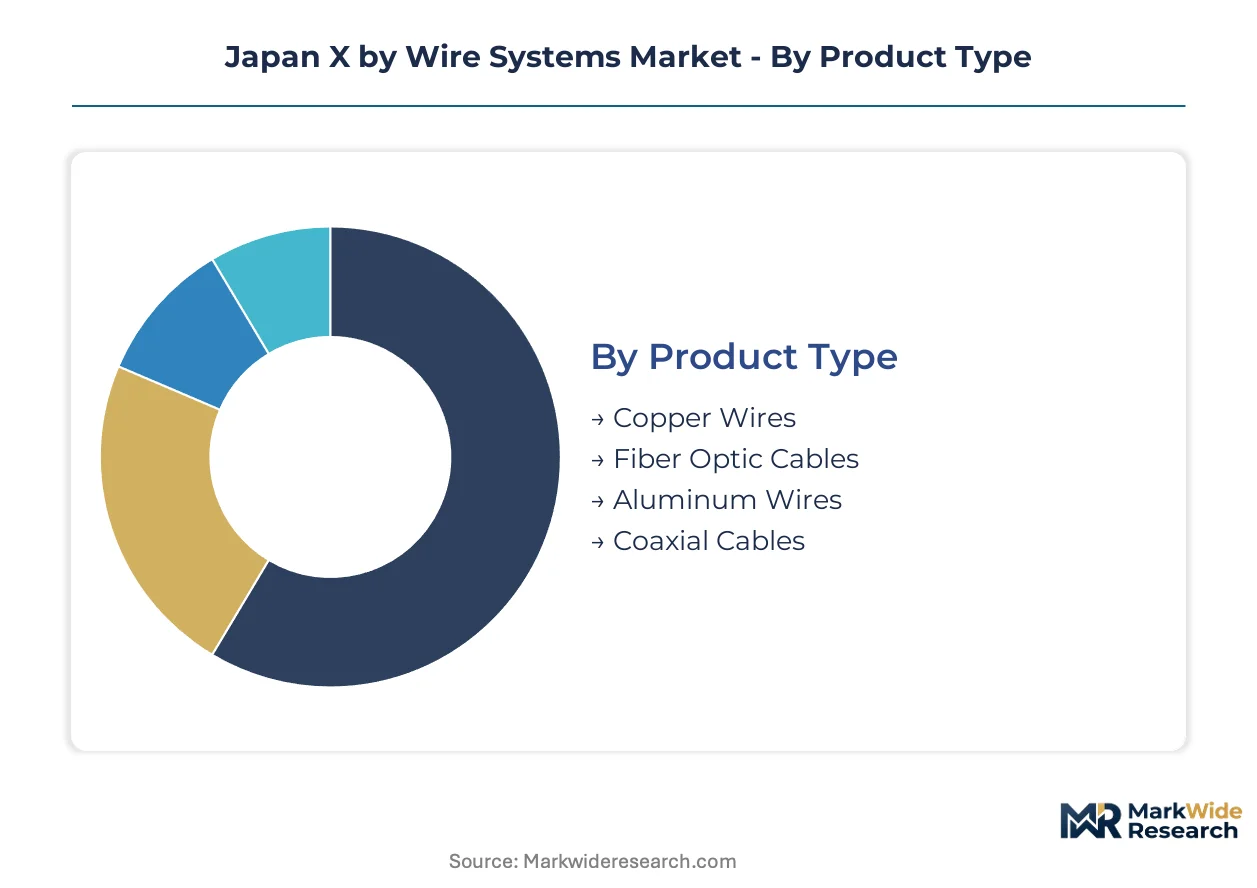
X-by-wire architectures demand precise material specifications across signal transmission pathways. Each segmentation dimension reveals distinct procurement patterns driven by vehicle electrification timelines and autonomous driving certification requirements.
Product Type:
Upgrade cycles in Japanese vehicle platforms are accelerating material transitions as OEMs redesign wiring harnesses for 48V architectures and optical signaling.
- Copper Wires:Shielded copper conductors with twisted-pair configurations dominate current production due to established termination methods and electromagnetic compatibility performance. Volume demand concentrates in mass-market electric vehicle platforms from Nissan and Toyota, where cost engineering priorities favor proven supply chains over bandwidth expansion.
- Fiber Optic Cables:Multi-mode optical fibers transmitting control signals at gigabit speeds enable real-time sensor fusion for Level 3 autonomy systems. Premium electric vehicle programs in the Kanto corridor specify fiber for steer-by-wire feedback loops where latency thresholds fall below mechanical alternatives.
- Aluminum Wires:Lightweight conductors reduce harness mass in battery-electric platforms where every kilogram impacts range certification.
- Coaxial Cables:Specialized shielding preserves signal integrity for high-frequency motor control unit interfaces in redundant steering architectures.
Copper Wires sits at the top of the volume ranking, with Fiber Optic Cables climbing the fastest.
Installation Type:
Cost tier differentiation separates premium vehicle programs with integrated harness routing from economy platforms using conventional pathways.
- Onshore:Standard cabin and chassis routing through protected conduits accounts for the majority of X-by-wire installations in passenger vehicles. Assembly lines in Toyota City and Yokohama optimize onshore harness placement for robotic installation compatibility.
- Underground:Subsurface cable deployment in commercial fleet infrastructure supports charging station connectivity and depot-based maintenance networks. Tokyo's mobility service operators specify underground routing for durability in high-cycling applications.
- Overhead:Exposed harness segments in engine bay and underbody zones require enhanced thermal shielding for power electronics proximity.
- Offshore:Marine-rated X-by-wire systems for coastal commercial vehicles face salt corrosion resistance requirements distinct from automotive standards.
Onshore commands the deepest procurement volumes, while Underground gains share fastest in fleet electrification programs.
End User:
Application maturity varies sharply across customer segments, with automotive transportation demanding ASIL-D certification absent in other verticals.
- Transportation:Automotive OEMs and tier-one suppliers constitute the core demand base for X-by-wire systems, driven by METI autonomous vehicle mandates and electric platform proliferation. Nissan's integrated vehicle dynamics programs and JTEKT's redundant steering gear development anchor procurement concentration in Aichi and Kanagawa prefectures.
- Telecommunications:Fiber optic cable demand from NTT and regional carriers creates secondary volume for optical signaling expertise transferable to automotive applications.
- Power Generation:Utility grid modernization programs specify high-reliability wiring for distributed energy resource integration.
- Construction:Equipment electrification in Komatsu and Hitachi Construction Machinery product lines adopts adapted X-by-wire architectures for remote operation capability.
Transportation dominates current procurement, with Construction expanding most quickly as off-highway electrification accelerates.
Application:
Margin pools concentrate where firmware validation and cybersecurity certification erect substantial barriers to supplier qualification.
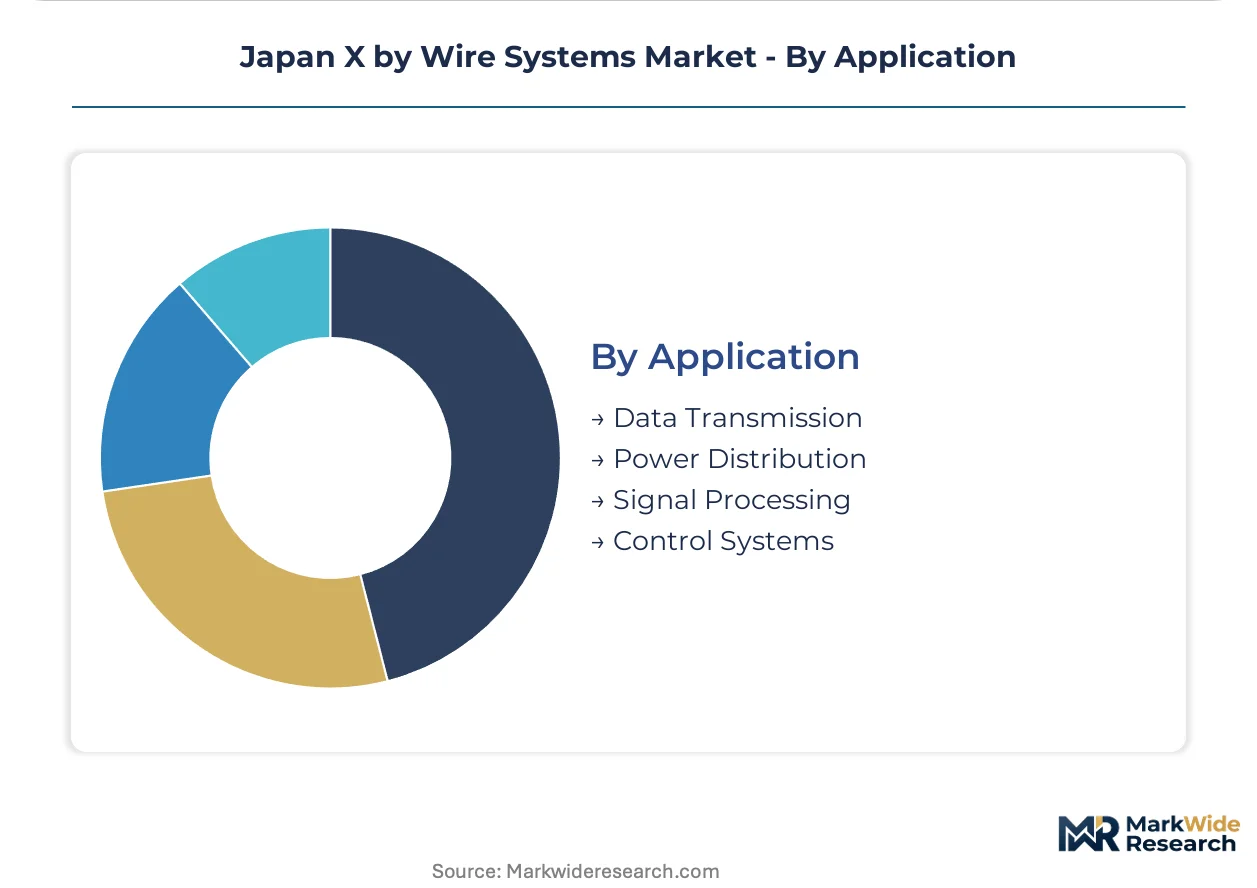
- Control Systems:Real-time actuator command pathways for steer-by-wire and brake-by-wire modules command premium pricing due to ISO 26262 ASIL-D functional safety requirements. DENSO's in-house motor control unit production and embedded software development capabilities defend position in this high-barrier segment.
- Data Transmission:High-bandwidth sensor fusion networks connecting lidar, radar, and camera arrays to central compute platforms drive fiber optic cable specification in premium autonomous vehicle programs.
- Power Distribution:48V architecture migration expands demand for high-current carrying capacity in mild-hybrid electric vehicle platforms.
- Signal Processing:Analog-to-digital conversion pathways in legacy platform retrofits require custom gateway development extending program timelines.
Control Systems captures the deepest margin tier, with Data Transmission gaining specification authority fastest in next-generation autonomous platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
X-by-wire technology matured through Japanese automotive engineering centers, with early steer-by-wire prototypes emerging from Kanagawa prefecture research consortia during the 1990s before commercial deployment in domestic electric vehicle platforms.
Kanto/Tokyo
Tier-one suppliers cluster around Yokohama and Tokyo engineering centers to compress validation cycles for METI-mandated autonomous driving certifications. METI's type approval protocols for electronic steering systems require electromagnetic compatibility testing that domestic firms co-locate near OEM headquarters to satisfy. DENSO anchors sensor-to-actuator production in this corridor, while fleet operators in Tokyo mandate standardized X-by-wire modules across mixed-vehicle procurement.
Kansai/Osaka
Precision manufacturing heritage in Osaka prefecture supports redundant steering gear machining for fail-operational Level 3 systems. JIS standards alignment creates qualification efficiencies for suppliers serving both domestic and export markets from Kansai port infrastructure. Aisin Corporation maintains transmission-adjacent engineering capabilities that extend into brake-by-wire module development for hybrid platforms.
Chubu/Nagoya
Toyota City-centered production creates concentrated demand for high-volume copper wiring harnesses in mass-market electric vehicle programs. The Chubu manufacturing belt remains underpenetrated for localized X-by-wire module assembly relative to Kanto, presenting expansion opportunities for tier-one suppliers. 48V architecture migration in mild-hybrid platforms accelerates specification activity among Nagoya-based motor control unit suppliers.
Kyushu
Semiconductor fabrication facilities in Kumamoto and Fukuoka prefectures supply ASICs for real-time control loops in steer-by-wire actuators. Kyushu's electronics supply chain feeds upstream into Kanto and Chubu assembly operations through specialized logistics networks. Regional technical universities collaborate with automotive OEMs on firmware validation protocols for ISO 26262 compliance.
Tohoku
Materials science research institutes in Sendai advance fiber optic cable durability for underbody automotive deployment. Tohoku suppliers specialize in thermal shielding composites that protect wiring harness segments in engine bay proximity. Rural commercial vehicle segments in this region retain hydraulic steering systems due to service infrastructure constraints that delay X-by-wire penetration.
Japan X by Wire Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across functional safety certification tiers, with ASIL-D validation capabilities determining supplier access to OEM sourcing lists. The market structure concentrates around integrated vehicle dynamics platforms and redundant steering architectures, with tier-one automotive suppliers defending position through captive motor control production. Three archetypes dominate: diversified automotive conglomerates with in-house electronics divisions, specialized chassis component manufacturers with steering gear expertise, and semiconductor suppliers providing ASICs for real-time signal processing. Competitive moves center on co-location of validation laboratories with OEM engineering centers and backward integration into sensor-to-actuator signal chains.
Within the diversified conglomerate tier, Nissan Motor and DENSO Corporation exemplify integrated platform strategies that bundle steer-by-wire with brake-by-wire control modules. JTEKT Corporation occupies a position among specialized chassis manufacturers focused on redundant steering gear systems for fail-operational autonomy requirements. These three Japanese firms anchor domestic supply relationships while competing against German-based Robert Bosch and Continental AG for platform specification authority in next-generation electric vehicle programs.
| Leading Market Players |
|---|
| Nissan Motor |
| DENSO Corporation |
| Aisin Corporation |
| JTEKT Corporation |
| Robert Bosch |
| Continental AG |
| ZF Friedrichshafen AG |
| Infineon Technologies AG |
| Nexteer Automotive |
| Others |
Pricing and Supply Chain Analysis
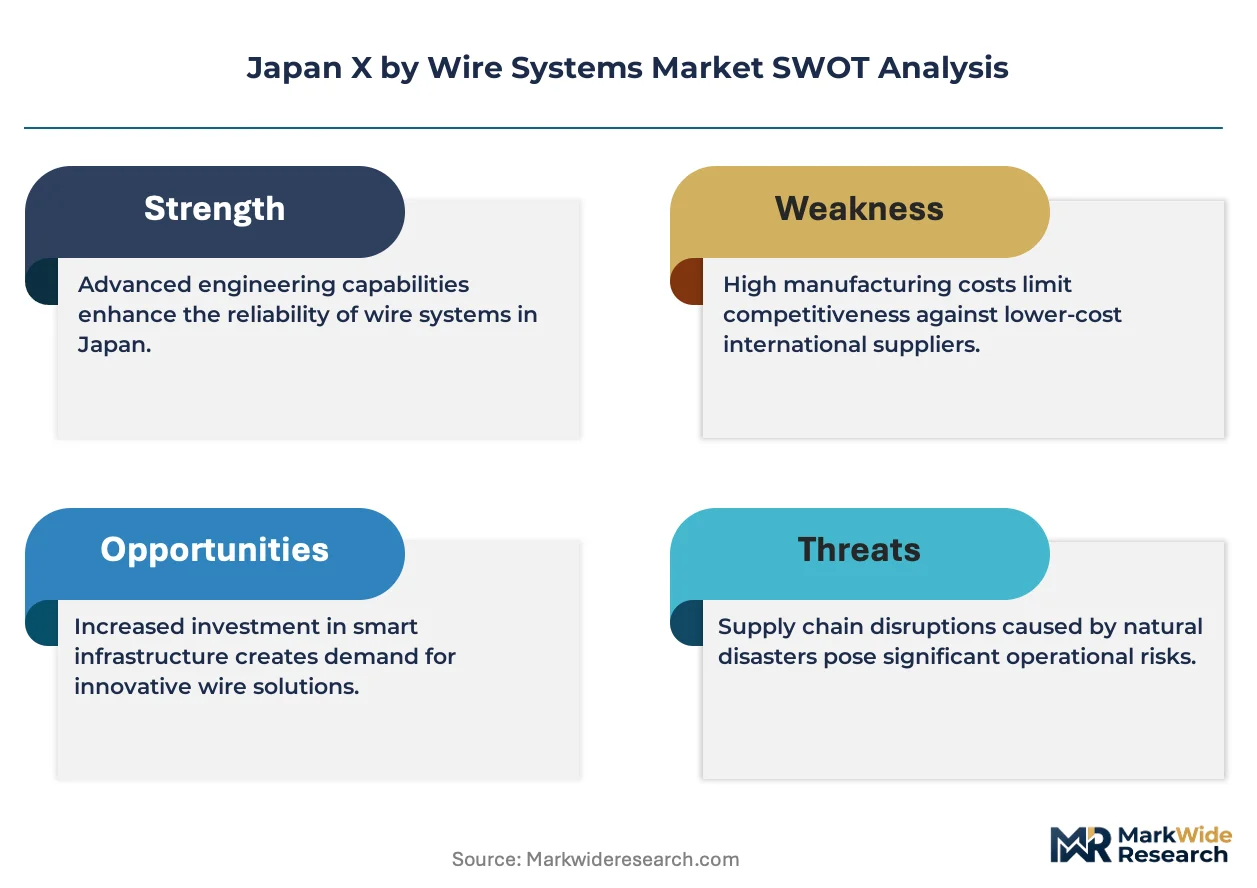
Fleet procurement standardization across Tokyo's commercial mobility operators is compressing specification variance and forcing tier-one suppliers toward unified module architectures that sacrifice margin for volume lock-in. METI's ASIL-D certification mandates add fixed compliance costs that suppliers recover through premium pricing on control systems while absorbing erosion in copper wiring harnesses.
Pricing Analysis
Three-tier pricing structure across ASIL-D certified, ASIL-B intermediate, and non-certified economy levels governs procurement contracts in the Japanese X-by-wire market. Price differentiation rests on ISO 26262 functional safety grade and copper versus fiber optic material selection. Cost compression in copper wiring harnesses is intensifying because raw material volatility and high-volume OEM negotiations squeeze manufacturer margins. Mass-market electric vehicle platforms exhibit acute price sensitivity, while premium autonomous programs prioritize fail-operational performance over unit cost.
Supply Chain Analysis
High-purity copper cathode supply rests on Chilean mining operations and Japanese smelter refinement, with optical fiber preform drawing concentrated in domestic and U.S. facilities. Critical inputs include shielded copper conductors, multi-mode optical fibers, and rare-earth magnets for brushless DC steering motors. Single-source vulnerability pervades ASIC fabrication for real-time control loops, where Kumamoto-based semiconductor foundries anchor regional production. Distribution runs through tier-one supplier direct contracts with OEM engineering centers, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's X-by-wire market functions as a geographic-arbitrage play where METI's stringent autonomous vehicle safety frameworks create regulatory moats that foreign competitors must surmount through domestic validation investment, while Chubu manufacturing underpenetration offers cost-advantaged assembly expansion.
For Market Incumbents: Anchor ASIL-D certification leadership through co-located validation laboratories with Nissan and Toyota engineering centers in Kanto and Chubu corridors. Backward integration into motor control unit production defends margin pools against Bosch and Continental platform incursions. Prioritize fiber optic cable qualification for premium steer-by-wire programs where latency requirements exceed copper capabilities. For New Entrants and Emerging Players: Fiber optic signaling expertise transferable from telecommunications infrastructure creates entry pathways into premium electric vehicle sensor fusion architectures. Chubu module assembly remains underpenetrated relative to Kanto supplier clustering, offering localized production cost advantages. Pursue joint development agreements with Nagoya-based motor control suppliers seeking optical signaling partnerships for 48V architecture migration. For Investors and Strategic Acquirers: Asymmetric upside sits with tier-two wiring harness specialists possessing latent ASIL-D certification capabilities and established OEM relationships. Long-term viability hinges on firmware validation talent scarcity resolution and autonomous platform proliferation across analysis windows. Watch METI safety framework update timing as inflection indicator for certification investment cycles and supplier qualification thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Unlocks tier-one OEM sourcing lists for steer-by-wire and brake-by-wire modules under METI protocols. |
| Fiber Optic Capability Expansion | Captures premium specification in Level 3 autonomy programs requiring sub-millisecond sensor fusion latency. |
| Chubu Manufacturing Footprint | Reduces logistics costs for Toyota City-centered electric vehicle platform assembly relative to Kanto concentration. |
| 48V Architecture Partnership | Aligns motor control unit specifications with mild-hybrid electrification convergence in next-generation platforms. |
| Firmware Validation Laboratory Co-location | Compresses METI electromagnetic compatibility testing cycles through proximity to Yokohama OEM engineering centers. |
Research Methodology
Coverage spans Japan's Kanto, Kansai, Chubu, Kyushu, and Tohoku regions, with primary inputs from each corridor's supplier and OEM concentration. The approach combines structured interviews with tier-one procurement directors, OEM platform engineers, and aftermarket service heads with secondary validation through METI regulatory filings, JIS standards documentation, vehicle production databases, and semiconductor trade flow records. Bottom-up segment sizing triangulates against top-down market value reconstruction across product type, installation configuration, end user vertical, and application function.
Rate-of-change decomposition separates volume expansion from value migration across copper-to-fiber material transitions and 12V-to-48V architecture shifts. Segmentation dimensions model product type, installation pathway, end user industry, and application function, with additional granularity on functional safety certification tier. CAGRs derive from regression-adjusted historical trajectory projection, incorporating ASIL-D penetration curves, autonomous vehicle platform rollout schedules, and fleet electrification procurement patterns throughout the forecast period.
The model holds under stable METI regulatory frameworks and copper price band assumptions; deviation in safety standard acceleration or raw material cost spikes would shift supplier margin distributions and certification investment timelines. Forecasts reflect documented assumptions on technology substitution elasticities and OEM sourcing consolidation trends. A small set of named triggers—METI framework updates, fiber optic cost parity achievement, and tier-two supplier certification success—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Global Automotive Electronic Lock Differential Market
Automotive Electrical & Electronics
Automotive E-Compressor Market
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Stair Lift Motors Market
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
Mexico Automotive EPS Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
Automotive Pressure Sensors Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market