
 GRC Conduit Fittings Market | 2026-2036
GRC Conduit Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
GRC Conduit Fittings Market Insights
Utility procurement consolidation is expanding as regional power providers merge purchasing functions and standardize on galvanized rigid conduit specifications. Atkore International leverages vertical integration from steel coil to finished fittings to sustain margin control across volatile raw material cycles. Zekelman Industries anchors its position through domestic melt-and-manufacture capabilities in North America. Legrand competes on channel density, stocking GRC fittings through electrical wholesale networks that reach mid-sized electrical contractors.
Galvanized rigid conduit fittings are threaded metal connectors fabricated from hot-dip galvanized steel, designed to join, terminate, or change direction in electrical raceway systems rated for physical protection and corrosion resistance in demanding environments. The couplers segment dominates volume shipments due to repetitive installation demand across commercial and infrastructure projects, while elbows command premium positioning in complex routing applications where bend radius compliance matters. Data centers represent the fastest-growing application channel as hyperscale operators specify GRC for critical power distribution corridors requiring electromagnetic shielding and mechanical durability.
NFPA 70 (NEC Article 344) governs GRC installation in the United States, mandating threading standards and zinc coating weights that shape product design and testing protocols. IEC 61386 and UL 6 certifications create tiered market access where uncertified suppliers face exclusion from specification-driven projects. Stakeholders must monitor evolving amendments to national electrical codes and building efficiency standards that will determine which fitting geometries and material grades qualify for public infrastructure spend.
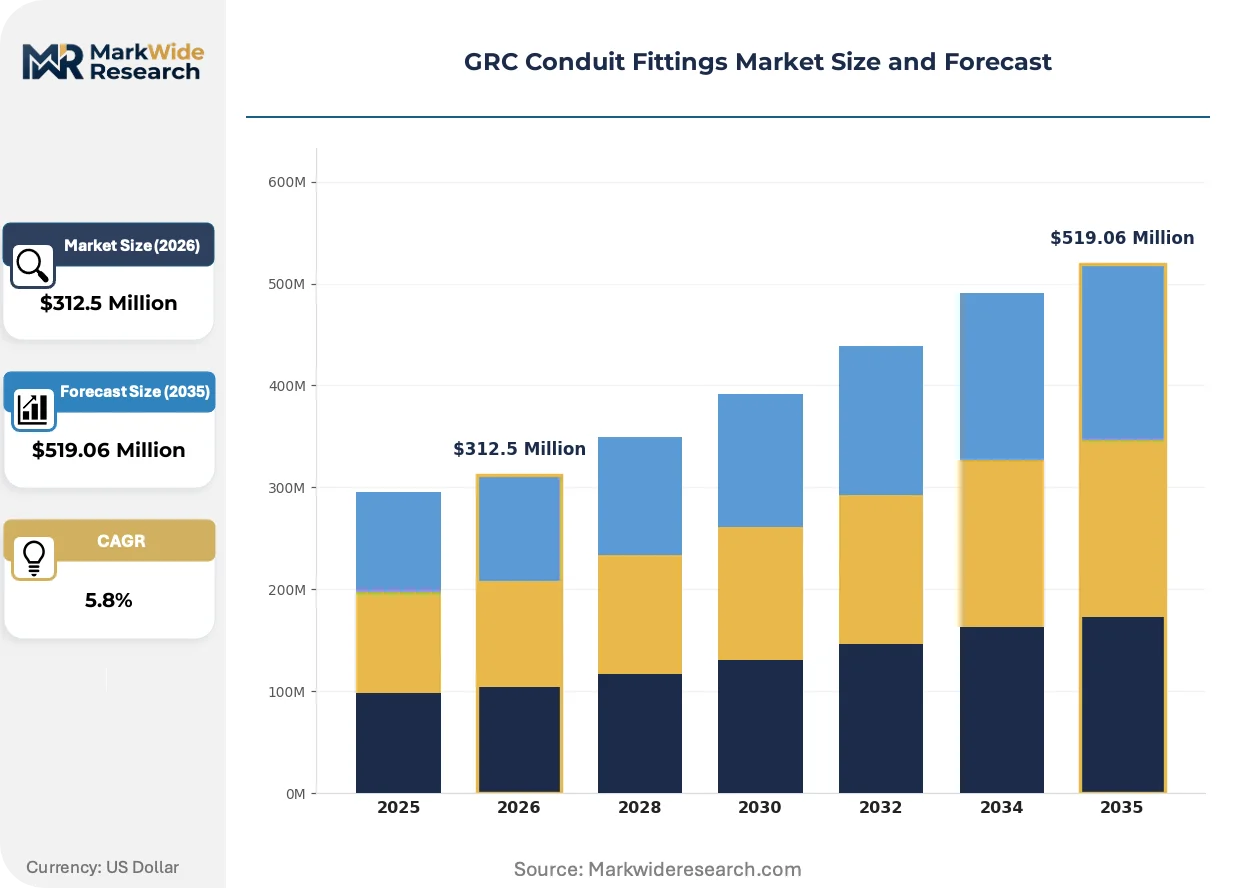
Market Dynamics
Utility procurement consolidation and hyperscale data center construction are compressing supplier margins while demanding higher certification tiers from GRC fitting manufacturers.
Growth Catalysts
- NEC Article 344:Threading and zinc coating mandates in the United States are locking uncertified suppliers out of specification-driven infrastructure projects, concentrating volume among qualified producers.
- Hyperscale data center buildouts:Electromagnetic shielding requirements for critical power corridors in cloud computing facilities are specifying GRC over PVC and aluminum alternatives.
- Grid modernization in India:State electricity boards are replacing legacy distribution infrastructure with galvanized rigid conduit systems rated for outdoor corrosion resistance.
Market Restraints
- Hot-dip zinc price volatility:Coating cost fluctuations compress margins for fabricators without captive galvanizing capacity or long-term steel coil contracts.
- Supply concentration in Chinese steel:Dependence on Hebei and Shandong province mills for substrate coil creates tariff and logistics exposure for non-integrated distributors.
- Threading precision limits:Tight-tolerance NPT requirements for explosion-proof environments reject a measurable share of imported fittings at port inspection.
Strategic Opportunities
- Southeast Asia manufacturing migration:Vietnam and Indonesia offer tariff-advantaged production bases for serving ASEAN electrification programs without China-origin duties.
- Smart conduit integration:Embedding fiber optic sensing cables inside GRC raceways creates bundled offerings for industrial automation and predictive maintenance contracts.
- Buy American compliance:Domestic melt-and-manufacture certification opens federal infrastructure spend under the Infrastructure Investment and Jobs Act.
Industry Challenges
- Certification timeline compression:UL 6 and IEC 61386 testing cycles now exceed twelve months for new fitting geometries, delaying product launches.
- Skilled threading operator scarcity:Precision NPT machining requires journeyman-level machinists that electrical fitting plants struggle to recruit in Midwestern US manufacturing zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GRC Conduit Fittings Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elbows, Couplers, Tees, Bushings, Connectors Material: Galvanized Steel, PVC, Aluminum, Brass, Copper Application: Commercial Buildings, Industrial Facilities, Infrastructure Projects, Data Centers, Educational Institutions End User: Electrical Contractors, EPC Contractors, Facility Management, Utility Providers, Maintenance Companies |
| Companies Covered | Atkore International, American Conduit, Zekelman Industries, Nucor Tubular Products, Legrand, Schneider Electric, Thomas & Betts, Arlington Industries, Elementia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GRC Conduit Fittings Market Trends and Innovations
Threading automation and coating chemistry advances are reshaping how GRC fittings compete on precision and lifecycle cost against polymer alternatives.
Robotic NPT threading systems are absorbing quality variability from manual machining operations. Data center contractors in Northern Virginia and Dallas-Fort Worth are specifying robotic-threaded couplings for mission-critical power distribution corridors. This precision shift is absorbing share from lower-grade imports in specification-sensitive segments.
REACH-compliant hexavalent chromium alternatives are tightening coating chemistry standards across European infrastructure procurement. The restriction on traditional passivation treatments is forcing reformulation of zinc coating post-treatments. German and French electrical wholesalers are now stocking only trivalent chromium-certified fittings for public sector projects.
Direct sourcing from mill-certified fabricators is bypassing traditional electrical wholesale tiers for large contractor accounts. Tier-one data center EPCs in Phoenix and Frankfurt are establishing approved manufacturer lists that eliminate distributor markups on high-volume fitting purchases. This channel compression is most visible in contracts exceeding five thousand units where logistics integration justifies direct relationships.
GRC Conduit Fittings Market Segmentation
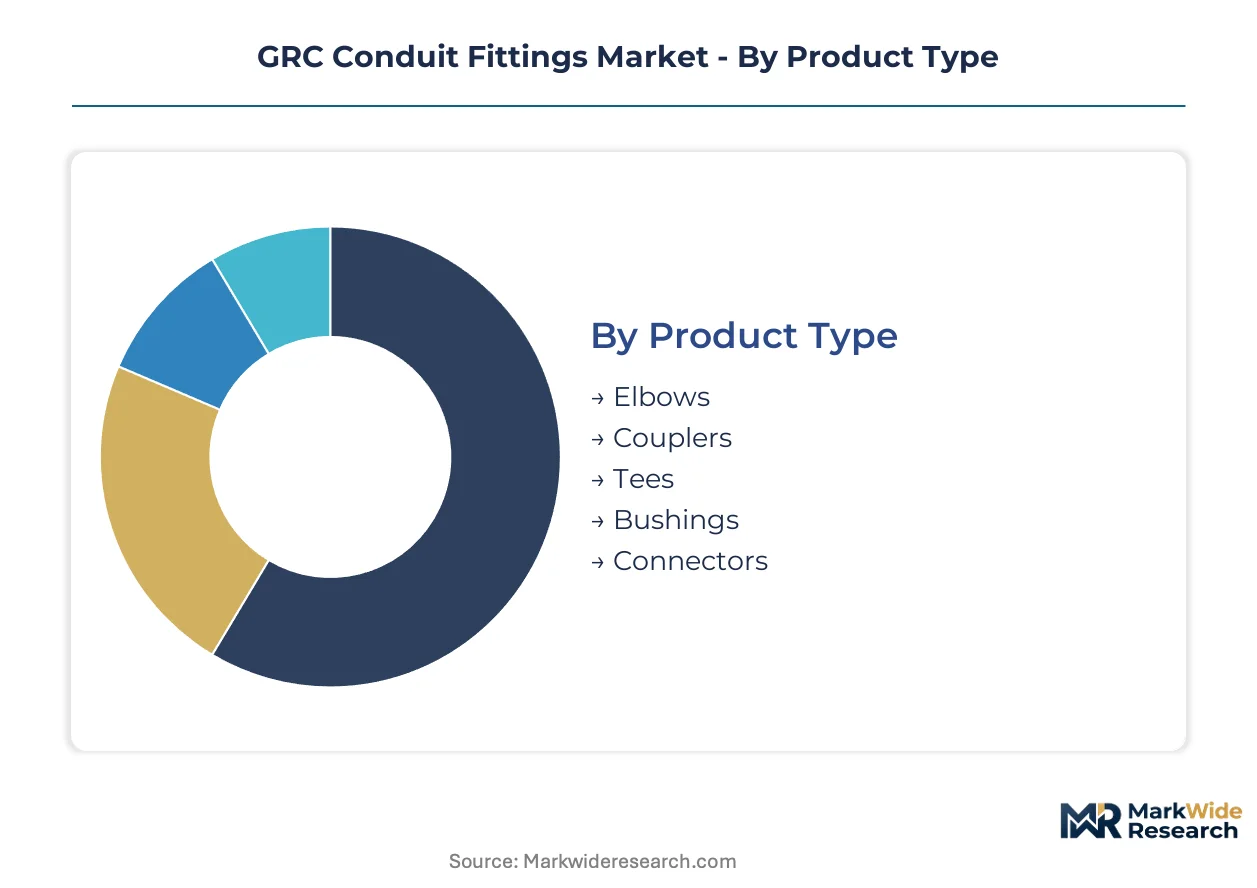
Segmentation in the GRC conduit fittings market reveals how product specifications, material certifications, and end-user procurement power reshape competitive positioning. Understanding these divides exposes where margin concentrates and which channels absorb volume at scale.
Product Type:
Couplers function as standalone connection points in straightforward raceway runs, while elbows and tees embed into complex routing systems where bend radius and directional change requirements dominate specification sheets.
- Couplers:Threaded cylindrical sleeves join straight conduit sections in repetitive commercial and infrastructure installations. Demand clusters in United States utility grid modernization and Indian state electricity board contracts where linear corridor builds predominate. NEC Article 344 threading tolerances and zinc coating weights lock out uncertified imports from these specification-driven channels.
- Elbows:Precision-bent fittings navigate directional changes in confined mechanical spaces. Hyperscale data center EPCs in Northern Virginia and Dallas-Fort Worth specify elbows with tight bend radii for electromagnetic shielding in critical power corridors, commanding premium positioning over standard commercial grades.
- Tees:Three-way junctions branch power distribution in industrial automation environments. German manufacturing facilities specify heavy-wall tees for machine tool power feeds.
- Bushings:Insulated throat fittings protect cable insulation at conduit terminations. Oil and gas facilities in Texas and Louisiana mandate explosion-proof bushing ratings.
- Connectors:Termination hardware anchors raceway systems to enclosures and equipment. Data center contractors in Frankfurt specify compression connectors for rapid installation cycles.
Volume placements concentrate in couplers; the faster expansion belongs to elbows.
Material:
Material selection tracks corrosion exposure severity, electromagnetic interference sensitivity, and total installed cost tradeoffs across project types.
- Galvanized Steel:Hot-dip zinc coating delivers mechanical durability and corrosion resistance for outdoor and industrial environments. United States federal infrastructure spend under the Infrastructure Investment and Jobs Act requires domestic melt-and-manufacture certification, favoring captive steel production over import-dependent competitors.
- Aluminum:Lightweight extrusions reduce labor costs in elevated commercial installations. Indian high-rise construction in Mumbai and Bangalore specifies aluminum for reduced structural load.
- PVC:Non-metallic raceways compete on cost in corrosive chemical environments. REACH-compliant formulations face coating chemistry restrictions in European public sector procurement.
- Brass:Marine-grade corrosion resistance serves coastal and offshore applications. UAE desalination plants specify brass for salt-air exposure.
- Copper:Superior conductivity supports grounding and bonding applications. Hospital electrical systems in Japan specify copper for medical equipment protection.
Galvanized steel absorbs the dominant share of infrastructure and data center specification; aluminum climbs fastest in commercial high-rise construction.
Application:
Application segmentation maps how building codes, operational criticality, and contractor procurement scale reshape fitting demand patterns.
- Data Centers:Hyperscale cloud computing facilities specify GRC for electromagnetic shielding in critical power distribution corridors. Northern Virginia and Dallas-Fort Worth EPCs establish approved manufacturer lists that bypass distributor tiers on high-volume contracts.
- Infrastructure Projects:Grid modernization and transportation electrification demand outdoor-rated corrosion resistance. Indian state electricity boards replace legacy distribution systems with galvanized rigid conduit.
- Commercial Buildings:Office and retail construction drives repetitive coupler demand across standardized electrical plans. United States metropolitan buildouts in Phoenix and Atlanta concentrate volume.
- Industrial Facilities:Manufacturing automation requires explosion-proof and washdown-rated fittings. German automotive plants specify precision-threaded components.
- Educational Institutions:Public school and university construction follows standardized specifications with cost-sensitive procurement. State-level buying cooperatives in Texas aggregate demand.
Commercial buildings generate the highest unit volume; data centers exhibit the steepest expansion trajectory.
End User:
End-user segmentation exposes procurement consolidation trends and technical specification authority that reshape channel economics.
- Electrical Contractors:Mid-sized installation firms purchase through electrical wholesale networks stocking GRC fittings for commercial and light industrial projects. Legrand's channel density reaches this fragmented base.
- EPC Contractors:Engineering-procurement-construction firms on data center and utility projects establish direct manufacturer relationships. Tier-one accounts in Phoenix and Frankfurt eliminate distributor markups on contracts exceeding five thousand units.
- Utility Providers:Regional power providers merge purchasing functions and standardize on galvanized rigid conduit specifications. United States utility procurement consolidation expands volume concentration.
- Facility Management:Corporate and institutional maintenance departments specify replacement fittings for existing infrastructure. Retrofit demand concentrates in aging United States commercial building stock.
- Maintenance Companies:Service contractors respond to emergency repairs and code compliance upgrades. Rapid fulfillment requirements favor distributor stock positions.
Electrical contractors absorb the widest unit dispersion; EPC contractors command the fastest-growing procurement scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement consolidation and hyperscale data center construction concentrate GRC fitting demand in the United States, China, and India. Federal infrastructure programs and national electrical code enforcement are reshaping supplier qualification requirements across these markets.
United States
Data center construction in Northern Virginia and Dallas-Fort Worth drives specification-grade fitting demand for electromagnetic shielding corridors. NEC Article 344 mandates threading standards and zinc coating weights that exclude uncertified imports from federal infrastructure projects. Phoenix EPC contractors establish direct manufacturer relationships for contracts exceeding five thousand units.
China
Hebei and Shandong province steel mills supply substrate coil to domestic fabricators serving grid modernization and commercial buildouts. GB standards and IEC 61386 certification requirements govern product qualification for infrastructure procurement. Yangtze River Delta manufacturing clusters produce fittings for both domestic electrification programs and export markets.
India
State electricity boards replace legacy distribution infrastructure with galvanized rigid conduit systems rated for outdoor corrosion resistance. Central Electricity Authority guidelines influence material specifications for utility-scale projects. Mumbai and Bangalore high-rise construction specifies aluminum alternatives for reduced structural load in commercial towers.
Germany
Automotive manufacturing plants in Bavaria and Baden-Württemberg specify precision-threaded components for machine tool power feeds. REACH-compliant coating chemistry restrictions eliminate hexavalent chromium passivation treatments from public sector procurement. Frankfurt data center EPCs bypass distributor tiers on high-volume fitting purchases.
United Arab Emirates
Desalination plants and coastal infrastructure specify brass fittings for salt-air corrosion resistance. Federal infrastructure standards emphasize material durability for harsh environmental exposure. Dubai construction authorities mandate certified fittings for commercial and industrial electrification projects.
GRC Conduit Fittings Market Competitive Landscape
United States producers anchor one tier; Chinese specialists hold cost-competitive positions in volume segments. The vendor base spans integrated steel producers, electrical component multinationals, and regional fabrication shops. Three archetypes dominate: captive steel producers with galvanizing capacity, channel-dense electrical wholesalers, and precision-threading specialists serving specification-sensitive data center contracts. Consolidation through utility procurement standardization and direct sourcing by tier-one EPCs is compressing distributor margins.
Among North American fabricators, Atkore International, Zekelman Industries, and Legrand occupy distinct competitive positions. Atkore represents the captive-capacity archetype with backward integration into steel coil supply. Zekelman exemplifies domestic melt-and-manufacture positioning for federal procurement compliance. Legrand sits within the channel-density tier, leveraging electrical wholesale networks to reach fragmented contractor bases. Each anchors a different vector of competitive advantage as certification requirements tighten and procurement scales concentrate.
| Leading Market Players |
|---|
| Atkore International |
| American Conduit |
| Zekelman Industries |
| Nucor Tubular Products |
| Legrand |
| Schneider Electric |
| Thomas & Betts |
| Arlington Industries |
| Elementia |
| Others |
Pricing and Supply Chain Analysis
Hot-dip zinc coating costs cascade from Hebei province steel mills through captive galvanizing lines to finished fitting price tiers, threading precision requirements compressing margins for fabricators without in-house NPT machining capacity.
Pricing Analysis
Volume shipments of standard couplers trade on thin margins against premium elbow pricing for data center electromagnetic shielding specifications. Three-tier pricing structure across specification-grade, commercial-grade, and import-economy levels separates UL 6-certified domestic production from tariff-exposed Chinese alternatives. Pricing pressure stems from utility procurement consolidation demanding longer-term contract terms. Mid-sized electrical contractors exhibit highest price sensitivity; hyperscale EPCs prioritize certification compliance over unit cost.
Supply Chain Analysis
Direct-to-EPC channels handle hyperscale buyer demand above five thousand units, bypassing electrical wholesale markups. Hebei and Shandong province steel mills in China, domestic melt-and-manufacture facilities in the United States, and emerging Vietnamese fabrication bases anchor global supply. Substrate coil, hot-dip zinc coating chemicals, and precision threading equipment feed production. Tariff exposure on China-origin steel creates structural vulnerability for non-integrated distributors. Distribution runs through electrical wholesale networks for fragmented contractor accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotic NPT threading systems are displacing manual machining operations, creating technology-transition dynamics that reward precision-automation investment over legacy fabrication.
For Market Incumbents: Hedge against PVC and aluminum substitution in commercial construction by deepening captive steel supply and accelerating UL 6 certification for smart conduit integration. Precision-threading automation in Midwestern manufacturing zones defends specification-grade positioning against lower-cost imports.
For New Entrants and Emerging Players: E-commerce procurement platforms serving maintenance contractors and facility management departments offer white-space entry below tier-one EPC direct-sourcing thresholds. Southeast Asian manufacturing migration targets ASEAN electrification programs without China-origin duty exposure.
For Investors and Strategic Acquirers: Tier-one data center EPC approved manufacturer list expansion is the leading indicator that specification-grade fitting demand is accelerating. Five-to-ten year viability favors precision-threading specialists with captive galvanizing capacity. Watch for utility procurement consolidation announcements as volume-concentration signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Threading Automation Deployment | Robotic NPT systems absorb quality variability from manual machining in Northern Virginia data center corridors. |
| Domestic Melt-and-Manufacture Certification | Buy American compliance unlocks federal infrastructure spend under the Infrastructure Investment and Jobs Act. |
| Southeast Asia Manufacturing Migration | Vietnam and Indonesia bases serve ASEAN electrification without China-origin tariff exposure. |
| Smart Conduit Integration | Fiber optic sensing cable embedding creates bundled predictive maintenance offerings for industrial automation. |
| REACH-Compliant Coating Reformulation | Trivalent chromium alternatives secure European public sector procurement as hexavalent restrictions tighten. |
Research Methodology
Multi-period observation of NEC Article 344 amendment trajectories, utility procurement consolidation patterns, and hyperscale data center construction pipelines anchored the trend analysis, supplemented by interviews with electrical contractor procurement managers, EPC specification engineers, utility supply chain directors, electrical wholesale category buyers, and precision-threading plant operators. Secondary validation drew from UL certification databases, IEC 61386 testing records, FERC infrastructure filings, and customs trade data. Bottom-up fitting shipment estimates triangulated against top-down construction spend allocation models.
Input-output matrices mapped steel coil consumption through galvanizing capacity to finished fitting production across product type, material grade, application channel, and end-user procurement tier dimensions. CAGRs derived from regression analysis of construction spend elasticities and electrification program commitments. Forecast inputs included state electricity board replacement schedules, hyperscaler capex disclosure patterns, and national electrical code enforcement intensity indices.
The model holds under stable zinc pricing and continued NEC Article 344 threading mandate enforcement; deviation in raw material volatility or regulatory relaxation would shift volume toward lower-cost alternatives. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Metal-Faced Insulated Panels Market
Building & Construction Materials
North America Siding and Decking Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
Concrete Densifier Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Global Concrete Block and Brick Manufacturing Market
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
Cultured Marble Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
North America Prefab Wood Building Market