
 Water Leakage Tester Market | 2026-2036
Water Leakage Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Water Leakage Tester Market Intelligence
Software-defined diagnostics is restructuring how water leakage testers create recurring value beyond hardware sales. Honeywell International leverages its building automation ecosystem to bundle cloud-based leak monitoring with sensor hardware. Siemens sustains competitive pressure through industrial IoT platforms that integrate inline testers into factory-wide quality systems. TTK Leak Detection specializes in cable-based distributed sensing, occupying a defensible niche in data center and critical infrastructure protection.
A water leakage tester is an instrument that detects and quantifies fluid escape from sealed assemblies, typically resolving pressure differentials down to 0.1 mbar or detecting mass flow rates below 0.01 sccm depending on the method employed. These systems validate hermetic integrity across packaging, medical devices, automotive components, and electronic enclosures to prevent contamination, corrosion, or functional failure. Inline testers and automated test systems command the strongest margin pools where throughput requirements justify capital-intensive integration into production lines. Portable testers retain relevance in field service and spot-check applications where mobility outweighs cycle-time optimization. Ultrasonic and pressure decay technologies dominate installed bases, though vacuum decay methods gain traction in pharmaceutical and aerospace segments demanding non-destructive validation of complex geometries.
ISO 9001 quality management frameworks, FDA 21 CFR Part 820 quality system regulations, and EU MDR technical documentation requirements collectively elevate testing rigor and documentation burdens for manufacturers serving regulated industries. These standards mandate traceable calibration protocols and repeatable test methods that favor established suppliers with validated software platforms. Stakeholders must monitor evolving sustainability mandates from EU Ecodesign requirements and emerging EPA water stewardship guidelines that could expand leakage detection obligations beyond traditional industrial boundaries.
Market Dynamics
Smart sensor convergence with industrial IoT platforms is restructuring procurement criteria, as buyers prioritize predictive maintenance capabilities and cloud-native diagnostics over standalone hardware specifications.
Growth Catalysts
- FDA 21 CFR Part 820:Medical device manufacturers face intensified sterility validation mandates, driving automated inline tester deployment for hermetic seal verification.
- Vacuum decay technology:Pharmaceutical and aerospace segments adopt non-destructive methods for complex geometries previously untestable with pressure decay approaches.
- German automotive supplier clusters:Battery pack sealing requirements for electric vehicles create sustained demand for high-throughput production line integration.
Market Restraints
- Helium scarcity pricing:Mass spectrometry methods face input cost volatility as helium supply concentrates in geopolitically sensitive extraction regions.
- Calibration equipment concentration:Traceable reference standards depend on a limited supplier base, creating bottleneck risks for manufacturers seeking ISO 17025 compliance.
- Technical limitation:Microfluidic device geometries below 50 microns challenge conventional pressure-based detection thresholds, restricting addressable applications.
Strategic Opportunities
- India PLI scheme:Domestic medical device manufacturing incentives create localized demand for cost-optimized testers with simplified validation protocols.
- Data center liquid cooling:Cable-based distributed sensing systems address thermal management leak detection in hyperscale facilities.
- EU Ecodesign requirements:Water stewardship mandates expand leakage detection obligations to building infrastructure and municipal distribution networks.
Industry Challenges
- Metrology talent scarcity:Qualified calibration technicians and pressure standards engineers remain concentrated in mature industrial economies, constraining service network expansion.
- Legacy system integration:Brownfield manufacturing lines require custom mechanical interfaces and protocol bridges, extending deployment timelines and eroding project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Leakage Tester Market |
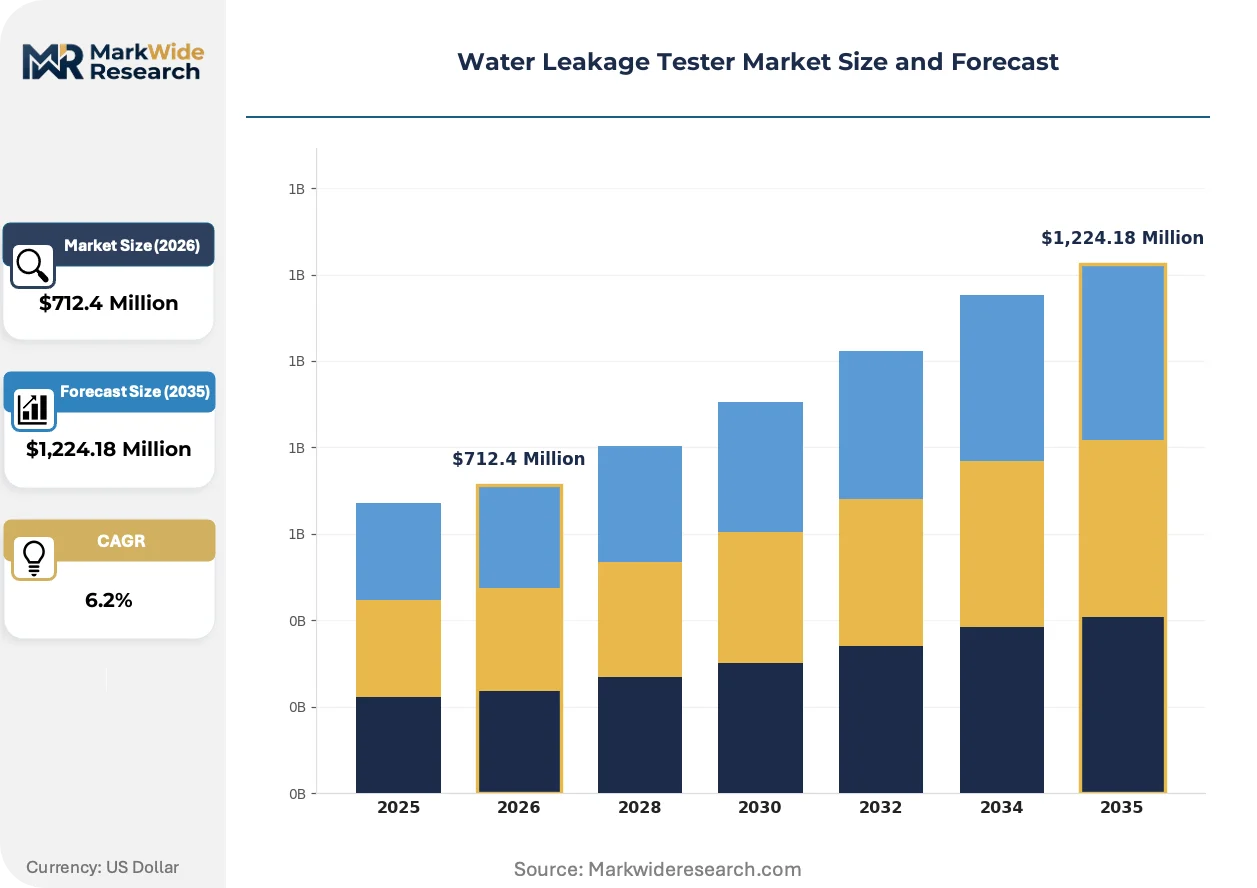
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,224.18 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Testers, Benchtop Testers, Inline Testers, Automated Test Systems, Modular Testers Technology: Pressure Decay, Vacuum Decay, Ultrasonic, Dye Penetrant, Mass Flow, Infrared Detection Application: Packaging Inspection, Home Appliance Quality Control, Medical Device Testing, Automotive Assembly, Electronic Device Sealing, Aerospace Components End User: Manufacturing Plants, Research Laboratories, Quality Assurance Departments, Calibration Services |
| Companies Covered | Honeywell International, Siemens, TTK Leak Detection, Andel, Badger Meter, Perma-Pipe, RLE Technologies, Gutermann AG, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Leakage Tester Market Strategic Shifts & Innovations
Diagnostic capabilities are migrating from hardware-bound functions to software-defined services, compressing equipment replacement cycles while expanding recurring revenue pools for integrated platform providers.
MEMS-based pressure sensors are integrating with edge computing architectures to enable real-time leak signature analysis without centralized processing delays. Automotive battery manufacturers in South Korea and Japan deploy these systems for 100% inline testing of pouch cell seals. The technology is integrating machine learning models that distinguish acceptable process variation from genuine defect signals, reducing false rejection rates.
EU MDR technical documentation requirements now mandate traceable test data retention exceeding product lifecycles, forcing manufacturers to adopt blockchain-anchored audit trails. Sterile barrier packaging suppliers face expanded validation scope for complex multi-material seals. German medical device exporters invest in automated test management systems to preempt notified body scrutiny during conformity assessments.
Buyer organizations are consolidating supplier relationships around full-stack diagnostic platforms rather than point-solution hardware vendors. Japanese electronics OEMs now require API-accessible test data feeds for direct MES integration, displacing traditional standalone instruments. This concentration is most visible in precision manufacturing clusters where quality system unification reduces audit complexity and training overhead.
Water Leakage Tester Market Segmentation
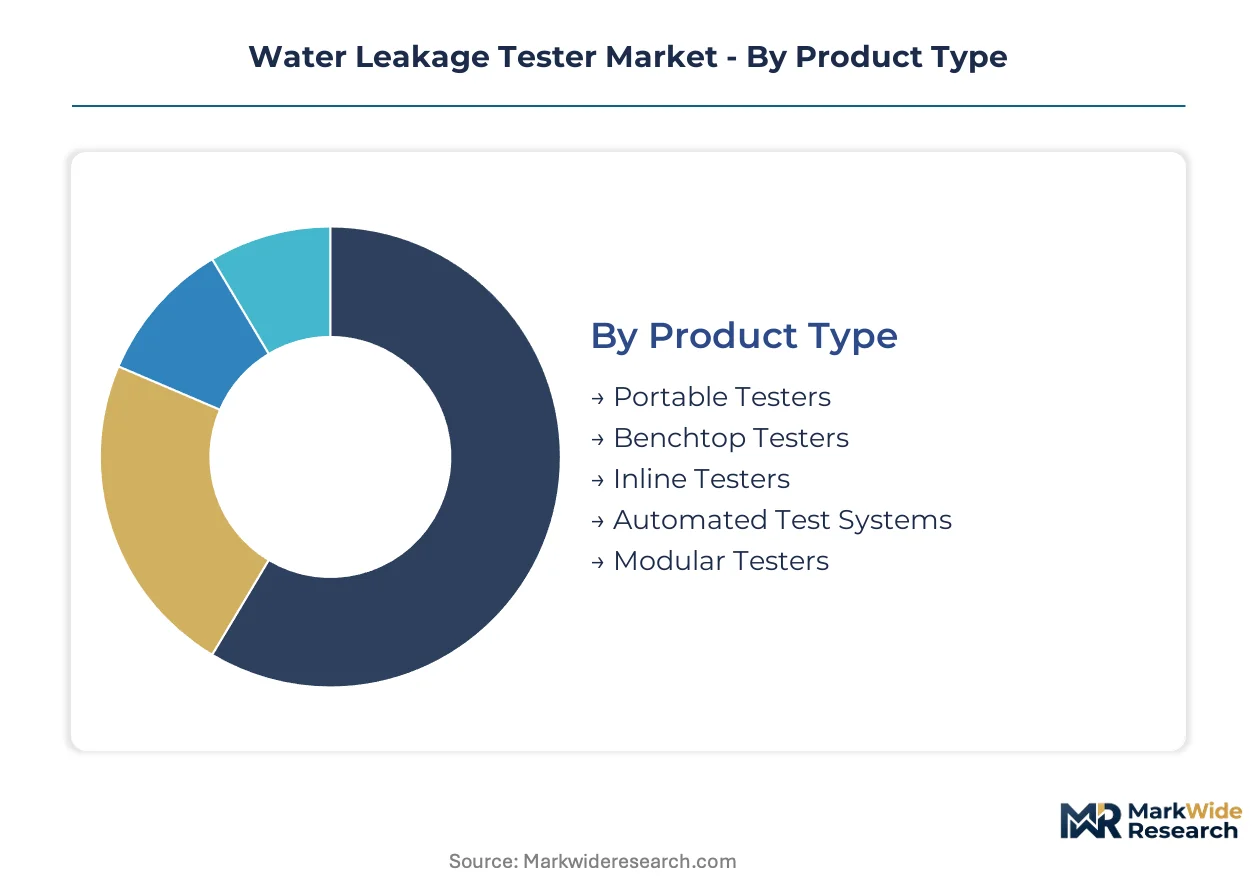
Water leakage tester procurement decisions diverge sharply across operational contexts. Production line managers prioritize throughput and integration depth, while field service teams value portability and rapid deployment. Understanding these segment boundaries clarifies where technology investments concentrate and which specifications command price premiums.
Product Type:
Capital intensity and throughput requirements dictate buyer selection across product categories, with automation level serving as the primary cost differentiator.
- Inline Testers:These systems integrate directly into production conveyors for 100% inspection at cycle times under 10 seconds. German automotive battery manufacturers deploy these for pouch cell seal verification where line stoppage costs exceed equipment amortization within months.
- Automated Test Systems:Multi-station configurations combine robotic handling with programmable test sequences for complex assemblies. Medical device manufacturers serving FDA-regulated markets favor these for documented repeatability and 21 CFR Part 820 compliance.
- Portable Testers:Battery-powered units enable field validation of installed systems without production disruption.
- Benchtop Testers:Laboratory-grade precision suits R&D environments and small-batch validation.
- Modular Testers:Configurable architectures allow capability expansion as test requirements evolve.
Inline testers lead on scale; automated test systems lead on momentum.
Technology:
Detection sensitivity and material compatibility determine technology adoption, with non-destructive methods gaining preference in high-value component testing.
- Vacuum Decay:Pharmaceutical blister packs and aerospace fuel system components require detection thresholds below 0.01 sccm without fluid contact. This method eliminates contamination risk while validating complex geometries inaccessible to pressure-based alternatives.
- Pressure Decay:Automotive cooling circuits and industrial valve assemblies rely on this established approach for its speed and equipment simplicity. Japanese electronics OEMs specify pressure decay for consumer device enclosure testing where throughput exceeds sensitivity demands.
- Ultrasonic:Acoustic emission detection suits pressurized systems and external surface scanning.
- Mass Flow:Direct measurement methods serve applications requiring quantitative leak rate certification.
- Infrared Detection:Thermal imaging identifies temperature anomalies from evaporative cooling at leak sites.
- Dye Penetrant:Visual inspection methods persist in low-cost, destructive testing environments.
Pressure decay dominates installed base; vacuum decay is expanding most quickly.
Application:
Regulatory stringency and liability exposure create tiered demand patterns across end-use sectors.
- Medical Device Testing:EU MDR technical documentation mandates traceable seal validation for sterile barrier systems. German exporters invest in automated test management to preempt notified body scrutiny during conformity assessments.
- Automotive Assembly:Electric vehicle battery pack sealing requirements drive high-throughput production line integration. South Korean and Japanese manufacturers deploy MEMS-based sensors for real-time pouch cell seal analysis.
- Packaging Inspection:Food and pharmaceutical barrier systems require integrity verification.
- Electronic Device Sealing:Ingress protection ratings for smartphones and wearables necessitate precision testing.
- Aerospace Components:Fuel and hydraulic systems demand non-destructive validation under extreme specification ranges.
- Home Appliance Quality Control:Washing machine and dishwasher manufacturers test component sealing.
Automotive assembly leads on scale; medical device testing leads on momentum.
End User:
Organizational function shapes procurement authority and technical specification priorities.
- Manufacturing Plants:Production engineering teams specify inline integration and MES connectivity. Japanese electronics OEMs now require API-accessible test data feeds, displacing traditional standalone instruments.
- Quality Assurance Departments:Validation groups prioritize documented calibration traceability and audit trail completeness. ISO 9001 frameworks mandate repeatable test methods favoring established suppliers with validated software platforms.
- Research Laboratories:R&D functions emphasize measurement precision and method flexibility.
- Calibration Services:Third-party providers require portable reference standards and multi-manufacturer compatibility.
Manufacturing plants lead on scale; quality assurance departments lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier clusters demand high-throughput inline testers for EV battery sealing, while Japanese electronics OEMs prioritize MEMS-integrated systems for consumer device validation. Regulatory divergence between FDA 21 CFR Part 820 in the United States and EU MDR technical documentation requirements shapes distinct procurement patterns across these precision manufacturing hubs.
United States
Medical device manufacturers serving FDA-regulated markets deploy automated test systems for hermetic seal verification under 21 CFR Part 820 quality system regulations. The FDA's intensified sterility validation mandates accelerate capital expenditure on inline testers with documented calibration traceability. Greater Boston's medical device corridor anchors demand for systems integrating blockchain-anchored audit trails exceeding product lifecycles.
Germany
Automotive battery pack sealing requirements for electric vehicles sustain demand for vacuum decay and pressure decay technologies with sub-10-second cycle times. The KBA's evolving type-approval standards for EV safety systems pressure suppliers to validate complex multi-material seals. Stuttgart and Munich supplier clusters invest in automated test management systems to preempt notified body scrutiny during EU MDR conformity assessments.
Japan
Electronics OEMs specify API-accessible test data feeds for direct MES integration, displacing traditional standalone instruments across consumer device manufacturing. METI's industrial IoT promotion policies accelerate smart sensor convergence with edge computing architectures. Kyushu's semiconductor packaging facilities deploy MEMS-based pressure sensors for real-time pouch cell seal analysis with machine learning-enabled defect classification.
China
Domestic medical device manufacturing scales under NMPA regulatory alignment with international standards, creating demand for cost-optimized testers with simplified validation protocols. The country's dual carbon goals expand leakage detection obligations to hydrogen fuel cell component manufacturing. Yangtze River Delta battery producers integrate cloud-native diagnostics into factory-wide quality systems.
India
The PLI scheme for domestic medical device manufacturing generates localized procurement of benchtop and modular testers for small-batch validation. CDSCO's progressive alignment with ISO 13485 quality management frameworks elevates documentation burdens for sterile barrier packaging suppliers. Maharashtra and Gujarat medical device parks attract investments in automated test systems with traceable calibration protocols.
Water Leakage Tester Market Key Industry Players
Top-tier vendors anchor platform-based competition, while mid-tier specialists occupy technology-specific niches. The vendor base stratifies across three tiers: diversified industrial conglomerates bundling leakage detection into automation ecosystems, focused instrumentation specialists defending positions in cable-based or ultrasonic methods, and regional fabricators serving cost-sensitive procurement in emerging manufacturing hubs. Two dominant competitive moves reshape positioning: industrial IoT platform integration to capture recurring software revenue, and strategic partnerships with battery cell manufacturers to secure inline tester deployment at greenfield EV facilities.
Within the diversified industrial tier, Honeywell International and Siemens exemplify platform-centric strategies that bundle hardware with cloud-native diagnostics. TTK Leak Detection occupies a defensible position among cable-based distributed sensing specialists serving data center and critical infrastructure applications. Emerson Electric represents the instrumentation archetype integrating leakage detection into broader process automation portfolios. These three anchors illustrate how competitive positioning increasingly depends on software-defined service layers rather than standalone hardware specifications.
| Leading Market Players |
|---|
| Honeywell International |
| Siemens |
| TTK Leak Detection |
| Andel |
| Badger Meter |
| Perma-Pipe |
| RLE Technologies |
| Gutermann AG |
| Emerson Electric |
| Others |
Cost & Logistics Intelligence
Helium scarcity pricing cascades from geopolitically sensitive extraction regions through mass spectrometry tester tiers, compressing margins for manufacturers dependent on trace gas methods while vacuum decay alternatives capture price premiums from pharmaceutical buyers seeking non-destructive validation.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for MEMS-integrated inline testers, eroding premium capture for legacy pressure decay equipment. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated automated systems from benchtop units and portable field-service instruments. Price differentiation hinges on ISO 17025 calibration certification and MES integration depth. Cost compression in the economy tier intensifies because regional fabricators in India and Vietnam undercut established suppliers on small-batch validation equipment. Quality assurance departments at German automotive suppliers demonstrate lowest price sensitivity, prioritizing sub-10-second cycle times over capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with helium refining capacity concentrated in Qatar and the United States, exposing mass spectrometry method users to input cost volatility. Manufacturing draws from precision machining clusters in Germany, sensor fabrication in Japan, and final assembly in China. Raw material dependencies include stainless steel pressure vessels, MEMS die from Taiwanese foundries, and specialized elastomer seals. Tariff exposure runs through component flows subject to trans-Pacific trade friction. Distribution runs through direct OEM relationships for inline systems and regional distributor networks for portable and benchtop units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined service layers expand recurring revenue pools beyond hardware replacement cycles, with cloud-native diagnostics commanding margin premiums that offset capital equipment commoditization.
For Market Incumbents: Acquire edge computing and machine learning capabilities to defend against MEMS-integrated challengers eroding traditional pressure decay markets. Deepen backward integration into sensor fabrication through partnerships with South Korean semiconductor packaging facilities. Lock in long-term helium supply contracts or accelerate vacuum decay R&D to decouple from mass spectrometry input volatility.
For New Entrants and Emerging Players: Begin with cable-based distributed sensing for data center liquid cooling applications, where TTK Leak Detection's established position leaves room for cost-optimized alternatives. Target India's PLI scheme medical device parks with simplified validation protocols that undercut FDA-tier documentation burdens. Pursue API-first architectures that bypass incumbent software lock-in at Japanese electronics OEMs.
For Investors and Strategic Acquirers: Consolidation pressure builds where metrology talent scarcity constrains service network expansion for mid-tier instrumentation specialists. Position for platform roll-ups combining hardware vendors with cloud-native diagnostics providers over a multi-year industrial IoT adoption window. Monitor EU Ecodesign enforcement timing as the signal indicating when building infrastructure leakage detection obligations expand addressable market boundaries.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundles Honeywell's cloud-based leak monitoring with sensor hardware for recurring SaaS revenue. |
| Acquisition of Specialist Firm | Consolidates cable-based sensing capabilities serving hyperscale data center thermal management. |
| Strategic Partnership | Secures inline tester deployment at greenfield EV battery facilities through cell manufacturer alliances. |
| Product Launch | Introduces MEMS-based edge computing architectures enabling real-time leak signature analysis without latency. |
| Geographic Expansion | Establishes calibration service networks in India and Southeast Asia addressing metrology talent concentration gaps. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with production engineering directors, quality assurance managers, biomedical equipment procurement leads, and aftermarket service heads informed operational requirements and purchasing criteria. Secondary validation drew from FDA 21 CFR Part 820 guidance documents, EU MDR technical documentation specifications, ISO 17025 accreditation records, and industrial automation trade databases. Triangulation between demand-side capital expenditure patterns and supply-side production capacity announcements ensures coherence across volume and value estimates.
Historical trendline analysis of technology adoption curves and regulatory implementation timelines anchors projection methodology across the modeling period. Segmentation dimensions include product automation level, detection technology, application sector, and end-user organizational function. CAGRs derive from fitted growth curves adjusted for industry-specific inputs including battery electric vehicle production ramp rates, medical device sterility validation mandate expansion, and data center liquid cooling infrastructure buildout.
Several conditions sit outside the modeled scope, including unannounced regulatory preemptions, abrupt helium supply disruptions, and breakthrough detection technologies displacing established methods. Forecasts reflect documented assumptions about compliance timeline adherence and capital expenditure continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Calorimeters Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Shock Testing System Market
Test and Measurement
Automated Optical Inspection (AOI) System Market
Test and Measurement
Thin Film Metrology Systems Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
United States Borescope Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
Miniaturized Package Solder Joint Reliability Test Equipment Market
Test and Measurement
Shock Data Logger Market
Test and Measurement
Psophometer Market