
 High Voltage Testing Market | 2026-2036
High Voltage Testing Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Testing Market Foresight
The EU F-Gas Regulation is repositioning equipment certification requirements across European high-voltage testing workflows, forcing manufacturers to redesign gas-insulated test setups for lower global-warming-potential alternatives. BAUR GmbH leverages its Austrian manufacturing base to dominate cable fault location systems for medium-to-high voltage grids. Megger Group Limited anchors its position through deep R&D investment in portable AC and DC test sets for field deployment. OMICRON Electronics GmbH differentiates by specializing in dissolved gas analysis and partial discharge monitoring for transformer health assessment.
High voltage testing encompasses the controlled application of electrical stress above rated operating levels to verify insulation integrity, dielectric strength, and equipment safety margins in power apparatus, typically involving test voltages from 50 kV AC or DC up to several megavolts for ultra-high-voltage research. The practice serves to prevent catastrophic failures in transformers, switchgear, and cable systems by detecting latent defects before energization under load. Test Equipment commands the largest revenue pool given the capital intensity of impulse generators and resonant test systems, while Partial Discharge Testing represents the fastest-expanding technique dimension as utilities prioritize predictive maintenance over scheduled replacement. The Renewable Energy Sector end-user category is gaining share fastest, driven by offshore wind array commissioning protocols that mandate full-sequence high-voltage verification before grid synchronization.
FDA oversight applies to medical-grade isolation transformers requiring high-voltage hipot validation, while IEEE C37.20 and IEC 62271 shape product design rules for switchgear testing apparatus sold into North American and European markets respectively. China's GB standards and NMPA-equivalent electrical safety mandates impose additional conformity layers for imported test equipment. India's CEA grid codes and BIS certification requirements are tightening procurement specifications for domestic utilities. Stakeholders must monitor how carbon-border adjustment mechanisms and embodied-emission tracking reshape the total cost of ownership for gas-insulated test systems relative to air-insulated alternatives.
Market Dynamics
Grid operators across Germany, China, and the United States are accelerating high-voltage validation cycles as aging infrastructure collides with renewable interconnection mandates, forcing testing protocols to compress from scheduled maintenance into continuous monitoring architectures.
Growth Catalysts
- IEC 62271 Dielectric Thresholds:European utilities are retrofitting switchgear test bays to meet tightened partial discharge limits, triggering replacement demand for resonant test systems.
- Offshore Wind Commissioning:Array developers in the North Sea and East China Sea mandate full-sequence high-voltage verification before grid synchronization, embedding testing into project finance covenants.
- Sulfur Hexafluoride Phase-Down:The EU F-Gas Regulation is forcing gas-insulated test equipment redesign toward fluoronitrile blends, opening retrofit service contracts for installed bases.
Market Restraints
- Copper and Rare-Earth Input Costs:Resonant reactor and impulse generator manufacturers face margin compression from commodity volatility in magnet wire and ferrite cores.
- Specialized High-Voltage Engineering Talent:The pool of technicians qualified for megavolt-class field testing is contracting in OECD markets, constraining deployment velocity.
- SF6 Alternative Technical Maturity:Fluoronitrile-based test setups exhibit higher liquefaction temperatures, limiting operational envelopes in Nordic and Alpine climates.
Strategic Opportunities
- India CEA Grid Code Alignment:Domestic utilities are importing test equipment to meet tightening BIS certification requirements, creating first-mover advantages for localized assembly partnerships.
- Digital Twin Convergence:Integration of partial discharge sensors with asset performance management platforms is enabling subscription-based predictive maintenance revenue streams.
- Mobile Test Fleet Deployment:Rental and on-demand field testing services are penetrating transmission owner markets that lack capital for captive equipment.
Industry Challenges
- Multi-Standard Certification Timelines:Equipment vendors must sequence IEC, IEEE, and GB standard approvals sequentially, stretching product launch windows.
- Legacy GIS Integration Complexity:New low-GWP test setups must interface with existing sulfur hexafluoride infrastructure without contaminating gas compartments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Testing Market |
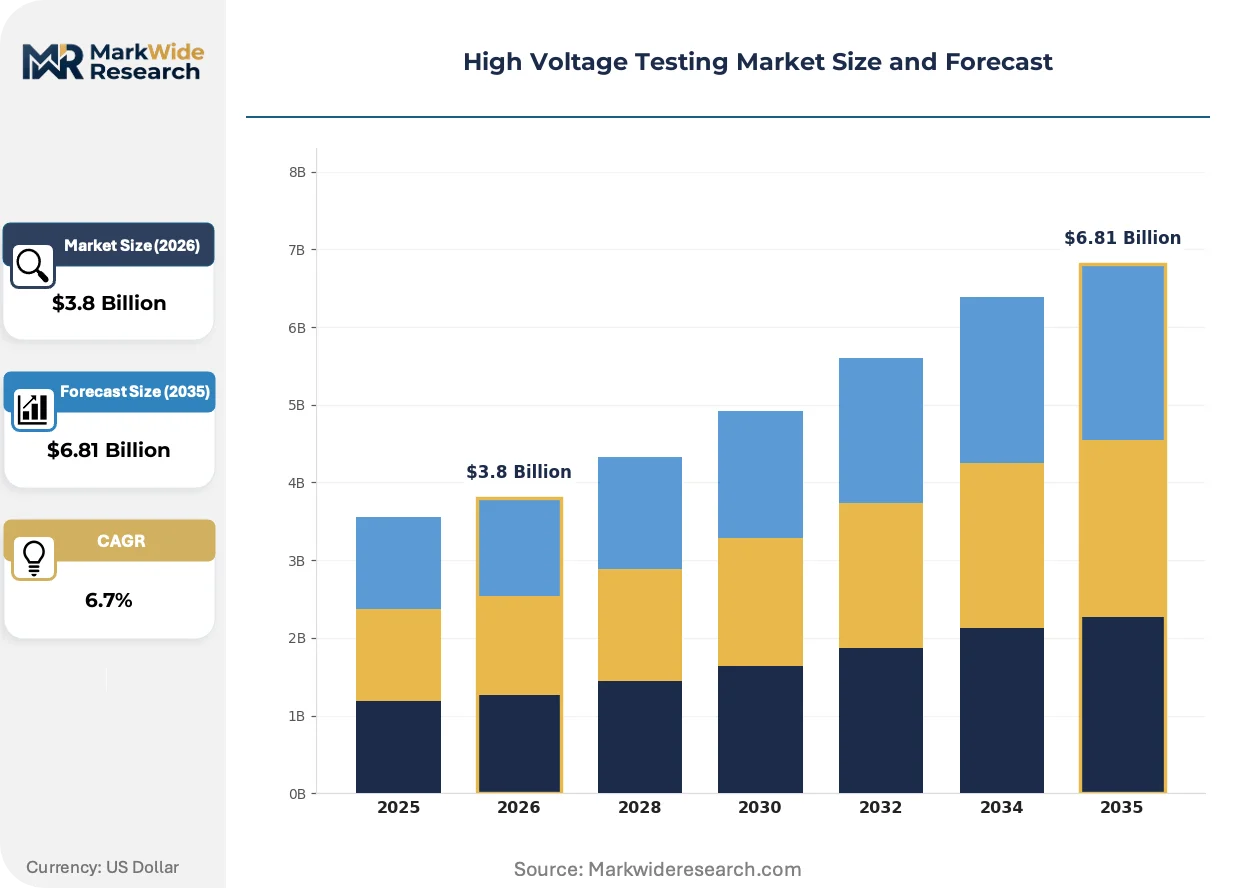
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Equipment, Diagnostic Tools, Calibration Instruments, Safety Gear Application: Power Generation, Transmission Lines, Electrical Substations, Industrial Equipment End User: Utilities, Manufacturing Plants, Research Laboratories, Renewable Energy Sector Technique: AC Testing, DC Testing, Insulation Resistance Testing, Partial Discharge Testing |
| Companies Covered | BAUR GmbH, HV Technologies, Inc., OMICRON Electronics GmbH, Power Diagnostix Systems GmbH, Haefely Test AG, Megger Group Limited, Phenix Technologies, HIGHVOLT Prüftechnik Dresden GmbH, Doble Engineering Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Testing Market Shifts & Advancements
Very fast transient overvoltage simulation and dissolved gas analysis automation are compressing commissioning cycles while regulatory pressure on insulating gases forces material science pivots across test equipment architectures.
Very fast transient overvoltage (VFTO) test systems are expanding into ultra-high-voltage substation validation, with Chinese grid operators adopting 1100 kV-class impulse generators for GIS commissioning. State Grid Corporation deploys these systems at Xinjiang and Anhui converter stations. VFTO simulation is expanding into research contracts for next-generation 800 kV DC cable qualification.
The EU F-Gas Regulation mandates 80% sulfur hexafluoride reduction in new electrical equipment by 2030, compelling test equipment manufacturers to certify fluoronitrile and vacuum interrupter compatibility. German TSOs now require gas-handling protocols during factory acceptance testing. The regulation is compressing product development cycles for European switchgear test bay suppliers.
Asset owners are unbundling after-sales calibration and recertification from original equipment purchases, creating independent service provider channels. Transmission system operators in the United States are contracting third-party mobile labs for transformer hipot retesting rather than maintaining captive facilities. This shift concentrates in the PJM and ERCOT interconnection regions where fleet age exceeds 35 years.
High Voltage Testing Market Segmentation
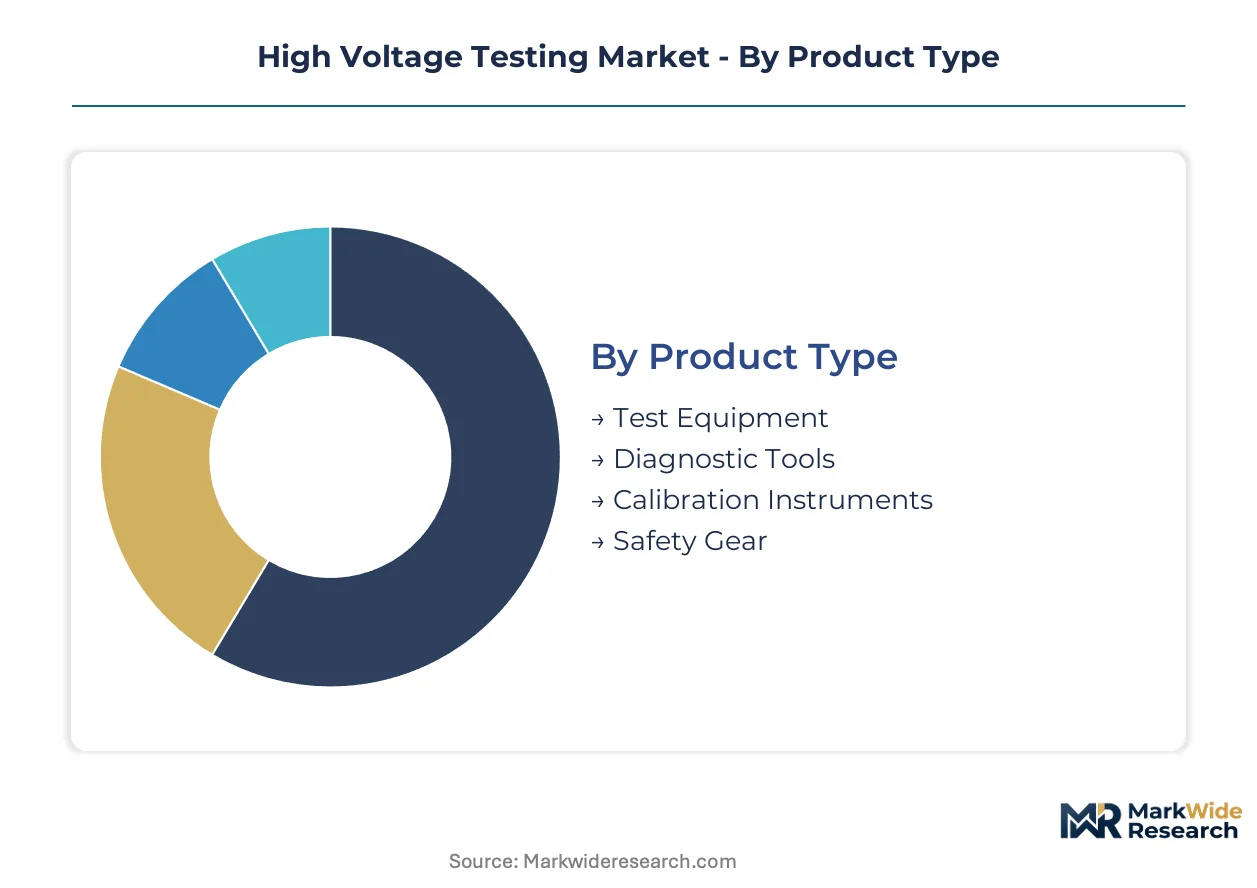
Segmentation in high voltage testing reveals distinct procurement patterns across equipment categories, with capital intensity and regulatory compliance requirements driving divergent upgrade cycles. Understanding these divisions enables suppliers to align R&D roadmaps with replacement timelines and emerging certification standards.
Product Type:
Replacement cycles vary sharply across product categories, with capital equipment demanding decade-long investment horizons while consumables and safety gear turn over on annual contracts.
- Test Equipment:Resonant test systems and impulse generators constitute the capital backbone of high voltage laboratories, with voltage ratings spanning 50 kV to megavolt-class research applications. German TSOs and Chinese grid operators are replacing aging oil-insulated units with compact modular designs to accommodate SF6 phase-down requirements.
- Diagnostic Tools:Portable partial discharge detectors and cable fault locators enable field-deployed condition assessment without de-energizing primary circuits. Offshore wind developers in the North Sea embed these tools into commissioning protocols, creating bundled service contracts that extend beyond hardware sales.
- Calibration Instruments:Traceable reference dividers and standard capacitors maintain measurement integrity across test laboratory networks. National metrology institutes in the United States and Germany certify these units under IEC 61000 and IEEE 4 standards.
- Safety Gear:Insulating platforms, arc flash suits, and grounding assemblies protect personnel during energized testing procedures. Industrial equipment manufacturers in India source these through localized distributors to meet tightening CEA procurement specifications.
Test Equipment sits at the top of the volume ranking, with Diagnostic Tools climbing the fastest.
Application:
Application segments map directly to asset ownership structures, with regulated utilities dominating transmission and substation testing while industrial users concentrate spend on production-critical equipment validation.
- Power Generation:Generator step-up transformers and isolated phase bus systems require repetitive high-potential verification during outage windows. Chinese provincial power corporations are expanding test bay capacity to accommodate renewable hybrid plants combining solar, wind, and storage.
- Transmission Lines:Overhead conductor and underground cable systems demand AC resonant and DC withstand validation before energization. German TSOs now mandate partial discharge monitoring for all new 380 kV XLPE cable circuits.
- Electrical Substations:Gas-insulated switchgear and power transformers undergo factory acceptance testing and site commissioning sequences. The EU F-Gas Regulation is forcing redesign of test setups to handle fluoronitrile blends without cross-contaminating legacy SF6 compartments.
- Industrial Equipment:Motor drives, rectifier systems, and electrostatic precipitators require periodic insulation resistance verification. US petrochemical facilities embed testing into turnaround schedules governed by OSHA electrical safety mandates.
Transmission Lines commands the largest revenue pool, with Electrical Substations gaining share fastest as GIS retrofit cycles accelerate.
End User:
End user procurement patterns diverge between capital-constrained public utilities and research-intensive institutions with grant-funded equipment refresh cycles.
- Utilities:Transmission and distribution owner-operators maintain captive test fleets for routine maintenance and emergency fault investigation. PJM and ERCOT interconnection regions in the United States are contracting third-party mobile labs rather than replacing aging fixed facilities.
- Manufacturing Plants:Heavy electrical equipment producers operate in-house high voltage laboratories for type testing and quality assurance. Chinese transformer manufacturers are expanding test capacity to meet GB standard certification requirements for export markets.
- Research Laboratories:Universities and national laboratories operate megavolt-class facilities for fundamental dielectric research and standard development. State Grid Corporation in China deploys 1100 kV-class impulse generators at Xinjiang and Anhui converter stations for UHV research.
- Renewable Energy Sector:Wind turbine OEMs and array developers mandate full-sequence high voltage verification before grid synchronization. Offshore wind projects in the East China Sea embed testing protocols into project finance covenants.
Utilities dominate installed base volumes, with Renewable Energy Sector expanding most quickly as offshore wind buildouts accelerate.
Technique:
Testing technique selection reflects a trade-off between diagnostic sensitivity and operational practicality, with field-deployable methods gaining ground over laboratory-intensive alternatives.
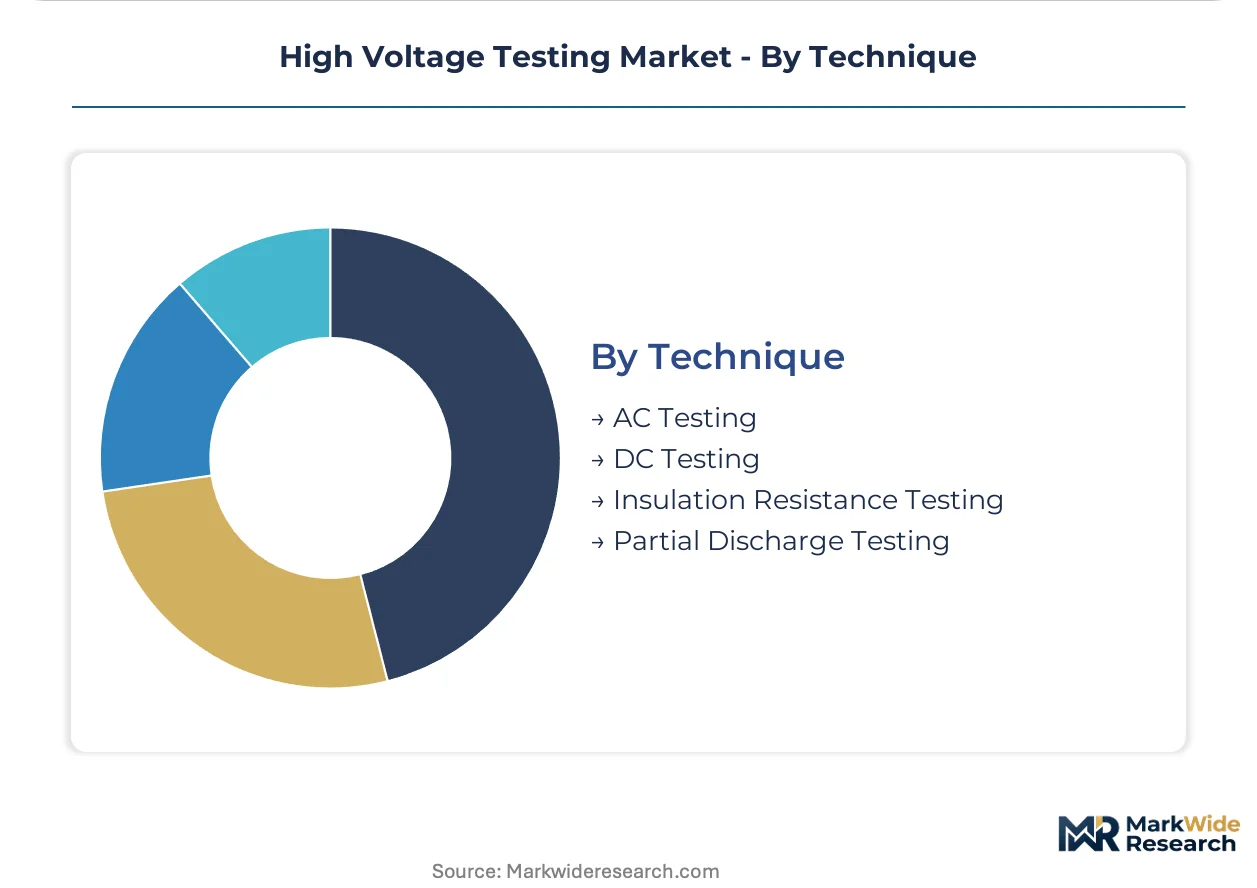
- AC Testing:Power frequency withstand and induced overvoltage methods remain the reference standard for factory acceptance testing of transformers and switchgear. Resonant test systems dominate this segment due to their compact footprint relative to conventional test transformers.
- DC Testing:High voltage DC withstand and leakage current measurement serve cable and generator applications where AC excitation would be impractical. Offshore wind array developers in the North Sea rely on DC test sets for subsea cable commissioning.
- Insulation Resistance Testing:Megohm measurement at elevated voltage provides baseline condition assessment for rotating machinery and distribution cables. Manufacturing plants in India deploy portable units for preventive maintenance under CEA grid code alignment.
- Partial Discharge Testing:Detection of localized electrical discharges enables predictive maintenance and defect localization before catastrophic failure. German utilities are retrofitting switchgear test bays to meet tightened IEC 62271 partial discharge limits.
AC Testing retains the largest installed base, with Partial Discharge Testing showing the steepest expansion trajectory as predictive maintenance displaces scheduled replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized high-voltage engineering talent concentrates in German industrial clusters, Chinese state-grid research facilities, and American utility corridors, anchoring regional testing capacity and equipment procurement intensity.
United States
PJM and ERCOT transmission owners are contracting third-party mobile testing labs as captive facilities age beyond 35 years. OSHA electrical safety mandates govern petrochemical turnaround schedules requiring periodic hipot validation. Houston and the Gulf Coast corridor host concentrated demand from oil and gas facilities integrating renewable hybrid systems.
Germany
Transmission system operators mandate partial discharge monitoring for all new 380 kV XLPE cable circuits across the North Sea offshore wind buildout. The EU F-Gas Regulation forces test bay redesign for fluoronitrile compatibility without SF6 cross-contamination. Bavarian manufacturing clusters supply resonant test systems retrofitting European switchgear facilities.
China
State Grid Corporation deploys 1100 kV-class impulse generators at Xinjiang and Anhui converter stations for ultra-high-voltage research. GB standards and NMPA-equivalent electrical safety mandates impose additional conformity layers for imported equipment. Yangtze River Delta transformer manufacturers expand test capacity to meet export certification requirements.
India
Domestic utilities import test equipment to align with tightening CEA grid codes and BIS certification requirements. Manufacturing plants in Maharashtra and Gujarat deploy portable diagnostic units for preventive maintenance under localized procurement specifications. The PLI scheme for electrical equipment is accelerating captive testing infrastructure buildout.
High Voltage Testing Market Competitive Landscape
The competitive structure tilts toward specialized engineering houses with deep domain expertise in dielectric physics and field deployment logistics. The vendor base clusters around three archetypes: Austrian-German precision manufacturers dominating cable fault location and resonant systems, Anglo-American instrumentation groups anchoring portable AC/DC test sets, and Swiss-Austrian diagnostic specialists concentrating on dissolved gas analysis and partial discharge monitoring. Dominant competitive moves include geographic licensing partnerships for emerging market regulatory compliance and retrofit service contracting for installed gas-insulated bases facing F-Gas phase-down deadlines.
Among Germanic engineering specialists, BAUR GmbH, OMICRON Electronics GmbH, and HIGHVOLT Prüftechnik Dresden GmbH occupy positions exemplifying the precision-manufacturing archetype. These Austria- and Germany-based entities represent the engineering-intensive tier where dielectric system design and regulatory certification capabilities create defensive positioning against commoditized portable equipment. Megger Group Limited and Doble Engineering Company anchor the Anglo-American instrumentation vector, situating within portfolios that balance field-deployable hardware with software-integrated asset management platforms. HV Technologies, Inc. and Phenix Technologies exemplify the North American field-service orientation, representing the mobile testing fleet deployment model penetrating transmission owner markets lacking capital for fixed laboratory infrastructure.
| Leading Market Players |
|---|
| BAUR GmbH |
| HV Technologies, Inc. |
| OMICRON Electronics GmbH |
| Power Diagnostix Systems GmbH |
| Haefely Test AG |
| Megger Group Limited |
| Phenix Technologies |
| HIGHVOLT Prüftechnik Dresden GmbH |
| Doble Engineering Company |
| Others |
Supply & Pricing Matrix
Family-owned precision engineering specialists in Germany and Austria anchor supply-side discipline, translating captive manufacturing expertise into premium pricing power for resonant test systems while resisting commoditization through embedded calibration services.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture, with hardware vendors unbundling after-sales calibration to capture recurring revenue streams. Three-tier pricing structure across premium, standard, and economy levels separates IEC 62271-certified resonant systems from portable field units and basic safety gear. Pricing pressure stems from copper and rare-earth magnet wire volatility squeezing margins on impulse generator cores. Utilities exhibit highest price sensitivity for capital equipment, while research laboratories demonstrate lowest sensitivity given grant-funded procurement cycles.
Supply Chain Analysis
Freight costs for megavolt-class test transformers and impulse generators concentrate supply planning around German, Austrian, and Chinese manufacturing clusters. Magnet wire draws from Chinese rare-earth processing and Chilean copper smelting. Single-source vulnerability haunts ferrite core supply from Japanese specialty ceramic producers. Distribution runs through direct sales engineers for capital equipment and localized distributors for portable diagnostic tools and safety gear.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The High Voltage Testing Market compounds steadily as grid modernization mandates and renewable interconnection requirements perpetuate equipment refresh cycles across regulated utilities.
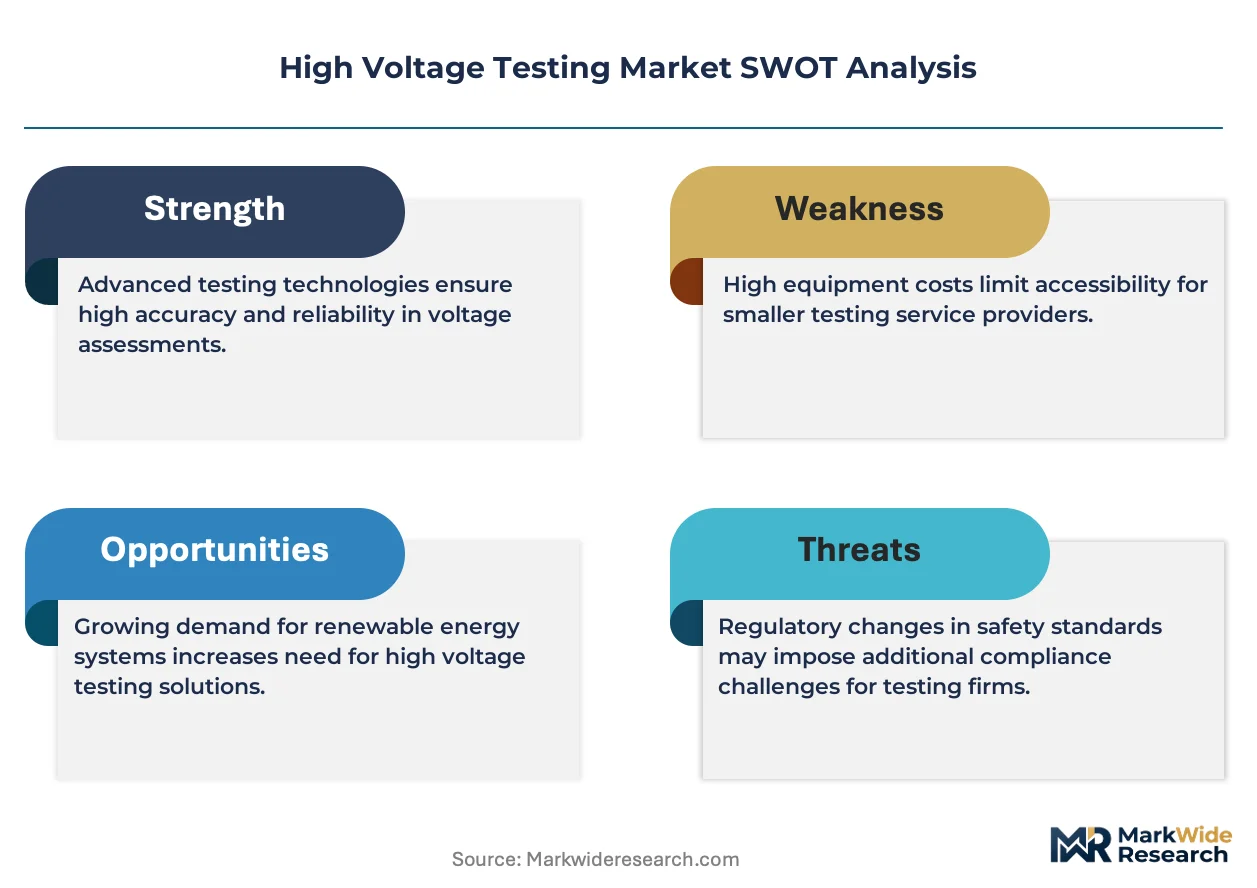
For Market Incumbents: To counter specialized high-voltage engineering talent contraction in OECD markets, deepen backward integration into magnet wire winding and ferrite core fabrication to secure input cost stability. Anchor defensive positioning through captive certification laboratories accelerating IEC, IEEE, and GB standard approvals in parallel rather than sequentially. For New Entrants and Emerging Players: Launch via mobile testing fleet deployment targeting transmission owners in PJM and ERCOT interconnection regions lacking capital for fixed laboratory infrastructure. Penetrate India's CEA grid code alignment opportunity through localized assembly partnerships with Maharashtra and Gujarat industrial clusters. Lead with subscription-based predictive maintenance bundling partial discharge sensors with asset performance management platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among field-service-oriented mobile testing providers with aging equipment fleets and concentrated utility customer relationships. Long-term viability rests on digital twin convergence enabling recurring software revenue attachment to hardware deployments. Watch for EU F-Gas Regulation enforcement intensity as inflection signal for retrofit service contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| SF6 Alternative Test Bay Redesign | EU F-Gas Regulation mandates fluoronitrile compatibility certification without cross-contaminating legacy gas compartments. |
| Mobile Testing Fleet Expansion | PJM and ERCOT transmission owners contract third-party field services rather than replacing aging captive facilities. |
| Digital Twin Platform Integration | Partial discharge sensor convergence with asset performance management enables subscription-based predictive maintenance revenue. |
| India Localized Assembly Partnership | CEA grid code alignment and BIS certification requirements create first-mover advantages for domestic manufacturing. |
| Certification Laboratory Captive Buildout | Parallel IEC, IEEE, and GB standard approval compresses product launch windows against multi-standard sequencing delays. |
Research Methodology
Coverage spans Germany, China, the United States, and India, with primary inputs from each market combining interviews with utility planning officers, high-voltage test laboratory directors, OEM procurement teams, and aftermarket service heads alongside secondary validation. Regulatory filings from FERC, CEA, and State Grid Corporation supplement trade data from customs records and IEC standard development documentation. Bottom-up equipment shipment tracking triangulates against top-down utility capital expenditure disclosures.
Granularity-level framing models voltage class tiers, testing technique categories, and end-user ownership structures across the projection horizon. CAGRs derive from replacement cycle analysis intersecting with regulatory compliance deadlines. Forecast inputs incorporate SF6 phase-down timelines, offshore wind commissioning protocol evolution, and grid code harmonization trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price volatility and engineering talent availability constraints. Forecasts reflect documented assumptions about standard adoption velocity and renewable buildout pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Ground Resistance Testers Market
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Structure Tester Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Metal Testing Equipment Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Color Meter Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
DSL Tester Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
Wireless Network Test Equipment Market