
 Destructive Testing Market | 2026-2036
Destructive Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Destructive Testing Market Analysis
REACH compliance is repositioning the cost-of-entry calculus for European destructive testing laboratories by mandating extensive chemical characterization of materials before industrial deployment. Thermo Fisher Scientific leverages its analytical instrument portfolio to anchor testing workflows across polymer and metals verification. Ametek Mocon specializes in permeation and package integrity testing, occupying a defensible niche within food and pharmaceutical safety protocols. Shimadzu Corporation dominates materials characterization in Asia-Pacific manufacturing hubs through its universal testing machine installed base.
Destructive testing encompasses mechanical procedures that subject specimens to controlled stress beyond failure thresholds to quantify tensile strength, fracture toughness, elongation percentage, and compressive yield points under standardized load conditions. These methods serve as the definitive validation layer for structural integrity in safety-critical components where simulation alone cannot satisfy certification requirements. Tensile and compression test types command the largest equipment spend due to their ubiquity across metals and polymer certification workflows. Composites testing represents the fastest-expanding material category as carbon fiber reinforced polymers displace aluminum in aerospace and electric vehicle architectures. Data acquisition systems and software segments capture disproportionate margin pools through recurring calibration contracts and regulatory audit trail functionality.
The European Chemicals Agency enforces REACH substance registration thresholds that compel manufacturers to submit destructive test data for material safety dossiers, directly expanding laboratory throughput requirements. The U.S. Federal Aviation Administration mandates specific fracture mechanics testing protocols under Part 25 airworthiness standards, creating captive demand for aerospace-certified testing houses. Japan's Ministry of Economy, Trade and Industry maintains JIS standards that govern metallic material acceptance testing for domestic infrastructure projects. Stakeholders must monitor evolving harmonization between regional standards bodies as cross-border supply chains face divergent certification burdens.
Market Dynamics
Composite airframe certification demands from aerospace manufacturers are compressing testing timelines while expanding specimen volumes, forcing laboratories to automate mechanical load frames and integrate real-time data acquisition systems.
Growth Catalysts
- REACH substance registration:ECHA mandates compel European manufacturers to submit comprehensive destructive test data for material safety dossiers, expanding laboratory throughput requirements across polymer and metals verification workflows.
- Electric vehicle architectures:Carbon fiber reinforced polymers displacing aluminum in battery enclosures and structural components are accelerating composites testing demand beyond traditional aerospace applications.
- Ruhr industrial cluster consolidation:Automotive and steel testing laboratories in Germany are merging capacity to capture economies of scale in tensile and compression certification services.
Market Restraints
- Helium supply volatility:Inert gas requirements for fracture mechanics testing under FAA Part 25 protocols face price instability from concentrated Middle Eastern and North American production sources.
- High-purity reagent costs:Chemical characterization for REACH compliance depends on specialized solvents and reference materials with limited qualified suppliers.
- Non-destructive testing substitution:Ultrasonic and radiographic inspection methods are capturing routine quality assurance workflows previously reserved for destructive specimen analysis.
Strategic Opportunities
- India infrastructure buildout:National highway and railway expansion under the Ministry of Road Transport and Highways is creating demand for JIS-equivalent metallic material acceptance testing protocols.
- Digital audit trail software:Regulatory mandates for data integrity are opening recurring revenue streams in calibration management and certificate authentication platforms.
- Battery materials characterization:Solid-state electrolyte and silicon-anode development programs require novel fracture toughness and thermal cycling test methods not standardized in existing protocols.
Industry Challenges
- Certified technician scarcity:ASTM E8 and ISO 6892 test protocol proficiency requires specialized training pipelines that academic institutions have not scaled to match laboratory expansion rates.
- Multi-standard harmonization delays:Divergent load frame calibration cycles between FAA, EASA, and CAAC airworthiness directives force redundant equipment investments for cross-certified testing houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Destructive Testing Market |
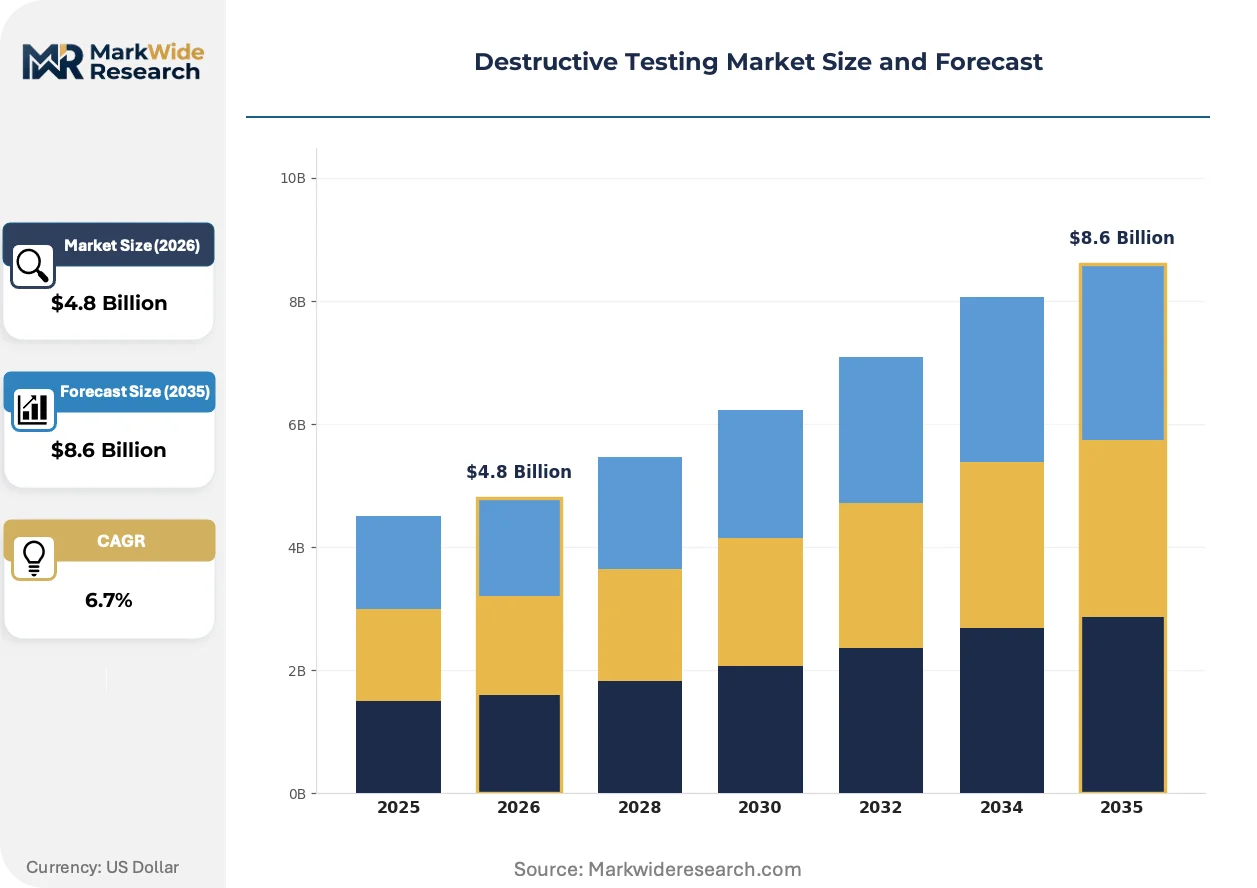
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Tensile, Compression, Bend, Impact Material Type: Metals, Polymers, Composites, Ceramics Industry Vertical: Aerospace, Automotive, Energy, Construction Equipment Type: Testing Machines, Sensors, Data Acquisition Systems, Software |
| Companies Covered | Thermo Fisher Scientific, Ametek Mocon, Mettler Toledo, METER Group, Anéolia, Metrohm, Shimadzu Corporation, Sartorius, IMADA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Destructive Testing Market Emerging Trajectories
Automation of specimen handling and machine learning interpretation of fracture surfaces are compressing test cycle times while expanding the volume of data extractable from each destructive event.
Digital image correlation systems paired with high-speed cameras are overtaking traditional extensometry in strain measurement applications. Aerospace tier-one suppliers in the United States and Japan are adopting full-field deformation mapping for composite coupon testing. This technology is overtaking contact-based measurement methods by eliminating knife-edge attachment failures and enabling post-test strain field reconstruction.
The EU Machinery Directive's updated material validation annex is mandating traceable destructive test documentation for industrial equipment imports into member states. Machinery OEMs must now submit tensile and Charpy impact certificates from ISO 17025-accredited laboratories. German automotive press manufacturers and Italian packaging machinery builders are restructuring supplier qualification programs to pre-certify steel and aluminum stock before assembly.
Asset-light testing service contracts are displacing capital-intensive in-house laboratory ownership among mid-tier automotive suppliers. Tier-two component manufacturers in South Korea and Mexico are outsourcing fracture mechanics and fatigue testing to regional specialists rather than maintaining captive equipment. This shift concentrates specimen logistics complexity with third-party providers while reducing fixed cost exposure for OEMs managing multiple platform launches.
Destructive Testing Market Segmentation
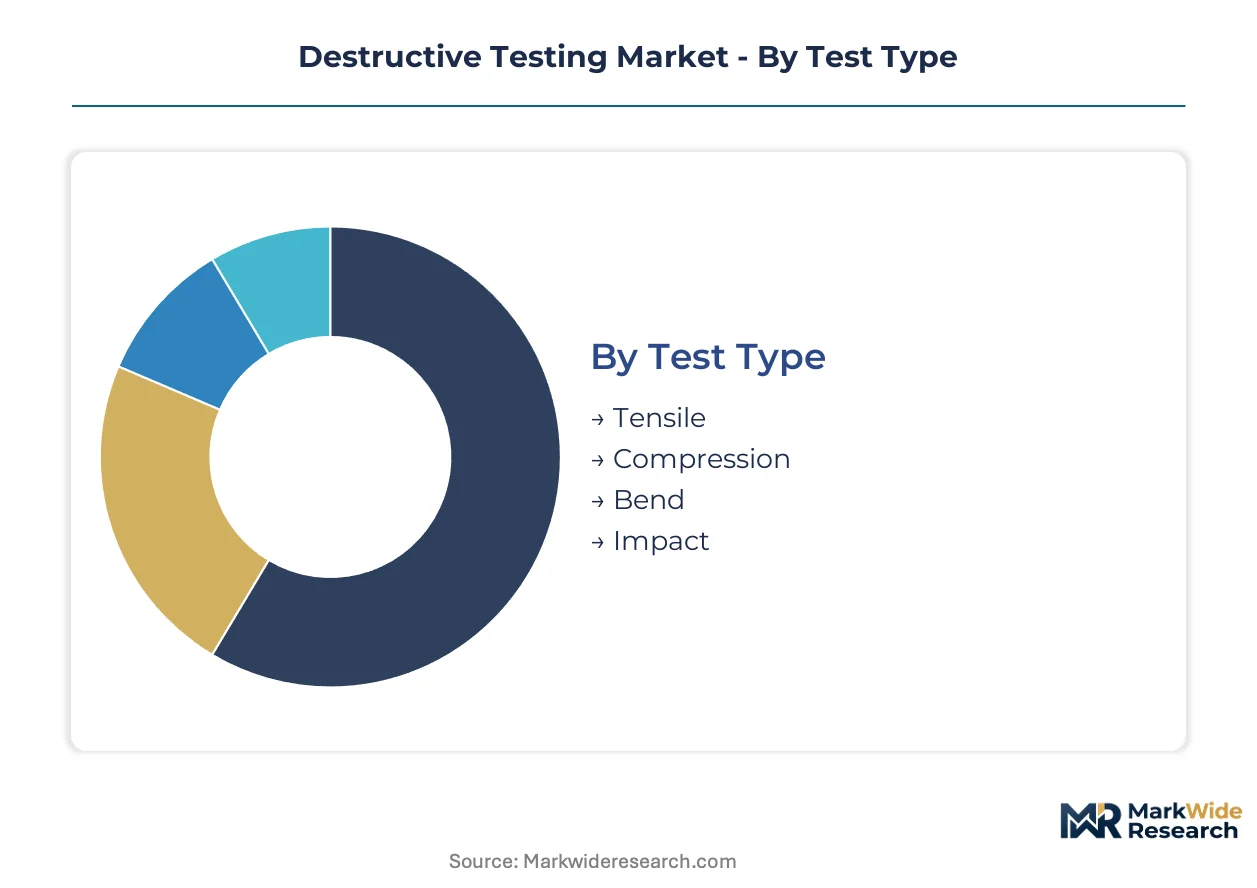
Destructive testing workflows fragment across multiple technical dimensions that dictate equipment specifications, regulatory compliance pathways, and customer procurement patterns. Test protocols, material classes, industry applications, and instrumentation layers each create distinct margin pools and competitive dynamics for laboratory operators and equipment vendors.
Test Type:
Standalone mechanical load frames dominate high-volume certification workflows, while integrated multi-axis systems serve complex specimen characterization in aerospace and automotive R&D centers.
- Tensile:Universal testing machines apply uniaxial load to failure, measuring ultimate tensile strength, yield point, and elongation percentage per ASTM E8 and ISO 6892 protocols. Demand concentrates in Germany's Ruhr industrial cluster where automotive and steel laboratories are consolidating capacity to capture economies of scale in metals certification.
- Compression:Specimens undergo controlled crushing loads to determine compressive yield strength and modulus in structural materials. Carbon fiber reinforced polymers displacing aluminum in battery enclosures and electric vehicle architectures are accelerating composites compression testing demand beyond traditional aerospace applications.
- Bend:Three-point and four-point flexural tests quantify modulus of rupture in brittle materials and weld qualification samples.
- Impact:Charpy and Izod pendulum methods measure energy absorption at fracture for low-temperature toughness verification.
Volume placements concentrate in Tensile; the faster expansion belongs to Compression.
Material Type:
Cost tiers separate commodity metals verification from premium composites characterization, with polymer testing occupying a mid-market position driven by REACH chemical characterization mandates.
- Metals:Ferrous and non-ferrous alloys undergo standardized tensile, hardness, and impact testing for structural qualification. Japan's Ministry of Economy, Trade and Industry maintains JIS standards governing metallic material acceptance testing for domestic infrastructure projects, creating captive demand for certified laboratories.
- Polymers:Thermoplastics and thermosets require specialized grips and environmental chambers to measure stress-strain behavior across temperature ranges. ECHA mandates compel European manufacturers to submit comprehensive destructive test data for material safety dossiers, expanding laboratory throughput requirements across polymer verification workflows.
- Composites:Carbon fiber reinforced polymers displace aluminum in aerospace and electric vehicle architectures.
- Ceramics:Brittle structural materials demand specialized flexural and fracture toughness protocols for high-temperature applications.
Metals retain the largest installed base; Composites are climbing the fastest on airframe and battery enclosure certification demand.
Industry Vertical:
Application-specific regulatory burdens create divergent testing frequencies, with aerospace mandating fracture mechanics documentation and construction emphasizing batch-level tensile verification.
- Aerospace:Airframe manufacturers and tier-one suppliers execute coupon, element, and subcomponent testing under FAA Part 25 and EASA CS-25 airworthiness directives. Composite airframe certification demands from United States manufacturers are compressing testing timelines while expanding specimen volumes, forcing laboratories to automate mechanical load frames.
- Automotive:Crashworthiness, fatigue life, and material qualification support platform development and supplier certification. Asset-light testing service contracts are displacing capital-intensive in-house laboratory ownership among mid-tier suppliers in South Korea and Mexico.
- Energy:Pipeline steel, turbine alloys, and nuclear pressure vessel materials require specialized fracture mechanics protocols.
- Construction:Rebar, structural steel, and concrete reinforcement undergo batch testing for infrastructure project acceptance.
Aerospace commands premium pricing per specimen; Automotive delivers the steepest volume expansion trajectory through outsourcing trends.
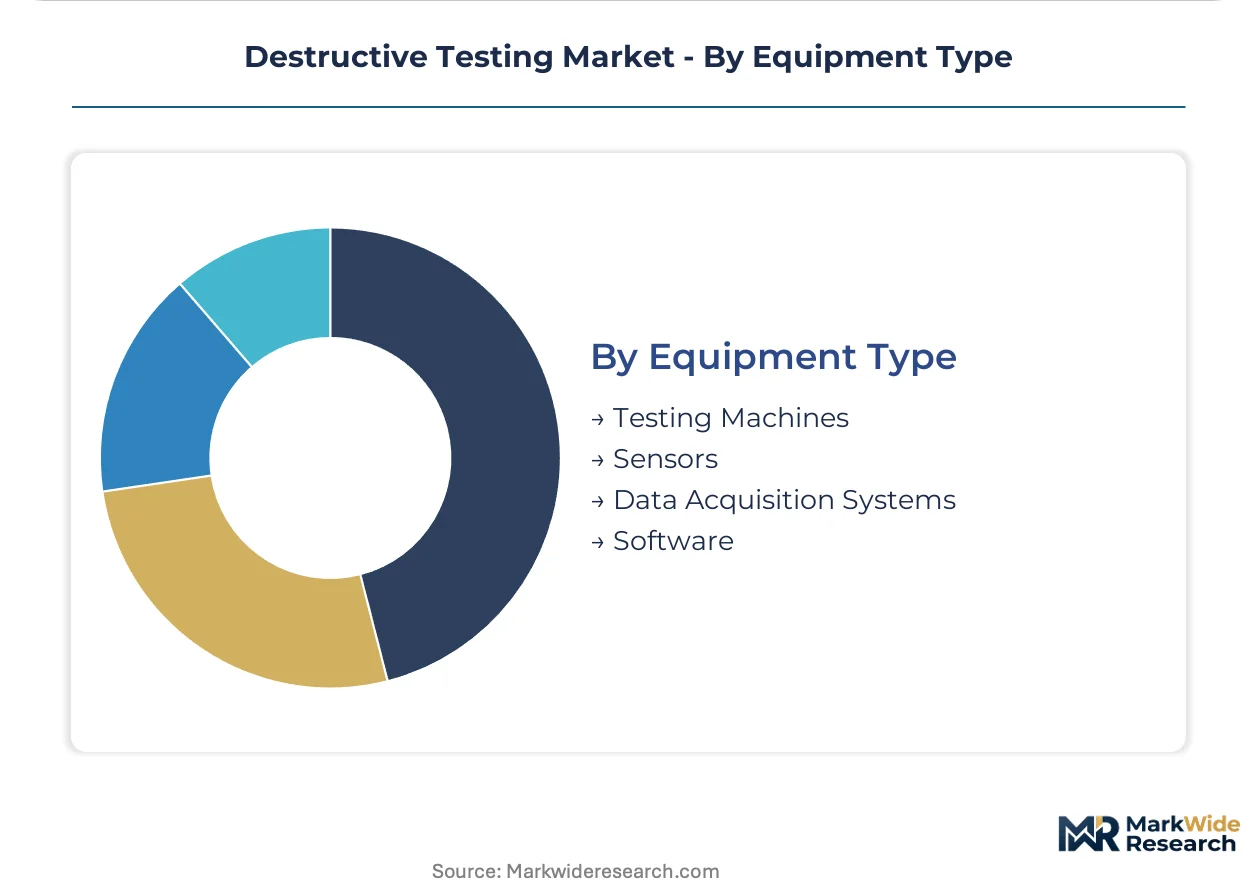
Equipment Type:
Margin pools concentrate in software and data layers where recurring calibration contracts and regulatory audit trail functionality capture disproportionate value relative to capital hardware.
- Testing Machines:Electromechanical and hydraulic load frames constitute the capital foundation of destructive testing laboratories. Digital image correlation systems paired with high-speed cameras are overtaking traditional extensometry in strain measurement applications at aerospace tier-one suppliers in the United States and Japan.
- Sensors:Load cells, strain gauges, and environmental monitoring devices provide precision measurement inputs. Thermo Fisher Scientific leverages its analytical instrument portfolio to anchor testing workflows across polymer and metals verification.
- Data Acquisition Systems:Real-time signal conditioning and digitization hardware integrate with machine control loops.
- Software:Test control, analysis, and certificate generation platforms with calibration management and audit trail functionality.
Testing Machines absorb the largest capital allocation; Software is gaining share fastest on recurring revenue and regulatory data integrity mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and India's Gujarat International Finance Tec-City are concentrating destructive testing capacity through tax incentives and streamlined customs procedures for imported equipment.
United States
Aerospace manufacturers in Seattle and Wichita are expanding composite airframe certification protocols. FAA Part 25 mandates specific fracture mechanics testing for airworthiness documentation. Laboratories in Southern California are automating mechanical load frames to compress testing timelines for defense contractors.
Germany
Automotive and steel testing laboratories in the Ruhr industrial cluster are consolidating capacity to capture economies of scale. The EU Machinery Directive's updated material validation annex mandates traceable destructive test documentation for industrial equipment imports. Bavarian automotive press manufacturers are restructuring supplier qualification programs to pre-certify steel stock.
China
Battery enclosure manufacturers in Shenzhen and Chengdu are accelerating composites compression testing for electric vehicle architectures. GB standards governing metallic material acceptance testing create captive demand for certified laboratories. Yangtze River Delta testing houses are integrating real-time data acquisition systems to handle expanded specimen volumes.
Japan
Aerospace tier-one suppliers in Nagoya and Tokyo are adopting digital image correlation systems for composite coupon testing. METI maintains JIS standards that govern metallic material acceptance testing for domestic infrastructure projects. Kansai-region laboratories are overtaking contact-based measurement methods with full-field deformation mapping technology.
India
National highway and railway expansion under the Ministry of Road Transport and Highways is creating demand for JIS-equivalent metallic material acceptance testing. BIS certification requirements for construction materials are expanding laboratory throughput. Gujarat-based testing facilities are capturing outsourced contracts from mid-tier automotive suppliers in Pune and Chennai.
Destructive Testing Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented tiers. The vendor base spans analytical instrumentation conglomerates, precision measurement specialists, and regional testing service providers. Three strategic archetypes dominate: diversified laboratory equipment conglomerates with broad analytical portfolios, focused mechanical testing specialists with deep load frame expertise, and permeation testing niche players serving food and pharmaceutical safety protocols. Competitive moves concentrate on portfolio diversification through adjacent analytical capabilities and geographic expansion into emerging manufacturing hubs.
Among diversified analytical conglomerates, Thermo Fisher Scientific and Shimadzu Corporation exemplify scale-driven archetypes with broad materials characterization portfolios. Ametek Mocon occupies a defensible specialist position within permeation and package integrity testing workflows. These three companies represent contrasting strategic postures: diversified instrumentation breadth versus focused niche dominance versus mid-scale regional specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Ametek Mocon |
| Mettler Toledo |
| METER Group |
| Anéolia |
| Metrohm |
| Shimadzu Corporation |
| Sartorius |
| IMADA |
| Others |
Supply Flow & Price Mechanics
ISO 17025 accreditation tiering bifurcates destructive testing services into premium-certified and commodity-uncertified segments, with aerospace and pharmaceutical buyers paying substantial markups for FAA-traceable documentation while construction and general industrial procurement gravitates toward lower-cost unaccredited laboratories. This divergence manifests in parallel supply chains: premium-tier providers concentrate in Germany's Ruhr cluster and Southern California defense corridors with captive technician pipelines, while commodity operators source equipment through Shenzhen distributors and rely on uncertified freelance operators.
Pricing Analysis
Expedited lead-time premiums dominate pricing negotiations, with aerospace OEMs paying substantial markups for sub-72-hour turnaround on fracture mechanics documentation under FAA Part 25 protocols. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited houses with full audit trails from mid-tier regional specialists and uncertified commodity operators. Cost compression in the economy tier is intensifying because Chinese equipment manufacturers are flooding secondary markets with refurbished universal testing machines. Automotive tier-two suppliers in Mexico exhibit the highest price sensitivity, while pharmaceutical safety teams show minimal elasticity given regulatory exposure.
Supply Chain Analysis
Single-source vulnerability sits with helium suppliers concentrated in Qatar and the United States, where inert gas extraction for fracture mechanics testing faces geopolitical and production disruption risks. Equipment manufacturing draws from Germany, Japan, and China, with load cell precision components resting on Japanese strain gauge foundries and software layers anchored in United States and European development centers. Tariff exposure on analytical instruments threatens laboratory capital expenditure cycles in emerging markets. Distribution runs through regional equipment distributors with service contracts, bypassing direct manufacturer relationships for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
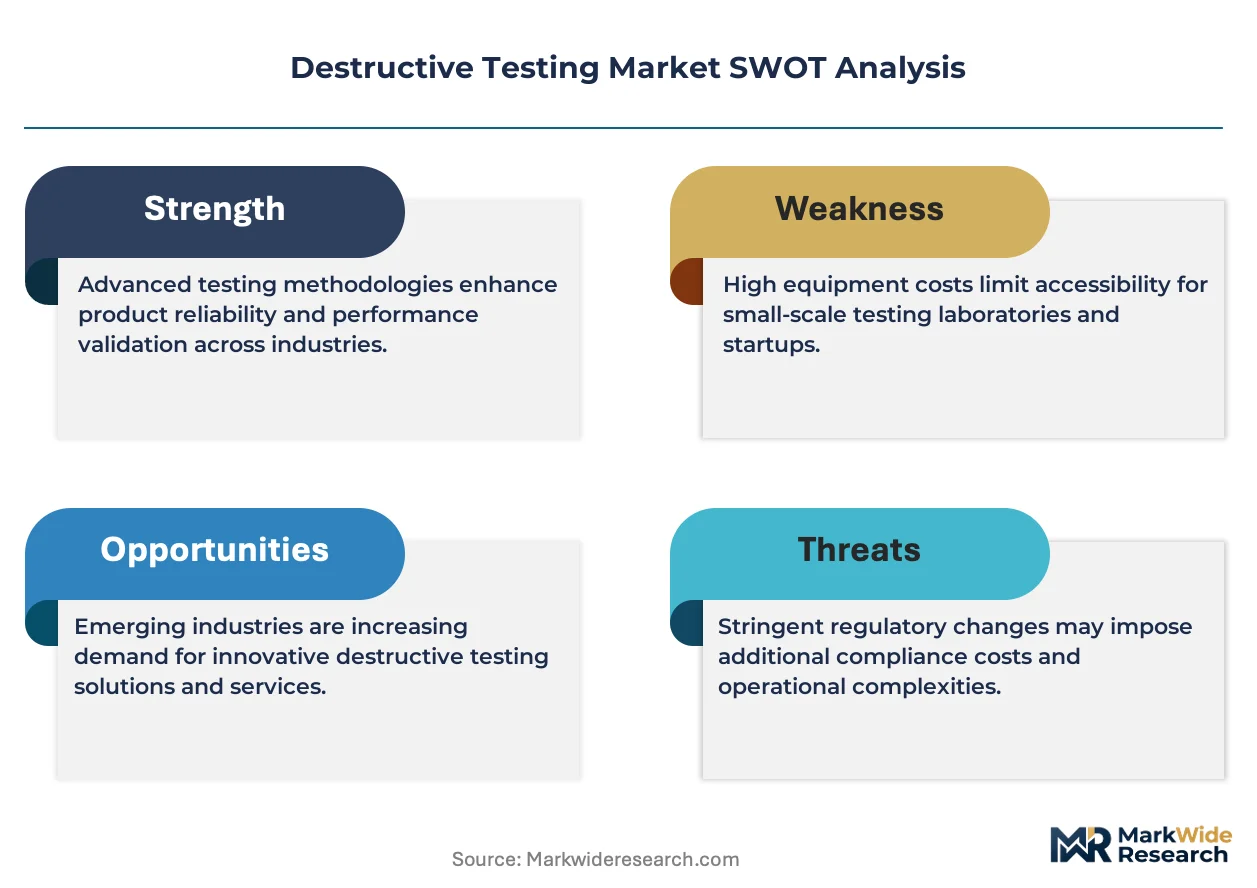
Destructive testing operates as a cost-of-compliance market where REACH substance registration and FAA Part 25 documentation requirements erect substantial barrier-to-entry moats for laboratories with established accreditation and audit trail capabilities.
For Market Incumbents: Deploy backward integration into certified technician training pipelines to lock in scarce ASTM E8 and ISO 6892 proficiency. Consolidate regional capacity in Germany's Ruhr cluster to capture economies of scale in tensile and compression certification workflows. Non-destructive testing substitution threatens routine quality assurance volumes; counter by embedding digital image correlation and real-time data acquisition as differentiated service bundles. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian infrastructure testing offers immediate white-space capture under BIS certification requirements for highway and railway materials. Target mid-tier automotive suppliers in Pune and Chennai with asset-light service contracts displacing captive laboratory ownership. Go-to-market leverage rests on JIS-equivalent protocol expertise transferred from Japanese technical partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with software-centric testing platforms given regulatory mandates for data integrity and calibration management recurring revenue. Long-term viability favors laboratories with embedded digital audit trail capabilities over pure equipment operators. Watch for harmonization momentum between FAA, EASA, and CAAC airworthiness directives as inflection signal for cross-certified testing house valuations.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Expansion | FAA and EASA traceability requirements lock in premium pricing for certified laboratories. |
| Digital Audit Trail Platform Development | REACH and FDA data integrity mandates create recurring software revenue streams. |
| Technician Training Pipeline Investment | ASTM E8 proficiency scarcity limits laboratory expansion capacity industry-wide. |
| Composites Testing Capacity Buildout | Carbon fiber battery enclosures and airframe architectures accelerate specimen volumes. |
| Regional Laboratory Consolidation | Ruhr cluster mergers capture scale economies in automotive and steel certification. |
Methodological Framework
Independent corroboration across laboratory operations directors, aerospace procurement managers, and regulatory compliance officers underwrites the qualitative findings in this study. Primary fieldwork encompassed structured interviews with equipment vendor technical sales leads, aftermarket service heads at German and Japanese manufacturers, and certification body auditors from ISO 17025 accreditation bodies. Secondary validation drew from FAA airworthiness directive filings, ECHA substance registration databases, customs records for analytical instrument imports, and SEC disclosures from diversified instrumentation conglomerates. Bottom-up laboratory capacity modeling and top-down end-use demand estimation were cross-referenced for triangulation.
Comparable-period anchoring tied forward projections to historical certification volume patterns across aerospace platform cycles and automotive outsourcing waves. Segmentation modeling spanned test protocol type, material class, industry vertical, and instrumentation layer across the projection horizon. CAGRs were derived from specimen volume growth rates calibrated to airframe production schedules, electric vehicle platform launches, and infrastructure project pipelines. Industry-specific inputs included helium supply volatility indices and technician training pipeline graduation rates from vocational institutions.
Inputs from primary interview subjects and regulatory filing databases were available through the study window; gaps in real-time laboratory utilization rates and uncertified operator market sizing introduce uncertainty bands around capacity expansion forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Battery CT Inspection Market
Test and Measurement
Hipot Tester Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Global Platform Electronic Laboratory Balance Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Digital Inspection Tools Market
Test and Measurement
Global Source Measure Unit Market
Test and Measurement
Digital Comparators Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Four-Quadrant Battery Simulator Market
Test and Measurement
Battery Testing and Inspection Equipment Market
Test and Measurement
PXI SMU Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Flow Meter Calibration Market
Test and Measurement
Semiconductor Test Socket Market
Test and Measurement
Sound Level Measurement Meter Market