
 Calibration Services Market | 2026-2036
Calibration Services Market Size, Share, and Industry Trends Forecast 2026-2036
Calibration Services Market Intelligence
Software-defined calibration protocols is consolidating around cloud-connected asset management platforms that bundle recurring verification schedules with real-time drift alerts. Keysight Technologies leverages its test-and-measurement heritage to anchor enterprise accounts with integrated calibration management software. Trescal competes through its pan-European laboratory network, while Intertek Group sustains credibility through ILAC-MRA accredited facilities across multiple industrial corridors.
Calibration services encompass the comparison of measurement instruments against reference standards with known uncertainties, typically traceable to national metrology institutes such as NIST or PTB, with procedures specifying parameters like temperature coefficients, resolution limits, and guard-banding ratios to ensure measurement reliability. Electrical calibration dominates revenue contribution due to the ubiquity of multimeters, oscilloscopes, and power analyzers in electronics and automotive test environments. Automated calibration systems within the technology dimension capture expanding share as manufacturers pursue throughput gains and reduced operator-induced variance in high-volume production settings.
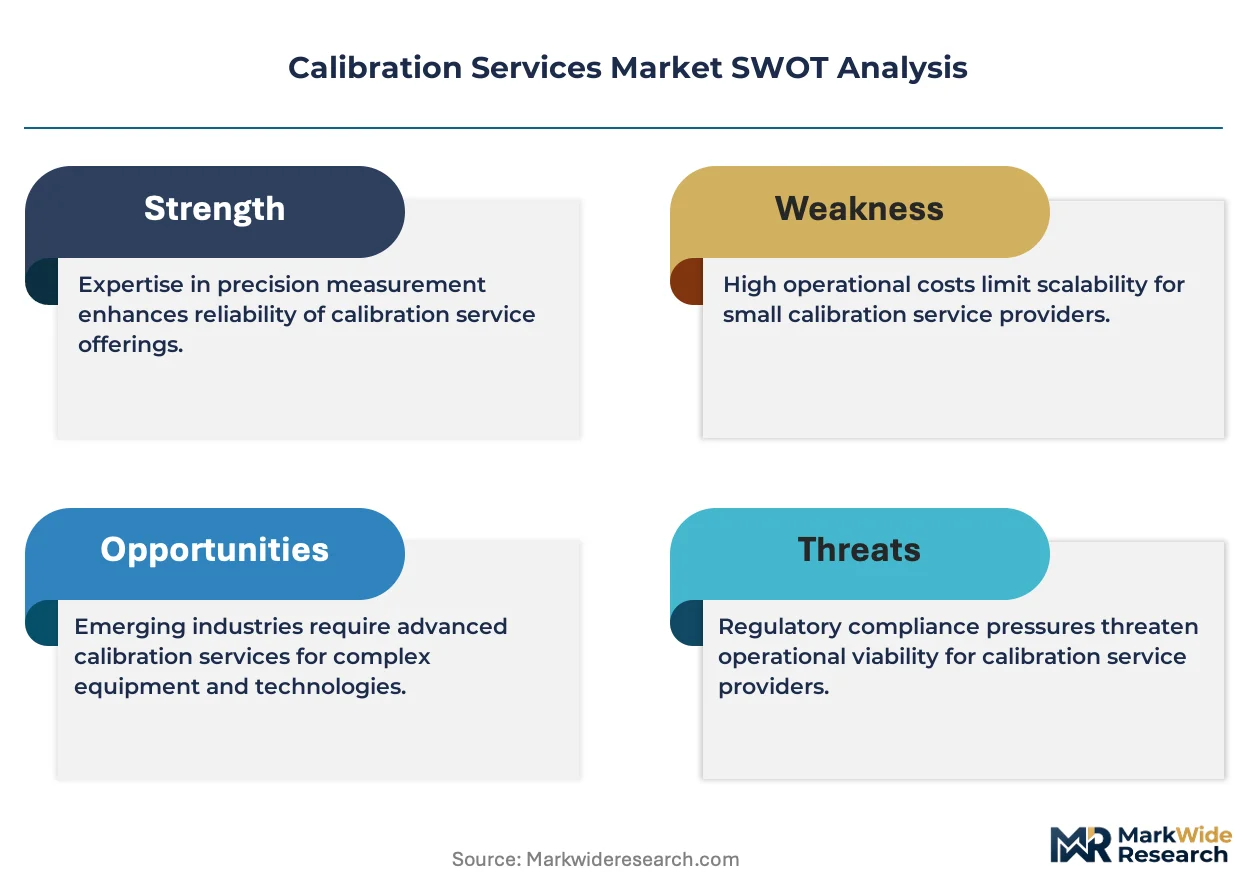
FDA 21 CFR Part 820, ISO/IEC 17025 accreditation requirements, and the EU Measuring Instruments Directive collectively mandate demonstrable metrological traceability for regulated industries, forcing service providers to maintain multi-standard competency and audit-ready documentation. NHTSA's vehicle safety testing protocols and FAA repair station rules extend this compliance burden into transportation verticals. Stakeholders must evaluate whether to build captive calibration laboratories or outsource to accredited providers as instrumentation portfolios diversify and regulatory scrutiny intensifies.
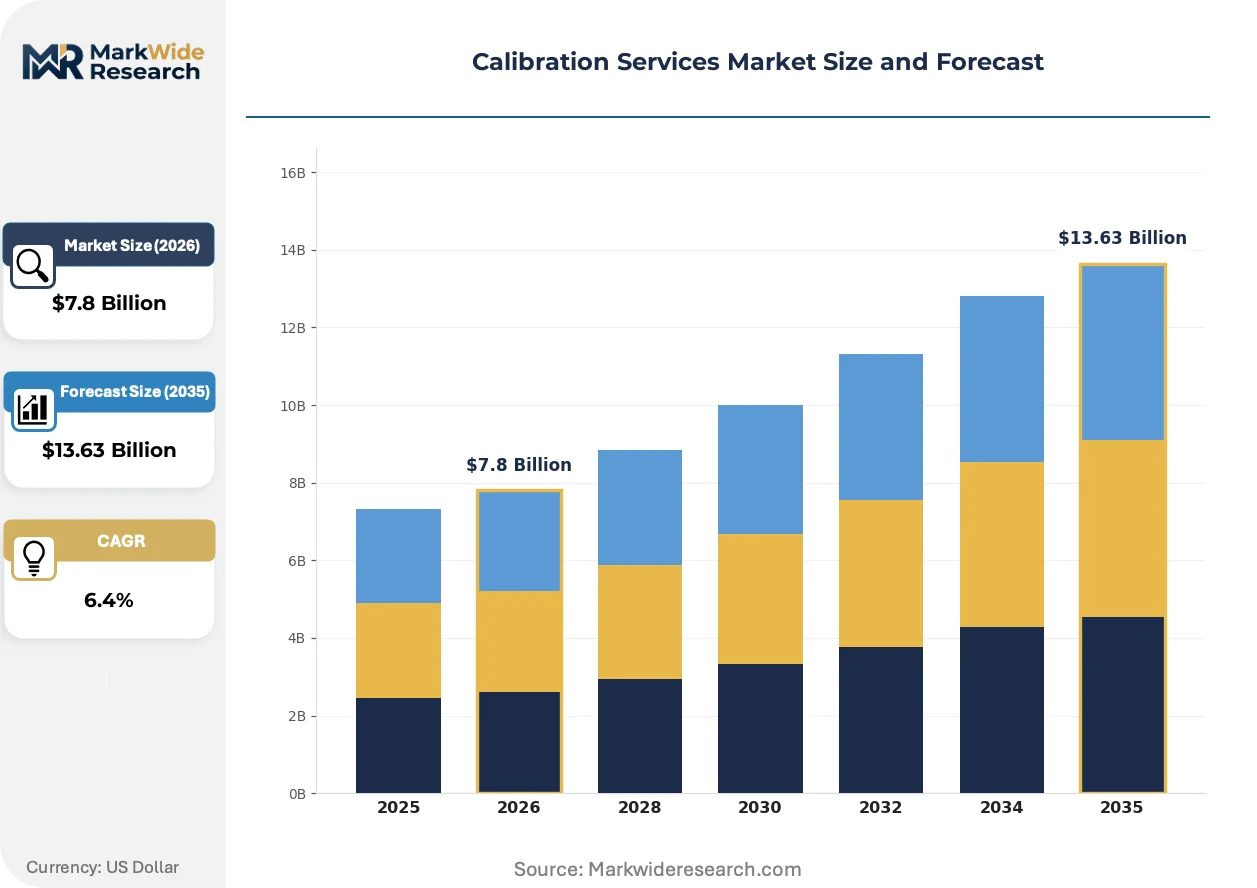
Market Dynamics
Cloud-connected asset management platforms are consolidating calibration workflows by bundling automated scheduling with real-time drift monitoring, compressing the traditional vendor-buyer relationship into continuous digital engagement.
Growth Catalysts
- EU Measuring Instruments Directive:Mandates demonstrable metrological traceability for industrial equipment, compelling manufacturers across Germany, France, and Italy to maintain accredited calibration partnerships.
- Aerospace airworthiness protocols:FAA repair station rules and EASA Part 145 requirements force MRO facilities to outsource precision instrument verification to ILAC-MRA accredited laboratories.
- Electronics test environments:The ubiquity of multimeters, oscilloscopes, and power analyzers in automotive R&D centers generates recurring demand for electrical calibration cycles.
Market Restraints
- Reference standard volatility:Platinum-iridium alloy and specialized ceramic substrates used in primary standards face supply concentration from a limited set of national metrology institutes.
- Accreditation cost structure:ISO/IEC 17025 compliance demands perpetual investment in interlaboratory comparisons, proficiency testing, and auditor training that smaller regional providers cannot sustain.
- Automated system substitution:In-house automated calibration workstations with embedded uncertainty calculators reduce reliance on external service providers for high-volume production lines.
Strategic Opportunities
- India's precision manufacturing corridor:BIS certification requirements and the PLI scheme for electronics assembly create demand for traceable calibration infrastructure around Bengaluru and Pune.
- Medical device convergence:Wearable diagnostics and point-of-care instruments require novel biocompatibility-aware calibration protocols that accredited labs can develop as differentiated offerings.
- Digital thread integration:API-first calibration platforms that feed directly into enterprise ERP and quality management systems represent white space beyond standalone software modules.
Industry Challenges
- Metrologist talent scarcity:The specialized skill set combining uncertainty analysis, thermodynamics, and regulatory documentation faces generational replacement gaps in both developed and emerging markets.
- Legacy system integration friction:Paper-based calibration certificates and disconnected asset databases resist migration to cloud-native platforms without substantial data cleansing investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calibration Services Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Electrical, Mechanical, Thermal, Dimensional End User: Aerospace, Automotive, Manufacturing, Electronics Technology: Manual, Automated, Portable, In-house Industry Vertical: Healthcare, Oil & Gas, Telecommunications, Food & Beverage |
| Companies Covered | Tektronix, Mettler Toledo, Trescal, Intertek Group, Hexagon AB, Keysight Technologies, VIAVI Solutions, TÜV Rheinland AG, Rohde & Schwarz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calibration Services Market Strategic Shifts & Innovations
Calibration service delivery is fragmenting across three vectors: the automation of bench-level procedures, the tightening of cross-border accreditation reciprocity, and the unbundling of verification from repair and asset management.
Automated calibration systems equipped with robotic artifact handling and machine-vision alignment are overtaking manual bench setups in high-throughput electronics manufacturing. Automotive tier-1 suppliers in Germany and South Korea deploy these systems for 24/7 production line verification. The technology is compressing turnaround times from days to hours while eliminating operator-induced variance in guard-banding calculations.
MDR and IVDR implementation in Europe is mandating stricter instrument traceability for medical device manufacturers. The regulations require documented calibration intervals tied to risk classification rather than generic annual cycles. In-vitro diagnostic producers in Ireland and the Netherlands are restructuring supplier qualification programs to prioritize DAkkS and UKAS-accredited laboratories with dedicated healthcare metrology competencies.
Asset-light procurement models are displacing long-term exclusive calibration contracts in industrial manufacturing. Buyers now aggregate instrument portfolios across multiple sites and auction verification work to accredited networks through digital tendering platforms. This pattern is most visible among pharmaceutical multinationals operating FDA-inspected facilities across Switzerland, Singapore, and Puerto Rico.
Calibration Services Market Segmentation
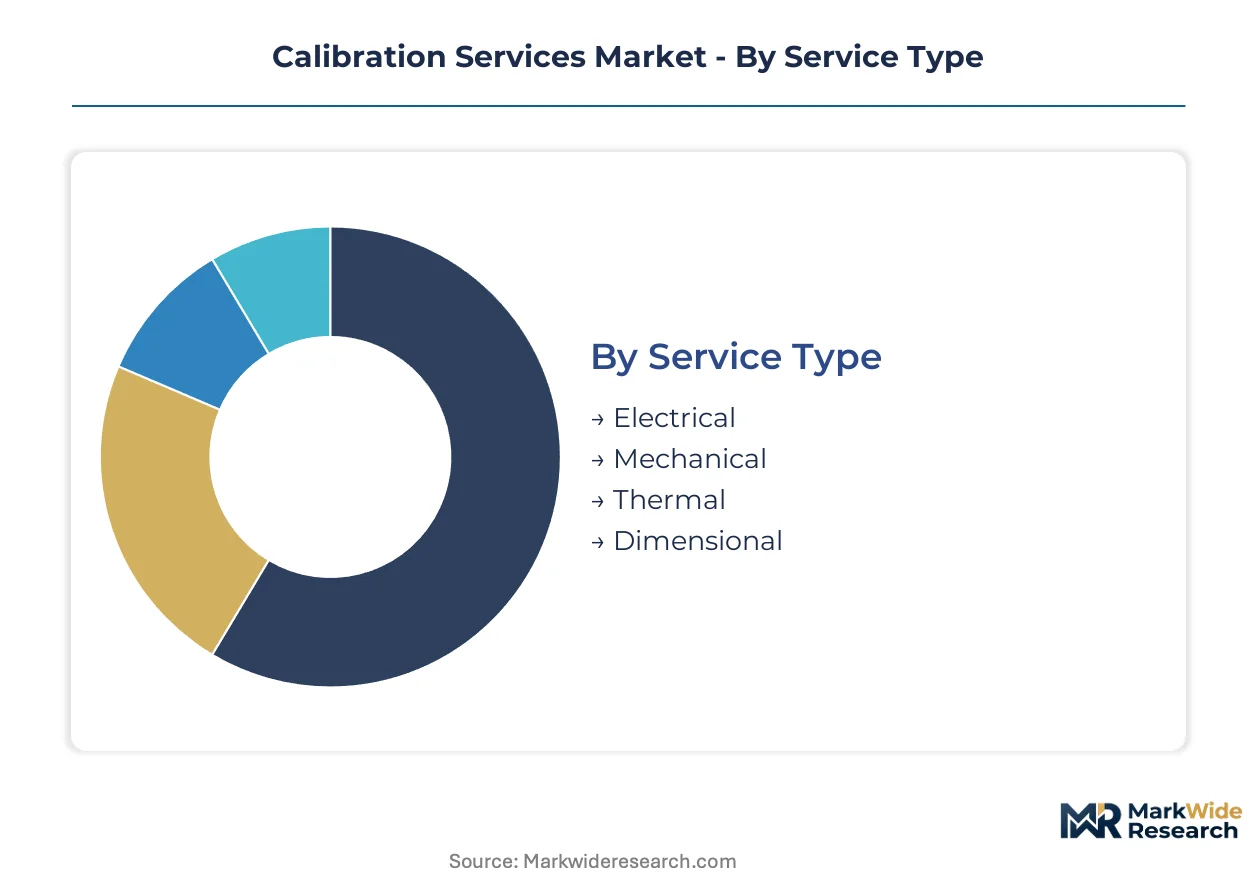
Calibration service providers configure their laboratory infrastructure and technician specializations around distinct technical domains and client operational models. Segmentation reveals where capital deployment concentrates and which verification protocols command premium pricing.
Service Type:
Electrical calibration demands the heaviest upfront investment in primary voltage references and RF power standards traceable to national metrology institutes.
- Electrical:Multimeter, oscilloscope, and power analyzer verification against Josephson junction voltage standards requires cryogenic reference systems and shielded laboratory environments. Semiconductor fabs in Taiwan and South Korea sustain the densest demand cycles for high-frequency RF calibration.
- Mechanical:Force, torque, and pressure instrument verification employs deadweight testers and strain-gauge reference transducers. Automotive powertrain test cells in Stuttgart and Detroit generate recurring demand for dynamic torque calibration at production-line throughput.
- Thermal:Temperature sensor and furnace calibration against fixed-point cells uses indium, tin, and zinc phase transitions. Pharmaceutical stability chambers in Ireland and Singapore require documented thermal uniformity mapping under FDA 21 CFR Part 11 protocols.
- Dimensional:Gauge block and coordinate measuring machine verification relies on laser interferometry and tactile probing systems. Precision aerospace machining clusters around Toulouse and Wichita sustain demand for sub-micron length standard traceability.
Most installed capacity flows through Electrical. Expansion is steepest in Dimensional as additive manufacturing tolerances tighten.
End User:
Capital recovery timelines vary dramatically across end-user categories, with aerospace contracts extending across multi-year airworthiness certification cycles.
- Aerospace:FAA repair station and EASA Part 145 compliance mandates ILAC-MRA accredited calibration for flight-critical measurement chains. Boeing and Airbus tier-1 suppliers in Toulouse and Seattle outsource precision instrument verification to maintain audit-ready documentation.
- Automotive:NHTSA safety testing protocols and powertrain electrification drive demand for high-voltage and electromagnetic compatibility calibration. Battery cell manufacturers in Nevada and Thuringia require documented measurement uncertainty for cell formation equipment.
- Manufacturing:General industrial metrology spans coordinate measuring machines, surface roughness testers, and hardness calibration. Machine tool builders in Switzerland and Japan maintain captive laboratories for spindle and axis verification.
- Electronics:5G base station and smartphone test environments demand vector network analyzer and spectrum analyzer calibration. Contract manufacturers in Shenzhen and Penang operate 24-hour calibration shifts for production line throughput.
Contract values peak in Aerospace. Volume throughput concentrates in Electronics.
Technology:
Laboratory automation separates high-throughput providers from manual bench operations, with robotic artifact handling compressing turnaround times.
- Manual:Technician-operated bench procedures dominate low-volume, high-complexity instruments requiring subjective alignment judgment. National metrology institutes in Germany and the United States reserve manual methods for primary standard realization.
- Automated:Robotic artifact handling and machine-vision alignment enable unattended overnight calibration sequences. Automotive tier-1 suppliers in Bavaria and Gyeonggi-do deploy these systems for production-line gauge verification.
- Portable:On-site calibration vehicles bring reference standards directly to client facilities, eliminating instrument shipping risk. Oil & gas pipeline operators in Alberta and Kazakhstan rely on portable deadweight testers for pressure safety valve verification.
- In-house:Captive calibration laboratories within manufacturing sites maintain direct control over measurement uncertainty budgets. Medtronic and Johnson & Johnson operate FDA-registered in-house labs for surgical instrument verification.
Provider margins are widest in Portable. Technology investment concentrates in Automated.
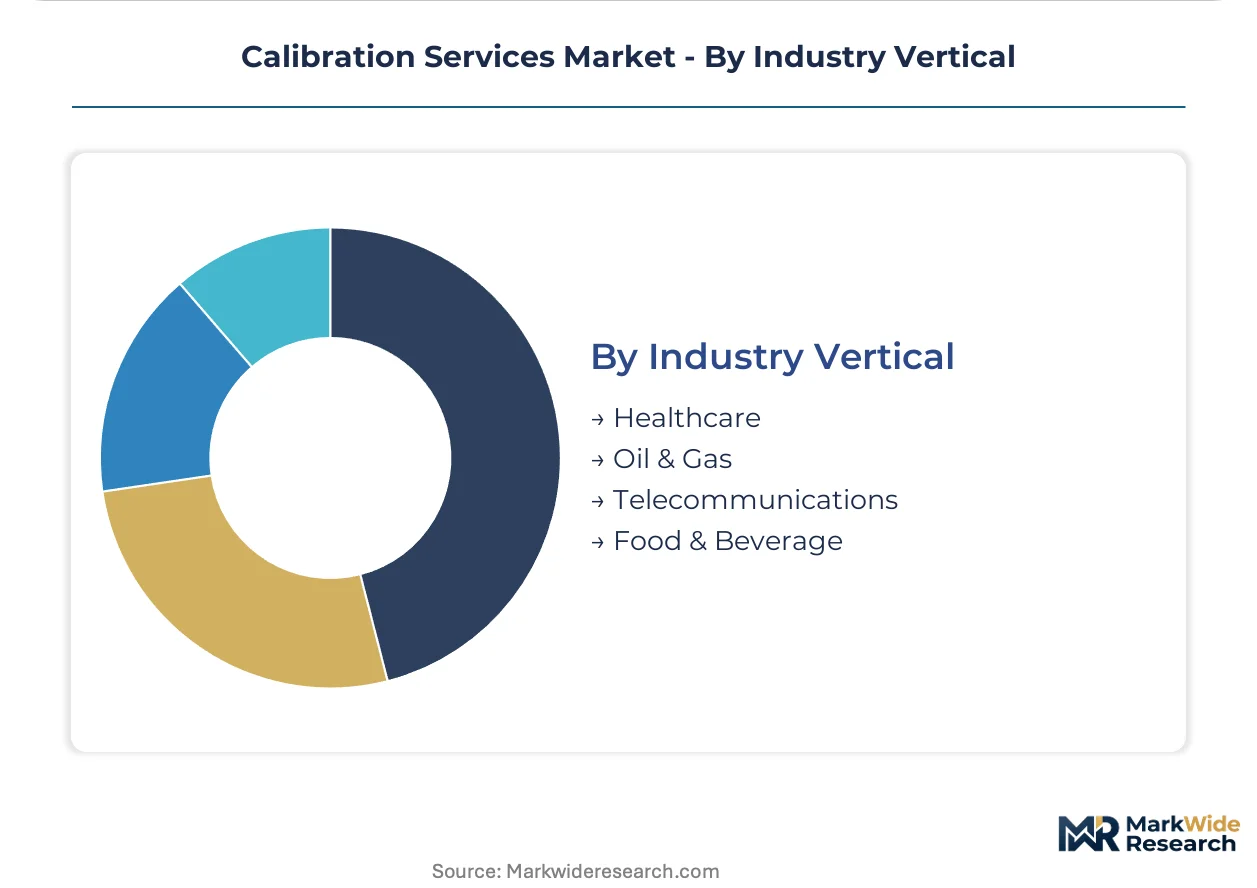
Industry Vertical:
Regulatory stringency determines pricing power, with healthcare and food safety commanding the strictest accreditation requirements.
- Healthcare:FDA 21 CFR Part 820 and EU MDR mandate documented calibration intervals tied to device risk classification. In-vitro diagnostic manufacturers in the Netherlands and Massachusetts restructure supplier qualification around DAkkS and UKAS healthcare metrology competencies.
- Oil & Gas:API standards and custody transfer regulations require flow meter and tank calibration traceable to national standards. LNG export terminals in Qatar and Australia maintain continuous verification contracts for ultrasonic flow measurement.
- Telecommunications:5G mmWave and optical fiber test equipment calibration supports network equipment manufacturer R&D cycles. Ericsson and Nokia suppliers in Finland and Sweden require phase noise and modulation analyzer verification.
- Food & Beverage:HACCP and FSMA regulations mandate temperature and pH meter calibration for process control. Dairy processors in Wisconsin and Normandy operate continuous verification programs for pasteurization monitoring.
Accreditation barriers are highest in Healthcare. Procurement volume concentrates in Oil & Gas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the densest concentration of industrial metrology infrastructure, while the United States sustains the broadest aerospace and defense calibration demand. Regulatory fragmentation across jurisdictions forces multinational manufacturers to maintain accredited laboratory networks in multiple countries.
Germany
Automotive electrification and precision manufacturing drive verification demand for torque transducers and high-voltage test equipment. The EU Measuring Instruments Directive mandates traceable calibration for industrial measuring devices used in trade. Stuttgart and Munich host clusters of DAkkS-accredited laboratories serving Bosch, Siemens, and tier-1 automotive suppliers.
United States
FAA repair station rules and NHTSA safety testing protocols compel aerospace and automotive manufacturers to outsource instrument verification. FDA 21 CFR Part 820 enforcement in medical device hubs creates recurring demand for documented calibration intervals. Seattle's Boeing supplier ecosystem and Boston's medical device corridor sustain ILAC-MRA accredited laboratory networks.
China
Semiconductor fabrication expansion in the Yangtze River Delta generates demand for RF and high-frequency calibration traceable to national standards. SAMR oversight of measuring instruments for trade enforcement compels electronics manufacturers to maintain accredited partnerships. Shenzhen contract manufacturers operate 24-hour calibration shifts for smartphone and 5G base station test equipment.
India
BIS certification requirements and the PLI scheme for electronics assembly create demand for traceable calibration infrastructure. CDSCO medical device regulations mandate instrument verification for diagnostic equipment manufacturers. Bengaluru and Pune precision manufacturing clusters attract NABL-accredited laboratory investments from multinational service providers.
South Korea
Memory semiconductor and display panel test environments sustain dense demand for electrical and dimensional calibration cycles. MFDS medical device regulations require documented metrological traceability for in-vitro diagnostic producers. Gyeonggi-do automotive tier-1 suppliers deploy automated calibration systems for production-line gauge verification.
Calibration Services Market Key Industry Players
Top-tier vendors anchor enterprise accounts through integrated software platforms, while mid-tier specialists compete on geographic density and sector-specific accreditation. The vendor base stratifies across three tiers: multinational testing giants with ILAC-MRA networks, regional laboratory chains with national accreditation, and captive in-house operations within large manufacturers. Two dominant competitive moves define positioning: cloud-connected asset management platform development and pan-regional laboratory network expansion through acquisition.
Within the test-and-measurement heritage tier, Keysight Technologies and Tektronix exemplify vendors leveraging instrument manufacturing roots to anchor calibration management software sales. Trescal occupies a position among European laboratory network specialists competing through geographic coverage density rather than vertical integration. These three represent distinct archetypes: equipment-origin platforms, independent laboratory networks, and hybrid service-technology bundlers.
| Leading Market Players |
|---|
| Tektronix |
| Mettler Toledo |
| Trescal |
| Intertek Group |
| Hexagon AB |
| Keysight Technologies |
| VIAVI Solutions |
| TÜV Rheinland AG |
| Rohde & Schwarz |
| Others |
Cost & Logistics Intelligence
Accreditation-grade bifurcation between ILAC-MRA accredited laboratories and non-accredited regional providers manifests in both pricing power and supply chain resilience. Premium-tier providers command sustained margins through embedded software platforms and audit-ready documentation, while commodity calibration faces cost compression from automated in-house systems and digital tendering platforms that aggregate demand across pharmaceutical multinationals.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard electrical and mechanical calibration services. Three-tier pricing structure across premium, standard, and economy levels separates ILAC-MRA accredited laboratories with embedded asset management software from national-accreditation providers and unaccredited local shops. Price differentiation rests on certification tier and geographic delivery cost, with on-site portable calibration commanding widest margins. Cost compression in economy-tier bench services is intensifying because automated calibration workstations reduce external dependency. Pharmaceutical multinationals operating FDA-inspected facilities show least price sensitivity, while general manufacturing procurement teams exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with platinum-iridium alloy reference standards sourced primarily from NIST and PTB national metrology institutes. Supply concentration centers on Germany, the United States, and Japan for primary voltage references, Josephson junction systems, and ceramic substrate standards. Raw material dependencies encompass cryogenic cooling systems, specialized RF power sensors, and precision gauge block ceramics. Tariff exposure runs through cross-border shipment of temperature fixed-point cells and laser interferometry components. Distribution runs through accredited laboratory networks with regional hub-and-spoke configurations, supplemented by portable calibration vehicles for on-site verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in calibration services hinges on software platform bundling that transforms transactional verification into recurring SaaS relationships. Cloud-connected asset management systems reduce customer churn while capturing premium pricing through integrated drift monitoring and automated scheduling.
For Market Incumbents: Lock in enterprise accounts by deepening API-first integration into client ERP and quality management systems. Expand automated calibration capacity in South Korea and Germany to defend against in-house workstation substitution. Prioritize DAkkS and UKAS healthcare metrology competencies to capture MDR and IVDR implementation demand from in-vitro diagnostic manufacturers. For New Entrants and Emerging Players: Machine-vision alignment technology for unattended overnight calibration sequences offers a technology-first wedge into automotive tier-1 supplier accounts in Bavaria and Gyeonggi-do. Target India's precision manufacturing corridor around Bengaluru and Pune, where BIS certification requirements and PLI scheme incentives outpace accredited laboratory infrastructure. Deploy digital tendering platform participation as the primary go-to-market angle to bypass entrenched exclusive contracts. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale accredited laboratory networks possessing healthcare metrology competencies but lacking integrated software platforms. Long-term viability favors providers that bridge physical calibration expertise with cloud-native asset management capabilities. Acquisition target archetype: regional DAkkS or UKAS-accredited labs with established pharmaceutical client relationships and underinvested digital infrastructure. Watch FDA 21 CFR Part 820 enforcement intensity and EU MDR implementation pace as inflection indicators for healthcare calibration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first calibration systems feeding directly into Siemens and SAP ERP environments capture enterprise stickiness. |
| Healthcare Metrology Competency Buildout | DAkkS-accredited labs with dedicated IVDR protocols secure restructuring supplier qualification programs in Ireland and Netherlands. |
| Automated Calibration Capacity Expansion | Robotic artifact handling systems in Germany and South Korea compress turnaround times from days to hours for automotive clients. |
| Geographic Expansion | NABL-accredited laboratory investments in Bengaluru and Pune address BIS certification gaps in India's electronics assembly corridor. |
| Acquisition of Specialist Firm | Regional laboratories with FDA-registered in-house capabilities extend reach into Medtronic and Johnson & Johnson supplier networks. |
Research Approach
Bottom-up end-user modeling reconciled against top-down laboratory capacity tracking forms the analytical core of this study. Primary interviews with calibration laboratory directors, biomedical engineers at medical device manufacturers, quality assurance managers at automotive tier-1 suppliers, and GPO contracts managers at hospital systems combined with secondary validation from FDA 483 inspection observations, DAkkS and UKAS accreditation registries, SEC filings of listed testing companies, and customs data on reference standard imports. Triangulation across these sources ensures demand estimates align with verified laboratory throughput capacity.
Historical trendline analysis of calibration cycle frequencies by instrument category established baseline demand patterns across the projection horizon. Segmentation dimensions modeled encompass service type, end-user industry, technology tier, and geographic regulatory cluster. CAGRs were derived from instrument installed base growth, regulatory interval tightening, and automation substitution elasticity. Industry-specific forecast inputs include semiconductor fab equipment spend trajectories and medical device PMA submission volumes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NIST funding continuity, ILAC-MRA mutual recognition scope expansion, and generational replacement gaps in metrologist talent pools. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
RFID Tester Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
Power Electronics GaN and SiC Device Reliability Test Systems Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
ESG Sensor Data Quality and Validation Test Platforms Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Dosimeter Market
Test and Measurement
5G Testing Equipment Market
Test and Measurement
Digital Video Extensometers Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
One-Box Testers Market
Test and Measurement
Fluorometers Market