
 Non-Destructive Testing (NDT) Service Market | 2026-2036
Non-Destructive Testing (NDT) Service Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Destructive Testing (NDT) Service Market Analysis
North American inspection laboratory capacity is decoupling from traditional oilfield service pricing, creating margin autonomy for specialized providers. MISTRAS Group leverages its refinery-centric footprint to sustain recurring turnaround contracts across the Gulf Coast. Bureau Veritas anchors its competitive position through marine and offshore certification authority. SGS Société Générale de Surveillance SA differentiates via its global network density in energy and industrial corridors.
Non-Destructive Testing (NDT) Services encompass inspection methodologies that evaluate material properties, structural integrity, and component defects without impairing future utility, utilizing ultrasonic wave propagation, radiographic imaging, magnetic flux leakage, and electromagnetic induction across frequencies from kilohertz to megahertz. These services primarily assure safety compliance, prevent catastrophic failure, and extend operational life in pressure-boundary equipment, welded joints, and load-bearing structures. Ultrasonic Testing commands the largest share of service revenue due to its portability and crack-sizing precision in thick-walled pressure vessels. Radiographic Testing retains dominance in pipeline girth weld verification where volumetric defect documentation is mandatory. Visual Inspection, though lowest in unit cost, generates substantial volume through baseline condition assessment across construction and maritime applications.
API 510, API 570, and API 653 standards enforced by OSHA-process-safety inspectors shape inspection frequency and technique selection in US downstream facilities. ASME Boiler and Pressure Vessel Code Section V governs NDT procedure qualification, directly determining service provider accreditation thresholds and market access eligibility. Stakeholders must monitor evolving drone-deployed thermography and AI-assisted defect recognition as these technologies compress inspection timelines and redistribute value from manual interpretation toward automated analytics platforms.
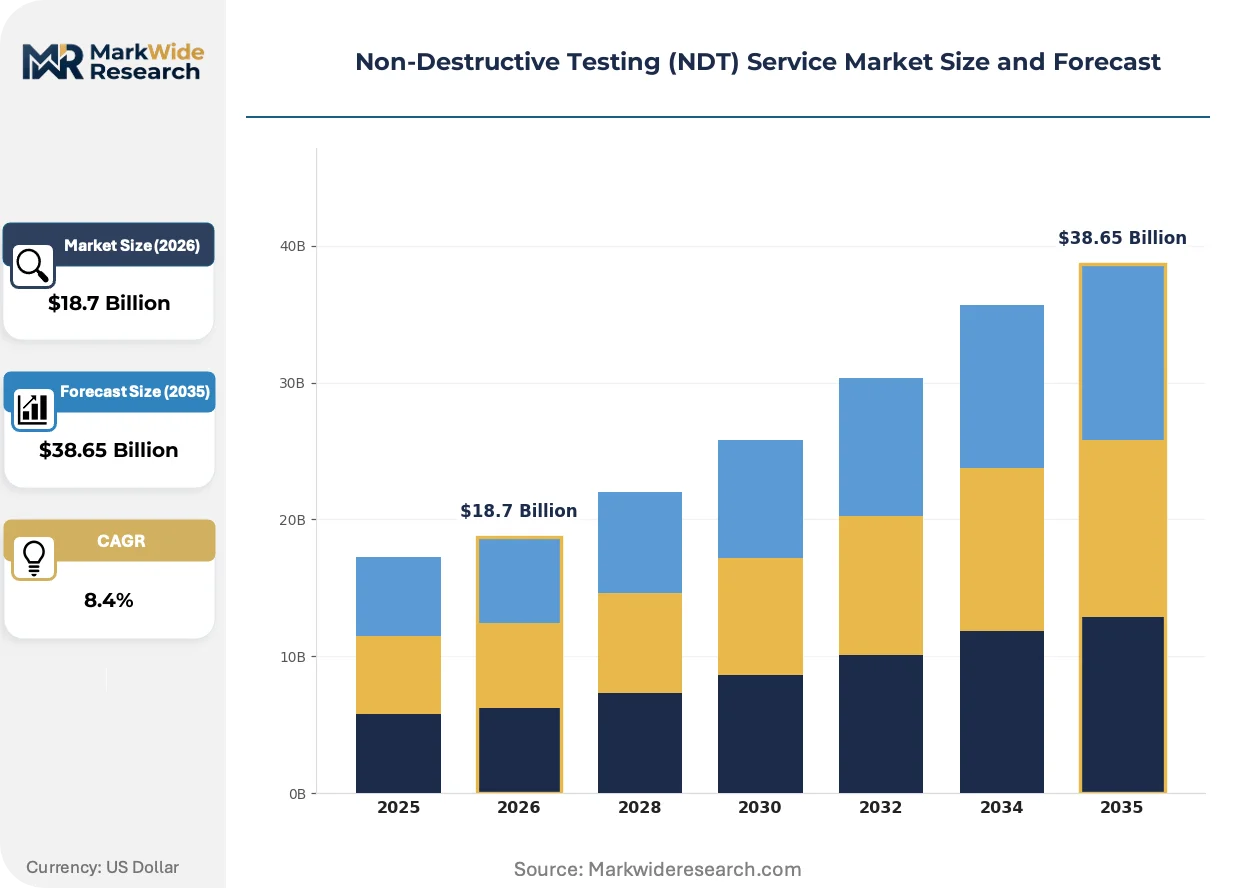
Market Dynamics
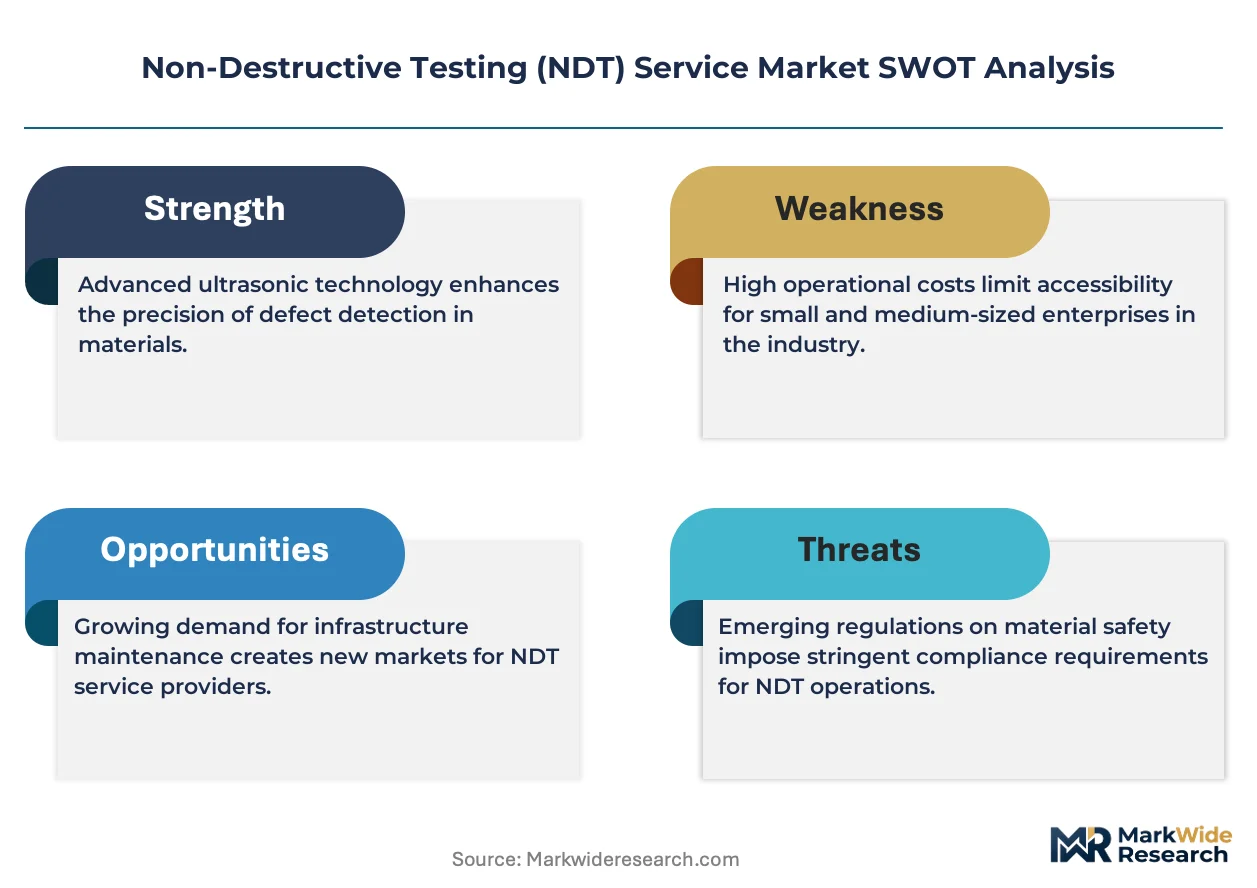
Drone-deployed thermography and AI-assisted defect recognition are compressing inspection timelines and redistributing value from manual interpretation toward automated analytics platforms across pressure-boundary equipment assessment.
Growth Catalysts
- API 510 Pressure Vessel Inspection Mandates:OSHA-process-safety inspectors enforce tighter turnaround cycles at US refineries, sustaining recurring contract volumes for specialized providers.
- Ultrasonic Phased Array Advancement:Crack-sizing precision in thick-walled components drives replacement of radiographic methods in aerospace airframe inspection cycles.
- Pipeline Integrity Management Requirements:FERC-regulated transmission operators face escalating girth weld verification obligations across interstate natural gas infrastructure.
Market Restraints
- Certified Inspector Supply Scarcity:ASME Section V qualification timelines stretch 18-24 months, constraining provider capacity expansion.
- Isotope Sourcing Concentration:Radiographic testing depends on cobalt-60 and iridium-192 supply chains concentrated in Russia and South Africa.
- Equipment Capital Intensity:Automated ultrasonic testing systems require $150,000-$400,000 initial outlay, limiting mid-tier provider participation.
Strategic Opportunities
- Offshore Wind Foundation Inspection:Bureau Veritas marine certification authority positions service providers for monopile weld assessment in North Sea developments.
- AI-Defect Recognition Integration:Machine learning algorithms trained on historical radiographic film archives enable real-time anomaly flagging during pipeline construction.
- Turnaround Service Unbundling:Refinery operators separate mechanical maintenance from NDT scope, creating standalone inspection contract opportunities.
Industry Challenges
- Multi-Standard Certification Burden:Providers must maintain parallel ASME, API, and ISO 9712 qualifications to access cross-sector opportunities.
- Legacy System Integration Friction:Digital radiography outputs require format conversion to interface with decades-old asset management databases at downstream facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Destructive Testing (NDT) Service Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ultrasonic Testing, Radiographic Testing, Magnetic Particle Testing, Visual Inspection Industry Vertical: Aerospace, Automotive, Oil & Gas, Construction Technology: Electromagnetic Testing, Acoustic Emission Testing, Thermography, Laser Testing Application: Pipeline Integrity, Weld Inspection, Material Testing, Structural Evaluation |
| Companies Covered | MISTRAS Group, Bureau Veritas, SGS Société Générale de Surveillance SA, Applus+, Intertek Group plc, TÜV Rheinland, Element Materials Technology, Ashtead Technology, DEKRA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Destructive Testing (NDT) Service Market Emerging Trajectories
Thermographic imaging systems are migrating from laboratory settings to field-deployable configurations. Automated defect classification algorithms are reducing interpretation cycle times. Service providers are restructuring workforce composition toward data science capabilities.
Phased array ultrasonic testing is converging with robotics for confined-space vessel inspection. Offshore platform operators in the Gulf of Mexico deploy crawler-mounted transducer arrays for storage tank floor assessment without human entry. This convergence is eliminating scaffolding costs and reducing inspection preparation from days to hours.
REACH restrictions on industrial chemicals are reshaping penetrant testing formulations across European manufacturing. ECHA-registered fluorescent dyes face substitution pressure from water-removable alternatives. Aerospace suppliers in Germany and France accelerate validation of biodegradable contrast agents for turbine blade inspection.
Asset owner engineering teams now specify inspection-scope unbundling in turnaround procurement. Refinery maintenance contractors lose automatic NDT inclusion; specialized providers win direct contracts. This pattern concentrates in Texas and Louisiana where integrated operators maintain captive engineering standards.
Non-Destructive Testing (NDT) Service Market Segmentation
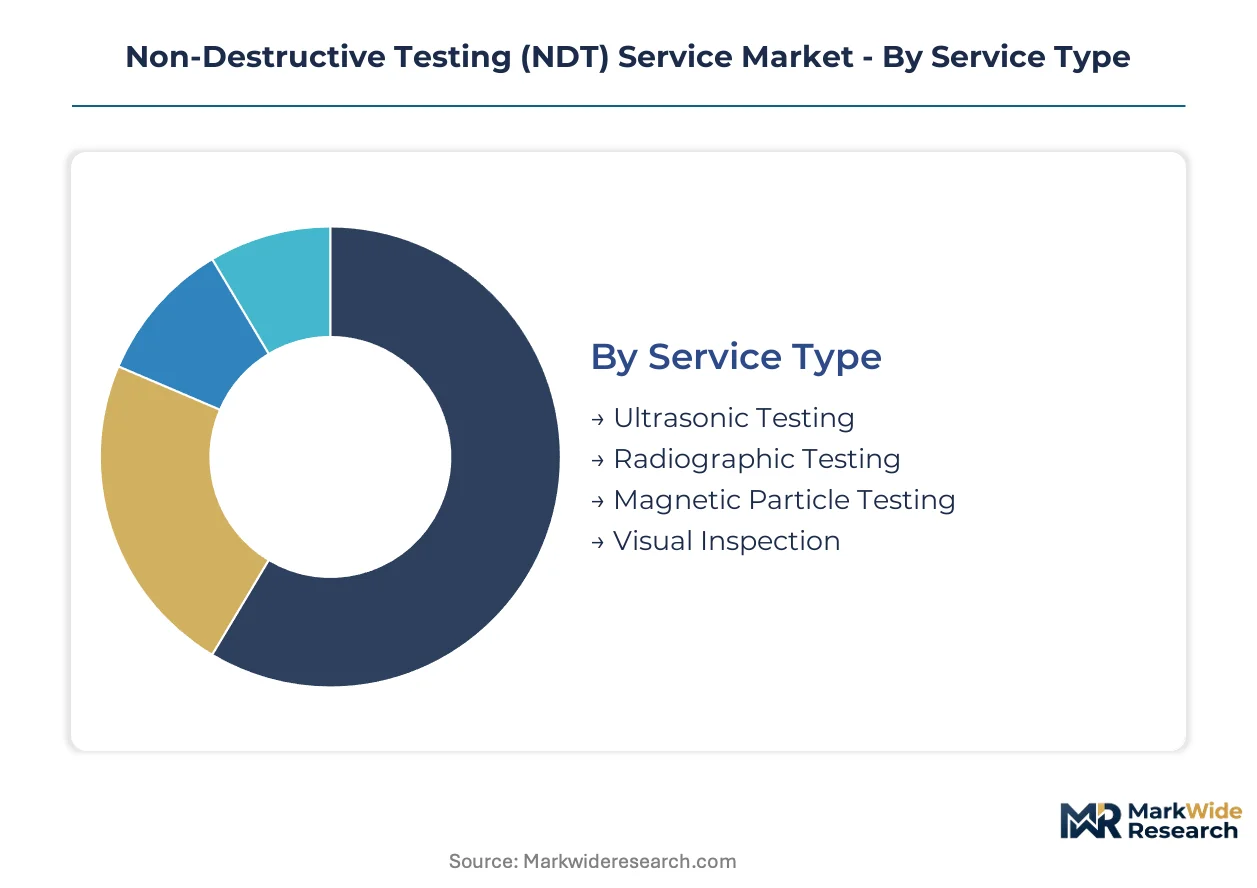
Segmentation in the NDT service market determines which providers qualify for specific contract tiers. Certification requirements vary sharply across service types and industry verticals, creating distinct competitive arenas with different margin profiles and barrier heights.
Service Type:
ASME Section V and ISO 9712 certifications gate market access unevenly across these methodologies, with volumetric techniques demanding lengthier qualification timelines than surface methods.
- Ultrasonic Testing:Phased array and time-of-flight diffraction techniques dominate thick-walled pressure vessel assessment. Demand concentrates in US Gulf Coast refineries where OSHA-process-safety mandates drive turnaround inspection volumes. API 510 qualification requirements restrict provider pools.
- Radiographic Testing:Gamma and X-ray sources deliver volumetric defect documentation for pipeline girth welds. FERC-regulated interstate transmission operators in Texas and Louisiana sustain contract flows through integrity management mandates. Isotope sourcing constraints limit capacity expansion.
- Magnetic Particle Testing:Surface-breaking flaw detection for ferromagnetic components in automotive stamping operations.
- Visual Inspection:Baseline condition assessment across maritime classification surveys and construction handovers.
Leading the category by volume: Ultrasonic Testing. Growing fastest: Radiographic Testing.
Industry Vertical:
End-use concentration shapes service provider specialization, with each vertical imposing distinct technical standards and procurement rhythms.
- Aerospace:FAA airworthiness directives and OEM specification control define inspection protocols for turbine blades and airframe structures. Phased array methods displace radiography in fatigue crack monitoring programs.
- Automotive:High-volume production lines demand rapid automated inspection for weld quality verification in electric vehicle battery tray assembly.
- Oil & Gas:Downstream facilities in the United States generate recurring contract volumes through API 510, 570, and 653 mandated turnaround cycles. Midstream pipeline operators face escalating FERC girth weld verification obligations.
- Construction:Structural steel fabrication inspection for seismic compliance drives demand in California and Pacific Northwest infrastructure projects.
Dominant revenue source: Oil & Gas. Steepest expansion trajectory: Aerospace.
Technology:
Equipment capital intensity and algorithm development costs stratify provider participation across these emerging and established platforms.
- Electromagnetic Testing:Eddy current arrays inspect heat exchanger tubing in refinery process units. Ease of automation supports high-throughput screening applications.
- Acoustic Emission Testing:Passive monitoring detects active crack growth in pressure vessels during hydrostatic testing. Lower deployment frequency limits market penetration.
- Thermography:Drone-mounted infrared systems assess electrical substations and photovoltaic installations. AI-assisted defect recognition compresses interpretation timelines.
- Laser Testing:Shearography and holography methods target composite delamination in aerospace structures. High equipment costs constrain adoption.
Highest deployment frequency: Electromagnetic Testing. Gaining share fastest: Thermography.
Application:
Regulatory enforcement intensity varies by application, with pressure-boundary equipment facing the most stringent inspection mandates.
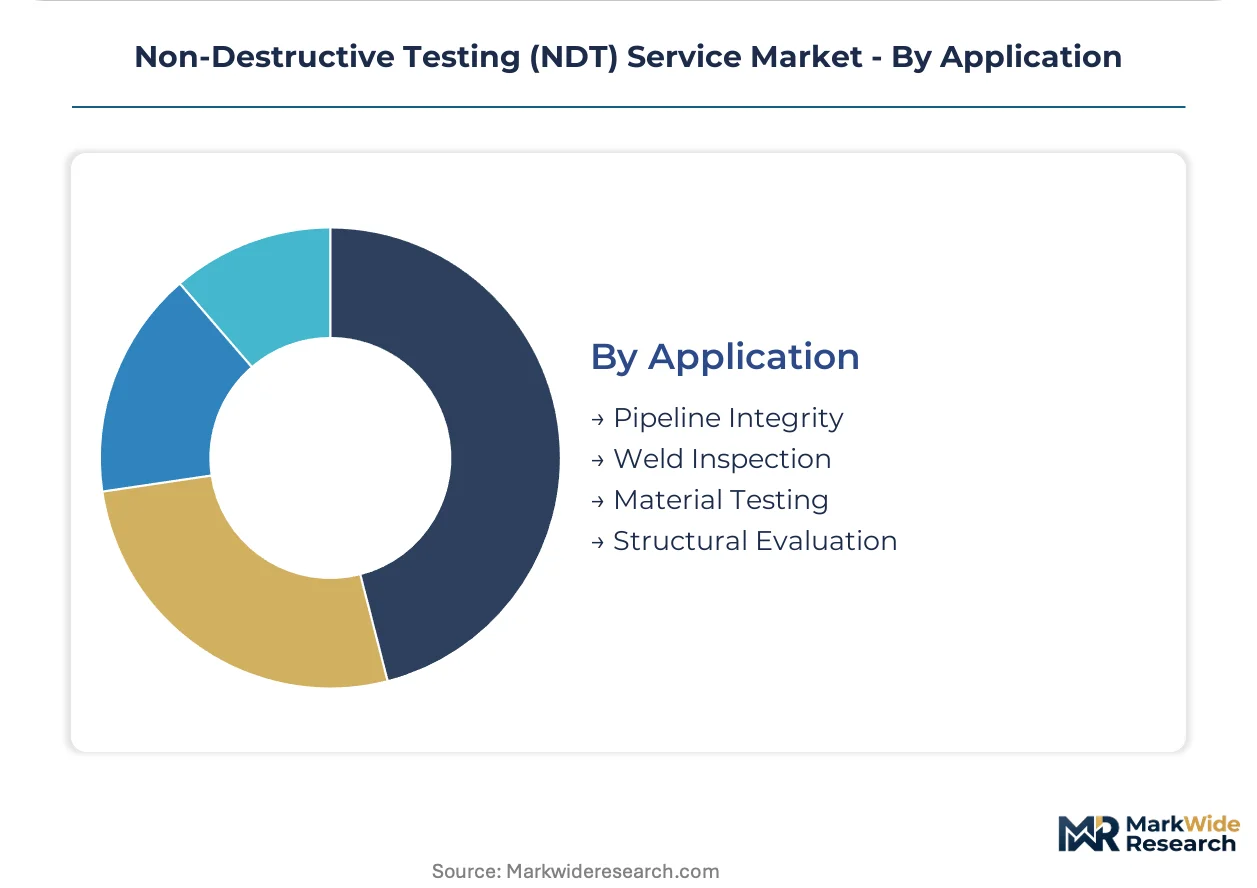
- Pipeline Integrity:FERC-regulated transmission and distribution operators maintain continuous assessment programs for high-consequence areas. Smart pig validation and direct assessment protocols sustain service demand across interstate infrastructure.
- Weld Inspection:ASME Boiler and Pressure Vessel Code Section IX qualification requirements govern procedure approval for structural and pressure-containing joints. Fabrication shops in Houston and Beaumont generate concentrated contract volumes.
- Material Testing:Metallurgical verification for incoming raw stock in aerospace supply chains.
- Structural Evaluation:Bridge and building condition assessment for state department of transportation compliance.
Largest contract scale: Pipeline Integrity. Expanding most quickly: Weld Inspection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cobalt-60 and iridium-192 sourcing corridors anchor radiographic testing capacity in Russia and South Africa, yet service demand concentrates where pipeline integrity mandates and refinery turnaround cycles create contract density.
United States
Gulf Coast refineries sustain recurring API 510 turnaround volumes while FERC-regulated interstate pipelines escalate girth weld verification obligations. OSHA-process-safety inspectors enforce tighter inspection frequencies at downstream facilities. Houston and Beaumont fabrication clusters generate concentrated contract flows for ASME-qualified providers.
Germany
Aerospace suppliers accelerate phased array validation for turbine blade fatigue monitoring as REACH restrictions reshape penetrant testing formulations. ECHA-registered fluorescent dyes face substitution pressure from water-removable alternatives. Munich and Hamburg engineering centers drive biodegradable contrast agent development.
China
GB standards governing pressure vessel inspection expand domestic qualification requirements for ultrasonic and radiographic methods. SAMR oversight tightens weld verification protocols across petrochemical infrastructure buildouts. Yangtze River Delta fabrication yards concentrate demand for automated testing systems.
Saudi Arabia
Downstream expansion at Jubail and Yanbu industrial cities sustains volumetric inspection demand for thick-walled process equipment. The country's national petroleum regulator mandates API-aligned qualification for turnaround contractors. Eastern Province energy corridors attract specialized NDT providers through long-term maintenance agreements.
United Kingdom
North Sea offshore platform operators deploy crawler-mounted transducer arrays for storage tank floor assessment without human entry. HSE regulations govern confined-space inspection protocols. Aberdeen subsea engineering clusters drive robotics convergence with phased array methods.
Non-Destructive Testing (NDT) Service Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-assisted defect recognition and drone-deployed thermography. The provider base stratifies across three tiers: integrated multinationals with marine certification authority, refinery-centric specialists with recurring turnaround footprints, and technology-focused disruptors compressing interpretation timelines. Two dominant competitive moves define current positioning: M&A activity consolidating regional laboratory networks, and strategic partnerships pairing automated equipment vendors with data analytics platforms.
Within the integrated multinational tier, Bureau Veritas and SGS Société Générale de Surveillance SA exemplify archetypes leveraging global network density and certification authority to anchor cross-sector contracts. MISTRAS Group occupies a position representing the refinery-centric specialist model, sustaining recurring volumes through Gulf Coast turnaround relationships. These three entities illustrate how geographic footprint and regulatory accreditation interact to determine market access eligibility.
| Leading Market Players |
|---|
| MISTRAS Group |
| Bureau Veritas |
| SGS Société Générale de Surveillance SA |
| Applus+ |
| Intertek Group plc |
| TÜV Rheinland |
| Element Materials Technology |
| Ashtead Technology |
| DEKRA |
| Others |
Supply Flow & Price Mechanics
API 510 turnaround mandates at US Gulf Coast refineries are compressing procurement cycles and forcing service providers to pre-position certified inspection teams, which concentrates pricing power among ASME-qualified specialists with established refinery footprints.
Pricing Analysis
Warranty bundling separates full-service turnaround contracts from unbundled inspection-only scopes, with the latter commanding 15-25% price premiums due to liability transfer. Three-tier pricing structure across premium, standard, and economy levels reflects ASME Section V certification grade, equipment automation level, and geographic delivery radius. Cost compression in standard-tier radiographic testing is intensifying because isotope sourcing constraints limit provider expansion. Mid-tier fabrication shops in Houston and Beaumont exhibit highest price sensitivity; integrated refinery operators with captive engineering standards show lowest.
Supply Chain Analysis
ASME-certified inspector availability in Houston, Rotterdam, and Jubail determines service capacity deployment timelines across major energy corridors. Equipment manufacturing draws from Germany for phased array systems, Japan for eddy current instrumentation, and the United States for automated crawler platforms. Single-source vulnerability concentrates in cobalt-60 and iridium-192 isotope supply chains anchored in Russia and South Africa. Distribution runs through refinery turnaround procurement offices, marine classification societies, and aerospace OEM approved supplier lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified inspector scarcity stretching 18-24 months for ASME Section V qualification is propping pricing autonomy for incumbent providers with established training pipelines.
For Market Incumbents: Anchor competitive position through captive inspector training academies in Gulf Coast energy corridors, defending against AI-assisted defect recognition platforms that compress interpretation margins. Deepen backward integration into automated equipment manufacturing to control deployment timelines during turnaround rushes. For New Entrants and Emerging Players: Launch via drone-deployed thermography subscriptions targeting electrical substation and photovoltaic asset owners, bypassing ASME certification barriers that gate traditional pressure-vessel markets. Concentrate on FERC-regulated pipeline integrity direct assessment protocols where automated analytics platforms command pricing premiums over manual interpretation. For Investors and Strategic Acquirers: The window for entry favors technology-focused disruptors with proven AI-defect recognition algorithms and established equipment vendor partnerships. Monitor offshore wind foundation inspection contract awards as inflection indicator for marine certification authority valuations.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Defect Recognition Platform Development | Machine learning algorithms trained on API pipeline archives enable real-time anomaly flagging during construction. |
| ASME Inspector Training Academy Investment | Captive qualification pipelines address 18-24 month certification timelines constraining provider expansion. |
| Drone Thermography Service Launch | Field-deployable infrared systems compress electrical substation assessment timelines without scaffolding. |
| Offshore Wind Certification Partnership | Bureau Veritas marine authority positions providers for North Sea monopile weld assessment contracts. |
| Isotope Supply Chain Diversification | Alternative sourcing corridors reduce cobalt-60 concentration risk in Russia and South Africa. |
Methodological Framework
Document review covered ASME Boiler and Pressure Vessel Code filings, API inspection standard updates, and FERC pipeline integrity management reports, complemented by interviews with turnaround procurement managers at Gulf Coast refineries, ASME-qualified inspection contractors, marine classification surveyors, and aerospace supplier quality engineers. Secondary validation drew from OSHA process safety enforcement data, ECHA chemical restriction registers, and SAMR pressure vessel oversight disclosures. Bottom-up service provider capacity estimates and top-down end-use demand projections were triangulated against inspection frequency mandates.
Revenue and volume outputs across the projection horizon reflect modeled segmentation by service type, industry vertical, and technology platform, with ultrasonic and radiographic methods tracked separately. CAGRs were derived from inspection cycle compression rates, regulatory mandate expansion timelines, and equipment automation adoption curves. Forecast inputs incorporated refinery turnaround schedules, pipeline construction permit flows, and offshore wind installation projections.
The model assumes a particular technology adoption path; alternative pathways for AI-assisted defect recognition would alter the outlook if algorithm accuracy thresholds advance faster than ASME procedure qualification frameworks accommodate. Forecasts reflect assumptions about inspector supply elasticity, isotope sourcing stability, and regulatory enforcement intensity. Material deviation in API standard revision timelines or FERC integrity mandate scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Shock Data Logger Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
Calorimeters Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Test Rig Market
Test and Measurement
Data Center Testing Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Transformer Testing Equipment Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Calibration Solutions Market