
 Non-Destructive Testing (NDT) Software Market | 2026-2036
Non-Destructive Testing (NDT) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Destructive Testing (NDT) Software Market Analytics
The performance gap between premium analytics suites and commodity inspection tools is shifting how capital gets allocated across the NDT software stack. General Electric leverages its digital industrial heritage to anchor high-end predictive maintenance integrations. Eddyfi Technologies Inc. specializes in advanced eddy current array software for complex geometries. Baker Hughes Co. (Waygate Technologies) dominates inspection data standardization through its heritage platform reach.
Non-Destructive Testing (NDT) Software encompasses digital platforms that acquire, process, analyze, and archive inspection data from ultrasonic, radiographic, electromagnetic, and visual testing modalities, typically supporting real-time signal processing at sampling rates exceeding 100 MHz and compliance with ASTM E317 resolution standards. These systems enable flaw characterization, thickness mapping, and structural health monitoring without material destruction across welded joints, cast components, and composite laminates. Ultrasonic Testing software commands the largest revenue pool due to its penetration across pressure vessel and pipeline inspections, while Cloud-Based Solutions represent the fastest expansion vector as distributed inspection teams demand centralized data lakes. Digital Imaging technology sustains margin concentration through proprietary reconstruction algorithms that reduce false call rates.
FAA airworthiness directives and ASME Boiler and Pressure Vessel Code standards in the United States, alongside EASA certification requirements and EU Pressure Equipment Directive frameworks in Europe, mandate documented traceability for safety-critical inspections, directly expanding software licensing for compliance archiving. The EPA's leak detection and repair protocols for oil and gas infrastructure further tighten data retention requirements. Stakeholders must weigh cloud migration timelines against cybersecurity hardening for radiographic source control systems.
Market Dynamics
Cloud-based inspection data architectures are compressing deployment cycles and forcing legacy on-premise vendors to restructure licensing models around subscription economics.
Growth Catalysts
- ASME Section V mandates:Pressure equipment operators in the United States must archive ultrasonic and radiographic test data with full traceability, accelerating automated capture platform procurement.
- Composite airframe penetration:Aerospace manufacturers in Germany and France require specialized eddy current and phased array software for carbon fiber laminate inspection workflows.
- Pipeline integrity management:EPA leak detection protocols for midstream oil and gas infrastructure mandate continuous monitoring data retention, expanding software licensing for ultrasonic corrosion mapping.
Market Restraints
- Semiconductor supply concentration:High-speed ADC chips for ultrasonic sampling above 100 MHz rely on TSMC and Samsung foundry capacity, creating procurement bottlenecks for hardware-software bundles.
- Radiographic source cybersecurity:Industrial radiography software must integrate with NRC-licensed source control systems, adding compliance layers that delay cloud migration timelines.
- Specialized technician scarcity:ISO 9712 Level III certification requirements for data interpretation create talent bottlenecks in North American and European inspection service providers.
Strategic Opportunities
- India industrial corridor expansion:BIS certification requirements for pressure vessels and the PLI scheme for manufacturing are creating first-mover openings for integrated NDT data management platforms.
- Digital twin convergence:Pairing real-time ultrasonic thickness data with physics-based degradation models enables predictive maintenance subscriptions for offshore wind foundations.
- Remote inspection channels:Satellite-linked phased array systems allow centralized analysis of pipeline girth welds in remote Canadian oil sands and Australian mining operations.
Industry Challenges
- Legacy DICONDE interoperability:Decades of proprietary image formats in radiographic archives complicate migration to unified cloud repositories without data loss.
- Multi-modal certification timelines:Software vendors must validate algorithms separately for ultrasonic, electromagnetic, and visual testing modalities under ASTM E317 and ISO 18563, extending release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Destructive Testing (NDT) Software Market |
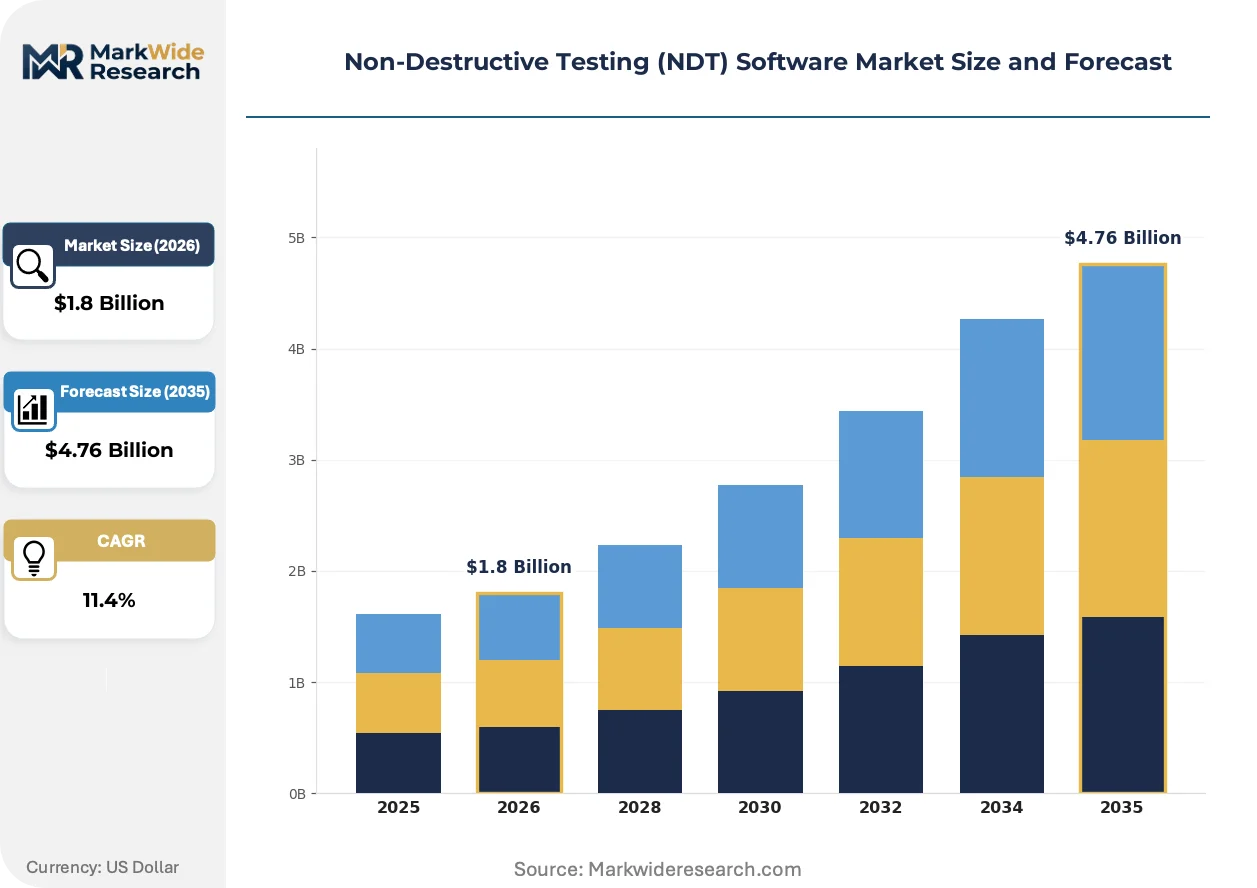
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Testing, Radiographic Testing, Magnetic Particle Testing, Liquid Penetrant Testing Technology: Digital Imaging, Automated Systems, Software as a Service, Cloud-Based Solutions End User: Aerospace, Oil & Gas, Manufacturing, Automotive Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Mistras Group Inc., General Electric, Zetec Inc., Yxlon International GmbH, Nikon Metrology Inc., Eddyfi Technologies Inc., Olympus Corporation, Ashtead Technology Inc., Baker Hughes Co. (Waygate Technologies), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Destructive Testing (NDT) Software Market Evolving Landscape
Artificial intelligence inference at the inspection edge is compressing false call rates and enabling real-time accept-reject decisions without human-in-the-loop validation.
Deep learning defect classification is overtaking rule-based thresholding in ultrasonic and radiographic analysis. Aerospace tier-1 suppliers in Toulouse and Hamburg are deploying GPU-accelerated edge devices for composite delamination detection. This compression of analysis latency is enabling 100% inspection coverage on high-volume production lines previously limited to statistical sampling.
EU AI Act risk classification requirements are reshaping algorithm validation protocols for safety-critical NDT applications. High-risk inspection systems must demonstrate explainability and bias mitigation before CE marking approval. German TÜV and French notified bodies are developing sector-specific conformity assessment routes for AI-enhanced flaw detection software.
Asset operators are consolidating vendor relationships around full-stack inspection platforms rather than point solutions. Oil majors in the North Sea and Gulf of Mexico now require unified data lakes spanning ultrasonic, eddy current, and visual testing modalities. This preference compression favors vendors with multi-modal software architectures over specialized single-technique providers.
Non-Destructive Testing (NDT) Software Market Segmentation
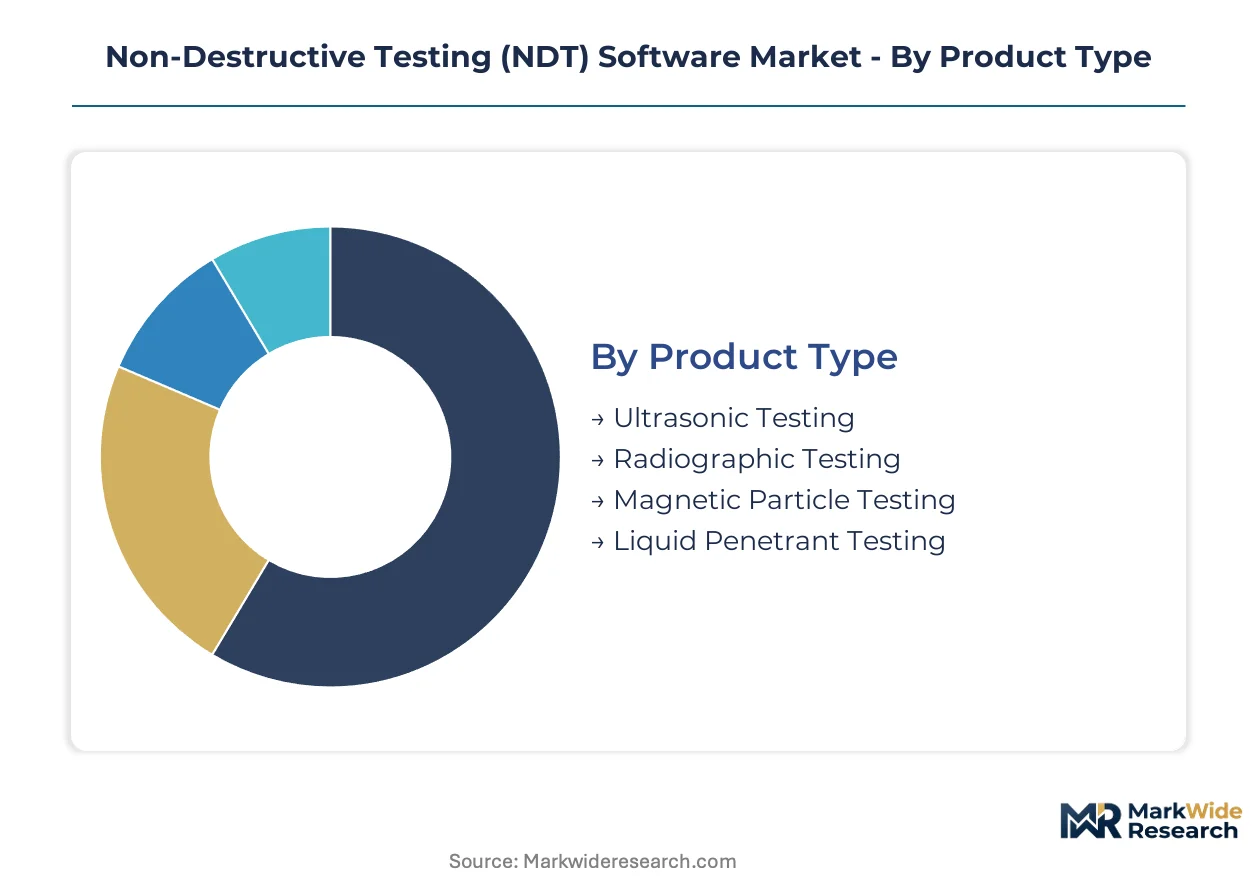
NDT software procurement splits sharply between compliance-driven sectors requiring ASME Section V traceability and operational-efficiency buyers seeking cloud analytics. Certification burden intensity varies dramatically across testing modalities and deployment architectures, reshaping vendor R&D allocation and pricing power.
Product Type:
ASME Section V mandates ultrasonic and radiographic data archiving with full traceability, while magnetic particle and penetrant testing face lighter documentation requirements under ASTM E1444 and E165.
- Ultrasonic Testing:Phased array and time-of-flight diffraction software dominate pressure vessel and pipeline inspections. German automotive clusters and Gulf of Mexico offshore operators drive procurement for corrosion mapping and weld verification workflows.
- Radiographic Testing:Digital radiography reconstruction algorithms reduce false call rates in aerospace casting inspections. FAA airworthiness directives and EPA leak detection protocols mandate source control integration, delaying cloud migration for this segment.
- Magnetic Particle Testing:Portable field units with embedded software serve railway and heavy equipment maintenance depots.
- Liquid Penetrant Testing:Simplified data capture tools address surface crack detection in foundry and forging operations with minimal regulatory overhead.
Leading the category by volume: Ultrasonic Testing. Growing fastest: Radiographic Testing as digital detector arrays displace film archives.
Technology:
Cost tier stratification separates capital-intensive automated systems from subscription SaaS models, with digital imaging commanding premium pricing through proprietary reconstruction IP.
- Digital Imaging:Proprietary tomographic reconstruction and computed radiography algorithms sustain margin concentration. Aerospace tier-1 suppliers in Toulouse and Hamburg deploy GPU-accelerated edge devices for composite laminate analysis.
- Cloud-Based Solutions:Centralized data lakes enable distributed inspection teams across remote Canadian oil sands and Australian mining corridors. Subscription economics compress deployment cycles versus perpetual license models.
- Automated Systems:Robotic scanner integration with real-time analysis commands six-figure price points in nuclear and aerospace qualification labs.
- Software as a Service:Browser-based platforms lower entry barriers for mid-tier inspection service providers in India's industrial corridor.
Margin concentration peaks in Digital Imaging. Steepest expansion trajectory: Cloud-Based Solutions as asset operators consolidate vendor relationships around unified repositories.
End User:
Application severity dictates software sophistication, with aerospace and nuclear requiring Level III certified interpretation modules while manufacturing tolerates automated pass-fail algorithms.
- Aerospace:EASA certification requirements and FAA airworthiness directives mandate documented traceability for composite airframe inspections. Airbus and Boeing tier-1 suppliers in Germany and France require specialized eddy current and phased array workflows for carbon fiber laminates.
- Oil & Gas:EPA leak detection protocols and PHMSA integrity management rules drive ultrasonic corrosion mapping subscriptions for midstream pipeline operators.
- Manufacturing:Automotive and industrial equipment producers prioritize throughput optimization over regulatory archiving.
- Automotive:German OEMs integrate NDT data management with production line PLM systems for powertrain component validation.
Revenue concentration centers on Aerospace. Fastest-climbing demand: Oil & Gas as methane emission regulations tighten monitoring requirements.
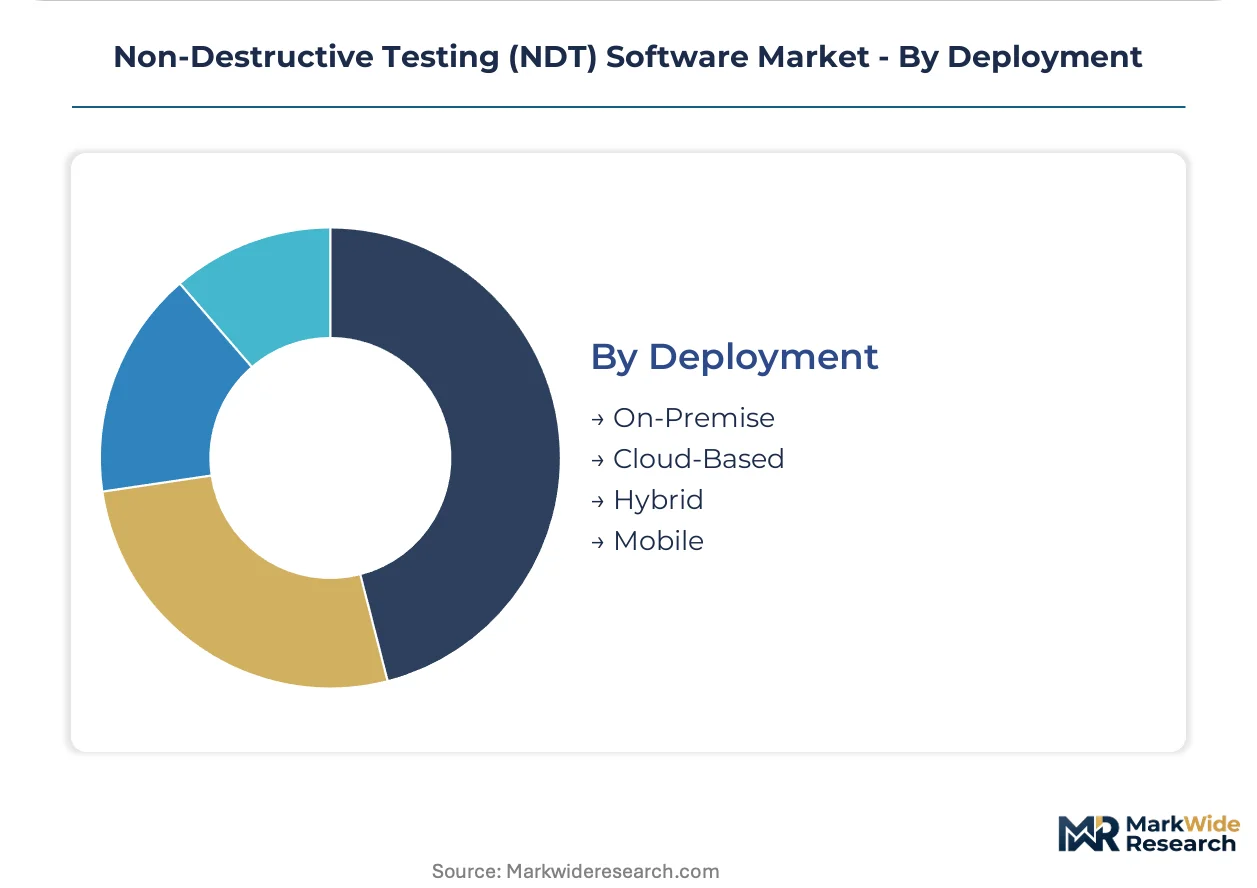
Deployment:
Customer type and security sensitivity split procurement between air-gapped on-premise installations for radiographic source control and mobile field units for remote infrastructure inspection.
- On-Premise:NRC-licensed radiography operations and nuclear qualification labs require localized data sovereignty. Hardware-software bundles with high-speed ADC sampling above 100 MHz face semiconductor supply constraints from TSMC and Samsung foundry capacity.
- Hybrid:Edge preprocessing with cloud archival balances latency requirements against centralized analytics for North Sea offshore wind foundations.
- Cloud-Based:Distributed inspection teams in remote Australian mining and Canadian oil sands operations demand satellite-linked data synchronization.
- Mobile:Tablet-based field data capture serves pipeline maintenance crews and wind turbine blade inspection services with intermittent connectivity.
Volume leadership: On-Premise in regulated sectors. Gaining share fastest: Hybrid architectures as asset operators navigate cybersecurity hardening timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor from Stuttgart to Hamburg anchors procurement intensity for integrated NDT data management platforms. Automotive and energy clusters in this region require compliance-grade software for composite inspection workflows and pressure vessel certification.
United States
Gulf of Mexico offshore operators and aerospace manufacturers in Seattle and Wichita drive ultrasonic corrosion mapping and phased array software procurement. FAA airworthiness directives and EPA leak detection protocols mandate documented traceability for safety-critical inspections. Houston's energy corridor concentrates demand for pipeline integrity management subscriptions.
Germany
Automotive OEMs in Munich and Stuttgart integrate NDT data management with production line PLM systems for powertrain validation. EASA certification requirements and EU Pressure Equipment Directive frameworks enforce algorithm validation for AI-enhanced flaw detection. Hamburg's aerospace tier-1 suppliers deploy specialized eddy current workflows for carbon fiber laminate inspection.
China
Pressure vessel manufacturers in Shanghai and Shenzhen expand automated capture platform procurement under GB standards and MIIT industrial digitization directives. The Yangtze River Delta concentrates demand for multi-modal inspection software serving nuclear and petrochemical infrastructure. Dual carbon goals accelerate predictive maintenance subscriptions for offshore wind foundations.
India
BIS certification requirements for pressure vessels and the PLI scheme for manufacturing create first-mover openings in Maharashtra and Gujarat. Automotive clusters in Pune and Chennai require browser-based platforms for mid-tier inspection service providers. The Delhi-Mumbai Industrial Corridor drives centralized data lake adoption for distributed asset monitoring.
France
Airbus tier-1 suppliers in Toulouse deploy GPU-accelerated edge devices for composite delamination detection. EU AI Act risk classification requirements reshape algorithm validation protocols for safety-critical applications. French notified bodies develop sector-specific conformity assessment routes alongside German TÜV counterparts.
Non-Destructive Testing (NDT) Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade software tiers, with proprietary reconstruction algorithms commanding pricing power over standardized inspection modules. The vendor base stratifies between full-stack platform providers and specialized single-technique developers. Three archetypes dominate: industrial conglomerates leveraging digital heritage, pure-play inspection specialists, and diversified testing service providers. Consolidation pressure favors multi-modal architectures, while M&A activity targets complementary algorithm portfolios and regional service networks.
Within the industrial conglomerate tier, General Electric and Baker Hughes Co. (Waygate Technologies) occupy positions anchored by heritage platform reach and predictive maintenance integration capabilities. Eddyfi Technologies Inc. exemplifies the specialized archetype, with its incorporation name signaling advanced electromagnetic inspection focus. These three entities represent distinct competitive vectors—digital industrial breadth, inspection data standardization, and technique-specific depth—shaping how capital allocates across the software stack.
| Leading Market Players |
|---|
| Mistras Group Inc. |
| General Electric |
| Zetec Inc. |
| Yxlon International GmbH |
| Nikon Metrology Inc. |
| Eddyfi Technologies Inc. |
| Olympus Corporation |
| Ashtead Technology Inc. |
| Baker Hughes Co. (Waygate Technologies) |
| Others |
Value Network & Pricing Analysis
Certification-grade software tiers diverge sharply from commodity inspection modules, with ASME Section V traceability requirements in the United States and EU Pressure Equipment Directive mandates in Germany anchoring premium pricing while browser-based SaaS platforms for India's mid-tier providers compete on deployment speed. This bifurcation concentrates margin capture among vendors with validated algorithm portfolios while forcing hardware-software bundle suppliers to navigate semiconductor foundry constraints.
Pricing Analysis
Value-based pricing anchors on inspection throughput and defect detection yield, with automated systems commanding six-figure price points in nuclear qualification labs while subscription SaaS models compress deployment cycles for distributed teams. Price differentiation rests on ISO 9712 certification tier and proprietary reconstruction IP, with aerospace tier-1 suppliers in Toulouse and Hamburg least sensitive to cost. Cost compression in commodity inspection tools is intensifying because cloud-native entrants are undercutting perpetual license models.
Supply Chain Analysis
ISO 9712 Level III certification requirements gate software validation timelines, with algorithm development concentrated in Germany, France, and the United States where notified bodies maintain accreditation authority. High-speed ADC chips for ultrasonic sampling above 100 MHz draw from TSMC and Samsung foundry capacity, creating single-source vulnerability for hardware-software bundles. Distribution runs through direct vendor relationships with asset operators consolidating around full-stack platforms rather than point solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NDT software market is becoming a vertical-integration race, with predictive maintenance subscription models and captive algorithm development emerging as the decisive downstream and upstream levers respectively.
For Market Incumbents: Cement multi-modal software architectures by acquiring specialized electromagnetic or eddy current algorithm portfolios before cloud-native entrants capture India's industrial corridor. Lock in ASME Section V validation partnerships with Houston's energy corridor operators to defend against SaaS challengers eroding perpetual license renewals. For New Entrants and Emerging Players: Enter via browser-based platforms targeting Maharashtra and Gujarat's mid-tier inspection service providers under BIS certification requirements, where incumbent hardware bundles face semiconductor procurement bottlenecks. Anchor go-to-market on PLI scheme manufacturing incentives and centralized data lake adoption across the Delhi-Mumbai Industrial Corridor. For Investors and Strategic Acquirers: Re-rating potential sits with GPU-accelerated edge device specialists given EU AI Act risk classification requirements reshaping algorithm validation protocols for safety-critical aerospace applications. Watch for inflection when French notified bodies and German TÜV publish sector-specific conformity assessment routes triggering consolidation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Portfolio Acquisition | Captures proprietary reconstruction IP that sustains margin concentration in digital radiography segments. |
| Cloud-Native Platform Launch | Compresses deployment cycles for distributed inspection teams in remote Canadian oil sands operations. |
| Notified Body Partnership | Accelerates CE marking approval under EU AI Act risk classification for AI-enhanced flaw detection. |
| Edge Device Manufacturing Scale-Up | Addresses GPU-accelerated composite delamination detection demand from Airbus tier-1 suppliers in Hamburg. |
| Predictive Maintenance Subscription | Pairs real-time ultrasonic thickness data with physics-based degradation models for offshore wind foundations. |
Research Methodology
ASME regulatory filings, EASA certification databases, and EPA leak detection protocol documentation formed the secondary backbone, cross-referenced with primary interviews involving NDT software product managers, Level III certified inspection technicians, aerospace quality assurance directors, and pipeline integrity management officers. Bottom-up triangulation of vendor licensing data and top-down validation against industrial digitization expenditure trends anchored market sizing.
Bottom-up segmentation modeling across product type, deployment architecture, and end-use severity combined with top-down macro-industrial indicators across the analysis window. CAGRs derived from weighted regression of procurement cycle data, cloud migration timelines, and certification requirement phase-ins. Modeled inputs included semiconductor foundry capacity constraints for high-speed ADC chips and satellite bandwidth availability for remote inspection channels.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in TSMC foundry allocation or NRC radiographic source control cybersecurity mandates. A model refresh is warranted upon material change in EU AI Act implementation timelines or BIS certification requirement rollouts in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
PXI Source Measure Unit Market
Test and Measurement
Test and Measurement Market
Test and Measurement
Global Non-Destructive Testing and Inspection Market
Test and Measurement
Field Inspection Tester Market
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
Gloss Meters Market
Test and Measurement
Leak Testing Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Crock Meter Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Fluorometers Market
Test and Measurement
E-Beam Wafer Inspection System Market