
 Methylamines Market | 2026-2036
Methylamines Market Size, Share, and Industry Trends Forecast 2026-2036
Methylamines Market Outlook
The Methylamines Market is restructuring around a widening split between pharmaceutical-grade specifications and commodity agricultural grades. Balaji Amines dominates Indian supply chains with backward integration into methanol and ammonia feedstocks. Eastman Chemical Company sustains North American leadership through captive production of dimethylamine for downstream surfactant applications.
Methylamines are aliphatic amines produced by catalytic reaction of methanol with ammonia under elevated temperature and pressure, yielding mono-, di-, and trimethylamine in ratios controlled by reactant stoichiometry and reactor design. These intermediates serve primarily as building blocks for pesticides, solvents, pharmaceuticals, and rubber accelerators. Dimethylamine leads product type demand due to its versatility in N,N-dimethylformamide and surfactant production, while trimethylamine exhibits the fastest growth trajectory driven by choline chloride applications in animal feed. Pharmaceutical end users command premium pricing through stringent impurity profiling, whereas agricultural buyers prioritize volume procurement of standard-grade methylamine for pesticide synthesis.
EPA oversight governs air emissions and workplace exposure limits for methylamine production facilities in the United States, while REACH registration mandates comprehensive toxicological dossiers for European market access. China's MEE enforces wastewater discharge standards that constrain small-scale producers and favor integrated manufacturing complexes. Stakeholders must weigh feedstock cost volatility against regulatory compliance investments when evaluating capacity expansion timelines.
Market Dynamics
Pharmaceutical-grade methylamine specifications are diverging sharply from agricultural commodity grades, creating parallel supply chains with incompatible purity thresholds and pricing architectures.
Growth Catalysts
- REACH Phase-in Substances:ECHA registration deadlines for methylamine derivatives are accelerating facility upgrades across European production sites, pulling demand toward compliant suppliers.
- Choline chloride feed additive:Animal nutrition formulators in China are expanding trimethylamine offtake for choline chloride synthesis, creating dedicated demand streams separate from agrochemical applications.
- Catalytic methanol-ammonia optimization:Advanced reactor designs with real-time stoichiometric control are improving yield ratios toward higher-value dimethylamine output.
Market Restraints
- Methanol feedstock volatility:Natural gas pricing fluctuations directly compress methylamine producer margins, particularly for non-integrated facilities lacking captive methanol supply.
- Jiangsu-Zhejiang production cluster concentration:Over half of Chinese methylamine capacity sits within flood-prone coastal zones, exposing supply chains to concentrated weather and logistics disruption risk.
- Dimethylformamide substitution pressure:N-methyl-2-pyrrolidone and ionic liquids are displacing DMF in select pharmaceutical solvent applications, threatening downstream dimethylamine demand.
Strategic Opportunities
- India PLI scheme for APIs:Production-linked incentives for active pharmaceutical ingredient manufacturing are attracting methylamine investments toward pharmaceutical-grade capacity expansion.
- Continuous flow reactor adoption:Modular flow chemistry systems are enabling smaller-scale, distributed methylamine production with reduced capital intensity and faster regulatory qualification.
- Carbon border adjustment mechanism:EU CBAM implementation is creating premium positioning for low-carbon intensity methylamine produced via biomass-derived methanol or green ammonia routes.
Industry Challenges
- Process safety engineering talent:Experienced specialists in high-pressure catalytic amination are scarce, constraining capacity expansion timelines and operational risk management.
- Multi-jurisdiction dossier compilation:REACH, EPA TSCA, and China MEE registration requirements demand divergent toxicological data packages, fragmenting compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methylamines Market |
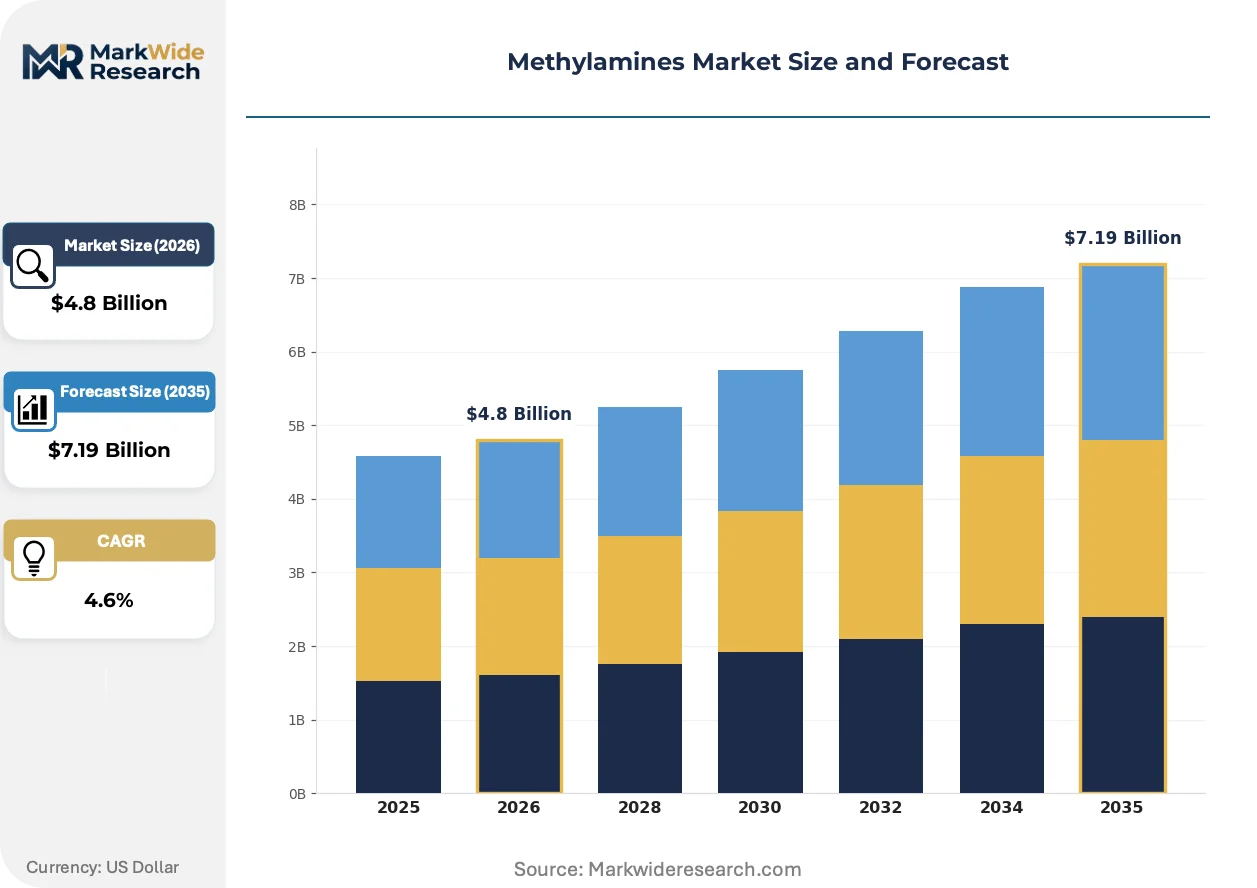
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methylamine, Dimethylamine, Trimethylamine, Methylamine Hydrochloride Application: Pesticides, Pharmaceuticals, Surfactants, Rubber Processing End User: Agriculture, Chemical Industry, Pharmaceutical Companies, Cosmetics Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Balaji Amines, Celanese, Eastman Chemical Company, Huntsman, INEOS, BASF SE, Chemours, DOW, Mitsubishi Gas Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methylamines Market Strategic Shifts
Digital process control and modular reactor architectures are compressing the traditional scale economics of methylamine production, enabling viable smaller-batch pharmaceutical-grade supply.
Membrane separation technology is expanding into methylamine product purification, replacing energy-intensive distillation sequences with selective permeation systems. Pharmaceutical manufacturers are adopting membrane-polished grades for high-sensitivity API synthesis, where residual ammonia and water specifications must reach parts-per-million thresholds. This shift is expanding into specialty surfactant and electronic chemical applications previously served by standard distillation grades.
EPA Risk Management Plan amendments are tightening accidental release prevention requirements for anhydrous methylamine storage and handling facilities. Producers must implement enhanced detection systems and emergency response protocols, elevating operational costs for smaller facilities below threshold scale economies. Agricultural methylamine distributors in the US Midwest are consolidating storage assets to share compliance infrastructure.
Specification-driven procurement is fragmenting traditional volume-contract structures. Pharmaceutical buyers are unbundling methylamine supply from integrated chemical distributors, establishing direct relationships with producers capable of batch-level impurity certification. This pattern is most visible in Basel and New Jersey pharmaceutical clusters, where sponsor-audited manufacturing sites now qualify suppliers through dedicated quality agreements rather than standard commercial terms.
Methylamines Market Segmentation
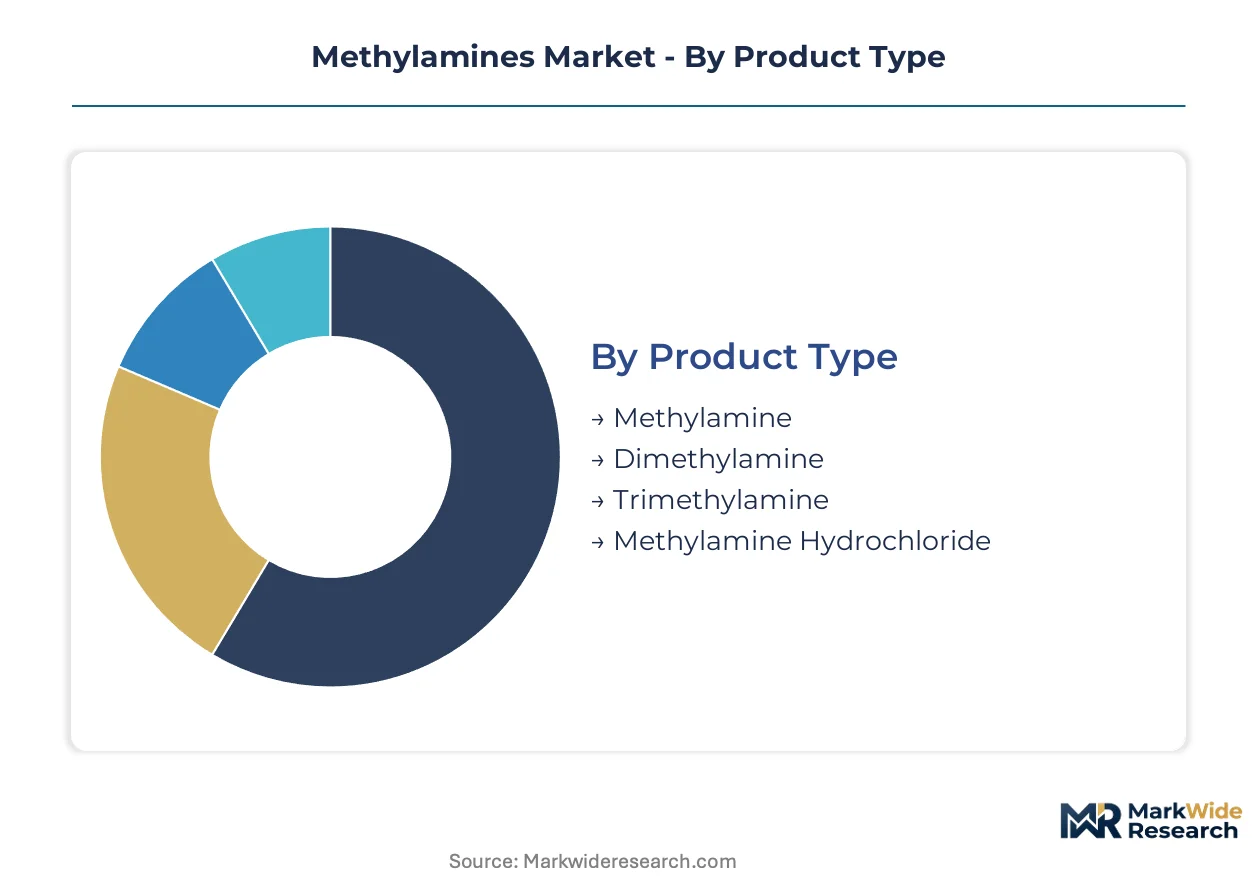
Methylamine segmentation reflects divergent capital requirements across pharmaceutical-grade and commodity production. Equipment specifications, purity thresholds, and regulatory compliance investments vary sharply by segment, reshaping competitive positioning.
Product Type:
Capital intensity peaks at continuous catalytic reactor systems for anhydrous grades, while batch crystallization units for salt derivatives demand lower upfront outlays.
- Dimethylamine:Produced through optimized methanol-ammonia stoichiometry yielding the highest-value intermediate for N,N-dimethylformamide and surfactant synthesis. BASF and Eastman Chemical sustain captive demand in Germany and the United States, though DMF substitution pressure from N-methyl-2-pyrrolidone constrains expansion timelines.
- Trimethylamine:The tertiary amine structure enables choline chloride production for animal feed applications, with Chinese formulators in Jiangsu and Zhejiang provinces absorbing dedicated supply streams separate from agrochemical channels.
- Methylamine:Primary amine serving pesticide and solvent intermediates with lower margin capture than downstream derivatives.
- Methylamine Hydrochloride:Salt form crystallized for pharmaceutical API synthesis requiring controlled humidity handling and batch-level certification.
Dimethylamine absorbs the bulk of installed capacity; trimethylamine is expanding most quickly.
Application:
Application mix determines regulatory exposure, with pharmaceutical and agrochemical end-uses facing divergent compliance architectures.
- Pesticides:Standard-grade methylamine consumption concentrates in glyphosate and organophosphate synthesis, with Chinese agrochemical clusters prioritizing volume procurement over impurity profiling.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturers impose batch-level impurity certification reaching parts-per-million thresholds for residual ammonia and water, unbundling supply from integrated distributors in Basel and New Jersey clusters.
- Surfactants:Dimethylamine-derived amphoteric and cationic surfactants serve personal care and industrial cleaning formulations.
- Rubber Processing:Vulcanization accelerators and antioxidants consume specialty amine grades with moderate purity requirements.
Pesticide applications anchor volume demand; pharmaceutical applications command the steepest price premiums.
End User:
Customer type shapes procurement modality, with agricultural buyers favoring long-term volume contracts and pharmaceutical sponsors requiring audited quality agreements.
- Pharmaceutical Companies:Sponsor-audited manufacturing sites qualify suppliers through dedicated quality agreements rather than standard commercial terms, fragmenting traditional distributor relationships.
- Agriculture:Agrochemical formulators in China and India prioritize backward integration into methanol feedstocks to defend margin position against natural gas volatility.
- Chemical Industry:Intermediate processors serving solvents, coatings, and specialty chemicals absorb standard distillation grades.
- Cosmetics:Personal care formulators demand membrane-polished grades for surfactant applications with emerging electronic chemical crossover.
Agricultural end users absorb the bulk of installed capacity; pharmaceutical companies are expanding specification requirements fastest.
Distribution Channel:
Channel selection reflects batch size and certification complexity, with pharmaceutical-grade supply bypassing traditional distributor networks.
- Direct Sales:Pharmaceutical manufacturers establish direct producer relationships for batch-level impurity certification, particularly visible in European and North American pharmaceutical clusters.
- Distributors:Agricultural and industrial chemical distributors consolidate storage assets to share EPA Risk Management Plan compliance infrastructure across the US Midwest.
- Online Sales:Digital procurement platforms serve small-batch research and specialty chemical customers with reduced qualification overhead.
- Retail:Limited to consumer-facing methylamine derivative products in select regional markets.
Distributor channels absorb the bulk of installed capacity; direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor methylamine production capacity, absorbing agrochemical and pharmaceutical feedstock demand across the Yangtze River Delta manufacturing corridor. EPA, REACH, and China's MEE regulations fragment compliance architectures across major supply regions.
China
Agrochemical formulators in Jiangsu and Zhejiang provinces drive trimethylamine consumption for choline chloride synthesis. MEE wastewater discharge standards constrain small-scale producers and favor integrated manufacturing complexes. Nantong and Taizang chemical parks concentrate capacity expansion toward pharmaceutical-grade specifications.
United States
Dimethylamine demand for surfactant and solvent applications sustains Gulf Coast production assets. EPA Risk Management Plan amendments tighten accidental release prevention requirements for anhydrous methylamine storage. Texas and Louisiana petrochemical corridors maintain backward integration into methanol feedstocks through natural gas-based supply chains.
Germany
BASF's Ludwigshafen complex anchors European captive consumption for N,N-dimethylformamide and specialty chemical derivatives. ECHA REACH registration mandates comprehensive toxicological dossiers for methylamine derivative market access. The Rhine-Neckar industrial region maintains specification leadership for pharmaceutical-grade amine supply.
India
Production-linked incentives for active pharmaceutical ingredient manufacturing attract methylamine investments toward pharmaceutical-grade capacity expansion. CDSCO and BIS purity standards tighten import substitution requirements for domestic amine supply. Maharashtra and Gujarat chemical clusters absorb backward integration into methanol and ammonia feedstocks.
Japan
Mitsubishi Gas Chemical's integrated operations serve domestic demand for electronic chemical and specialty solvent applications. METI chemical management regulations enforce strict handling protocols for high-pressure catalytic amination facilities. The Chubu industrial region around Nagoya maintains process safety engineering expertise for precision-grade production.
Methylamines Market Competitive Environment
Premium-margin players sit above commodity-margin players across purity certification and regulatory compliance capabilities. The methylamine market structures around three tiers: integrated petrochemical majors with captive methanol supply, regional specialists with backward integration into ammonia feedstocks, and toll manufacturers serving spot pharmaceutical demand. Strategic archetypes include specification leaders commanding batch-level impurity certification, scale players optimizing dimethylamine yield ratios, and integrated complexes defending margin position against natural gas volatility. Dominant competitive moves encompass capacity expansion toward pharmaceutical-grade assets and strategic partnerships for regulatory dossier compilation across REACH, EPA TSCA, and China MEE jurisdictions.
Within the integrated petrochemical tier, BASF SE and Eastman Chemical Company exemplify specification leadership through captive downstream demand for solvent and surfactant derivatives. Balaji Amines anchors the regional specialist archetype with Indian production base and backward integration into methanol and ammonia feedstocks. These three entities occupy positions spanning premium pharmaceutical-grade supply and volume agricultural commodity production, reflecting the market's bifurcated purity architecture.
| Leading Market Players |
|---|
| Balaji Amines |
| Celanese |
| Eastman Chemical Company |
| Huntsman |
| INEOS |
| BASF SE |
| Chemours |
| DOW |
| Mitsubishi Gas Chemical Company |
| Others |
Value Chain & Pricing Dynamics
Continuous flow reactor adoption simultaneously compresses capital intensity for pharmaceutical-grade batches and fragments supply concentration away from coastal Chinese mega-complexes. This technology shift enables smaller producers in India and Germany to capture premium pricing through faster regulatory qualification, while integrated majors defend margin position via methanol-ammonia backward integration.
Pricing Analysis
Batch-level impurity certification anchors value-based pricing for pharmaceutical-grade methylamine, with residual ammonia and water thresholds reaching parts-per-million specifications commanding three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on REACH dossier completeness and EPA Risk Management Plan compliance status. Cost compression in agricultural commodity grades is intensifying because Chinese agrochemical clusters prioritize volume procurement over certification investment. Agricultural buyers exhibit highest price sensitivity; pharmaceutical sponsors accept premium positioning for audited quality agreements.
Supply Chain Analysis
Methanol feedstock supply rests on integrated petrochemical complexes in the United States, China, and Germany, with natural gas pricing volatility transmitting directly to non-captive producers. Ammonia sourcing and catalytic reactor equipment feed from regional chemical engineering clusters. Single-source vulnerability concentrates in Jiangsu-Zhejiang coastal zones exposed to flood disruption. Distribution runs through direct sales channels for pharmaceutical-grade batches and consolidated distributor networks for agricultural volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The methylamine market functions as a cost-of-compliance story where ECHA REACH registration deadlines erect barrier-to-entry moats favoring dossier-complete incumbents over capital-only challengers.
For Market Incumbents: Deploy membrane separation technology upgrades to capture pharmaceutical-grade premium positioning as N-methyl-2-pyrrolidone substitution pressure threatens dimethylamine solvent demand. Consolidate storage assets across the US Midwest to share EPA Risk Management Plan compliance infrastructure. Capacity expansion in Nantong and Taizang chemical parks defends against Indian PLI-scheme challengers. For New Entrants and Emerging Players: Digital procurement platforms enable small-batch research chemical entry with reduced qualification overhead, bypassing integrated distributor relationships. Target pharmaceutical clusters in Basel and New Jersey with sponsor-audited manufacturing sites requiring batch-level impurity certification. Continuous flow reactor adoption lowers capital barriers for modular, distributed production. For Investors and Strategic Acquirers: Re-rating potential sits with specification leaders possessing REACH-compliant dossiers and pharmaceutical-grade membrane-polished capacity given EU CBAM implementation creating low-carbon intensity premium positioning. Acquisition focus: regional specialists with backward integration into methanol-ammonia feedstocks. Signal to watch: India PLI scheme API manufacturing incentive disbursement rates as capacity migration indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Capacity Expansion | Nantong and Taizang chemical parks attract investment toward batch-level impurity certification capabilities. |
| Backward Integration into Methanol Feedstocks | Balaji Amines and Gulf Coast producers defend margin position against natural gas price volatility. |
| Membrane Separation Technology Adoption | Pharmaceutical manufacturers adopt membrane-polished grades for parts-per-million threshold synthesis. |
| REACH Dossier Compilation Partnerships | Multi-jurisdiction registration requirements fragment compliance resources across European production sites. |
| Continuous Flow Reactor Deployment | Modular systems enable smaller-scale distributed production with faster regulatory qualification timelines. |
Study Parameters
Multi-period observation of capacity expansion announcements, regulatory filing timelines, and feedstock price movements anchored the trend analysis, supplemented by interviews with plant managers at catalytic amination facilities, procurement leads at agrochemical formulators, technical R&D directors in pharmaceutical API manufacturing, and distribution channel partners serving the US Midwest. Secondary validation drew from ECHA registration databases, EPA Risk Management Plan filings, China MEE wastewater discharge records, and SEC 10-K disclosures from integrated petrochemical majors. Bottom-up project-level capacity tracking and top-down end-use demand modeling enabled triangulation.
Segment-weighting applied grade tier differentiation between pharmaceutical and agricultural specifications, end-use industry exposure across pesticides and surfactants, and regional production hub concentration in Jiangsu-Zhejiang versus Gulf Coast corridors. CAGRs were derived through regression analysis of historical capacity utilization and forward projection of regulatory-driven facility upgrade cycles. Industry-specific inputs included methanol-ammonia stoichiometry yield ratios and choline chloride feed additive demand trajectories.
The model holds under stable natural gas pricing and consistent REACH enforcement intensity; deviation in methanol feedstock volatility or ECHA registration deadline extensions would shift capacity expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Wood Preservation Chemicals Market
Chemicals
Europe Fluorosilicic Acid Market
Chemicals
North America Methanol Market
Chemicals
Global Lactate Salts Market
Chemicals
De-Icing Agents Market
Chemicals
Guanidine Carbonate Market
Chemicals
Hexachloroethane Market
Chemicals
RDX and HMX Market
Chemicals
Laboratory Chemicals Market
Chemicals
China Methanol Market
Chemicals
North America Construction Chemicals Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Malic Acid Market
Chemicals
Decabromodiphenyl Ether Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Neopentyl Polyhydric Alcohol Market