
 North America Construction Chemicals Market | 2026-2036
North America Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Construction Chemicals Market Analytics
The capital-intensity divergence between integrated resin producers and formulation specialists is bifurcating competitive dynamics in the North America construction chemicals sector. Sika AG leverages its captive polymer technology to command premium positioning in high-performance waterproofing membranes. BASF SE anchors its regional presence through backward integration into acrylic and polyurethane intermediates, insulating margins from feedstock volatility. RPM International Inc. competes through a decentralized brand portfolio that lets it navigate local specification requirements across multiple states.
Construction chemicals encompass admixtures, sealants, coatings, and adhesives formulated with Portland cement, synthetic latex, or epoxy resin matrices to modify concrete rheology, protect substrates, or bond dissimilar materials. These formulations typically incorporate active solids concentrations between 30% and 60% by weight, with performance governed by ASTM C494 for chemical admixtures and ASTM C881 for epoxy bonding agents. Admixtures occupy the largest value pool due to their non-discretionary specification in commercial concrete production, while waterproofing coatings represent the fastest-expanding segment as building envelope codes tighten across humid subtropical zones. The residential end-user channel remains structurally fragmented, with margin accretion concentrating in infrastructure applications where performance-based specifications limit price competition.
The EPA enforces VOC emission limits under 40 CFR Part 59 that directly constrain solvent-borne coating formulations across the United States, while OSHA's hazard communication standards govern workplace exposure limits during application. Health Canada's PMPA regulates antimicrobial additives in Canadian construction products, creating a dual-compliance burden for cross-border suppliers. Stakeholders must monitor pending state-level embodied carbon disclosure rules in California and New York, as these threaten to reshape material selection criteria before federal harmonization emerges.
Market Dynamics
EPA's tightening VOC standards under 40 CFR Part 59 are compressing solvent-borne coating margins while redirecting R&D budgets toward waterborne polymer architectures across the United States and Canada.
Growth Catalysts
- Infrastructure Rehabilitation Mandates:Aging bridge decks and highway segments across the United States require concrete repair admixtures at scale, creating non-discretionary demand pools for epoxy bonding agents and corrosion inhibitors.
- California's Embodied Carbon Disclosure Rules:Pending state-level mandates in California and New York are forcing material specification changes toward lower-carbon cementitious systems before federal harmonization emerges.
- Polymer Technology Maturation:Synthetic latex and polyurethane intermediate production is consolidating around backward-integrated producers, improving formulation consistency for high-performance waterproofing membranes.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic and epoxy resin input costs fluctuate with crude oil derivatives, compressing margin visibility for formulation specialists lacking captive polymer supply.
- Cross-Border Compliance Burden:Health Canada's PMRA antimicrobial additive regulations create dual-certification requirements for suppliers operating across the United States-Canada corridor.
- Specification Lock-In:Performance-based infrastructure contracts limit substitution flexibility, freezing out innovative admixture formulations that lack decades of field verification data.
Strategic Opportunities
- Texas Megaproject Concentration:Commercial and institutional construction pipelines in Texas are drawing disproportionate chemical volumes, creating regional distribution hub opportunities for admixture suppliers.
- Waterborne Coating Transition:EPA VOC enforcement is accelerating demand for low-emission architectural coatings, rewarding early movers with qualified product portfolios.
- Building Envelope Code Tightening:Humid subtropical zones across the southeastern United States are adopting stricter moisture protection standards, expanding the addressable market for breathable waterproofing membranes.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in rheology modification and polymer-cement compatibility is concentrating at integrated producers, constraining talent pools for mid-tier specialists.
- ASTM Certification Timelines:ASTM C494 and C881 testing protocols require extended field validation periods, delaying commercialization of novel admixture chemistries by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Construction Chemicals Market |
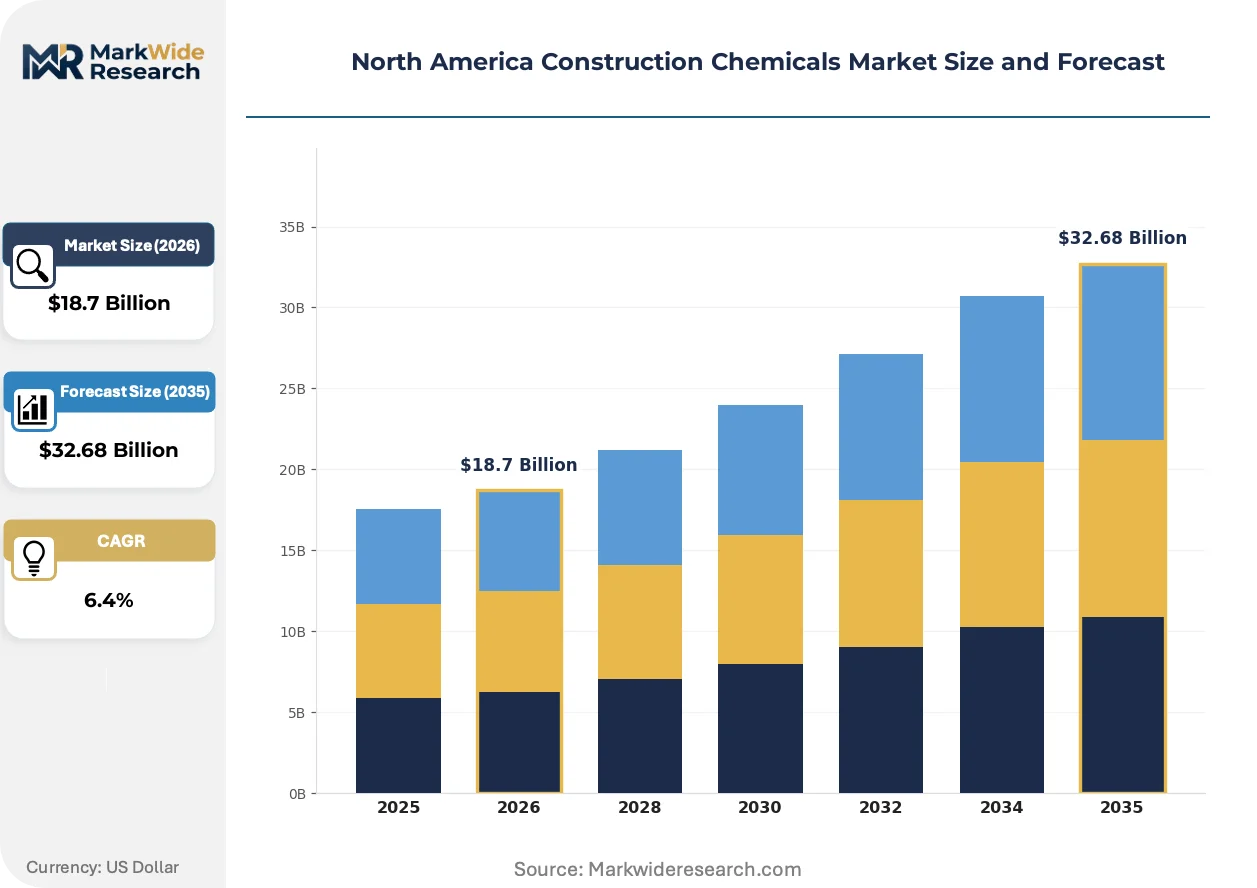
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Coatings, Adhesives End User: Residential, Commercial, Institutional, Infrastructure Application: Concrete Repair, Waterproofing, Flooring, Protective Treatments Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Sika AG, Saint-Gobain, RPM International Inc., MAPEI S.p.A., Holcim Group, BASF SE, Dow Inc, H.B. Fuller Co, Fosroc, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Construction Chemicals Market Evolving Landscape
Formulation science is pivoting toward bio-based and recycled-content polymers as procurement criteria harden around environmental performance metrics in public infrastructure bidding.
Self-healing concrete admixtures incorporating microencapsulated healing agents are displacing conventional repair mortars in critical infrastructure specifications. State transportation departments in California and Texas are piloting these systems for bridge deck applications. The technology is displacing scheduled maintenance contracts by extending service intervals and reducing lifecycle intervention frequency.
EPA enforcement of 40 CFR Part 59 is eliminating solvent-borne coating formulations from federal procurement channels. Manufacturers are reallocating production lines to waterborne acrylic and polyurethane systems. Architectural coatings for commercial buildings face the steepest compliance curve, with reformulation costs concentrated in the 2024-2026 window.
Specification authority is migrating from general contractors to asset owners and their engineering consultants. Infrastructure agencies in Texas and California now require pre-qualification of admixture suppliers against performance databases. This shift is compressing the approved vendor lists for megaprojects and privileging suppliers with captive technical service capabilities.
North America Construction Chemicals Market Segmentation
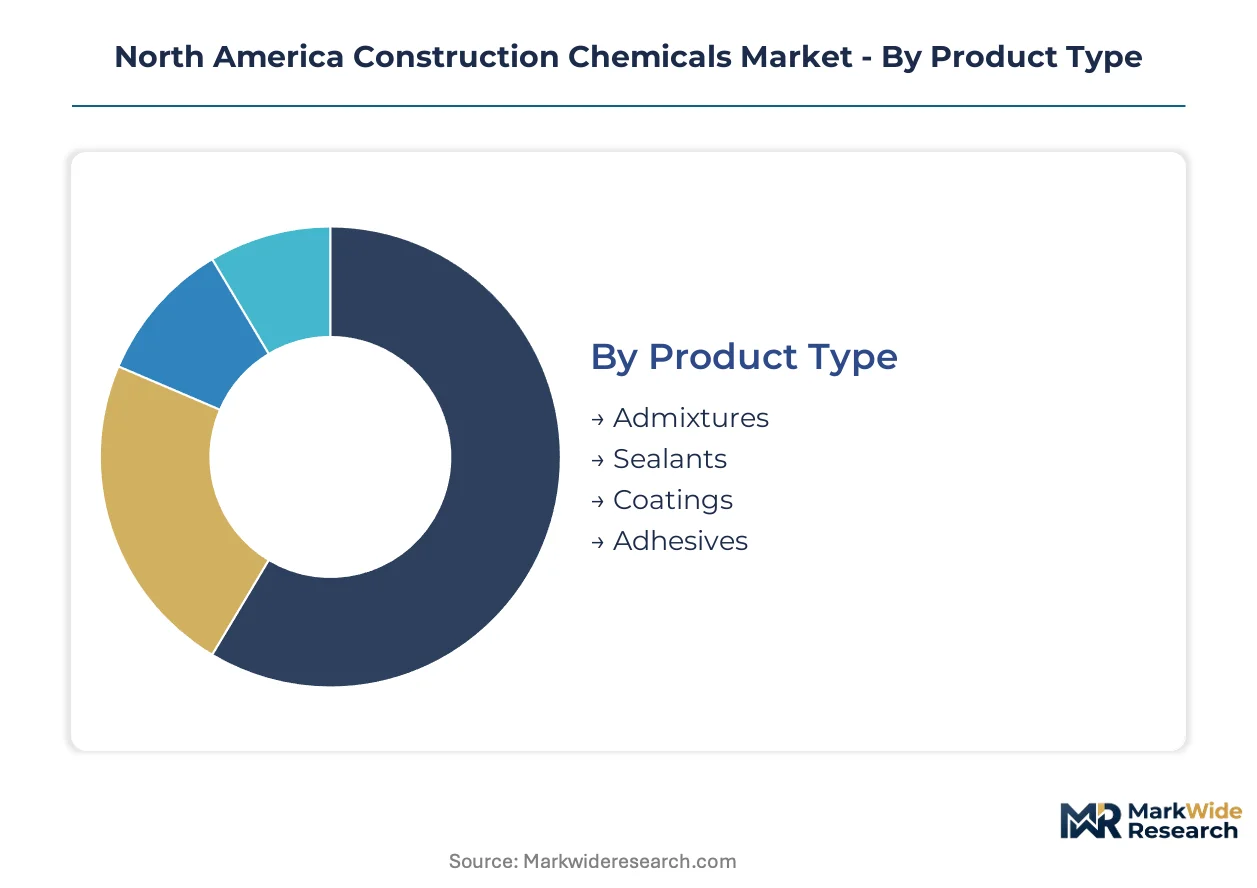
Segmentation in construction chemicals reveals how specification authority, margin capture, and channel economics diverge across product categories and end-use verticals. Understanding these fault lines helps suppliers prioritize R&D budgets and distribution investments.
Product Type:
Margin pools concentrate in formulations requiring captive polymer technology or extended ASTM certification timelines, creating defensive moats for integrated producers.
- Admixtures:These cement-modifying formulations govern concrete rheology, set time, and durability through active solids concentrations of 30-60% by weight. Demand concentrates in infrastructure rehabilitation across Texas and California, where state transportation departments mandate performance-based pre-qualification for bridge deck and highway projects. ASTM C494 compliance creates 18-36 month commercialization barriers that freeze out non-specialized competitors.
- Coatings:Architectural and protective film-forming systems face the steepest EPA VOC compliance curve under 40 CFR Part 59, forcing wholesale reformulation toward waterborne acrylic and polyurethane architectures. California's embodied carbon disclosure rules are accelerating specification shifts toward lower-emission cementitious systems in commercial building envelopes.
- Sealants:Joint-filling elastomeric compounds specified for movement accommodation and moisture exclusion in building envelopes.
- Adhesives:Bonding agents governed by ASTM C881 for structural concrete repairs and dissimilar material attachment.
The dominant share belongs to Admixtures, while Coatings is closing the gap fastest as building envelope codes tighten across humid subtropical zones.
End User:
Volume gravity shifts toward asset owners who control specification authority through performance databases and pre-qualified vendor lists.
- Infrastructure:State transportation departments and federal agencies drive non-discretionary demand for concrete repair admixtures, corrosion inhibitors, and epoxy bonding agents. Texas and California DOTs now require field verification data spanning decades, compressing approved supplier lists to integrated producers with captive technical service capabilities. Performance-based contracts limit price competition and protect margin pools.
- Commercial:Office, retail, and hospitality construction draws disproportionate chemical volumes in Texas megaproject corridors. Procurement criteria harden around environmental performance metrics, with LEED and embodied carbon disclosures reshaping material selection. Waterborne coating transitions face concentrated reformulation costs in the near-term window.
- Residential:Single-family and multifamily construction channels remain structurally fragmented, with margin compression from price-sensitive builders and distributor private-label competition.
- Institutional:Schools, hospitals, and government facilities specify high-performance waterproofing membranes under stricter moisture protection standards.
Infrastructure commands the deepest margin pools, while Commercial is gaining specification influence fastest as asset owners displace general contractors.
Application:
Technology maturation rates vary sharply, with self-healing systems displacing scheduled maintenance contracts in critical infrastructure.
- Waterproofing:Breathable membrane systems for building envelope protection face accelerating code adoption across southeastern United States humid subtropical zones. Polymer technology consolidation around backward-integrated producers improves formulation consistency for high-performance specifications. California and Texas pilot programs are validating next-generation moisture management systems.
- Concrete Repair:Microencapsulated self-healing admixtures are extending service intervals for bridge decks, displacing conventional epoxy bonding agents and repair mortars. State transportation departments in California and Texas lead pilot deployments, with lifecycle cost advantages reshaping maintenance contract structures.
- Flooring:Industrial and commercial surface systems requiring chemical resistance and load-bearing performance.
- Protective Treatments:Surface-applied barriers for substrate durability in aggressive exposure environments.
Concrete Repair retains the largest installed base, though Waterproofing is climbing the fastest as envelope codes proliferate.
Distribution Channel:
Channel economics fragment between specification-intensive direct relationships and volume-driven intermediaries.
- Distributors:Regional and national intermediaries dominate admixture and coating volumes, leveraging local specification relationships and technical service capabilities. Texas megaproject concentration creates hub economics for inventory positioning and just-in-time delivery to commercial and institutional job sites. Margin structures reflect value-added services including batching equipment and field troubleshooting.
- Direct Sales:Integrated producers deploy captive technical service teams for infrastructure pre-qualification and performance database management. Sika AG and BASF SE anchor direct channels for waterproofing membrane specifications requiring polymer customization.
- Wholesalers:Volume aggregators serving residential and light commercial contractors with standardized product lines.
- Online Retail:Emerging channel for standardized sealants and adhesives in maintenance and repair applications.
Distributors hold the deepest penetration, while Direct Sales is gaining share fastest as specification authority migrates to asset owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across the North American construction chemicals landscape. Infrastructure buyers prioritize performance verification over unit economics, while residential channels compress margins through distributor private-label competition.
United States
Texas and California dominate volume flows through megaproject pipelines in commercial and institutional construction. The EPA enforces VOC emission limits under 40 CFR Part 59 that constrain solvent-borne coating formulations nationwide. State transportation departments in Texas and California now require pre-qualification of admixture suppliers against decades-spanning performance databases.
Canada
Infrastructure rehabilitation across Ontario and Quebec drives demand for concrete repair admixtures and corrosion inhibitors. Health Canada's PMRA regulates antimicrobial additives, creating dual-certification requirements for cross-border suppliers. The Greater Toronto Area concentrates specification authority among engineering consultants who control approved vendor lists for public projects.
Mexico
Commercial construction in Mexico City and Nuevo León draws chemical volumes for waterproofing membranes and flooring systems. The country's national environmental regulator enforces emissions standards that increasingly align with US EPA frameworks. The Bajío Region hosts manufacturing clusters where formulation specialists serve regional cement producers.
California
Embodied carbon disclosure rules are forcing material specification changes toward lower-carbon cementitious systems before federal harmonization emerges. The state's Air Resources Board complements EPA standards with additional reporting requirements for architectural coatings. Los Angeles and San Francisco Bay Area megaprojects concentrate demand for high-performance waterproofing membranes.
Texas
Bridge deck rehabilitation and highway expansion create non-discretionary demand pools for epoxy bonding agents. The Texas Department of Transportation mandates field verification data spanning decades, compressing approved supplier lists. Houston and Dallas-Fort Worth corridors anchor distribution hub economics for just-in-time admixture delivery.
North America Construction Chemicals Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North American construction chemicals sector. Backward-integrated resin producers command defensive moats through captive polymer technology and feedstock cost insulation. Formulation specialists compete on decentralized service capabilities and local specification relationships. Dominant competitive moves include strategic partnerships with state transportation departments and portfolio diversification into waterborne coating architectures.
Within the integrated tier, Sika AG and BASF SE exemplify producers leveraging captive technical service capabilities for infrastructure pre-qualification. RPM International Inc. occupies a position representing the decentralized specialist archetype, navigating local specification requirements across multiple states through brand portfolio breadth. These three anchors illustrate how competitive positioning diverges between polymer-integrated leaders and service-intensive specialists.
| Leading Market Players |
|---|
| Sika AG |
| Saint-Gobain |
| RPM International Inc. |
| MAPEI S.p.A. |
| Holcim Group |
| BASF SE |
| Dow Inc |
| H.B. Fuller Co |
| Fosroc, Inc. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at backward-integrated resin producers in the United States Gulf Coast shapes price floors across admixture and coating formulations, concentrating margin capture among producers with captive polymer supply while forcing formulation specialists toward service-based differentiation.
Pricing Analysis
Technical service contracts and performance-based maintenance agreements drive lifetime value for integrated producers serving infrastructure pre-qualification requirements. Three-tier pricing structure across premium, standard, and economy levels separates ASTM-certified admixtures with decades of field data from commodity-grade alternatives. Cost compression in residential channels is intensifying because distributor private-label competition erodes brand premiums. Infrastructure buyers show the lowest price sensitivity, while residential contractors exhibit acute cost consciousness.
Supply Chain Analysis
Just-in-time delivery preferences dominate Texas megaproject corridors, where Texas Department of Transportation mandates compress inventory windows for approved admixture suppliers. Feedstock supply concentrates in the United States, Canada, and Mexico, with acrylic and polyurethane intermediates drawing from petrochemical complexes along the Gulf Coast. Raw material dependencies include crude oil derivatives, synthetic latex polymers, and epoxy resins. Single-source vulnerability around specialty corrosion inhibitors creates supply chain risk. Distribution runs through regional intermediaries with local specification relationships and technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as federal infrastructure rehabilitation mandates create non-discretionary demand pools for concrete repair admixtures and epoxy bonding agents.
For Market Incumbents: Consolidate specification authority by deepening captive technical service capabilities for state transportation department pre-qualification. Acquire regional distributors in Texas and California to secure hub economics for megaproject corridors. Invest in waterborne coating R&D ahead of EPA enforcement timelines to capture reformulation premiums.
For New Entrants and Emerging Players: Anchor in underserved waterproofing membrane specifications across humid subtropical zones in the southeastern United States, where building envelope code tightening outpaces incumbent capacity. Target mid-tier commercial contractors in Texas megaproject pipelines with qualified waterborne coating portfolios. Pursue partnership routes with engineering consultants who control approved vendor lists.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive polymer technology and long-term infrastructure maintenance contracts. Five-to-ten year viability favors backward-integrated specialists with ASTM certification depth and state DOT relationships. Monitor California embodied carbon disclosure implementation as an inflection indicator for specification shifts toward lower-carbon cementitious systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Intermediates | Captive acrylic and polyurethane supply insulates margins from petrochemical feedstock volatility. |
| Waterborne Coating Portfolio Expansion | EPA 40 CFR Part 59 compliance qualifies products for federal procurement channels. |
| State DOT Pre-Qualification Investment | Performance database management secures approved vendor status for bridge deck rehabilitation contracts. |
| Regional Distribution Hub Establishment | Texas megaproject concentration rewards just-in-time admixture delivery capabilities. |
| Self-Healing Admixture Commercialization | Microencapsulated healing agents displace scheduled maintenance contracts in critical infrastructure. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Plant managers at integrated resin producers, procurement leads at downstream concrete suppliers, distribution channel partners, and technical R&D directors at formulation specialists provided operational perspectives. Secondary validation drew from EPA enforcement records, state transportation department specification databases, SEC 10-K disclosures, and customs trade data. Bottom-up volume estimates triangulated against top-down market sizing across product categories and end-use verticals.
Sensitivity analysis tested forecast robustness across feedstock price scenarios and regulatory implementation timelines. The projection framework models segmentation across admixture grade tiers, end-use industries, application methods, and regional production hubs. CAGRs were derived from historical volume trajectories and elasticity-adjusted demand projections. Key inputs include infrastructure spending authorization levels, ASTM certification pipeline timelines, and state-level embodied carbon rule adoption curves.
Decision-makers should treat outputs as directional under stable petrochemical feedstock pricing and continued EPA enforcement intensity; material deviation would warrant model refresh. Forecasts reflect assumptions about infrastructure rehabilitation funding continuity and waterborne coating reformulation completion rates. Revision becomes warranted when California or New York embodied carbon disclosure thresholds trigger specification cascades before federal harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Ethyl Chloride Market
Chemicals
Ferric Phosphate Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Chromium Trioxide Market
Chemicals
Global Methyl Cellulose Market
Chemicals
Periodic Acid Market
Chemicals
Fireworks Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Dimethyl Phosphate Market
Chemicals
Coal Tar Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Hydrogen Chloride Market
Chemicals
Electroplating Chemicals Market
Chemicals
Glycerol Carbonate Market