
 Malic Acid Market | 2026-2036
Malic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Malic Acid Market Intelligence
ISO 22000 certification is unwinding competitive access across the malic acid supply base, filtering out smaller fermentation operators that lack documented food safety management systems. Bartek Ingredients Inc. leverages its Canadian manufacturing base to sustain North American supply continuity for beverage-grade acidulants. Fuso Chemical Co., Ltd. anchors Asian demand through synthetic process expertise and captive raw material sourcing.
Malic acid is a dicarboxylic acid with the molecular formula C₄H₆O₅, existing as L-, D-, and racemic DL-stereoisomers, produced through petrochemical synthesis or carbohydrate fermentation with Aspergillus species, functioning primarily as an acidulant, flavor enhancer, and pH buffer across food, pharmaceutical, and cosmetic systems. The L-malic acid segment dominates volume owing to its GRAS status and preferred metabolic pathway in human nutrition, while DL-malic acid occupies cost-sensitive industrial applications where optical purity carries less formulation value. Powder form leads current shipments due to handling efficiency and extended shelf stability, though liquid formulations are gaining traction in ready-to-drink beverage manufacturing lines.
REACH registration requirements in Europe and FDA GRAS self-affirmation protocols in the United States create divergent compliance cost structures that favor established multinationals with dedicated regulatory affairs capacity. China's GB standards for food additives and Japan's specifications and standards for food additives under the Food Sanitation Act impose additional testing burdens on cross-border suppliers. Stakeholders must monitor fermentation feedstock cost volatility and synthetic route energy intensity as dual levers that will determine regional cost competitiveness and sourcing strategy.
Market Dynamics
Fermentation-based malic acid production is consolidating competitive advantage as energy-intensive synthetic routes face carbon pricing pressure across major manufacturing jurisdictions. This feedstock pivot is redrawing supplier economics and certification requirements.
Growth Catalysts
- Clean-label acidulant demand:Beverage formulators in North America and Western Europe are replacing citric acid with malic acid for smoother tartness profiles in reduced-sugar formulations.
- REACH purity escalation:ECHA registration updates are disqualifying lower-grade imports, creating protected market space for compliant fermentation operators.
- Biopolymer feedstock expansion:Polyhydroxyalkanoate manufacturers are sourcing fermentation-grade malic acid as a chiral building block for biodegradable packaging materials.
Market Restraints
- Glucose price volatility:Fermentation operators face margin compression when corn-derived feedstock costs spike during poor harvest cycles in the US Midwest.
- Synthetic route lock-in:Maleic anhydride-based production in coastal China maintains cost advantages that delay regional fermentation adoption.
- Citric acid substitution:Established acidulant supply contracts and lower unit economics in soft drink manufacturing limit malic acid penetration in price-sensitive categories.
Strategic Opportunities
- India FSSAI pathway:India's food additive approval acceleration for GRAS-listed acidulants opens formulation partnerships with domestic processed food conglomerates.
- Pharmaceutical-grade L-malic:Excipient demand for chiral purity in tablet disintegration is creating premium pricing tiers separate from food-grade commodity markets.
- Carbon border adjustment alignment:EU CBAM implementation favors fermentation-derived acidulants with verifiable lifecycle emissions documentation.
Industry Challenges
- ISO 22000 audit backlog:Certification body capacity constraints are extending food safety management system approval timelines for new fermentation entrants.
- Aspergillus strain IP:Proprietary fungal culture licensing from Japanese and European research institutions creates royalty burdens for independent producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malic Acid Market |
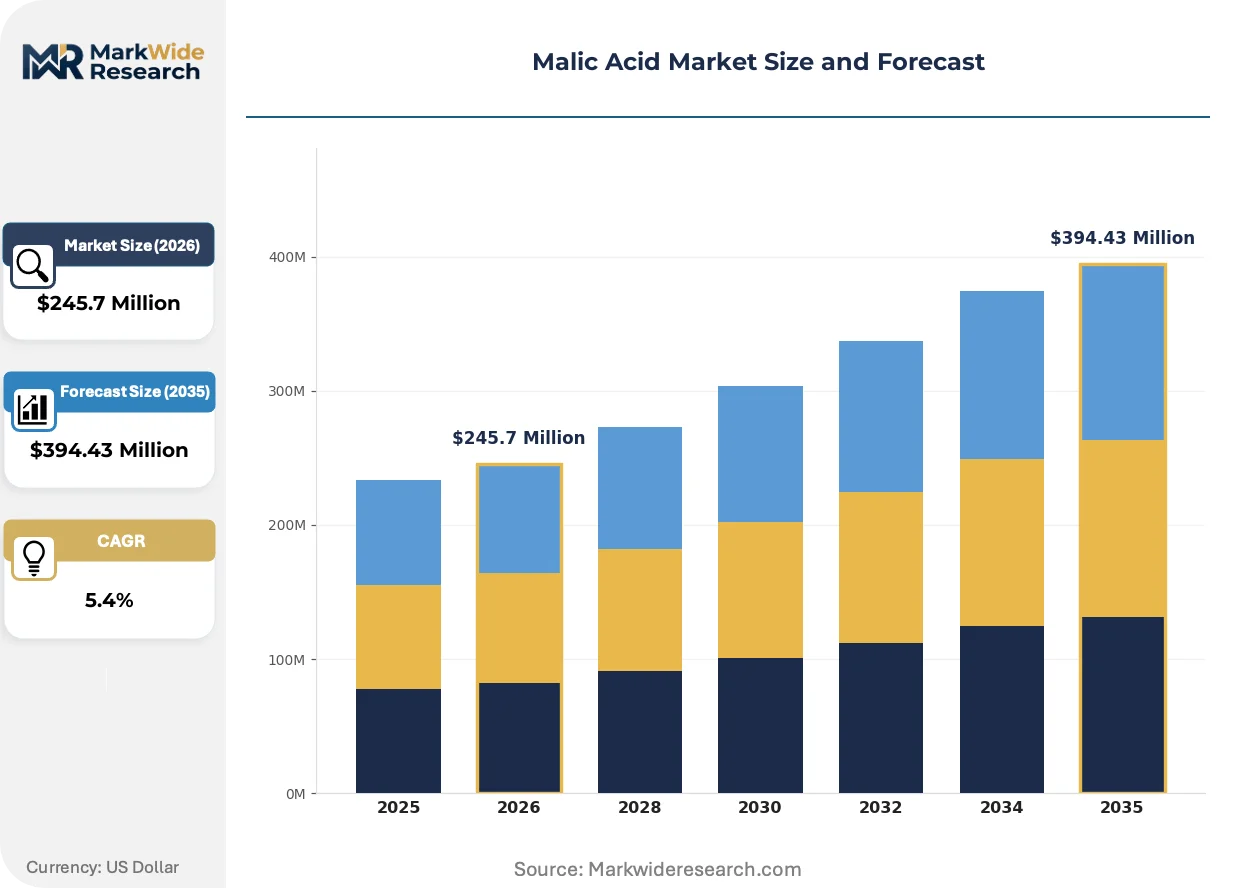
| Market Size in 2026 | $245.7 Million |
| Market Size in 2035 | $394.43 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Malic Acid, D-Malic Acid, DL-Malic Acid, Malic Acid Derivatives End User: Food & Beverage, Pharmaceuticals, Cosmetics, Personal Care Application: Food Additive, Flavoring Agent, pH Regulator, Nutraceutical Form: Powder, Liquid, Granules, Crystals |
| Companies Covered | Bartek Ingredients Inc., Fuso Chemical Co., Ltd., Polynt SpA, Jungbunzlauer Suisse AG, Anhui Sealong Biotechnology, Thirumalai Chemicals, Tate & Lyle PLC, Isegen South Africa, Changmao Biochemical Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malic Acid Market Strategic Shifts & Innovations
Bioprocess engineering advances are compressing fermentation cycle times while regulatory carbon accounting is rewiring feedstock sourcing decisions. These forces are converging to favor regional production over long-haul synthetic acidulant trade.
Continuous fermentation systems with cell retention technology are supplanting batch processing in new capacity installations. Beverage acidulant suppliers in Germany and California are adopting these systems to reduce utility costs and improve titer consistency. The shift is compressing capital recovery periods and enabling smaller-scale viable production.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration-dependent synthetic acidulant plant obsolescence. Maleic anhydride production facilities face retrofit requirements for low-global-warming-potential cooling systems. Synthetic operators in the Netherlands and Belgium are responding with fermentation joint ventures or import dependency strategies.
Direct supplier relationships with ready-to-drink beverage co-packers are displacing traditional distributor intermediaries in acidulant procurement. Large contract manufacturers in Texas and São Paulo are consolidating acidulant volumes and negotiating formula-exclusive supply agreements. This channel consolidation is most visible in private-label energy drink and functional water segments.
Malic Acid Market Segmentation

Malic acid segmentation reveals how optical purity, formulation requirements, and end-use certification tiers fragment margin capture across suppliers. Differentiation in stereoisomer specificity and delivery form creates distinct competitive battlegrounds that favor specialized fermentation operators over commodity synthetic producers.
Product Type:
L-Malic acid commands the widest margin pool due to GRAS status and pharmaceutical-grade pricing premiums, while DL-malic acid competes on cost in industrial applications where chiral purity carries minimal formulation value.
- L-Malic Acid:The naturally occurring stereoisomer preferred in human nutrition for its direct metabolic pathway through the citric acid cycle. Food and beverage formulators in the United States leverage L-malic acid for clean-label positioning in reduced-sugar beverages, with FDA GRAS self-affirmation protocols reinforcing supplier qualification barriers.
- DL-Malic Acid:Synthetic racemic mixture produced via maleic anhydride hydration, occupying cost-sensitive industrial niches where optical activity is irrelevant. Coastal Chinese manufacturers maintain cost advantages through maleic anhydride feedstock integration, though carbon pricing pressure is eroding this position in European markets.
- D-Malic Acid:The non-naturally occurring enantiomer with limited commercial application, primarily serving specialized pharmaceutical synthesis requiring chiral resolution intermediates.
- Malic Acid Derivatives:Esterified and salt forms including malates used as mineral chelates in nutraceutical formulations, with magnesium malate and calcium malate gaining traction in dietary supplement applications.
The dominant share belongs to L-Malic Acid, while DL-Malic Acid is closing the gap fastest through expanding industrial applications in regions with less stringent purity mandates.
End User:
Customer concentration patterns show beverage manufacturers consolidating acidulant procurement through direct supplier relationships, while pharmaceutical qualification timelines stretch revenue recognition cycles for excipient-grade producers.
- Food & Beverage:Acidulant demand concentrates in ready-to-drink manufacturing lines where malic acid replaces citric acid for smoother tartness profiles. Private-label energy drink co-packers in Texas and São Paulo are negotiating formula-exclusive supply agreements that displace traditional distributor channels.
- Pharmaceuticals:Excipient-grade L-malic acid for tablet disintegration commands premium pricing tiers separate from food-grade commodity markets, with chiral purity requirements filtering out fermentation operators lacking documented pharmaceutical quality systems.
- Cosmetics:pH buffering applications in skincare formulations leverage malic acid's alpha-hydroxy acid properties for exfoliant claims, with EU REACH registration updates tightening purity requirements for cosmetic-grade acidulants.
- Personal Care:Oral care products and hair conditioning formulations utilize malic acid as a pH adjuster, though volume remains constrained by established citric acid supply contracts in mass-market categories.
Food & Beverage generates the highest absolute volume, though Pharmaceuticals is expanding most quickly as chiral excipient demand outpaces commodity food-grade growth.
Application:
Functional positioning determines pricing power, with flavor enhancement commanding premiums over basic pH regulation while nutraceutical applications require additional clinical substantiation investments.
- Food Additive:Broad acidulant classification covering preservation and antimicrobial functions in processed foods, with EFSA evaluations under EU food additive reauthorization programs creating regulatory uncertainty for non-fermentation sources.
- Flavoring Agent:Taste modification in reduced-sugar beverages exploits malic acid's prolonged sour perception compared to citric acid. North American clean-label formulators are accelerating substitution patterns as consumer palates adjust to lower sweetness intensities.
- pH Regulator:Buffering capacity in beverage manufacturing lines requires consistent titratable acidity, with liquid malic acid formulations gaining share in continuous processing environments.
- Nutraceutical:Mineral malates for bioavailability enhancement in dietary supplements, with FSSAI approval acceleration in India opening formulation partnerships with domestic processed food conglomerates seeking functional positioning.
Flavoring Agent holds the dominant position, while Nutraceutical is gaining share fastest through mineral chelate applications in premium supplement segments.
Form:
Physical delivery format shapes logistics economics and manufacturing integration, with powder maintaining handling efficiency while liquid forms reduce processing steps in high-volume beverage operations.
- Powder:Dominant shipment format offering extended shelf stability and bulk handling efficiency. German fermentation operators supply powder grades with ISO 22000 certification for North American beverage manufacturers seeking supply continuity assurances.
- Liquid:Ready-to-use solutions eliminating dissolution steps in continuous beverage manufacturing lines. California-based co-packers are adopting liquid acidulant delivery to reduce utility costs and improve batch consistency.
- Granules:Intermediate flow characteristics for tableting operations in pharmaceutical and nutraceutical manufacturing, with controlled particle size distribution reducing segregation risks in powder blends.
- Crystals:High-purity solid form for analytical standards and specialized pharmaceutical synthesis requiring precise stoichiometric control.
Powder retains the dominant share, while Liquid is climbing the fastest through adoption in automated beverage production facilities seeking processing efficiency gains.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage formulators in the United States and Germany drive premium acidulant procurement, while Chinese fermentation capacity anchors volume supply. Regulatory divergence between FDA GRAS protocols and ECHA REACH registration creates distinct qualification barriers across major consumption zones.
United States
Clean-label beverage manufacturers in Texas and California are replacing citric acid with malic acid for smoother tartness profiles in reduced-sugar formulations. FDA GRAS self-affirmation protocols reinforce supplier qualification barriers that filter out non-compliant imports. Private-label energy drink co-packers in the Dallas-Fort Worth metroplex are consolidating acidulant volumes through direct supplier relationships.
China
Domestic fermentation-based production capacity continues expanding in Shandong and Jiangsu provinces to serve regional processed food demand. GB standards for food additives impose testing burdens on cross-border suppliers seeking market access. Coastal maleic anhydride-based synthetic operations in Zhejiang maintain cost advantages that delay regional fermentation adoption.
Germany
Continuous fermentation systems with cell retention technology are supplanting batch processing in new capacity installations across Bavaria and North Rhine-Westphalia. EU F-Gas Regulation phase-down schedules are accelerating refrigeration-dependent synthetic acidulant plant obsolescence. Beverage acidulant suppliers near Cologne are adopting liquid malic acid delivery to reduce utility costs.
India
FSSAI approval acceleration for GRAS-listed acidulants is opening formulation partnerships with domestic processed food conglomerates in Maharashtra and Gujarat. Glucose price volatility from corn-derived feedstock creates margin compression risks during poor monsoon cycles. Fermentation operators near Mumbai are navigating certification body capacity constraints for ISO 22000 approval timelines.
Japan
Specifications and standards for food additives under the Food Sanitation Act impose additional testing burdens on cross-border suppliers. Proprietary Aspergillus strain licensing from domestic research institutions creates royalty burdens for independent producers. Pharmaceutical-grade excipient demand in the Osaka-Kobe industrial zone commands premium pricing tiers separate from food-grade commodity markets.
Malic Acid Market Key Industry Players
Player mix skews toward fermentation specialists with documented food safety management systems and synthetic producers with captive petrochemical feedstock integration. The competitive terrain fragments across three tiers: premium-grade pharmaceutical suppliers, beverage-grade fermentation operators, and industrial-grade synthetic manufacturers. Two dominant competitive moves are reshaping positioning: strategic partnerships with ready-to-drink co-packers for formula-exclusive supply agreements, and backward integration into glucose feedstock sourcing to hedge agricultural commodity volatility.
Within the fermentation-specialist tier, Bartek Ingredients Inc. and Jungbunzlauer Suisse AG exemplify operators leveraging documented quality systems to sustain supply continuity for beverage-grade acidulants. Fuso Chemical Co., Ltd. occupies a distinct position among synthetic process specialists with expertise in maleic anhydride-based production routes. These three anchors illustrate how geographic manufacturing base and process technology selection determine competitive access across regulatory jurisdictions.
| Leading Market Players |
|---|
| Bartek Ingredients Inc. |
| Fuso Chemical Co., Ltd. |
| Polynt SpA |
| Jungbunzlauer Suisse AG |
| Anhui Sealong Biotechnology |
| Thirumalai Chemicals |
| Tate & Lyle PLC |
| Isegen South Africa |
| Changmao Biochemical Engineering |
| Others |
Cost & Logistics Intelligence
Fermentation scale economies in Shandong and Jiangsu provinces compress unit costs below synthetic thresholds, concentrating supply power among Chinese operators while establishing price floors that marginalize smaller Western batch processors. This scale advantage propagates through contract structures indexed to corn futures, binding buyer costs to agricultural commodity cycles rather than petrochemical spreads.
Pricing Analysis
Cost-plus contracts with corn futures indexation dominate procurement between fermentation operators and North American beverage manufacturers, creating predictable pass-through mechanics for glucose feedstock volatility. Pricing stratifies across pharmaceutical-grade excipient, beverage-grade certified, and industrial DL grades, with chiral purity and ISO 22000 documentation commanding substantial premiums. Cost compression in industrial DL segments intensifies because coastal Chinese synthetic producers maintain maleic anhydride integration advantages. Private-label energy drink co-packers exhibit highest price sensitivity, while pharmaceutical tablet manufacturers accept premium tiers for documented excipient traceability.
Supply Chain Analysis
China, Germany, and the United States anchor fermentation-based malic acid production, with coastal Chinese facilities supplying volume and Bavarian operators serving premium European demand. Production draws from corn-derived glucose, proprietary Aspergillus strain licenses, and maleic anhydride feedstocks. Single-source vulnerability concentrates in Japanese fungal culture IP, where royalty burdens tether independent producers to institutional licensors. Distribution runs through direct supplier relationships with ready-to-drink co-packers, displacing traditional distributor intermediaries in acidulant procurement.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation technology maturation and EU carbon border adjustment implementation constitute a dual inflection, reshaping competitive economics toward low-emission biological production and away from energy-intensive synthetic routes.
For Market Incumbents: Fortify market position through backward integration into glucose feedstock sourcing and captive Aspergillus strain development, neutralizing agricultural commodity volatility and Japanese IP royalty exposure. Expand continuous fermentation capacity in Germany and California to exploit EU F-Gas Regulation phase-down schedules that accelerate synthetic plant obsolescence. Prioritize ISO 22000 certification maintenance to sustain qualification barriers against emerging fermentation entrants facing audit backlog constraints. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade L-malic acid excipient positioning, where chiral purity requirements and documented quality systems filter out commodity fermentation operators. Target India's FSSAI-accelerated approval pathway for GRAS-listed acidulants, partnering with Maharashtra and Gujarat processed food conglomerates seeking functional nutraceutical positioning. Deploy direct technical sales to ready-to-drink co-packers in São Paulo and Texas, bypassing distributor channels that incumbents dominate. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation operators with long-term supply agreements to beverage co-packers, where formula-exclusive contracts generate contracted offtake visibility. Five-to-ten year viability favors operators with verifiable lifecycle emissions documentation aligned with EU CBAM implementation. Acquisition targets should demonstrate captive glucose sourcing or proprietary strain libraries. The signal to watch is carbon accounting disclosure maturity among synthetic producers, as regulatory pressure accelerates feedstock pivot decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Feedstock | Captive corn supply hedges against Midwest harvest volatility and secures fermentation input cost stability. |
| Continuous Fermentation Capacity Expansion | Cell retention technology in Bavaria reduces utility costs and improves titer consistency for beverage clients. |
| Pharmaceutical-Grade L-Malic Qualification | Chiral excipient certification opens premium pricing tiers separate from commodity food-grade markets. |
| Direct Co-Packer Supply Agreements | Formula-exclusive contracts with Texas and São Paulo manufacturers displace traditional distributor channels. |
| Proprietary Aspergillus Strain Development | In-house fungal culture libraries eliminate Japanese and European research institution royalty burdens. |
Research Approach
Initial hypotheses were tested against primary input from fermentation plant managers, beverage formulation chemists, pharmaceutical excipient procurement leads, and acidulant distribution channel partners and refined through secondary validation against customs trade data, SEC 10-K filings, ECHA REACH registration databases, and Food Sanitation Act additive specifications. Bottom-up capacity assessments across Shandong, Jiangsu, Bavaria, and California facilities were triangulated with top-down demand estimates from ready-to-drink beverage production volumes and pharmaceutical tablet disintegration excipient consumption.
Variance decomposition across the modeling period isolates volume drivers by stereoisomer grade, end-use certification tier, physical delivery form, and regional regulatory cluster. CAGRs were derived from segmented growth trajectory analysis incorporating fermentation feedstock cost projections and synthetic route carbon pricing exposure. Industry-specific forecast inputs include glucose futures curve assumptions and EU F-Gas Regulation retrofit cost schedules for maleic anhydride facilities.
Decision-makers should treat outputs as directional under sustained clean-label acidulant substitution patterns and REACH purity escalation timelines; material deviation in corn harvest cycles or carbon border adjustment implementation pace would warrant model refresh. Recalibration cycles align with material shifts in fermentation technology cost curves and regulatory carbon accounting stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
US Methanol Market
Chemicals
Detergent Alcohols Market
Chemicals
Cyclopentylamine Market
Chemicals
Industrial Odor Management Market
Chemicals
3,5-Dinitroaniline Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Electronic Grade Hydrofluoric Acid Market
Chemicals
Selenium Sulfide Market
Chemicals
China Inorganic Iodide Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
Diethyl Sulfate Market
Chemicals
Pyrimidine Market
Chemicals
Potassium Permanganate Market
Chemicals
Scouring Agents Market
Chemicals
Paint Remover Market
Chemicals
Oxybenzone Market