
 Neopentyl Polyhydric Alcohol Market | 2026-2036
Neopentyl Polyhydric Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Neopentyl Polyhydric Alcohol Market Foresight
China is reshaping supply dynamics through major capacity additions in Shandong and Jiangsu provinces. BASF leverages its integrated Ludwigshafen complex to sustain cost advantages in neopentyl glycol output. Perstorp Group anchors European supply with specialized high-purity grades for powder coatings. LG Chem competes through backward integration into petrochemical feedstocks at its Yeosu complex.
Neopentyl polyhydric alcohols comprise a class of sterically hindered polyols including neopentyl glycol, trimethylolpropane, and pentaerythritol, synthesized via aldol condensation or Cannizzaro routes and valued for hydroxyl functionality exceeding 98% with exceptional thermal and UV stability. These compounds serve primarily as polyester and alkyd resin building blocks for durable coatings and engineered plastics. Pentaerythritol dominates volume due to its four hydroxyl groups enabling highly crosslinked rosin esters and intumescent flame-retardant systems. Neopentyl glycol commands premium positioning in powder coatings where its non-crystallizing behavior eliminates surface defects. Trimethylolpropane grows fastest in UV-curable applications for electronics and automotive refinish segments.
EPA oversight of volatile organic compound emissions in industrial coatings directly constrains solvent-based formulation growth and redirects demand toward high-solids and powder systems reliant on neopentyl polyhydric alcohols. REACH registration requirements and ECHA substance evaluation force European suppliers to document full toxicological profiles, raising barriers for non-compliant imports. China's MEE enforces stricter wastewater discharge standards at chemical parks, accelerating consolidation among smaller aldehyde-based polyol producers. Stakeholders must track regulatory divergence between jurisdictions to optimize manufacturing location and product portfolio decisions.
Market Dynamics
Automotive OEMs are consolidating their powder coating specifications around high-performance polyester resins, compressing formulation windows and forcing polyol suppliers to certify thermal stability metrics that exceed legacy alkyd benchmarks by substantial margins.
Growth Catalysts
- EPA VOC mandates:Industrial coatings manufacturers in the US are reformulating solvent-based systems toward high-solids alternatives that rely on neopentyl glycol's low viscosity contribution.
- Automotive refinish demand:Collision repair networks in Germany and Japan are specifying UV-curable clearcoats that incorporate trimethylolpropane for rapid cure cycles.
- China chemical park consolidation:Capacity rationalization in Shandong province is concentrating aldehyde feedstock supply among integrated producers capable of ISO-grade purity certification.
Market Restraints
- Formaldehyde price volatility:Cannizzaro-route pentaerythritol output remains exposed to methanol and acetaldehyde feedstock swings that compress margin predictability.
- European import barriers:REACH registration costs and ECHA substance evaluation timelines are excluding smaller Asian producers from EU powder coating supply chains.
- Technical substitution ceiling:Neopentyl glycol's steric hindrance prevents direct replacement in certain flexible polyurethane foam applications requiring linear chain extension.
Strategic Opportunities
- India industrial coatings penetration:Protective coatings demand from infrastructure and automotive OEMs in Maharashtra and Gujarat remains underdeveloped relative to per-capita industrial output.
- Intumescent fire-retardant systems:Building codes in the UAE and Saudi Arabia are mandating expanded pentaerythritol-based char-forming layers in high-rise steel protection.
- UV-LED curing convergence:Electronics manufacturers in South Korea are pairing trimethylolpropane acrylates with 395nm LED sources to eliminate mercury lamp hazards.
Industry Challenges
- Specialized process engineering talent:Aldol condensation reactor optimization and hydrogenation catalyst management require expertise concentrated among retiring European and Japanese technical workforces.
- MEE wastewater compliance:China's Ministry of Ecology and Environment discharge standards are forcing capital expenditure on biological treatment and zero-liquid-discharge systems at legacy Shandong facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neopentyl Polyhydric Alcohol Market |
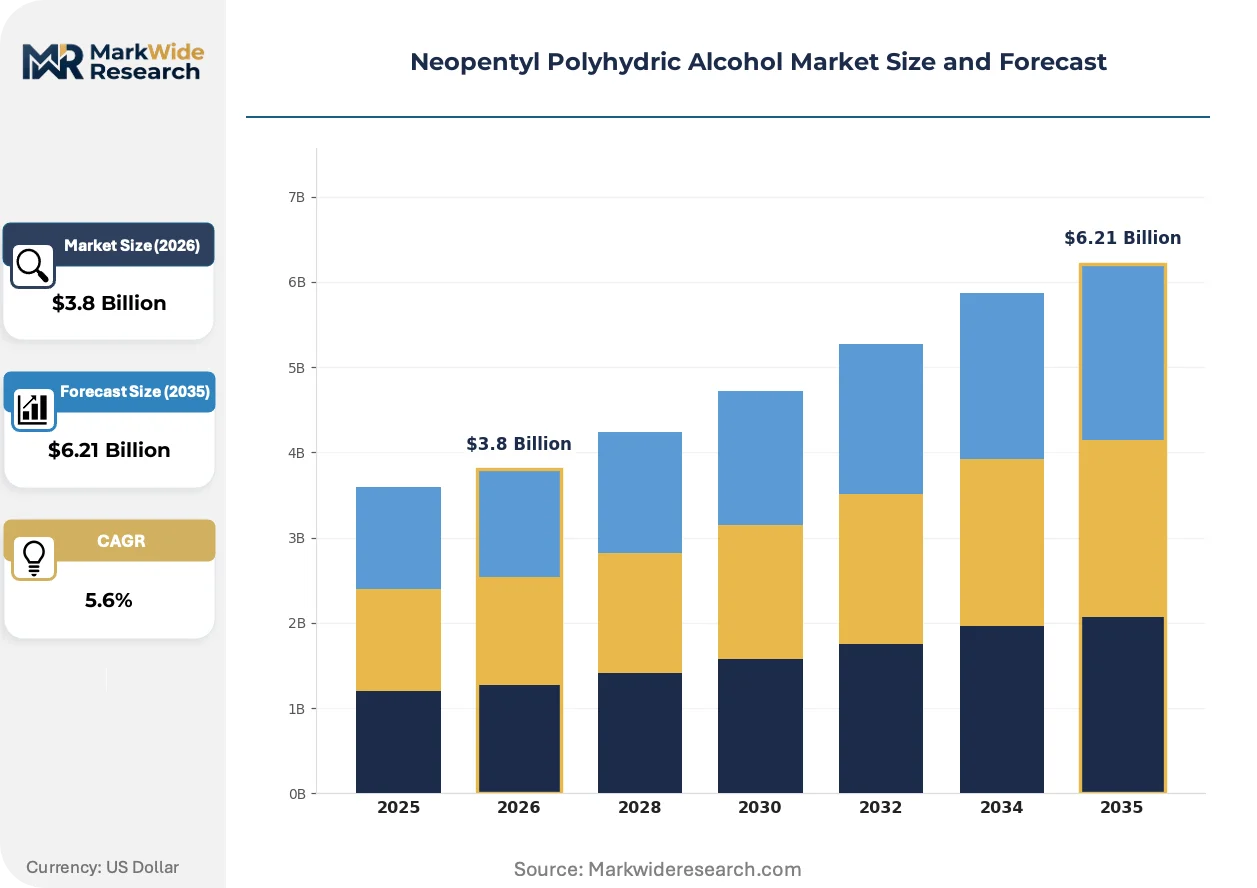
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neopentyl Glycol, Trimethylolpropane, Pentaerythritol, Others Application: Coatings, Plastics, Adhesives, Lubricants End User: Automotive, Construction, Consumer Goods, Electronics Distribution Channel: Direct Sales, Distributors, Online Sales, Retailers |
| Companies Covered | Perstorp Group, BASF, Lanxess, Oxea, Ercros SA, Eastman, LG Chem, Hubei Yihua Group, Mitsubishi Gas Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neopentyl Polyhydric Alcohol Market Shifts & Advancements
Formulation chemistry is pivoting toward systems that eliminate thermal cure energy entirely, with radiation-curable and ambient-cure platforms capturing specification share from traditional bake cycles.
Hybrid polyester-epoxy powder coating resins synthesized with neopentyl glycol are rendering obsolete conventional TGIC-cured systems in European architectural applications. Window and facade manufacturers in Germany and the Netherlands are qualifying these alternatives to eliminate isocyanurate health hazards from fabrication shops. The shift is compressing demand for legacy curatives while expanding specification opportunities for hindered polyol suppliers.
REACH authorization requirements for formaldehyde-releasing substances are forcing European coatings formulators to document supply chain aldehyde content across imported pentaerythritol batches. ECHA's 2023-2024 substance evaluation wave has triggered testing protocols that add six to nine months to raw material qualification timelines. Powder coating producers are responding by dual-sourcing from Ludwigshafen and Yeosu to reduce single-origin regulatory exposure.
Automotive tier-one suppliers are unbundling coating procurement from integrated body-in-white contracts, creating direct specification relationships with resin and polyol producers. Electronics contract manufacturers in Taiwan and South Korea are bypassing regional distributors to negotiate annual volume agreements with Perstorp and LG Chem for UV-grade trimethylolpropane. This disintermediation is most visible in automotive refinish segments where collision repair networks now source certified batches through approved importer channels rather than local chemical traders.
Neopentyl Polyhydric Alcohol Market Segmentation
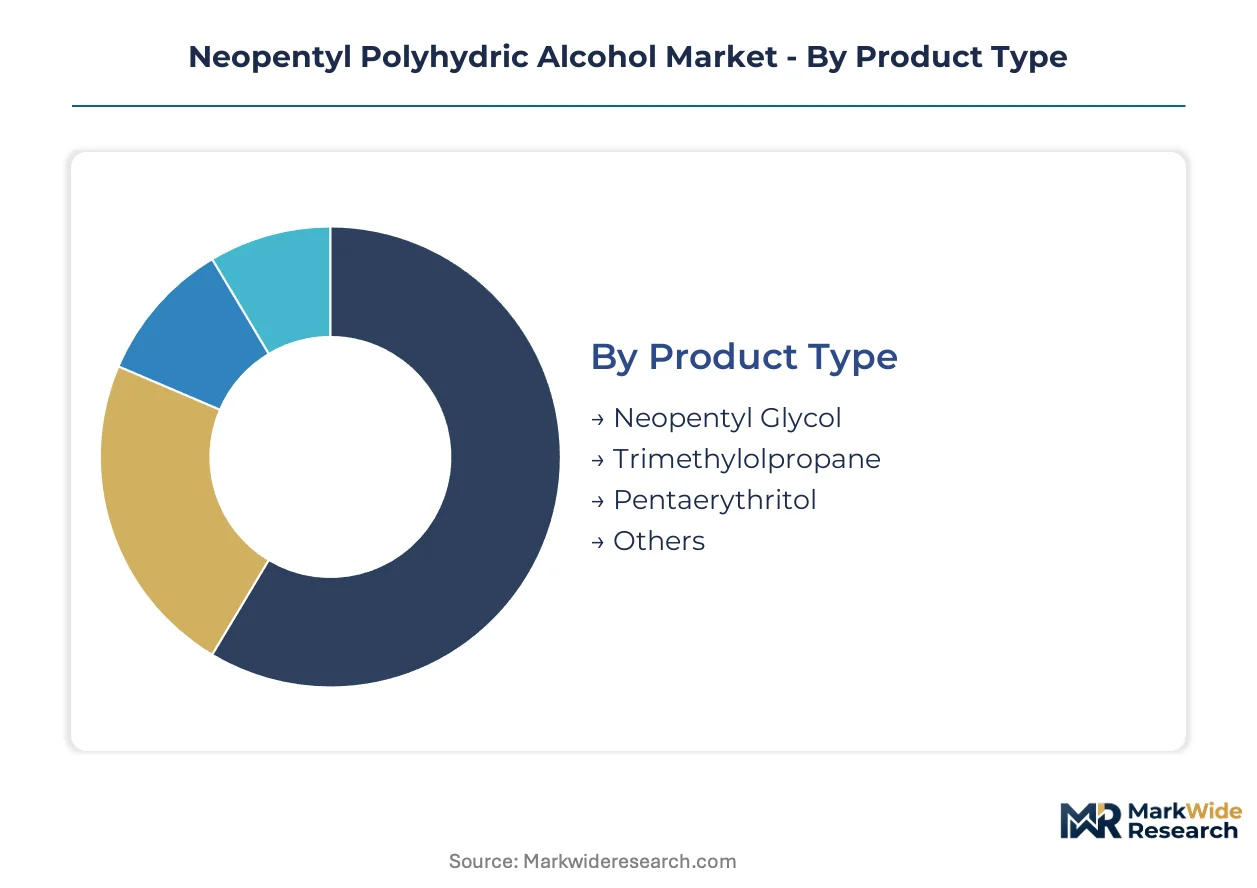
Neopentyl polyhydric alcohol suppliers configure technical service teams and specification support differently across segment boundaries. Product-grade certification requirements and end-use performance liabilities create distinct aftermarket engagement models that reshape margin structures and customer retention economics.
Product Type:
After-sales intensity peaks with high-purity grades requiring batch-specific certificates of analysis and regulatory documentation support.
- Neopentyl Glycol:A diol with gem-dimethyl substitution preventing crystallization in polyester resins. Powder coating formulators in Germany specify this grade for architectural facade systems requiring defect-free finish quality under ECHA REACH documentation protocols.
- Pentaerythritol:A tetrafunctional polyol synthesized via Cannizzaro or aldol condensation routes yielding 98% hydroxyl functionality. Intumescent fire-retardant compounders in the UAE and Saudi Arabia source technical-grade material for steel protection coatings mandated under Gulf building codes.
- Trimethylolpropane:A trifunctional polyol favored in radiation-curable acrylate oligomers for electronics and automotive refinish.
- Others:Includes dipentaerythritol and technical blends for specialized alkyd modifications.
By volume, Pentaerythritol leads. By growth pace, Trimethylolpropane is ahead.
Application:
Cost tier differentiation separates specification-grade coatings from commodity plastics compounding in procurement patterns and margin capture.
- Coatings:Powder, liquid, and UV-curable systems consuming over half of neopentyl glycol output. Automotive OEMs in Japan consolidate polyester resin specifications around thermal stability metrics exceeding legacy alkyd benchmarks.
- Plastics:Polyester polyol feedstocks for polyurethane and thermoplastic engineering resins. Shandong province chemical parks supply ISO-grade material to extrusion compounders facing MEE wastewater compliance deadlines.
- Adhesives:Reactive hot-melts and structural bonding systems requiring controlled hydroxyl equivalent weight.
- Lubricants:Neopentyl polyol esters for synthetic base stocks in aviation and industrial applications.
Coatings command premium pricing. Adhesives are expanding most quickly on electronics miniaturization demand.
End User:
Customer type fragmentation concentrates technical service resources among automotive tier-one suppliers while construction buyers prioritize logistics reliability.
- Automotive:Collision repair networks in Germany and Japan specify UV-curable clearcoats incorporating trimethylolpropane for rapid cure cycles. Tier-one suppliers now source certified polyol batches through approved importer channels rather than regional distributors.
- Construction:Protective and architectural coatings from Maharashtra and Gujarat infrastructure projects remain underdeveloped relative to per-capita industrial output.
- Consumer Goods:Packaging coatings and appliance finishes with moderate performance requirements.
- Electronics:South Korean manufacturers pair trimethylolpropane acrylates with 395nm LED sources to eliminate mercury lamp hazards in UV-LED curing convergence.
Automotive generates the highest specification intensity. Electronics shows the steepest expansion trajectory.
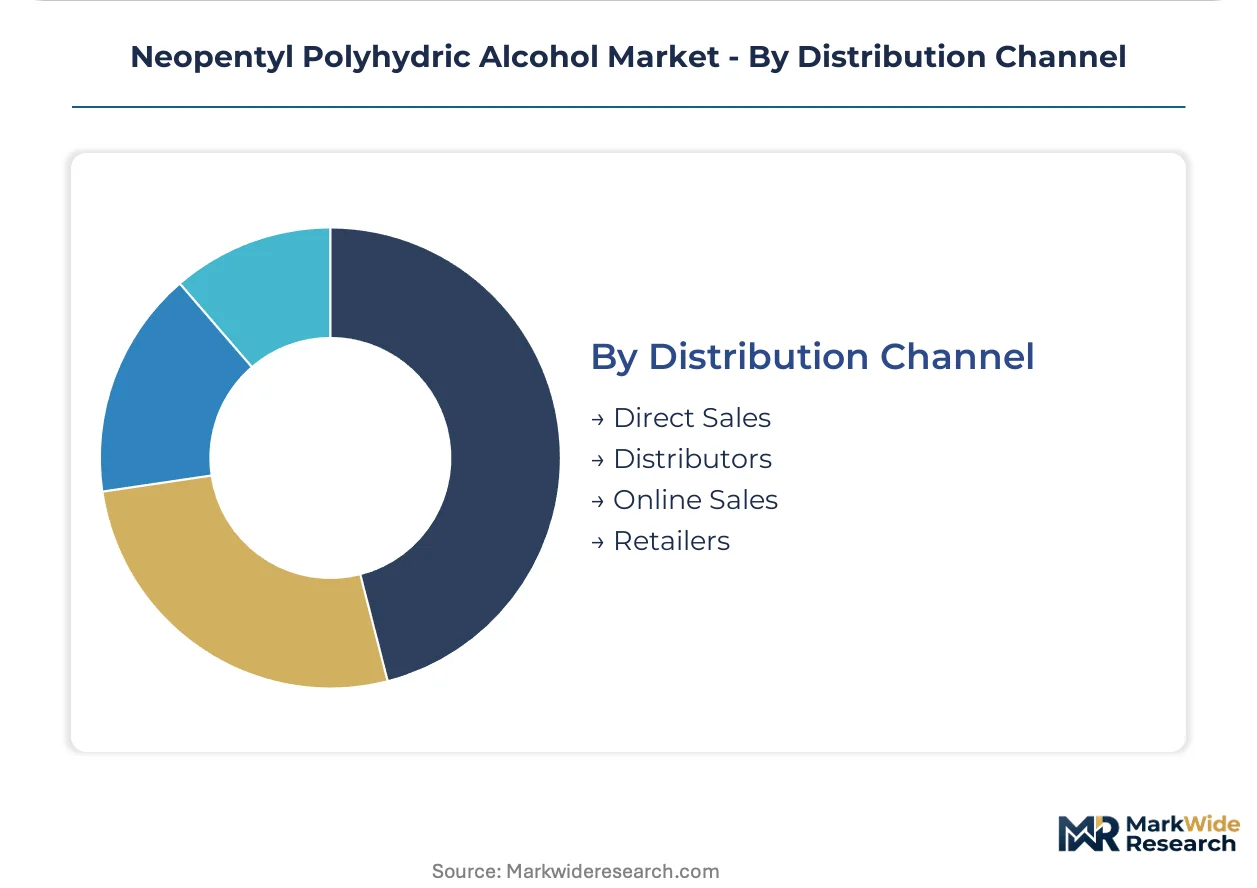
Distribution Channel:
Supply concentration among integrated producers favors direct relationships for volume accounts while distributors serve fragmented regional formulators.
- Direct Sales:Annual volume agreements between LG Chem at Yeosu and Taiwanese electronics contract manufacturers bypassing traditional distribution. BASF's Ludwigshafen complex sustains cost advantages through captive feedstock integration.
- Distributors:Regional chemical traders serving smaller coatings formulators with warehousing and blended delivery.
- Online Sales:Emerging procurement channel for standard-grade material with documented certificates.
- Retailers:Limited to specialty chemical outlets serving research and pilot-scale buyers.
Direct sales capture the largest volume share. Online channels are gaining share fastest on documentation transparency requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated petrochemical complexes in China, Germany, and South Korea concentrate the bulk of neopentyl polyhydric alcohol capacity. Feedstock access and hydrogenation expertise determine regional cost positioning. Regulatory divergence between EPA, REACH, and MEE standards fragments qualification requirements across export markets.
China
Shandong and Jiangsu provinces host aldehyde-based polyol clusters serving domestic coatings demand. MEE wastewater discharge standards at chemical parks are accelerating consolidation among smaller producers. Ningbo and Shanghai industrial zones concentrate ISO-grade purification capacity for powder coating exports.
Germany
Ludwigshafen's integrated chemical complex sustains cost advantages in high-purity neopentyl glycol output. ECHA substance evaluation timelines under REACH are forcing dual-sourcing strategies among European formulators. Window and facade manufacturers in the Netherlands qualify German-sourced material for architectural specifications.
United States
EPA VOC mandates for industrial coatings are redirecting solvent-based formulation demand toward high-solids systems. Gulf Coast petrochemical infrastructure supports aldehyde feedstock supply for pentaerythritol production. Automotive OEMs in Michigan consolidate polyester resin specifications around thermal stability metrics.
South Korea
Yeosu complex operations leverage backward integration into petrochemical feedstocks for trimethylolpropane output. Electronics manufacturers pair Korean-sourced acrylates with 395nm UV-LED curing systems. Taiwanese contract manufacturers negotiate direct annual volume agreements bypassing regional distributors.
Japan
Collision repair networks specify UV-curable clearcoats incorporating trimethylolpropane for rapid cure cycles. METI oversight of chemical manufacturing maintains stringent purity certification requirements. Automotive tier-one suppliers source certified batches through approved importer channels rather than local traders.
Neopentyl Polyhydric Alcohol Market Competitive Landscape
European chemical conglomerates and Asian integrated petrochemical groups split the market between specification-grade and volume-driven supply. The vendor base concentrates around three strategic archetypes: integrated petrochemical majors with captive feedstock, specialized polyol producers with hydrogenation expertise, and regional aldehyde-based manufacturers serving commodity grades. Capacity expansion and REACH-compliant certification programs represent the dominant competitive moves as qualification timelines extend.
Within the integrated major tier, BASF and LG Chem exemplify archetypes combining petrochemical feedstock control with hydrogenation scale. Perstorp Group occupies a position representing specialized European producers focused on high-purity grades for powder coating specifications. Among Asian manufacturers, Mitsubishi Gas Chemical and Hubei Yihua Group sit within regional supply structures serving domestic coatings demand and export qualification pipelines respectively.
| Leading Market Players |
|---|
| Perstorp Group |
| BASF |
| Lanxess |
| Oxea |
| Ercros SA |
| Eastman |
| LG Chem |
| Hubei Yihua Group |
| Mitsubishi Gas Chemical |
| Others |
Supply & Pricing Matrix
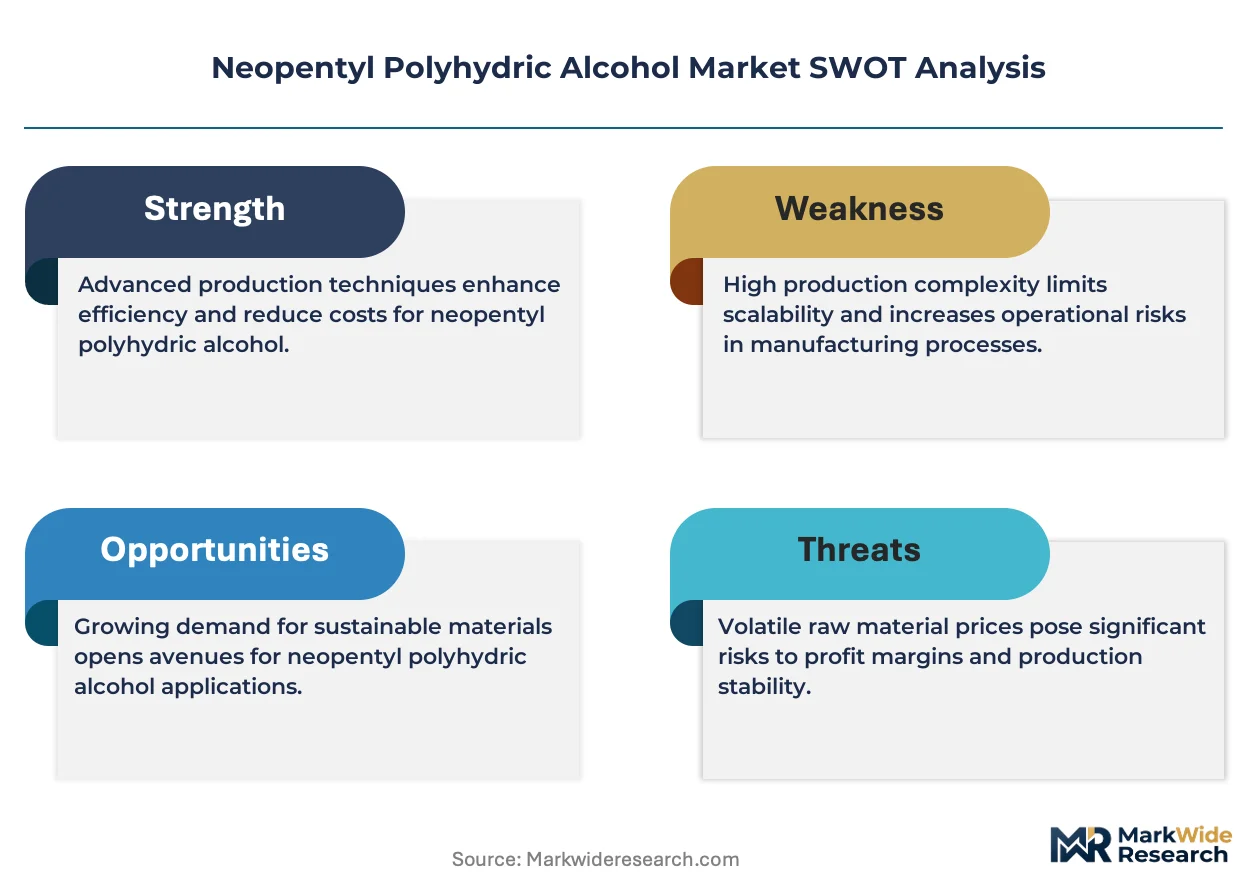
Formaldehyde price volatility determines both pricing tier spreads and supply chain shape across neopentyl polyhydric alcohol markets, compressing margin predictability for Cannizzaro-route producers while rewarding integrated complexes with captive aldehyde supply. REACH registration costs and ECHA substance evaluation timelines simultaneously erect regulatory chokepoints that bifurcate European procurement between qualified premium grades and excluded commodity imports.
Pricing Analysis
REACH dictates the pricing tier structure across European neopentyl polyhydric alcohol procurement, separating ECHA-registered premium grades from non-compliant commodity imports. Three-tier pricing structure across certification-grade, standard industrial, and technical-economy levels tracks hydroxyl purity and documentation depth. Cost compression in standard industrial tiers is intensifying because Shandong province chemical park consolidation concentrates ISO-grade supply among fewer integrated producers. Powder coating formulators in Germany exhibit lowest price sensitivity due to specification liability exposure, while commodity alkyd resin compounders in India face acute margin pressure from feedstock swings.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for neopentyl polyhydric alcohol distributors serving REACH-compliant markets. Production gravity centers on China, Germany, and South Korea, with aldehyde feedstock supply drawing from methanol and acetaldehyde streams tethered to regional petrochemical infrastructure. Single-source vulnerability persists for high-purity neopentyl glycol grades where Ludwigshafen and Yeosu complexes control hydrogenation catalyst expertise. Distribution runs through direct annual volume agreements for automotive tier-one suppliers and Taiwanese electronics contract manufacturers, supplemented by regional chemical traders serving fragmented coatings formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neopentyl polyhydric alcohol market sits at a platform-economics inflection where powder coating specification unbundling from integrated body-in-white contracts creates direct resin-producer relationships, with interoperability shifting from distributor-mediated to certified-batch traceability systems.
For Market Incumbents: Pre-empt specification consolidation among automotive OEMs by securing thermal stability certification exceeding legacy alkyd benchmarks through hydrogenation catalyst optimization at integrated complexes. Defend against emerging Asian entrants by accelerating REACH-compliant documentation programs that extend qualification timelines for non-registered imports. Capacity addition in Jiangsu province chemical parks with zero-liquid-discharge systems anchors cost position against MEE wastewater compliance pressures. For New Entrants and Emerging Players: UV-curable electronics applications in South Korea represent the most penetrable entry point given 395nm LED curing convergence and disintermediation of regional distributors by Taiwanese contract manufacturers. Intumescent fire-retardant compounders in the UAE and Saudi Arabia offer secondary white-space as Gulf building codes mandate expanded pentaerythritol-based steel protection. Go-to-market execution should prioritize direct technical service relationships over distributor channel stacking. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized hydrogenation expertise over commodity aldehyde capacity. Long-term viability over the next decade hinges on captive feedstock integration and REACH registration asset value. Acquisition target archetype: mid-scale European producers with ECHA-registered high-purity grades and stranded hydrogenation talent. Signal to monitor: MEE enforcement actions triggering Shandong facility closures and import qualification pipeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | Yeosu and Ludwigshafen complexes sustain cost advantages through captive aldehyde supply security. |
| REACH-Compliant Certification Investment | ECHA registration timelines exclude non-compliant Asian producers from EU powder coating supply chains. |
| Zero-Liquid-Discharge Capacity Upgrade | MEE wastewater standards force biological treatment capital expenditure at legacy Shandong facilities. |
| Direct Technical Service Team Deployment | Automotive tier-one unbundling creates specification relationships bypassing regional chemical traders. |
| UV-Grade Trimethylolpropane Capacity Expansion | South Korean electronics manufacturers pair acrylates with 395nm LED sources eliminating mercury hazards. |
Research Methodology
Operator-level perspectives from plant managers at integrated petrochemical complexes, procurement leads at powder coating OEMs, distribution channel partners serving fragmented formulators, and technical R&D directors specializing in aldol condensation reactor optimization anchored the qualitative base. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical conglomerates, and ECHA substance evaluation databases. Bottom-up volume modeling across grade tiers, end-use industries, and regional production hubs triangulated with top-down macroeconomic anchors.
Scenario-bracketing around regulatory enforcement intensity, feedstock price volatility bands, and specification unbundling velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, application category, end-user industry, and distribution channel structure. CAGRs were derived from installed capacity utilization rates, substitution elasticity estimates for UV-curable systems, and regional coatings demand intensity metrics.
Practitioners should monitor formaldehyde spot price movements, MEE enforcement action announcements, and automotive OEM specification consolidation timelines for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Anhydrous Aluminum Chloride Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
Schneider's Insect Medium Market
Chemicals
Valeronitrile Market
Chemicals
Lead Tetracetate Market
Chemicals
1-Methylimidazole Market
Chemicals
Chemical As a Service Market
Chemicals
Thioacetic Acid Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Whitening Ingredients Market
Chemicals
Global Glycine Market
Chemicals
Pyrogallol Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
Etching Chemicals Market
Chemicals
Phenothiazine Market