
 Aliphatic Amines Market | 2026-2036
Aliphatic Amines Market Size, Share, and Industry Trends Forecast 2026-2036
Aliphatic Amines Market Intelligence
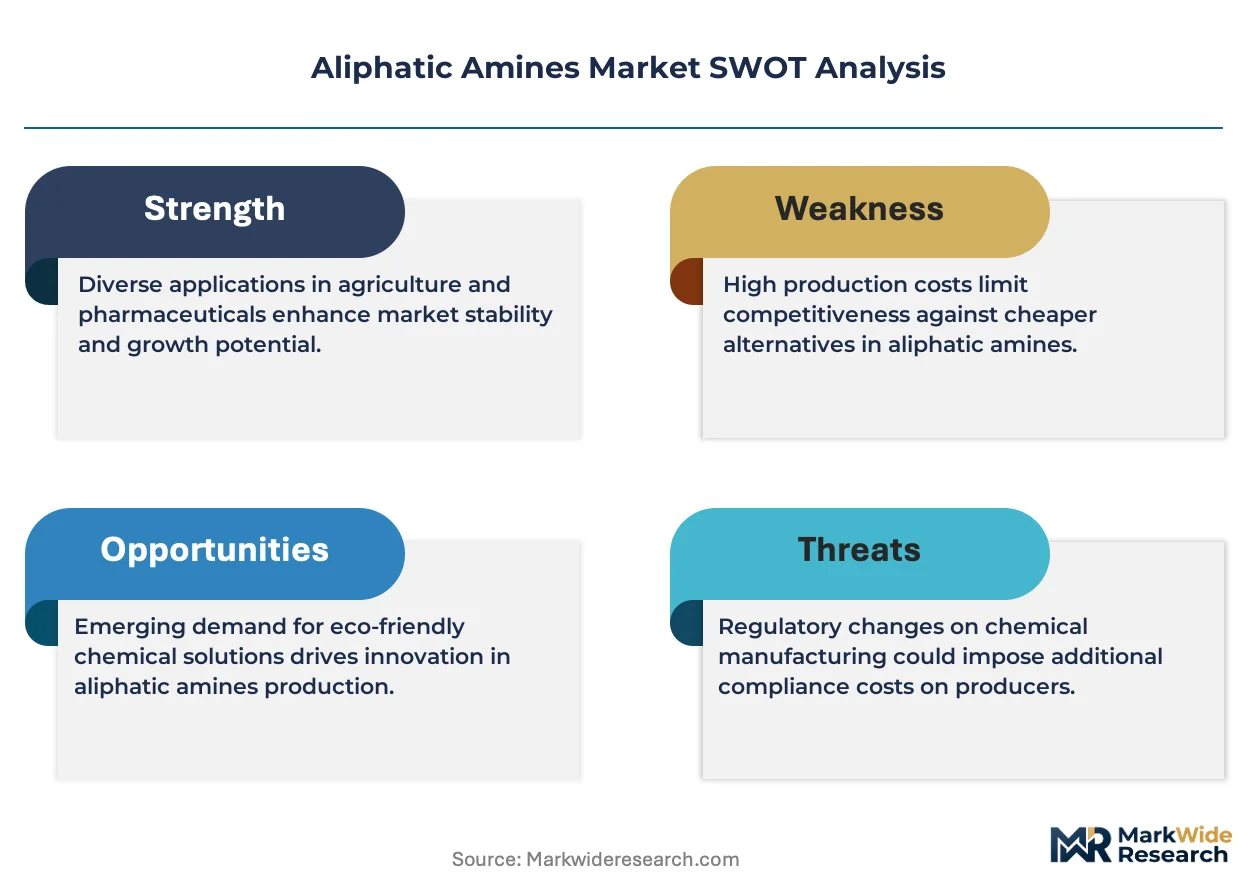
Water treatment is realigning the demand profile for aliphatic amines as municipalities and industrial plants scale chemical dosing programs. Dow Chemical Company leverages its integrated ethyleneamine chain to supply bulk corrosion inhibitor precursors to North American utilities. BASF SE anchors European supply through specialized tertiary amine production for reverse osmosis membrane cleaning.
Aliphatic amines are nitrogen-containing organic compounds derived from ammonia by replacing one or more hydrogen atoms with alkyl groups, typically manufactured via catalytic hydrogenation of nitriles or alcohol amination at 150-300°C and 10-50 bar pressure. These compounds serve as essential intermediates for surfactants, corrosion inhibitors, and agrochemical formulations across industrial and consumer applications. Primary amines occupy the largest volume share due to their versatility in downstream synthesis, while tertiary amines represent the fastest-expanding category driven by quaternization demand for personal care and water treatment biocides. Polyamines command premium pricing in epoxy curing and oilfield applications where crosslinking performance determines specification compliance.
EPA regulations under the Clean Water Act and Safe Drinking Water Act govern discharge limits for amine-containing effluents in US water treatment facilities, directly influencing product selection and dosage protocols. REACH registration requirements and the EU Green Deal's chemical sustainability targets are restricting certain ethoxylated amine chemistries while accelerating bio-based alternatives. India's BIS quality standards and CDSCO pharmaceutical-grade specifications shape import and domestic manufacturing requirements for amine producers serving regulated end uses. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as these intersect with fluorinated amine chemistries in specialty coatings and alter substitution pathways across multiple application segments.
Market Dynamics
Water treatment utilities are reconfiguring procurement priorities around corrosion inhibitor performance metrics, compressing specification cycles from multi-year frameworks to annual technical reviews.
Growth Catalysts
- REACH registration tiering:The EU Green Deal's chemical sustainability targets are accelerating substitution toward bio-based amine architectures in surfactant applications.
- Reverse osmosis membrane cleaning:Tertiary amine demand is concentrating in desalination infrastructure expansion across water-stressed coastal municipalities.
- Ethyleneamine chain integration:Captive nitrile hydrogenation capacity is insulating bulk suppliers from feedstock volatility in corrosion inhibitor precursor markets.
Market Restraints
- Ammonia feedstock exposure:Natural gas price spikes transmit directly to amine production economics, squeezing margin structures for non-integrated producers.
- Ethoxylated amine restrictions:ECHA hazard classifications are forcing reformulation of established surfactant chemistries without immediate drop-in replacements.
- Fluorinated amine substitution:PFAS restriction pathways are disrupting specialty coating segments dependent on fluorinated nitrogen chemistry.
Strategic Opportunities
- India BIS quality convergence:Domestic pharmaceutical-grade specification alignment is creating import substitution openings for local manufacturers serving CDSCO-regulated end uses.
- Quaternization biocide expansion:Personal care and institutional sanitation applications are absorbing tertiary amine derivatives at accelerated dosing rates.
- Epoxy curing polyamines:Wind turbine blade manufacturing specifications are pulling high-performance crosslinkers into renewable energy supply chains.
Industry Challenges
- Catalytic hydrogenation expertise scarcity:Nitrile-to-amine process optimization requires specialized chemical engineering talent concentrated at legacy production sites.
- Multi-jurisdictional registration timelines:Parallel EPA and REACH dossier preparation stretches regulatory affairs capacity for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aliphatic Amines Market |
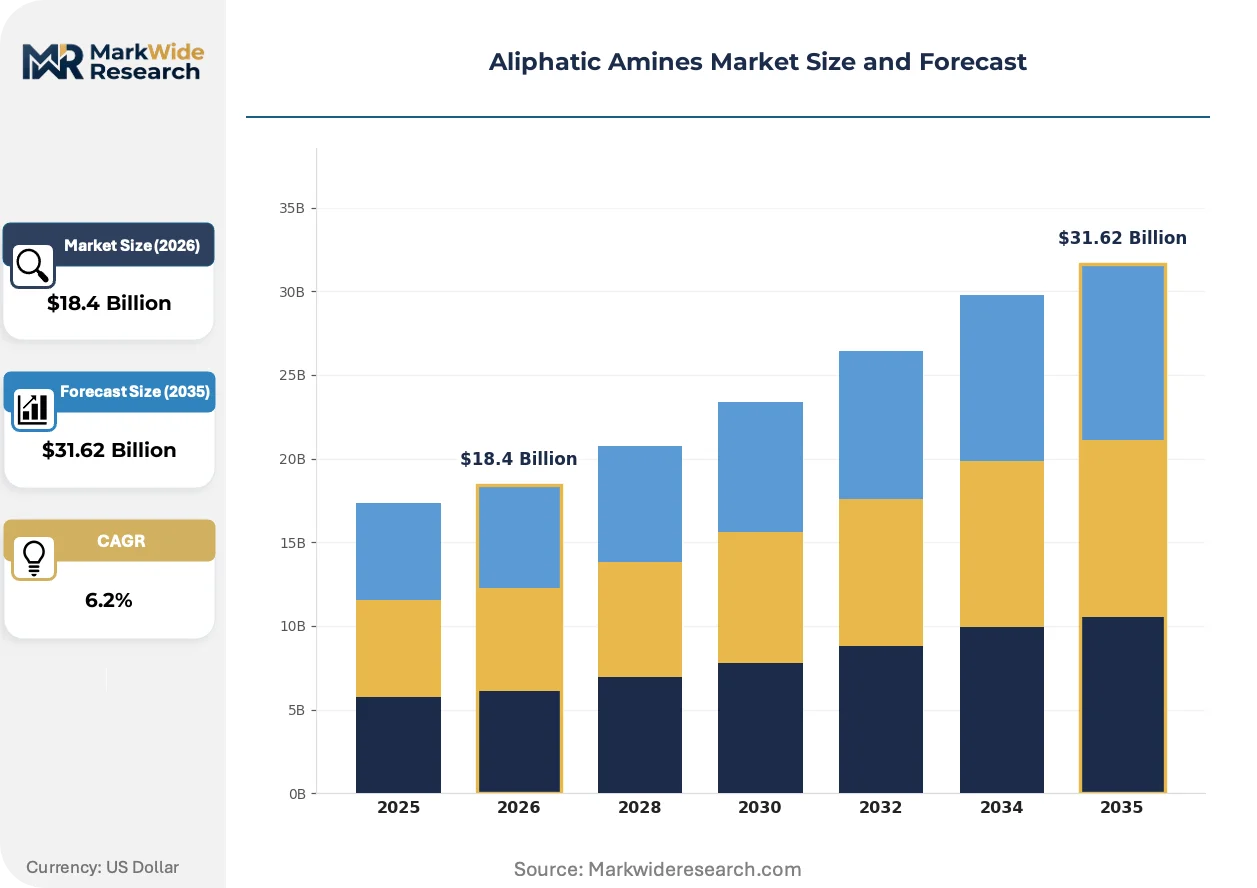
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $31.62 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Amines, Secondary Amines, Tertiary Amines, Polyamines Application: Surfactants, Corrosion Inhibitors, Agrochemicals, Adhesives End Use Industry: Pulp & Paper, Paints & Coatings, Water Treatment, Personal Care Packaging Type: Drums, IBC Totes, Bulk Tanks, Bottles |
| Companies Covered | Dow Chemical Company, Evonik Industries AG, BASF SE, Balaji Amines Ltd., Eastman Chemical Company, Huntsman Corporation, Alkyl Amines Chemicals Ltd., Solvay S.A., AkzoNobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aliphatic Amines Market Strategic Shifts & Innovations
Process intensification and regulatory chemistry are compressing traditional synthesis pathways while opening modular production architectures for distributed supply.
Continuous flow hydrogenation reactors are modularizing aliphatic amine manufacturing, enabling smaller-scale producers to achieve specification parity with integrated petrochemical complexes. Water treatment chemical distributors are piloting these units for on-site corrosion inhibitor precursor synthesis. The technology is modularizing capital deployment patterns, fragmenting historical economies-of-scale advantages held by ethyleneamine chain owners.
ECHA's restriction roadmap for ethoxylated amines under REACH is forcing surfactant formulators toward bio-based quaternary ammonium alternatives. The industrial consequence is a qualification bottleneck as personal care brands demand two-year stability data on replacement chemistries. European personal care contract manufacturers are most affected, accelerating partnerships with Indian amine suppliers holding CDSCO pharmaceutical-grade certifications.
Specification-driven procurement is consolidating buyer power among municipal water authorities running centralized chemical dosing programs. Traditional distributor networks are losing share to direct technical service contracts between amine producers and utility procurement departments. This concentration is most visible in US Great Lakes region utilities operating under combined EPA Clean Water Act and Safe Drinking Water Act compliance frameworks.
Aliphatic Amines Market Segmentation
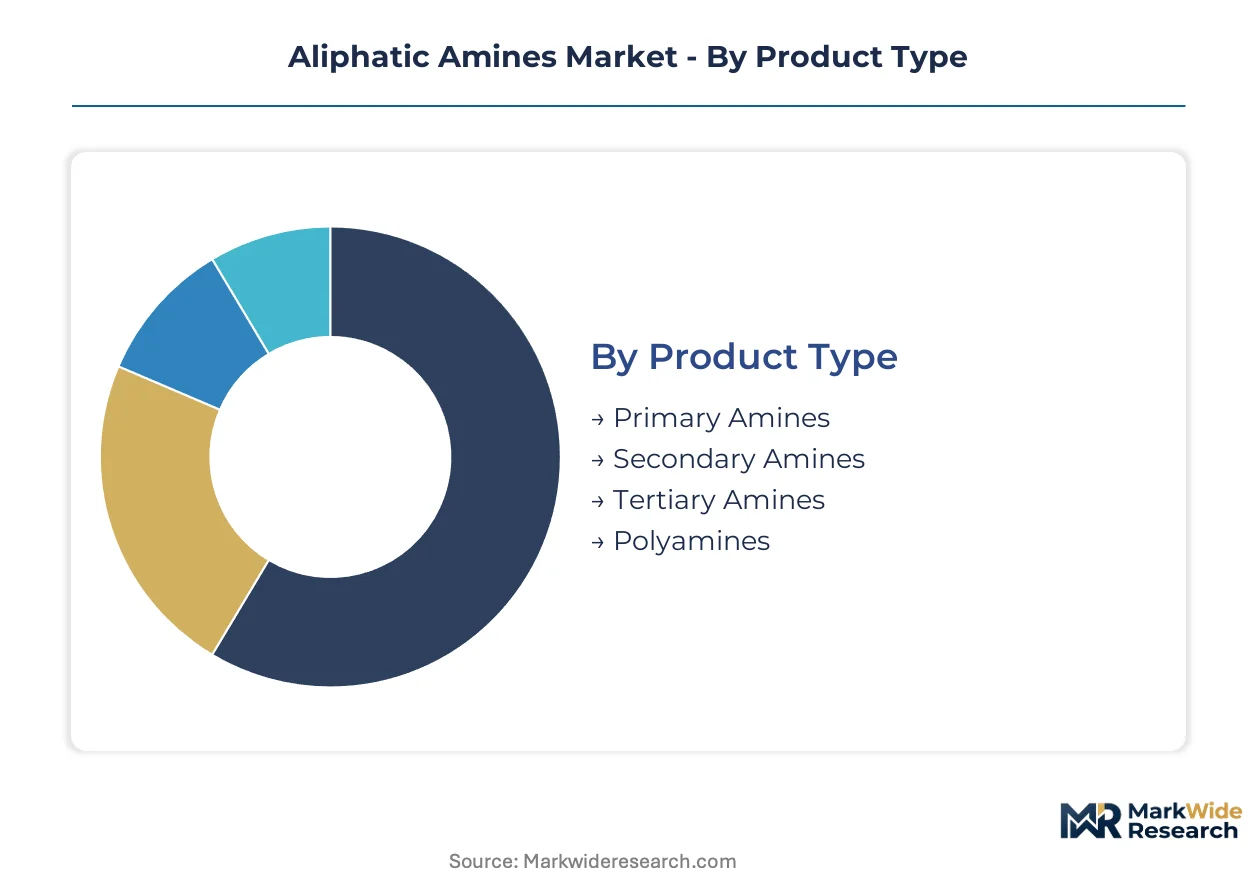
Aliphatic amine procurement decisions hinge on specification-grade requirements that vary sharply across water treatment utilities, pharmaceutical formulators, and epoxy manufacturers. Buyers prioritize hydrogenation purity tiers, molecular weight distribution, and regulatory certification status when selecting from the four core product categories.
Product Type:
Specification-grade requirements drive buyer selection across hydrogenation purity tiers and molecular weight distribution.
- Primary Amines:Single alkyl substitution on nitrogen enables versatile downstream synthesis for surfactant precursors and agrochemical intermediates. Water treatment utilities in India specify CDSCO-certified grades for corrosion inhibitor programs, compressing qualification timelines for domestic suppliers.
- Tertiary Amines:Three alkyl substitutions create quaternization-ready structures for biocide and personal care applications. Reverse osmosis membrane cleaning demand concentrates in Saudi coastal desalination plants, where SAMR-compliant tertiary amine formulations displace legacy chemistries.
- Secondary Amines:Dual alkyl substitution balances reactivity with stability for selective synthesis pathways.
- Polyamines:Multi-nitrogen architectures command crosslinking performance premiums in epoxy curing and oilfield applications.
Primary amines lead on scale; tertiary amines lead on momentum.
Application:
End-use performance thresholds determine formulation chemistry selection and supplier qualification depth.
- Corrosion Inhibitors:Amine-based film-forming compounds protect municipal water infrastructure and industrial cooling systems from oxidative degradation. EPA Clean Water Act discharge limits govern product selection at US Great Lakes utilities, forcing annual technical specification reviews.
- Surfactants:Ethoxylated amine derivatives reduce interfacial tension in industrial cleaning and personal care formulations. ECHA hazard classifications under REACH are accelerating bio-based substitution pathways for European contract manufacturers.
- Agrochemicals:Amine salts and quaternaries serve as herbicide adjuvants and fungicide active ingredients.
- Adhesives:Polyamine curing agents determine crosslink density and thermal resistance in structural bonding applications.
Corrosion inhibitors dominate volume absorption; surfactants face the steepest reformulation pressure.
End Use Industry:
Regulatory compliance frameworks segment buyer procurement authority and technical service requirements.
- Water Treatment:Municipal and industrial chemical dosing programs specify amine-based corrosion inhibitors and membrane cleaners. Centralized procurement at US utilities is consolidating supplier relationships around direct technical service contracts.
- Personal Care:Quaternary ammonium biocides and conditioning agents demand pharmaceutical-grade certification and two-year stability data. Indian CDSCO specifications are creating import substitution openings for BIS-certified domestic producers.
- Pulp & Paper:Amine-based deposit control and pitch dispersants maintain machine runnability in bleached board production.
- Paints & Coatings:Epoxy curing agents and pigment dispersants require amine functionality matched to application temperature and film thickness requirements.
Water treatment commands the largest specification volume; personal care absorbs derivatives at the fastest dosing rate expansion.
Packaging Type:
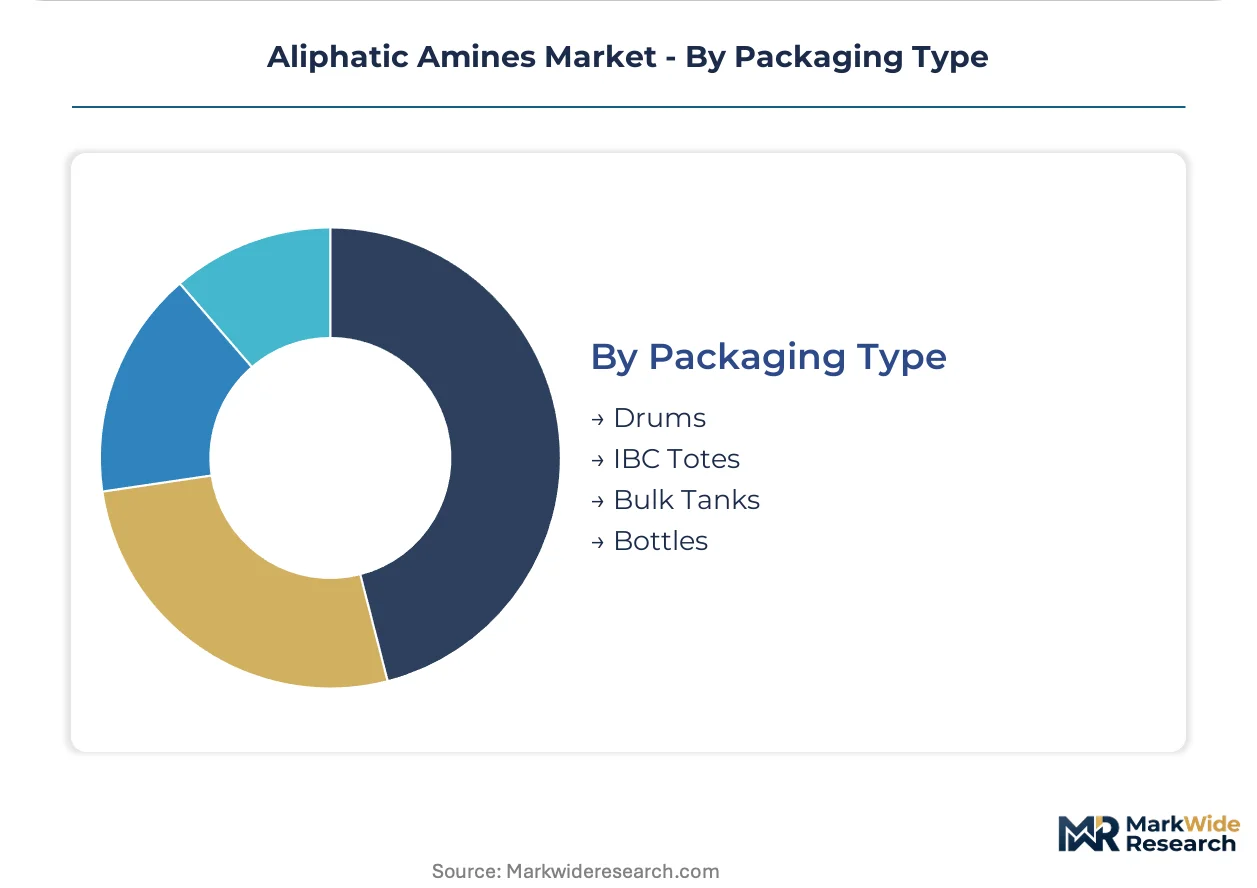
Distribution economics and handling safety protocols determine container selection across buyer scale tiers.
- Bulk Tanks:Dedicated tanker deliveries serve integrated chemical manufacturers and large water treatment utilities with continuous consumption profiles. Captive nitrile hydrogenation sites in India and the US deploy pipeline-connected bulk transfer systems.
- IBC Totes:Intermediate bulk containers balance logistics flexibility with volume efficiency for regional distributors serving mid-scale formulators. Modular flow hydrogenation units are piloting on-site IBC filling for corrosion inhibitor precursor synthesis.
- Drums:Standard 200-liter steel containers serve specialty chemical distributors and small-batch formulators requiring frequent product rotation.
- Bottles:Laboratory and pilot-scale packaging supports qualification testing and R&D sampling programs.
Bulk tanks dominate tonnage movement; IBC totes capture the fastest adoption in modular production architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling aliphatic amine production toward jurisdictions with streamlined chemical registration frameworks and lower energy input costs. Manufacturers are relocating nitrile hydrogenation capacity to exploit compliance-cost differentials between mature and emerging regulatory regimes.
United States
EPA Clean Water Act mandates at Great Lakes utilities are accelerating specification-grade corrosion inhibitor procurement. The Safe Drinking Water Act drives annual technical reviews of amine-based membrane cleaners at municipal treatment plants. Gulf Coast petrochemical clusters near Houston host integrated ethyleneamine production serving North American water treatment demand.
Germany
REACH registration tiering and EU Green Deal chemical sustainability targets are forcing surfactant-grade amine reformulation. ECHA hazard classifications for ethoxylated amines are compressing qualification timelines for bio-based alternatives. BASF SE anchors European supply through specialized tertiary amine production at Ludwigshafen.
India
BIS quality standards and CDSCO pharmaceutical-grade specifications are creating import substitution openings for domestic manufacturers. Balaji Amines and Alkyl Amines Chemicals have built substantial manufacturing footprints in Maharashtra and Gujarat. Mumbai-Pune industrial corridor producers are capturing personal care and agrochemical formulation demand across South Asia.
Saudi Arabia
SAMR-compliant tertiary amine formulations are displacing legacy chemistries in Red Sea and Arabian Gulf desalination infrastructure. The kingdom's water-stressed coastal municipalities are expanding reverse osmosis membrane cleaning programs. Jubail Industrial City hosts specialty chemical production serving regional desalination utility procurement.
China
NMPA and MIIT chemical management frameworks are tightening domestic amine production licensing. GB standards for water treatment chemicals are elevating specification requirements for corrosion inhibitor imports. Yangtze River Delta chemical clusters near Shanghai supply surfactant-grade amines to personal care contract manufacturers.
Aliphatic Amines Market Key Industry Players
Capacity expansion dominates the current landscape as producers scale nitrile hydrogenation to capture water treatment utility demand. The vendor base concentrates around three tiers: integrated petrochemical majors with captive ethyleneamine chains, regional specialists with pharmaceutical-grade certifications, and modular flow-reactor entrants piloting distributed production. Strategic archetypes include specification-grade pure-players, backward-integrated feedstock owners, and regulatory-compliance service providers. M&A activity and geographic expansion into India and Saudi Arabia represent the dominant competitive vectors.
Among integrated chemical majors, Dow Chemical Company and BASF SE exemplify the backward-integrated archetype controlling ethyleneamine chain economics. Balaji Amines Ltd. occupies a position within the India-based specialist tier leveraging BIS and CDSCO certifications for pharmaceutical-grade supply. Huntsman Corporation sits within the multinational diversified chemical group anchored by scale advantages in specialty amine derivatives.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Evonik Industries AG |
| BASF SE |
| Balaji Amines Ltd. |
| Eastman Chemical Company |
| Huntsman Corporation |
| Alkyl Amines Chemicals Ltd. |
| Solvay S.A. |
| AkzoNobel N.V. |
| Others |
Cost & Logistics Intelligence
Natural gas price benchmarks cascade through ammonia synthesis economics into aliphatic amine production tiers, compressing margins for non-integrated hydrogenation operators while concentrating pricing power with ethyleneamine chain owners. Contract-based offtake structures at Indian and US Gulf Coast production sites insulate specification-grade suppliers from spot volatility in corrosion inhibitor precursor markets.
Pricing Analysis
Distributor markups on corrosion inhibitor precursors vary by hydrogenation purity tier and CDSCO certification status. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade levels reflects downstream qualification depth. Cost compression in technical-grade segments is intensifying because ammonia feedstock volatility transmits directly to nitrile hydrogenation economics. Municipal water treatment utilities in the US Great Lakes region exhibit highest price sensitivity due to centralized procurement frameworks, while personal care formulators absorb premium pricing for BIS-certified quaternary derivatives.
Supply Chain Analysis
Empty IBC totes and spent catalyst streams flow back to Indian hydrogenation sites for reconditioning and metal recovery, closing material loops in modular production architectures. Manufacturing concentrates in India, Germany, and the United States, with Maharashtra and Gujarat hosting captive nitrile hydrogenation capacity. Production rests on ammonia, nitrile intermediates, and specialized hydrogenation catalysts as core inputs. Single-source vulnerability sits with European ethoxylated amine supply facing ECHA restriction pathways. Distribution runs through direct technical service contracts between producers and municipal utility procurement departments, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aliphatic amines function as a regulatory compounder where EPA Clean Water Act discharge mandates and REACH registration tiering continuously reshape procurement specifications and supplier qualification requirements.
For Market Incumbents: Anticipate ECHA ethoxylated amine restrictions forcing surfactant-grade reformulation by accelerating bio-based quaternary ammonium R&D partnerships. Defensive consolidation through backward integration into captive nitrile hydrogenation capacity in India or the US Gulf Coast insulates margin structures from ammonia feedstock volatility. Channel control via direct technical service contracts with municipal water utilities locks out distributor-dependent competitors. For New Entrants and Emerging Players: Begin with CDSCO pharmaceutical-grade certification pursuit to capture personal care formulation demand in India's Mumbai-Pune industrial corridor. Modular flow hydrogenation units piloting on-site corrosion inhibitor precursor synthesis represent the most penetrable white-space target. A technical service-led go-to-market angle bypasses entrenched distributor relationships at water-stressed coastal municipalities. For Investors and Strategic Acquirers: Asymmetric upside sits with India-based specialists holding dual BIS and CDSCO certifications for pharmaceutical-grade supply. Long-term viability across the analysis window hinges on regulatory compliance service capabilities rather than commodity hydrogenation scale. The signal to watch is ECHA restriction roadmap acceleration for ethoxylated amines as inflection indicator for bio-based substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrile Hydrogenation | Captive ammonia-to-amine conversion insulates Dow and BASF from feedstock volatility at Gulf Coast and Ludwigshafen sites. |
| CDSCO Pharmaceutical-Grade Certification | BIS-convergent quality standards unlock personal care formulation supply for Indian producers serving regulated end uses. |
| Modular Flow Reactor Deployment | Continuous hydrogenation units enable distributed corrosion inhibitor precursor synthesis at water treatment utility sites. |
| Bio-Based Quaternary Ammonium Development | REACH-compliant alternatives capture surfactant demand as ECHA restrictions displace legacy ethoxylated amine chemistries. |
| Direct Technical Service Contracts | US Great Lakes utilities consolidate supplier relationships around annual specification reviews under EPA compliance frameworks. |
Research Approach
Multiple input streams — primary interviews with plant managers and procurement leads at downstream water treatment utilities, technical R&D directors at surfactant formulators, and distribution channel partners — were reconciled against customs trade data, SEC 10-K filings, and Cefic industry reports. Bottom-up volume modeling across hydrogenation purity tiers and end-use industries was cross-validated through top-down triangulation with regional production capacity assessments.
Data-stream reconciliation anchored forecast outputs across the projection horizon. Segmentation dimensions modeled include amine substitution class, specification grade, end-use application, packaging format, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical volume movements adjusted for substitution dynamics and regulatory milestone impacts. Forecast inputs incorporated ammonia feedstock price trajectory assumptions and ECHA restriction timeline probabilities.
Several conditions sit outside the modeled scope, including unforeseen PFAS restriction pathways affecting fluorinated amine chemistries and abrupt natural gas supply disruptions at major hydrogenation hubs. Forecasts reflect documented assumptions about regulatory implementation pacing and feedstock cost transmission. Practitioners should monitor ECHA ethoxylated amine restriction finalization and Indian BIS standard revision cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market
Organic Chemicals
Acetylacetone Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
2,6-Dichloro Aniline Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Methyl Isobutyl Ketone (MIBK) Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
Lithium Chemicals Market
Organic Chemicals
Dimethyl Carbonate Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
North America Humic Acid Market
Organic Chemicals
Global Pseudocumene Market