
 Global Lactate Salts Market | 2026-2036
Global Lactate Salts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lactate Salts Market Foresight
Subscription-based technical service contracts for purity certification and batch-to-batch consistency monitoring is expanding as a revenue layer alongside commodity lactate salt sales. Corbion N.V. leverages its integrated fermentation platform to sustain cost advantages across calcium and sodium lactate grades. Jungbunzlauer Suisse anchors its position through pharmaceutical-grade specialization, while Dr. Paul Lohmann GmbH & Co. KGaA differentiates via custom mineral lactate formulations for niche therapeutic applications.
Lactate salts are ionic compounds formed from lactic acid neutralization with metal hydroxides or carbonates, typically produced through fermentation-derived lactic acid followed by controlled crystallization to achieve USP/EP/FCC-grade purity specifications above 99% assay. Their primary industrial purpose spans pH buffering in pharmaceutical injectables, moisture retention in processed meats, and mineral bioavailability enhancement in nutritional supplements. Sodium lactate and potassium lactate dominate food preservation applications due to their antimicrobial efficacy against Listeria and extended shelf-life performance in refrigerated proteins. Calcium lactate represents the fastest-expanding product category, driven by pharmaceutical manufacturers seeking compressible excipients for direct-tableting processes and fortification applications in functional beverages.
EMA pharmaceutical guidelines, FDA food additive regulations under 21 CFR 184, and REACH chemical registration requirements collectively govern purity thresholds, labeling protocols, and market access conditions for lactate salts across the European Union and United States. These frameworks elevate compliance costs for non-specialized producers while creating structural advantages for manufacturers with dedicated pharmacopeial certification capabilities. Stakeholders must monitor evolving EMA excipient guidelines and FDA GRAS notification pathways to anticipate qualification requirements that will determine supplier eligibility for pharmaceutical and food-grade contracts.
Market Dynamics
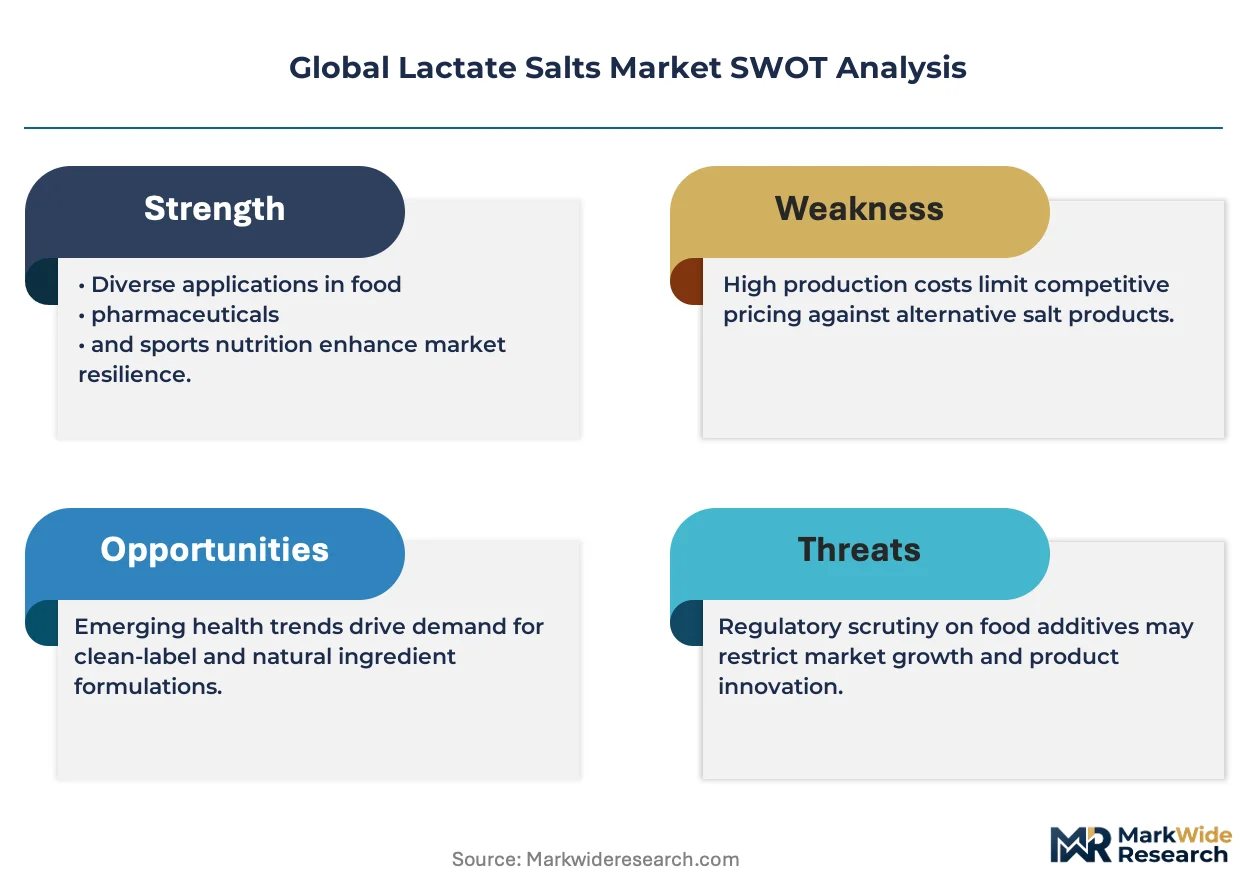
Pharmaceutical-grade purity requirements are compressing supplier margins while concentrating contract awards among fermentation-integrated producers capable of USP/EP-certified batch consistency. REACH registration costs and EMA excipient qualification timelines now function as structural filters, elevating compliance infrastructure above commodity scale in competitive positioning.
Growth Catalysts
- Controlled-release tablet demand:Pharmaceutical manufacturers in Germany and Switzerland are expanding direct-compression excipient procurement, prioritizing compressible calcium lactate grades for high-speed tableting lines.
- EU F-Gas Regulation compliance:Refrigerated protein processors face antimicrobial additive mandates, accelerating sodium lactate and potassium lactate adoption in processed meat shelf-life extension applications.
- Fermentation platform integration:Backward integration into lactic acid production is enabling cost-competitive pharmaceutical-grade supply chains for high-purity mineral lactate salts.
Market Restraints
- Feedstock volatility:Corn and sugar beet price swings directly compress fermentation economics for lactic acid precursors, squeezing lactate salt producer margins during agricultural commodity spikes.
- Supplier concentration risk:European pharmaceutical-grade production clusters in the Netherlands and Belgium create geographic vulnerability to regional energy cost shocks or logistics disruptions.
- Organic acid substitution:Citrate and acetate salts compete in pH buffering and mineral fortification applications, limiting lactate salt pricing power in cost-sensitive food additive segments.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO excipient registration pathways and domestic generic drug production growth create demand for import-substitute calcium lactate and sodium lactate supply.
- Functional beverage fortification:Bioavailable calcium lactate formats for ready-to-drink mineral enhancement represent an underdeveloped application with technical formulation support requirements.
- Subscription certification services:Batch-to-batch purity monitoring and pharmacopeial documentation packages offer recurring revenue streams beyond commodity salt volumes.
Industry Challenges
- EMA excipient qualification timelines:Master file preparation and regulatory response cycles extend 18-24 months, delaying new supplier entry into pharmaceutical contract pipelines.
- Fermentation scale-up capex:USP-grade production requires dedicated stainless-steel bioreactor trains and downstream crystallization suites with multi-year depreciation horizons.
- Cross-functional technical talent:Scarce expertise spanning fermentation microbiology, crystallization engineering, and pharmacopeial documentation limits operational expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lactate Salts Market |
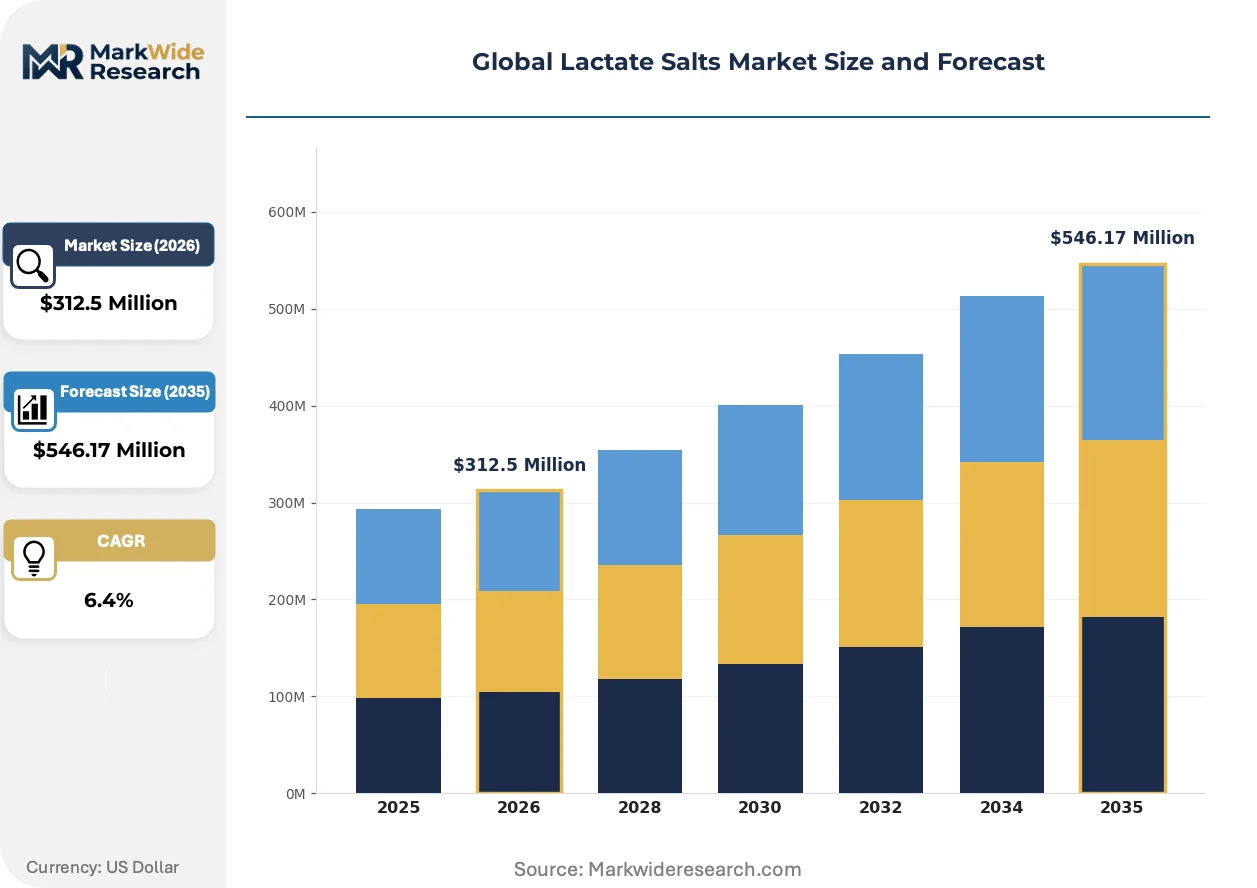
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Lactate, Sodium Lactate, Potassium Lactate, Magnesium Lactate, Ammonium Lactate Application: Food Preservation, Pharmaceutical Formulations, Cosmetic Ingredients, Animal Feed Additives, Industrial Chemicals End User: Pharmaceutical Manufacturers, Food & Beverage Producers, Cosmetic Companies, Animal Nutritionists, Chemical Suppliers Packaging Type: Bulk Bags, Paper Bags, Plastic Drums, Cartons, Bottles |
| Companies Covered | Corbion N.V., Jungbunzlauer Suisse, Henan Jindan Lactic Acid Technology, Merck KGaA, Thermo Fisher Scientific, Dr. Paul Lohmann GmbH & Co. KGaA, Galactic, FBC Industries, American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lactate Salts Market Shifts & Advancements
Continuous crystallization systems and real-time process analytical technology are compressing batch variability while enabling pharmaceutical-grade lactate salt production at commodity-equivalent unit economics.
Continuous manufacturing platforms for lactate salt crystallization are overtaking traditional batch vessel operations in new capacity investments. Pharmaceutical excipient suppliers in Germany and Switzerland are retrofitting existing plants with PAT-enabled flow chemistry systems. This technology compression is enabling real-time release testing and reducing pharmacopeial compliance costs per metric ton.
REACH registration dossier updates under the 2018-2023 substance evaluation cycle are tightening impurity specification thresholds for food-contact applications. ECHA's revised guidance on metal salt hazard classifications is forcing reformulation reviews across sodium lactate preservative blends. Processed meat processors in France and Italy are accelerating supplier audits to preempt authorization restrictions.
Technical service unbundling from product supply is restructuring buyer-supplier relationships in pharmaceutical applications. Formulation support and stability testing now frequently route through separate service contracts rather than bundled excipient procurement. This disintermediation is most advanced in Swiss and German generic drug manufacturing clusters, where quality agreement complexity favors specialized technical service providers.
Global Lactate Salts Market Segmentation
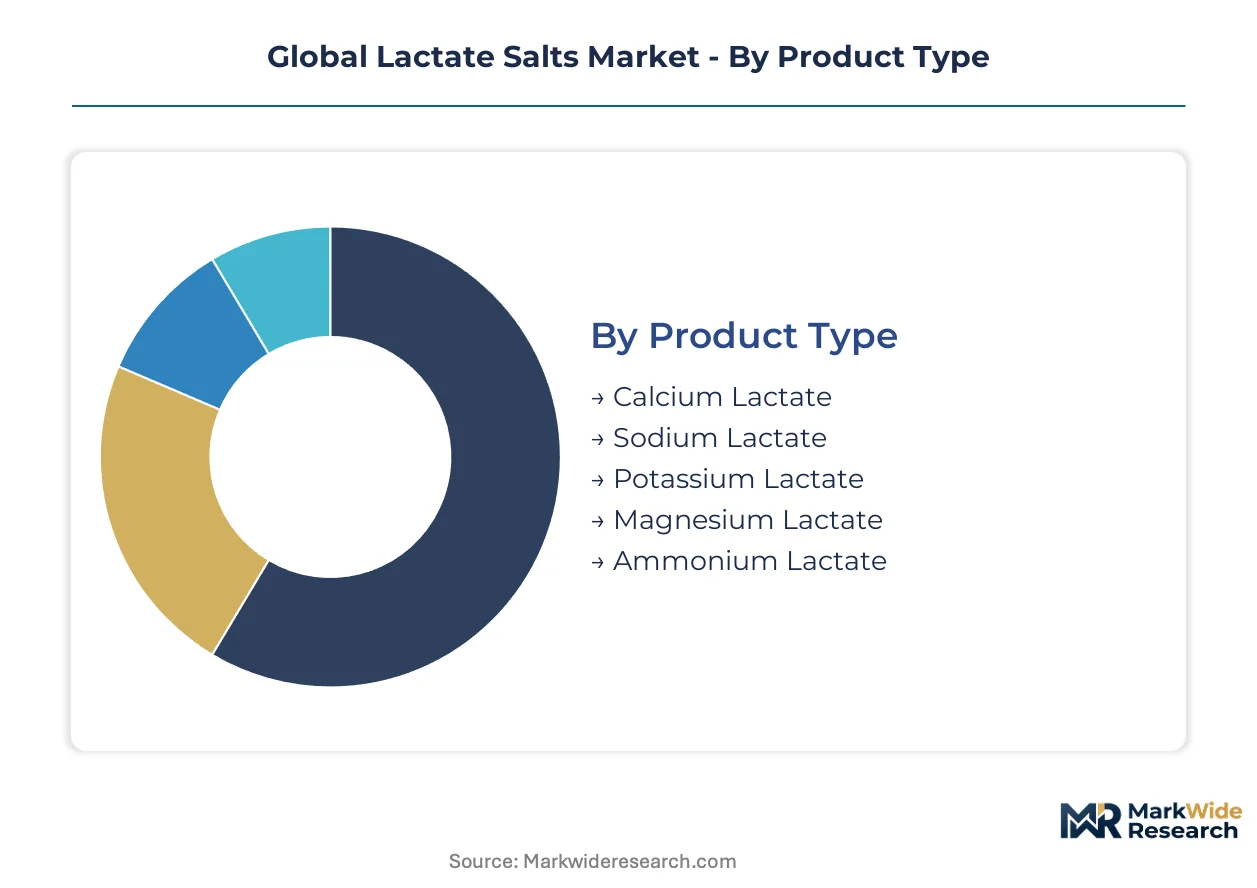
Segmentation in the lactate salts market reflects divergent purity specifications, regulatory pathways, and formulation requirements across pharmaceutical, food, and industrial end-uses. Each dimension—product chemistry, application function, customer procurement patterns, and logistics format—creates distinct margin structures and supplier qualification barriers.
Product Type:
Technical specifications around metal ion bioavailability, compressibility, and antimicrobial efficacy define competitive positioning within each salt chemistry.
- Calcium Lactate:A divalent calcium salt with superior compressibility characteristics for direct-compression tablet manufacturing. Pharmaceutical manufacturers in Germany and Switzerland prioritize this grade for high-speed tableting lines serving controlled-release formulations, though fermentation feedstock volatility constrains margin stability.
- Sodium Lactate:The monovalent sodium salt delivers potent antimicrobial efficacy against Listeria monocytogenes in refrigerated protein applications. Processed meat processors across France and Italy face EU F-Gas Regulation compliance mandates that accelerate sodium lactate adoption for shelf-life extension in vacuum-packed products.
- Potassium Lactate:Functions as a sodium-reduced alternative in clean-label meat preservation, with potassium's physiological role supporting cardiovascular positioning in functional food marketing.
- Magnesium Lactate:Targets bioavailable magnesium fortification in nutritional supplements, with solubility advantages over oxide and carbonate alternatives in beverage applications.
- Ammonium Lactate:Serves specialized industrial buffering and rare pharmaceutical applications where ammonium ion presence supports specific formulation pH targets.
Sodium lactate leads on scale; calcium lactate leads on momentum.
Application:
Regulatory jurisdiction and purity tier requirements fragment the addressable market across divergent compliance frameworks.
- Food Preservation:Antimicrobial additive deployment in processed meats, poultry, and seafood dominates volume consumption. EFSA safety evaluations and national food additive approvals under EU 1333/2008 govern sodium and potassium lactate inclusion levels in ready-to-eat proteins.
- Pharmaceutical Formulations:USP/EP-grade mineral lactate salts function as excipients, pH buffers, and active pharmaceutical ingredients. EMA excipient master file requirements and FDA Type II drug master file pathways create multi-year qualification timelines that filter supplier eligibility.
- Cosmetic Ingredients:Moisture retention and pH buffering in skincare formulations, with REACH cosmetic ingredient registration and EC 1223/2009 compliance governing market access.
- Animal Feed Additives:Mineral bioavailability enhancement in livestock and aquaculture nutrition, regulated under EU 1831/2003 feed additive authorization procedures.
- Industrial Chemicals:pH control and metal complexation in leather tanning, textile processing, and water treatment applications with lower purity thresholds.
Food preservation dominates volume throughput; pharmaceutical formulations command premium pricing tiers.
End User:
Procurement sophistication and technical service requirements stratify the customer base across certification-dependent industries.
- Pharmaceutical Manufacturers:Demand USP/EP-certified batch consistency, pharmacopeial documentation packages, and quality agreements with real-time release testing protocols. Swiss and German generic drug producers unbundle technical service contracts from commodity supply.
- Food & Beverage Producers:Prioritize antimicrobial performance validation and clean-label positioning over pharmacopeial certification, with processed meat processors driving sodium and potassium lactate volume.
- Cosmetic Companies:Require REACH-compliant safety data sheets and stability testing for formulation compatibility in emulsion systems.
- Animal Nutritionists:Specify mineral bioavailability studies and feed safety certifications under national veterinary regulations.
- Chemical Suppliers:Purchase technical-grade material for redistribution to industrial accounts with less stringent purity requirements.
Pharmaceutical manufacturers anchor premium-tier revenue; food and beverage producers generate base volume.
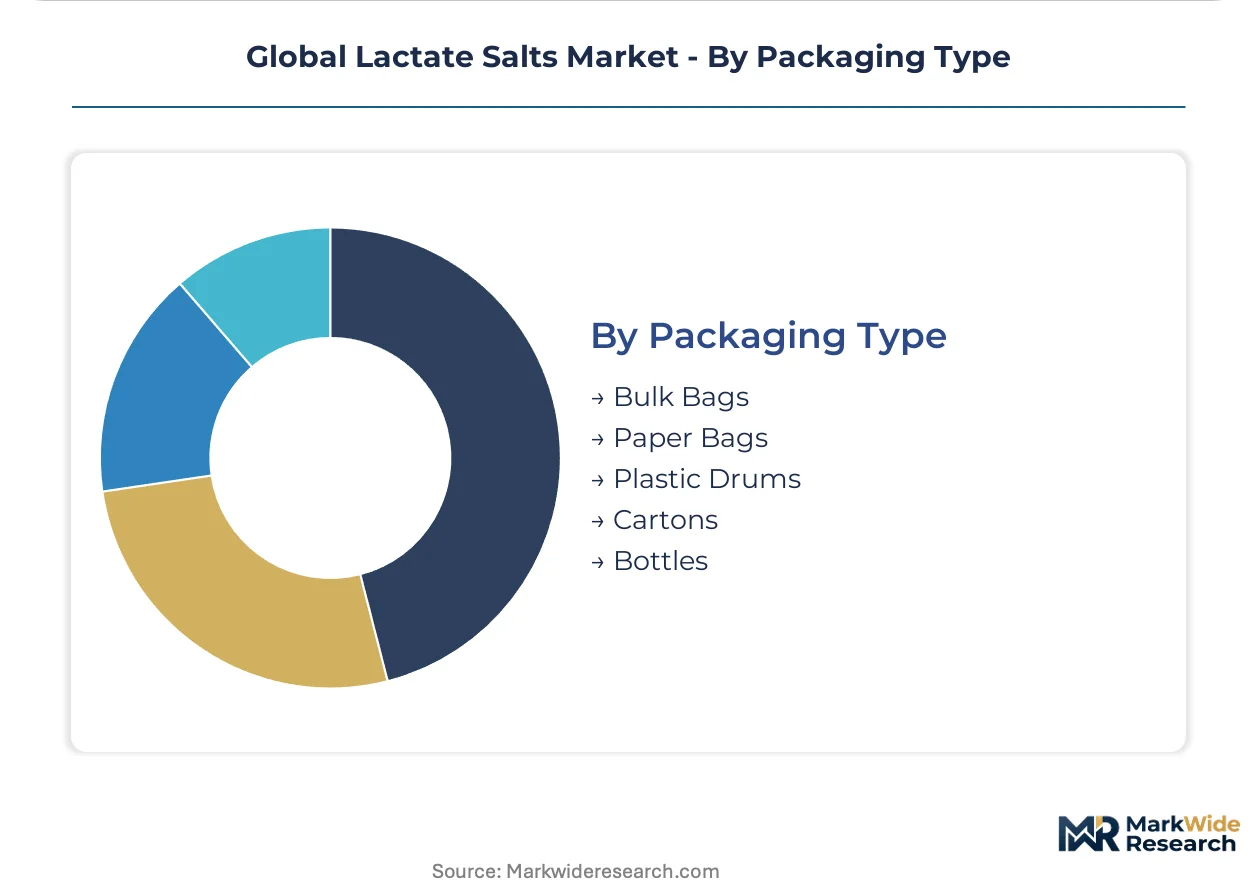
Packaging Type:
Logistics configuration and contamination risk management shape format selection across supply chain tiers.
- Bulk Bags:Flexible intermediate bulk containers for high-volume pharmaceutical and food manufacturing with dedicated silo unloading systems.
- Paper Bags:Multi-wall kraft construction for standard-grade material with moisture protection requirements in ambient distribution.
- Plastic Drums:UN-certified containment for liquid sodium lactate solutions and hygroscopic solid salts requiring humidity exclusion.
- Cartons:Retail-scale and sample quantities for cosmetic and laboratory applications with lower throughput requirements.
- Bottles:Pharmaceutical-grade packaging with tamper-evident closure systems for direct compounding use in hospital and clinical settings.
Bulk bags dominate tonnage movement; plastic drums capture liquid formulation value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pharmaceutical-grade lactate salt production capacity, while India accelerates generic drug manufacturing that demands import-substitute excipient supply chains. Regulatory frameworks diverge sharply across major markets, creating distinct compliance barriers and procurement patterns.
Germany
Pharmaceutical manufacturers in Baden-Württemberg and Bavaria expand direct-compression excipient procurement for controlled-release tablets. The German Federal Institute for Drugs and Medical Devices enforces stringent pharmacopeial documentation under EU GMP frameworks. Corbion maintains significant fermentation-integrated production near Amsterdam-Rotterdam-Antwerp corridor, supplying German generic drug clusters.
United States
Processed meat processors drive sodium lactate volume for Listeria control in refrigerated proteins. FDA food additive regulations under 21 CFR 184 govern inclusion levels and labeling protocols. Chicago-area meatpacking operations and California-based functional beverage formulators represent distinct demand poles with diverging purity requirements.
India
Domestic generic drug production growth creates demand for calcium lactate and sodium lactate excipient registration. CDSCO master file pathways and BIS quality standards filter supplier eligibility for pharmaceutical contracts. Hyderabad and Ahmedabad pharmaceutical manufacturing clusters seek import-substitute supply to reduce dependence on European imports.
Switzerland
Swissmedic excipient guidelines and quality agreement complexity favor specialized technical service providers over commodity suppliers. Basel and Zurich generic drug manufacturing clusters unbundle formulation support contracts from raw material procurement. Jungbunzlauer anchors pharmaceutical-grade specialization serving Swiss and adjacent German markets.
China
Fermentation capacity expansion targets technical-grade lactate salt exports for industrial and feed additive applications. NMPA pharmaceutical excipient registration and GB standards for food additives create dual-track regulatory compliance. Shandong Province chemical manufacturing bases concentrate bulk production with limited pharmacopeial certification penetration.
Global Lactate Salts Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade certification tiers, while regional fermentation specialists populate commodity segments. The vendor base stratifies across three tiers: fermentation-integrated multinationals with USP/EP capabilities, regional chemical processors serving food and industrial grades, and laboratory chemical distributors handling small-volume pharmaceutical orders. Two dominant competitive moves are reshaping positioning: backward integration into lactic acid fermentation to secure feedstock control, and unbundling of technical certification services from commodity salt supply.
Within the fermentation-integrated tier, Corbion N.V. and Galactic exemplify the European concentration of pharmaceutical-grade capacity. Jungbunzlauer Suisse occupies a position among Swiss-based specialists emphasizing pharmacopeial-grade purity. Dr. Paul Lohmann GmbH & Co. KGaA represents the custom mineral formulation archetype, serving niche therapeutic applications with tailored salt chemistries. These three entities collectively illustrate how geographic clustering near regulatory hubs and fermentation infrastructure creates sustainable competitive positioning.
| Leading Market Players |
|---|
| Corbion N.V. |
| Jungbunzlauer Suisse |
| Henan Jindan Lactic Acid Technology |
| Merck KGaA |
| Thermo Fisher Scientific |
| Dr. Paul Lohmann GmbH & Co. KGaA |
| Galactic |
| FBC Industries |
| American Elements |
| Others |
Supply & Pricing Matrix
Corn and sugar beet feedstock costs cascade through fermentation economics to stratify lactate salt pricing across pharmaceutical, food-grade, and industrial tiers. The Netherlands-Belgium production corridor anchors European supply, while Chinese fermentation capacity pressures technical-grade price floors in export markets.
Pricing Analysis
Capacity additions in China are reshaping price floors for technical-grade lactate salts, compressing margins for non-integrated processors. Three-tier pricing structure across USP/EP-certified pharmaceutical, FCC-grade food additive, and technical industrial levels separates buyers by purity requirements and documentation burden. Pricing pressure stems from agricultural commodity volatility and organic acid substitution threats in cost-sensitive segments. Food and beverage producers exhibit highest price sensitivity, while pharmaceutical manufacturers absorb premiums for batch consistency guarantees.
Supply Chain Analysis
Direct-to-pharmaceutical-manufacturer channels handle high-purity excipient demand with dedicated quality agreements and audit protocols. Supply concentrates in the Netherlands, Belgium, and Germany for pharmaceutical-grade material, while China dominates technical-grade fermentation capacity. Raw material dependencies include corn starch, sugar beet molasses, and fermentation nutrients. Single-source vulnerability around European pharmaceutical-grade production clusters creates exposure to regional energy cost shocks. Distribution runs through specialized chemical distributors for mid-tier food and industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Lactate Salts Market functions as a geographic-arbitrage play between European regulatory premium capture and Asian cost-base expansion, with EMA qualification timelines and REACH compliance costs creating structural margin differentials.
For Market Incumbents: Cement pharmacopeial certification moats by expanding USP/EP master file portfolios before EMA excipient guideline revisions tighten impurity thresholds. Deepen backward integration into lactic acid fermentation to neutralize corn price volatility and organic acid substitution threats in food preservative segments. For New Entrants and Emerging Players: Capture import-substitute opportunities in Indian pharmaceutical manufacturing by securing CDSCO excipient registration ahead of domestic generic drug production expansion. Target functional beverage fortification applications with bioavailable calcium lactate formats requiring technical formulation partnership rather than commodity scale. For Investors and Strategic Acquirers: Roll-up economics work for regional fermentation specialists with pharmacopeial certification gaps because EMA qualification timelines and capital intensity deter greenfield entry. Monitor CDSCO registration velocity and Indian pharmaceutical cluster capacity announcements as inflection indicators for excipient demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Corn price volatility neutralization secures margin stability for pharmaceutical-grade producers. |
| USP/EP Master File Expansion | EMA excipient qualification timelines filter competitor entry into generic drug supply chains. |
| CDSCO Registration Investment | Indian pharmaceutical cluster growth creates import-substitute revenue streams for calcium lactate. |
| Continuous Crystallization Deployment | PAT-enabled flow chemistry reduces pharmacopeial compliance costs per metric ton. |
| Technical Service Unbundling | Subscription certification contracts generate recurring revenue beyond commodity salt volumes. |
Research Methodology
Multiple input streams — fermentation technology assessments, regulatory filing databases, and excipient procurement patterns — were reconciled across primary interviews with pharmaceutical quality assurance directors, food additive procurement managers, and fermentation plant engineers, validated against secondary sources including EMA excipient guidelines, FDA Type II drug master files, EU 1333/2008 food additive registers, and trade flow data from customs authorities. Bottom-up volume modeling and top-down market sizing were triangulated to converge on segment-level estimates.
Historical shipment patterns were cross-referenced against panel input from industry participants to anchor projections across the analysis window. Segmentation dimensions modeled include salt chemistry, purity grade tier, end-use application, and regional regulatory cluster. CAGRs were derived from growth driver elasticity analysis calibrated to pharmaceutical tablet production forecasts and processed meat consumption trends. Fermentation capacity utilization rates and REACH registration status served as industry-specific forecast inputs.
Feedstock price spikes, EMA guideline revision timing, and pharmaceutical manufacturing relocation patterns are the dominant revision risks to base-case projections. Forecasts reflect assumptions about regulatory pathway stability and fermentation technology diffusion. Periodic stress-testing of base assumptions against CDSCO registration velocity and European energy cost trajectories is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Periodic Acid Market
Chemicals
Isoamyl Acetate Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Europe Biguanide Market
Chemicals
Thioacetic Acid Market
Chemicals
Nonaisoprenol Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Sodium Hydride Market
Chemicals
Ferric Phosphate Market
Chemicals
Global Amines Market
Chemicals
Aluminum Chemicals Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Desalination Chemicals Market
Chemicals
Sodium Methoxide Market
Chemicals
North America Isopropyl Alcohol Market