
 Global Methyl Methacrylate (MMA) Monomer Market | 2026-2036
Global Methyl Methacrylate (MMA) Monomer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Methyl Methacrylate (MMA) Monomer Market Foresight
The EU Green Deal is broadening the addressable market for bio-based MMA routes as European automotive OEMs impose Scope 3 emissions ceilings on transparent polymer suppliers. Mitsubishi Chemical Group leverages captive feedstock integration across Asian production nodes to sustain cost leadership in optical-grade material. Evonik Industries AG anchors its position through proprietary C4-based process technology that competes on carbon intensity metrics. BASF SE differentiates via modular production footprints that navigate regional regulatory divergence.
Methyl methacrylate monomer is an ester of methacrylic acid with methyl alcohol, characterized by a refractive index of 1.4142 and a glass transition temperature near 105 degrees Celsius when polymerized; manufacturers produce it primarily via acetone cyanohydrin or isobutylene oxidation routes for conversion into polymethyl methacrylate resins. Paints and coatings applications dominate volume consumption due to weatherability requirements in exterior architectural finishes, while optical lenses represents the fastest-growing application segment as ophthalmic demand intensifies in aging populations. Polymer grade MMA commands premium positioning over pure MMA variants because certification thresholds for medical and automotive optical use concentrate margin pools with specialized refiners.
REACH registration requirements in Europe, EPA Toxic Substances Control Act provisions in the United States, and China's GB standards administered by SAMR collectively govern monomer purity specifications, workplace exposure limits, and import documentation burdens that shape competitive access. The EU F-Gas Regulation indirectly influences MMA demand trajectories by restricting competing transparent materials in certain climate-control applications. Stakeholders must monitor regulatory divergence between acetone cyanohydrin and C4-based process classifications as carbon border adjustments mature.
Market Dynamics
Automotive lightweighting mandates in Germany and China's eastern coastal manufacturing corridor concentration are bifurcating MMA demand between optical-grade specifications and commodity architectural coatings.
Growth Catalysts
- EU Green Deal industrial emissions benchmarks:The regulation is accelerating bio-based acetone cyanohydrin route development as European automotive OEMs impose Scope 3 ceilings on transparent polymer suppliers.
- Ophthalmic lens fabrication:Aging demographics across Japan and Germany are intensifying demand for polymer-grade MMA with certified refractive stability.
- C4-based oxidation technology:Proprietary isobutylene routes are reducing carbon intensity metrics and qualifying producers for EU carbon border adjustment exemptions.
Market Restraints
- Acetone cyanohydrin feedstock volatility:Hydrogen cyanide supply concentration in China's Shandong province creates input cost instability for ACH-route producers.
- REACH registration documentation burdens:ECHA's monomer purity specifications and exposure limit protocols extend import clearance timelines for non-EU suppliers.
- Polycarbonate substitution in climate-control glazing:EU F-Gas Regulation restrictions on competing transparent materials only partially offset polycarbonate's cost advantage in automotive HVAC components.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic MMA capacity expansion under the production-linked incentive framework addresses import dependence for PMMA sheet fabrication.
- Medical device optical certification:ISO 10993 biocompatibility standards for intraocular lenses create premium positioning for polymer-grade refiners with dedicated clean-room production nodes.
- Direct-to-fabricator digital procurement platforms:B2B marketplace adoption among Chinese architectural glazing contractors is compressing distributor margins and enabling spot-price transparency.
Industry Challenges
- Process technology talent scarcity:C4 oxidation catalyst optimization and ACH route cyanide handling protocols require specialized chemical engineering expertise concentrated at legacy European and Japanese production sites.
- Multi-jurisdiction certification synchronization:FDA 21 CFR compliance for medical optical applications, EPA TSCA workplace exposure documentation, and SAMR GB standards for China imports create overlapping compliance timelines.
- Legacy acetone cyanohydrin asset retrofit complexity:Existing European production facilities face capex-intensive hydrogen cyanide recovery system upgrades to meet EU Industrial Emissions Directive benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Methyl Methacrylate (MMA) Monomer Market |
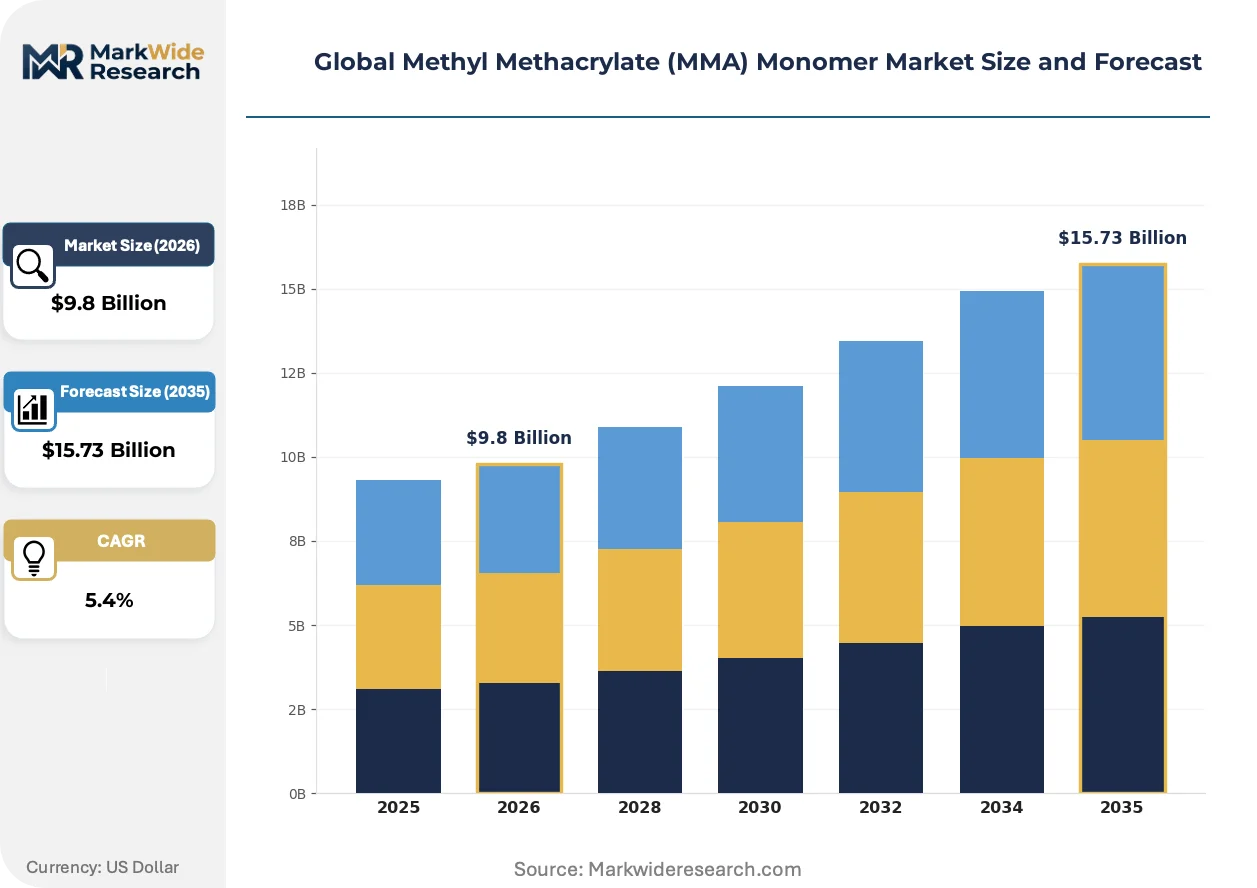
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure MMA, Stabilized MMA, Copolymer MMA, Polymer Grade MMA Application: Adhesives & Sealants, Automotive Components, Paints & Coatings, Electronic Encapsulation, Optical Lenses End User Industry: Construction Manufacturers, Consumer Electronics Producers, Packaging Suppliers, Transportation Fabricators, Appliance Makers Distribution Channel: Direct Sales, Distributors, Online Platforms, Industrial Suppliers |
| Companies Covered | Mitsubishi Chemical Group, Kuraray Co. Ltd., BASF SE, Trinseo PLC, Sumitomo Chemical Co. Ltd., Evonik Industries AG, Dow Chemical Co., Asahi Kasei Corp, Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Methyl Methacrylate (MMA) Monomer Market Shifts & Advancements
Process automation and carbon accounting integration are reconfiguring competitive advantage away from feedstock access toward operational precision and regulatory pre-certification.
Continuous-flow reactor technology for C4-based MMA synthesis is automating temperature and pressure control sequences that previously required manual intervention. German automotive glazing suppliers are adopting this automation for just-in-time optical-grade deliveries. The technology is compressing batch-to-batch variability and reducing off-spec material penalties in long-term supply agreements.
EU CSRD sustainability reporting mandates now require Scope 3 emissions disclosure from transparent polymer suppliers to automotive OEMs. This disclosure obligation is forcing acetone cyanohydrin route producers to document cradle-to-gate carbon intensity or risk contract non-renewal. Optical lens fabricators in Italy and France are prioritizing C4-based material with verified lifecycle data.
Consolidated procurement consortia among Chinese architectural coatings manufacturers are replacing fragmented spot-market purchasing. These buying groups negotiate annual volume commitments directly with integrated producers, bypassing traditional distributor networks. The shift is most visible in Jiangsu and Zhejiang provinces where exterior finish demand concentrates.
Global Methyl Methacrylate (MMA) Monomer Market Segmentation
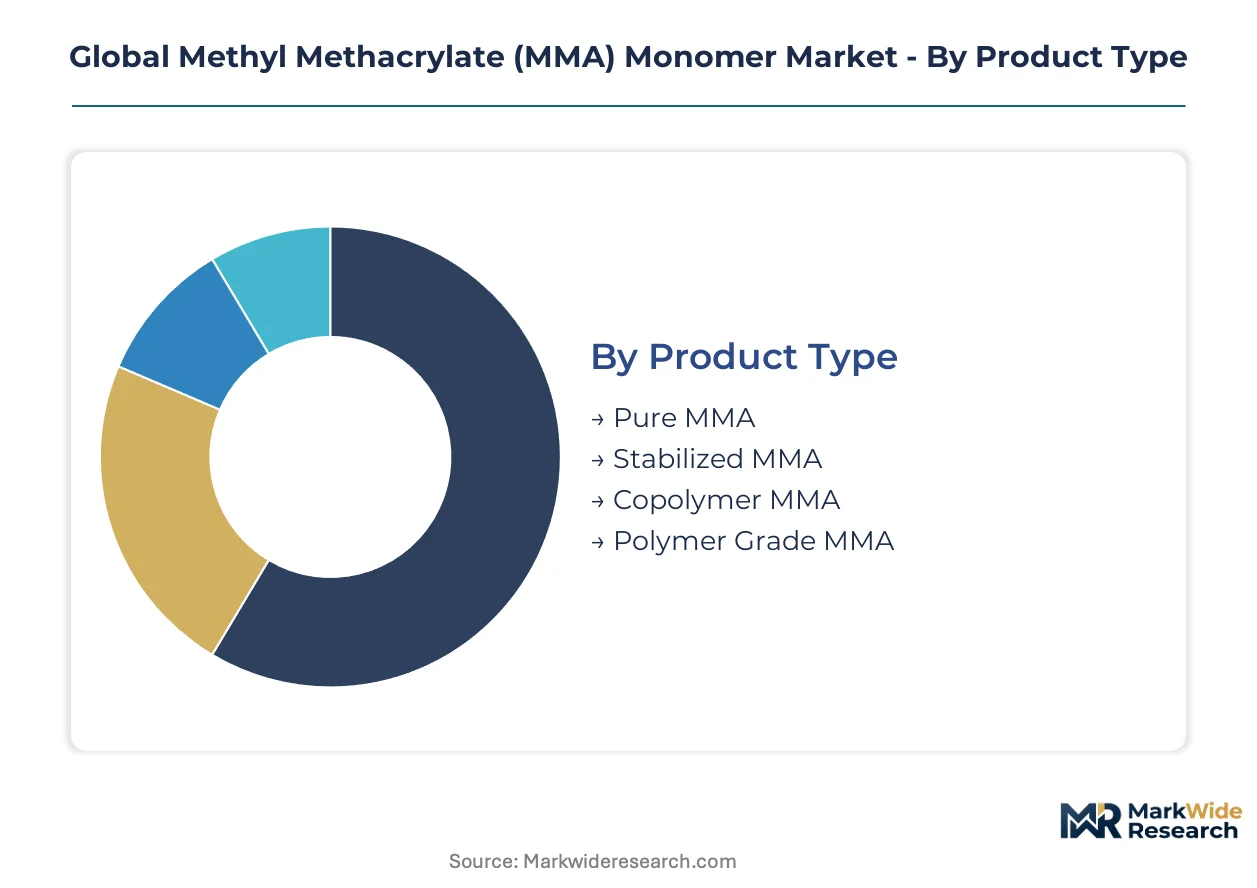
Segmentation in MMA monomer markets separates high-purity optical specifications from commodity architectural grades, with capital requirements varying tenfold between polymer-grade clean-room refineries and standard ACH-route facilities. Producers allocate capacity across these tiers based on long-term supply agreements with automotive and medical OEMs.
Product Type:
Capital intensity diverges sharply across these grades, with polymer-grade MMA requiring dedicated hydrogen cyanide recovery systems and pharmaceutical-certification infrastructure that multiplies upfront investment.
- Polymer Grade MMA:Ultra-high purity specifications with refractive index tolerance below 0.0005 and sub-ppm metal ion content for optical lens fabrication. Demand concentrates in Germany's automotive glazing corridor and Japan's ophthalmic device clusters, where OEMs mandate ISO 10993 biocompatibility documentation and batch-level carbon intensity disclosure.
- Pure MMA:Standard monomer with 99.8% minimum purity for general-purpose PMMA extrusion and casting. Chinese construction material fabricators in Jiangsu province absorb the bulk of spot-market volume, though price volatility from acetone cyanohydrin feedstock swings constrains margin stability.
- Stabilized MMA:Hydroquinone or phenothiazine-inhibited variant for extended storage and railcar shipment.
- Copolymer MMA:Pre-formulated blend with methyl acrylate or butyl methacrylate comonomers for modified impact resistance.
Polymer Grade MMA absorbs the bulk of installed capacity expansion capex; Pure MMA is expanding most quickly in China's coastal manufacturing corridor.
Application:
Application mix determines customer concentration risk, with long-term optical supply agreements contrasting against fragmented spot purchasing in architectural coatings.
- Optical Lenses:Precision-molded ophthalmic and automotive glazing requiring certified refractive stability across temperature cycling. Aging demographics in Japan and Germany are intensifying fabrication demand, while EU CSRD mandates force lens manufacturers to document cradle-to-gate emissions from monomer suppliers.
- Paints & Coatings:Exterior architectural finishes leveraging PMMA weatherability against UV degradation and salt corrosion. China's eastern coastal manufacturing corridor dominates volume consumption, with consolidated procurement consortia in Jiangsu and Zhejiang provinces replacing fragmented distributor purchasing.
- Automotive Components:Lightweight transparent panels and interior trim for fuel efficiency compliance.
- Adhesives & Sealants:Reactive acrylic systems for structural bonding in transportation assembly.
- Electronic Encapsulation:Low-outgassing potting compounds for LED and display manufacturing.
Paints & Coatings commands the widest producer participation; Optical Lenses shows the steepest expansion trajectory as medical device certification requirements deepen.
End User Industry:
End user concentration shapes contract structures, with transportation fabricators negotiating multi-year optical-grade commitments while construction manufacturers purchase on quarterly price formulas.
- Transportation Fabricators:German automotive OEMs and Chinese EV manufacturers specifying transparent polymer for lightweighting programs. KBA certification requirements and Scope 3 emissions ceilings imposed by Volkswagen, BMW, and Mercedes-Benz parent companies are disqualifying acetone cyanohydrin route suppliers without verified lifecycle data.
- Construction Manufacturers:Architectural glazing and exterior finish producers across China's coastal provinces and India's western industrial belt. India's PLI scheme for specialty chemicals is accelerating domestic PMMA sheet fabrication capacity to reduce import dependence from Mitsubishi Chemical Group's Singapore and Thai production nodes.
- Consumer Electronics Producers:Display cover lenses and light-guide plates for smartphone and tablet assembly.
- Packaging Suppliers:Premium cosmetic and pharmaceutical containers requiring clarity and chemical resistance.
- Appliance Makers:Refrigerator door panels and lighting diffusers for premium white goods.
Transportation Fabricators anchor long-term contract volumes; Construction Manufacturers show the fastest spot-market growth as China's real estate completion rates recover.
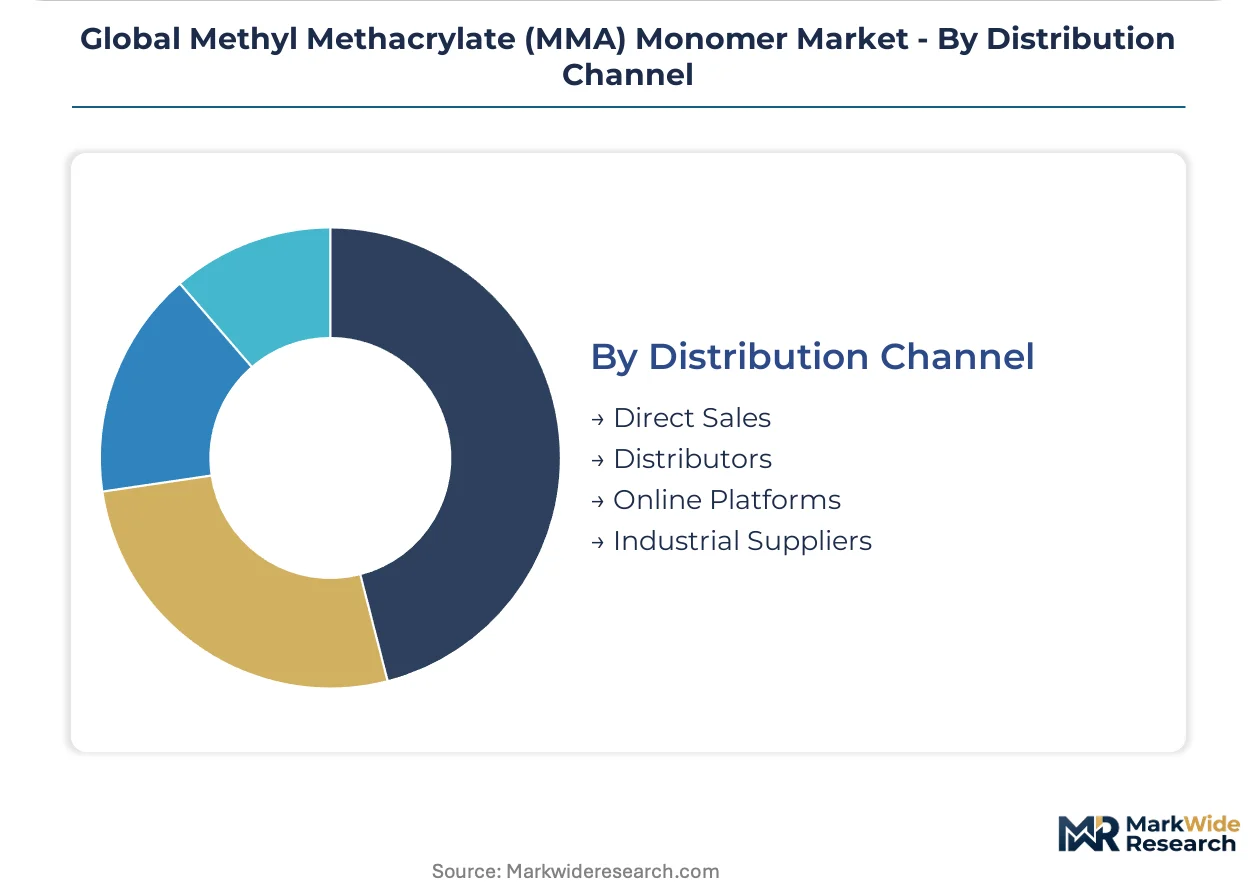
Distribution Channel:
Channel selection reflects buyer sophistication, with direct sales dominating certified optical grades while industrial suppliers aggregate fragmented architectural demand.
- Direct Sales:Long-term supply agreements between integrated producers and automotive OEMs, optical lens fabricators, and medical device manufacturers. BASF SE and Evonik Industries AG leverage these relationships to secure just-in-time delivery schedules with batch-level quality documentation.
- Distributors:Regional chemical distributors holding inventory for small-batch architectural coatings manufacturers and adhesive compounders. REACH registration documentation burdens and ECHA monomer purity specifications extend import clearance timelines, favoring EU-based distributors with established compliance infrastructure.
- Industrial Suppliers:Consolidated procurement platforms serving maintenance-repair-operations demand.
- Online Platforms:Emerging B2B marketplaces among Chinese architectural glazing contractors compressing traditional distributor margins.
Direct Sales captures the highest value per ton; Online Platforms are gaining share fastest in China's spot-market procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern coastal manufacturing corridor dominates global MMA consumption, with Jiangsu and Zhejiang provinces anchoring architectural coatings demand while Shanghai's automotive glazing cluster drives optical-grade specifications.
China
Shandong province concentrates hydrogen cyanide feedstock supply for acetone cyanohydrin route producers, creating input cost volatility that ripples through spot markets. SAMR's GB standards for monomer purity and import documentation enforce strict compliance timelines for foreign suppliers. Consolidated procurement consortia in Jiangsu province now negotiate directly with integrated producers, bypassing traditional distributor networks.
Germany
Volkswagen, BMW, and Mercedes-Benz parent companies impose Scope 3 emissions ceilings on transparent polymer suppliers, disqualifying acetone cyanohydrin route producers without verified lifecycle data. KBA certification requirements for automotive glazing materials enforce batch-level quality documentation. The automotive glazing corridor stretching from Stuttgart to Munich anchors premium optical-grade demand.
United States
EPA Toxic Substances Control Act provisions govern workplace exposure limits and import documentation burdens for monomer shipments. Construction material fabricators in Texas and Louisiana absorb commodity-grade volume for architectural finishes. The Gulf Coast petrochemical corridor sustains feedstock integration advantages for C4-based oxidation route economics.
Japan
Aging demographics intensify ophthalmic lens fabrication demand, with polymer-grade MMA requiring certified refractive stability across temperature cycling. METI's industrial emissions benchmarks shape process technology investment decisions. The Kansai region's optical device manufacturing cluster around Osaka prioritizes suppliers with ISO 10993 biocompatibility documentation.
India
The PLI scheme for specialty chemicals accelerates domestic PMMA sheet fabrication capacity to reduce import dependence from Singapore and Thai production nodes. CDSCO's medical device regulations govern intraocular lens material certification requirements. Gujarat's western industrial belt concentrates new capacity expansion under the production-linked incentive framework.
Global Methyl Methacrylate (MMA) Monomer Market Competitive Landscape
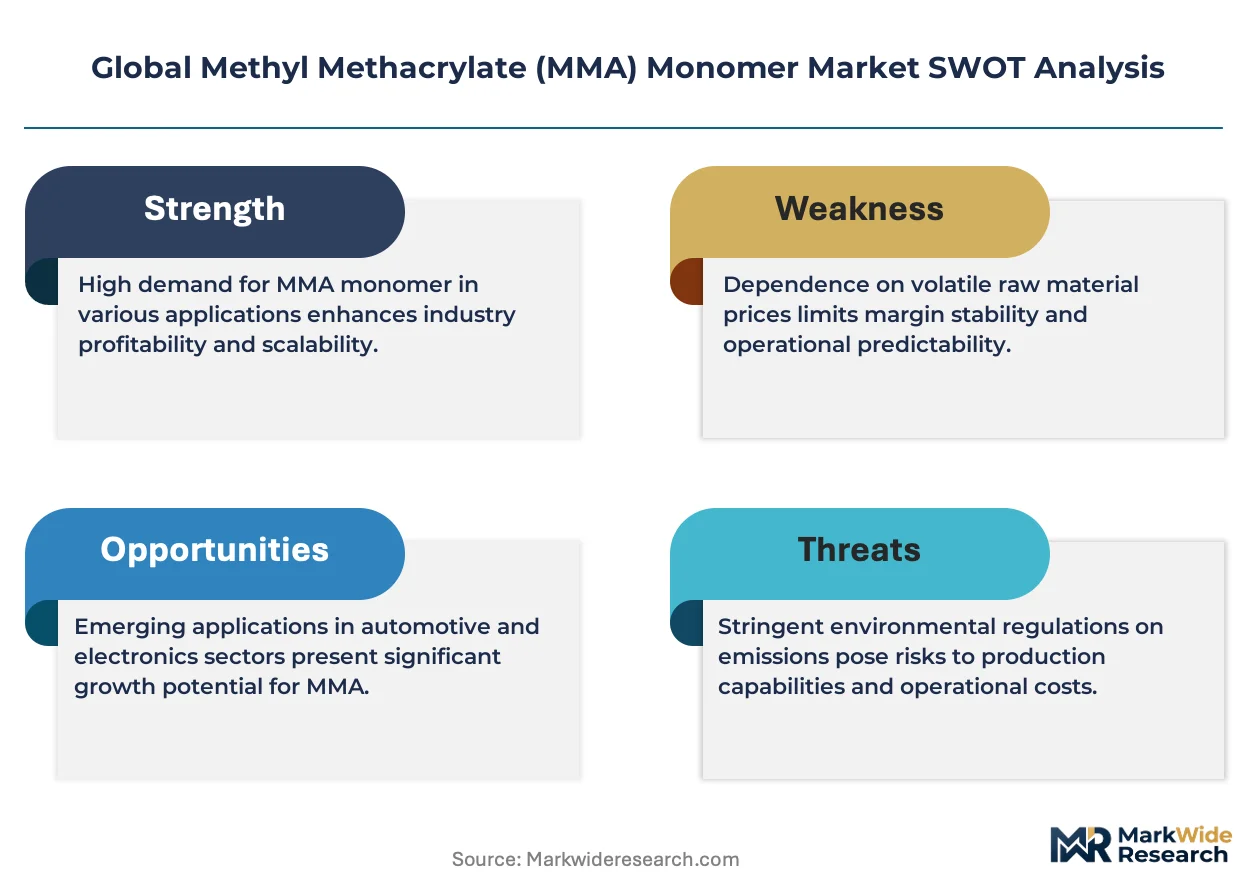
Premium-margin players sit above commodity-margin players across certification-grade and carbon-intensity dimensions, with polymer-grade optical specifications commanding tenfold capital intensity premiums over standard ACH-route facilities. The market structures around three archetypes: integrated chemical conglomerates with captive feedstock control, specialized refiners with pharmaceutical-certification infrastructure, and regional commodity producers serving spot architectural demand. Dominant competitive moves include backward integration into hydrogen cyanide or isobutylene feedstock and technology licensing for C4-based oxidation routes.
Among Japanese chemical conglomerates, Mitsubishi Chemical Group and Sumitomo Chemical Co. Ltd. exemplify integrated producers with Asian production node networks. German specialty chemical players including BASF SE and Evonik Industries AG occupy positions defined by modular production footprints and proprietary process technology. Trinseo PLC represents the mid-scale specialist archetype with focused PMMA downstream integration. These named entities anchor the competitive structure without exhaustively mapping strategic positioning across all market tiers.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| Kuraray Co. Ltd. |
| BASF SE |
| Trinseo PLC |
| Sumitomo Chemical Co. Ltd. |
| Evonik Industries AG |
| Dow Chemical Co. |
| Asahi Kasei Corp |
| Arkema Group |
| Others |
Supply & Pricing Matrix
Hydrogen cyanide feedstock costs in China's Shandong province cascade through acetone cyanohydrin route economics, compressing margins for commodity-grade producers while C4-based oxidation technology commands premium positioning in German automotive supply chains.
Pricing Analysis
Yield-based pricing anchors optical-grade MMA contracts, with polymer-grade specifications tying contract values to certified refractive stability outcomes in ophthalmic lens fabrication. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical material from construction-grade spot volumes. Pricing pressure stems from polycarbonate substitution in automotive climate-control glazing, where cost advantages displace PMMA despite EU F-Gas Regulation restrictions. Chinese architectural coatings manufacturers in Jiangsu province exhibit highest price sensitivity through consolidated procurement consortia, while German automotive OEMs prioritize carbon intensity documentation over unit cost.
Supply Chain Analysis
Specialized chemical engineering talent scarcity in legacy European and Japanese production sites constrains C4 oxidation catalyst optimization and cyanide handling protocol expansion. Supply concentration centers on China for hydrogen cyanide feedstock, Germany for optical-grade refinement, and the US Gulf Coast for isobutylene integration. Raw material dependencies draw from acetone cyanohydrin routes, isobutylene oxidation feedstocks, and pharmaceutical-certification infrastructure. Single-source vulnerability in Shandong province hydrogen cyanide supply creates input cost instability rippling through spot markets. Distribution runs through direct sales for certified optical grades and B2B platforms compressing margins in Chinese architectural procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over hydrogen cyanide or isobutylene feedstock separates margin sustainability from commodity volatility.
For Market Incumbents: Anchor long-term contract renewal through Scope 3 emissions documentation that satisfies Volkswagen, BMW, and Mercedes-Benz parent company requirements. Retrofit legacy acetone cyanohydrin assets with hydrogen cyanide recovery systems to meet EU Industrial Emissions Directive benchmarks. Deepen upstream control over isobutylene supply in the US Gulf Coast petrochemical corridor to defend against C4-based oxidation route competitors. For New Entrants and Emerging Players: Premium-to-economy price-point gaps in India's PMMA sheet fabrication market offer white-space entry under the PLI scheme for specialty chemicals. Target Gujarat's western industrial belt where domestic capacity expansion reduces import dependence from Singapore and Thai production nodes. Pursue ISO 10993 biocompatibility certification for intraocular lens material to access medical device premium positioning. For Investors and Strategic Acquirers: EU CSRD sustainability reporting mandates requiring Scope 3 disclosure from automotive OEMs is the leading indicator that carbon intensity verification infrastructure will determine supplier viability. Frame long-term positioning around producers with verified lifecycle data and clean-room polymer-grade refinement capabilities. Monitor KBA certification timelines for automotive glazing materials as inflection signals for contract renewal velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Cyanide | Captive feedstock supply insulates acetone cyanohydrin route producers from Shandong province price volatility. |
| C4-Based Oxidation Technology Licensing | Proprietary isobutylene routes qualify producers for EU carbon border adjustment exemptions. |
| Clean-Room Polymer-Grade Capacity Expansion | ISO 10993 certification infrastructure captures medical optical premium margins in Japan and Germany. |
| Direct-to-Fabricator Digital Platforms | B2B marketplace adoption among Chinese architectural glazing contractors compresses traditional distributor margins. |
| Long-Term Supply Agreements with Automotive OEMs | Scope 3 emissions documentation secures multi-year optical-grade commitments from German manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with plant managers, procurement leads at downstream automotive OEMs, distribution channel partners, and technical R&D directors provided operational validation. SEC 10-K filings, Cefic sector reports, SAMR GB standard documentation, and ECHA REACH registration databases supplied quantitative foundations. Bottom-up capacity modeling and top-down demand segmentation were cross-referenced for triangulation.
Segmentation granularity operated at grade tier, end-use industry, and regional production hub levels across the analysis window. CAGRs were derived from production capacity expansion schedules, demand elasticity by application, and feedstock cost trajectory modeling. Forecast inputs incorporated automotive lightweighting program timelines, ophthalmic demographic projections, and regulatory compliance cost burdens.
Inputs from ECHA registration databases and SAMR import documentation were available through the study window; gaps in real-time hydrogen cyanide spot pricing introduce uncertainty bands around acetone cyanohydrin route margin projections. Forecasts reflect assumptions regarding EU carbon border adjustment implementation and China dual carbon goal enforcement. Material deviation in KBA certification timelines or PLI scheme disbursement velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Acetic Anhydride Market
Chemicals
Ferric Oxide Market
Chemicals
Global Pine Chemicals Market
Chemicals
6 Hexanediol Market
Chemicals
Carcinogenic Chemical Alternatives Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
White Phosphorus Market
Chemicals
3-Iodoaniline Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Global Fluorosilicic Acid Market
Chemicals
Azodicarbonamide (ADC) Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Germany Methanol Market
Chemicals
Aluminum Phosphide Market
Chemicals
Laboratory Chemical Reagents Market