
 Europe Fluorosilicic Acid Market | 2026-2036
Europe Fluorosilicic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fluorosilicic Acid Market Intelligence
Phosphoric acid is consolidating its role as a partial substitute in certain fertilizer blending operations, narrowing the price premium that fluorosilicic acid historically commanded in agricultural applications. Solvay leverages its integrated fluorochemical platform to sustain feedstock security across Belgian and French production nodes. IXOM Limited anchors its competitiveness through specialized bulk logistics capabilities that serve Scandinavian municipal water authorities. Honeywell International differentiates via technical-grade purification protocols that meet stringent semiconductor etching specifications.
Fluorosilicic acid is an inorganic compound with the formula H2SiF6, typically supplied as a 20-25% aqueous solution derived from phosphate fertilizer production off-gas scrubbing; it functions primarily as a fluorine source for water fluoridation, metal surface treatment, and fluorosilicate salt manufacturing. Industrial grade material dominates volume flows into European municipal water treatment networks, where long-term tender structures create sticky supplier relationships. Chemical synthesis applications represent the fastest-expanding demand pool, driven by fluorochemical intermediate requirements for battery electrolytes and pharmaceutical active ingredients. Food grade and pharmaceutical grade categories command substantially wider margins, though their volumes remain constrained by batch certification cycles and EFSA purity benchmarks.
REACH registration obligations and the EU F-Gas Regulation impose escalating compliance burdens on fluorosilicic acid importers and blenders, effectively filtering smaller traders from formal supply chains. ECHA classification procedures for fluorinated substances are extending hazard documentation requirements, pushing downstream users toward pre-certified suppliers with established dossier management. Municipal procurement officers and chemical distributors must monitor evolving substance restriction proposals under the EU Green Deal chemicals strategy, as precursor controls could reshape domestic manufacturing economics and import dependency ratios.
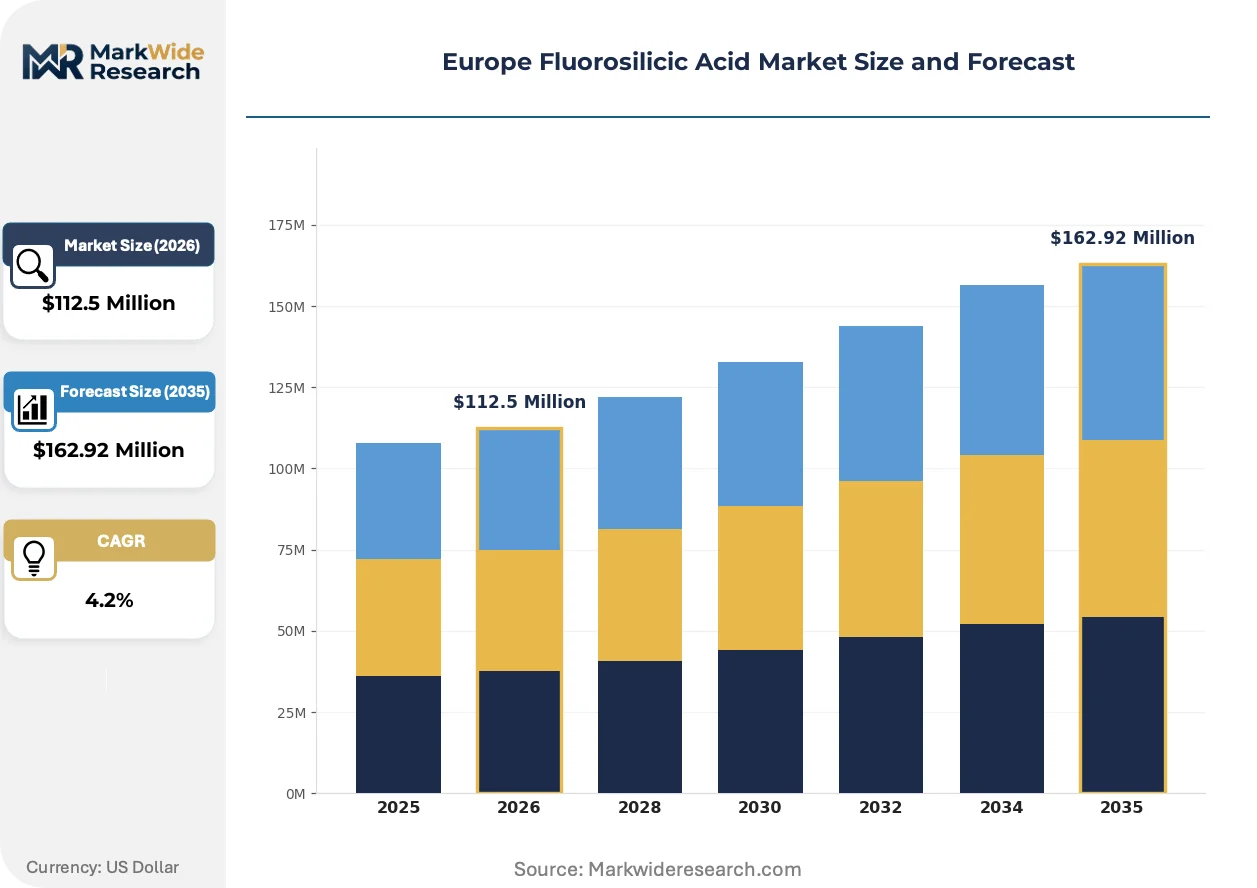
Market Dynamics
Municipal water fluoridation mandates across Germany and France are tightening feedstock qualification standards, forcing suppliers to consolidate certification documentation and lock in multi-year service contracts with utilities.
Growth Catalysts
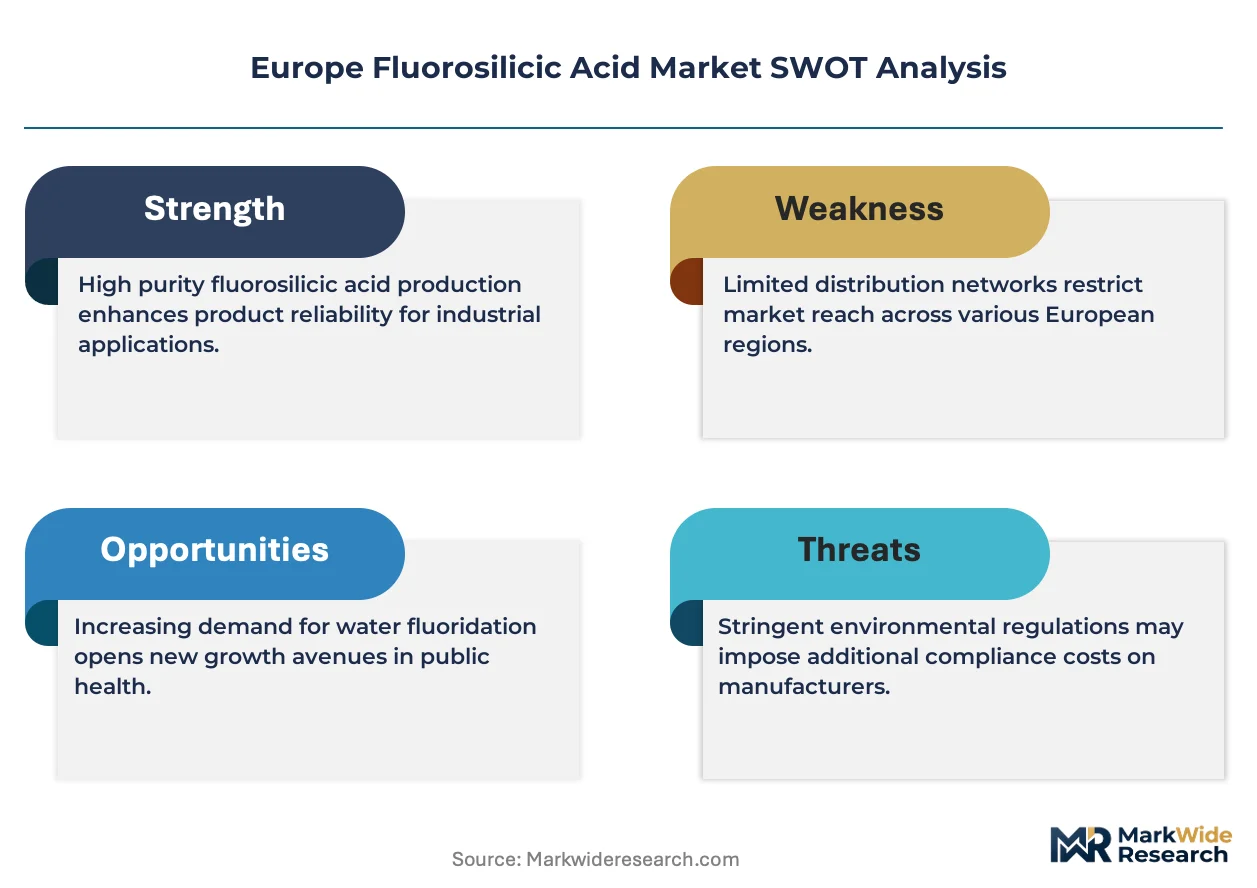
- REACH registration tiers:ECHA's updated dossier requirements for fluorinated substances are filtering out informal traders and formalizing procurement channels for certified industrial-grade suppliers.
- Battery electrolyte intermediates:Fluorochemical precursor demand from lithium-ion manufacturing is redirecting acid volumes toward chemical synthesis applications.
- Scandinavian tender structures:Long-term municipal contracts in Sweden and Norway are creating sticky supplier relationships with minimum volume guarantees.
Market Restraints
- Phosphoric acid substitution:Fertilizer blenders in Eastern Europe are partially displacing fluorosilicic acid with cheaper phosphate alternatives, compressing agricultural margins.
- Belgian production concentration:Feedstock security depends on a narrow corridor of phosphate fertilizer off-gas capture facilities near Antwerp.
- F-Gas Regulation compliance costs:EU obligations on fluorinated substance reporting are elevating operational overhead for importers and regional blenders.
Strategic Opportunities
- Semiconductor etching specifications:Technical-grade purification protocols for wafer surface treatment command substantial premiums over industrial-grade material.
- EFSA pharmaceutical benchmarks:Batch certification cycles for food-grade and pharmaceutical-grade categories create defensible margin pools for qualified producers.
- EU Green Deal chemicals strategy:Precursor control proposals under the chemicals sustainability agenda could reshape import dependency ratios for domestic manufacturers.
Industry Challenges
- ECHA hazard documentation:Extended classification procedures for fluorinated substances are stretching technical staff capacity at smaller formulation houses.
- Legacy logistics infrastructure:Specialized bulk transport capabilities for corrosive aqueous solutions require capital-intensive tanker fleet upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fluorosilicic Acid Market |
| Market Size in 2026 | $112.5 Million |
| Market Size in 2035 | $162.92 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Technical Grade Application: Water Treatment, Fertilizers, Glass Manufacturing, Chemical Synthesis End User: Municipalities, Agriculture, Chemical Industry, Construction Packaging Type: Drums, IBC Tanks, Bags, Bulk |
| Companies Covered | Solvay, IXOM Limited, Honeywell International, The Mosaic Company, ICL Group, LANXESS, Derivados Del Fluor, Hydrite Chemical, Univar Solutions, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fluorosilicic Acid Market Strategic Shifts & Innovations
Formulation strategies are pivoting toward lower-emission supply chains as regulatory pressure intensifies on fluorinated substance lifecycles. Technical purification advances and procurement model evolution are reshaping competitive positioning.
Membrane electrolysis purification is unifying technical-grade and pharmaceutical-grade production lines at integrated fluorochemical platforms. Belgian and French manufacturing nodes are adopting these systems to serve both municipal water utilities and semiconductor fabricators from common feedstock. This convergence is compressing the historical separation between industrial and specialty grade supply chains.
EU F-Gas Regulation amendments are tightening reporting thresholds for fluorinated substance imports and mandating downstream user traceability. Chemical distributors must now maintain substance-level documentation across blended product lines. Municipal procurement officers in Germany and France are responding by pre-qualifying suppliers with established ECHA dossier management capabilities.
Performance-based service agreements are displacing traditional commodity spot purchasing in Scandinavian municipal water authorities. IXOM Limited and similar logistics specialists are bundling bulk delivery with fluoridation system monitoring. This shift is most visible in Sweden and Norway, where long-term tender structures now specify outcome metrics rather than input volumes.
Europe Fluorosilicic Acid Market Segmentation
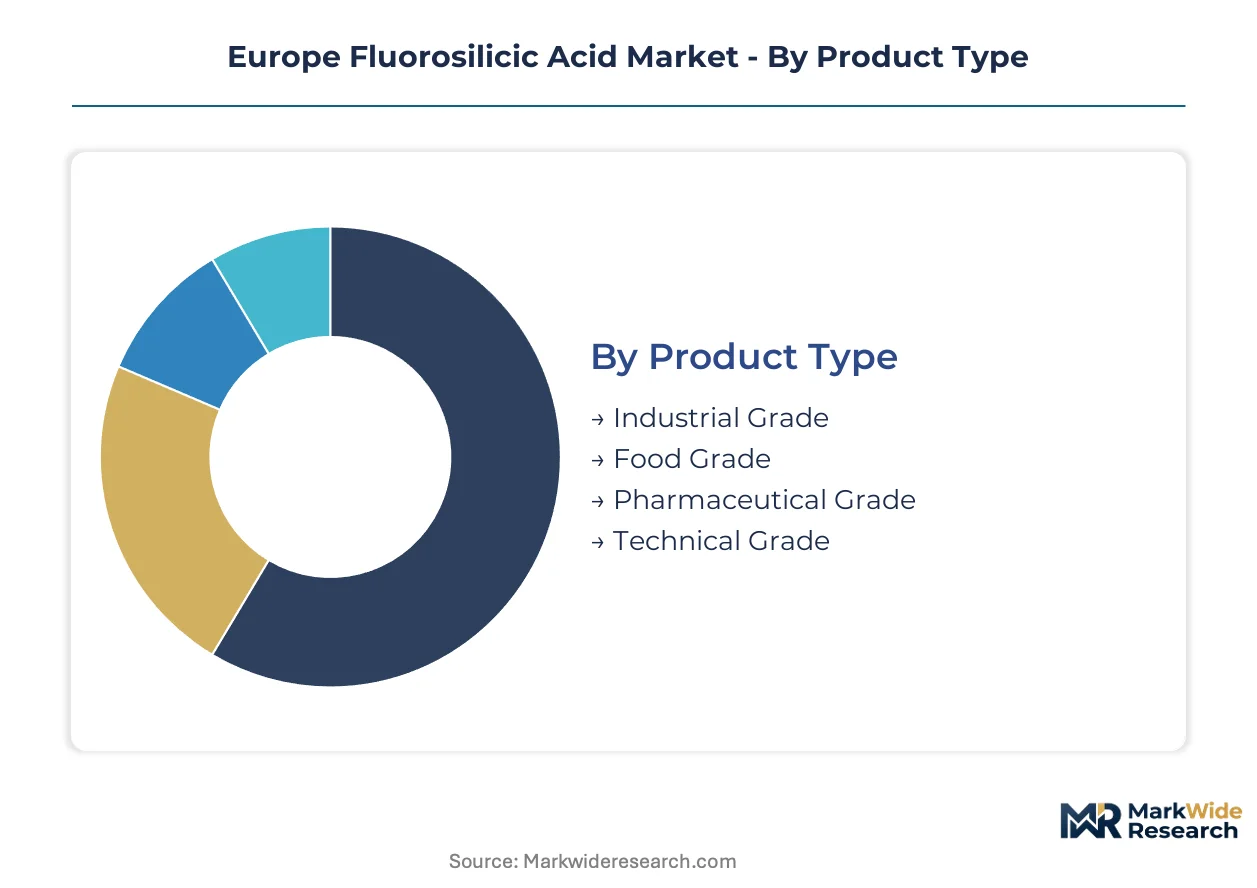
Fluorosilicic acid segmentation in Europe reflects divergent compliance burdens across purity tiers and end-use applications. Certification requirements from EFSA, ECHA, and national water authorities fragment procurement channels and reshape supplier economics.
Product Type:
REACH registration tiers and EFSA benchmarks impose sharply different documentation obligations across purity grades, filtering supplier participation by certification capability.
- Industrial Grade:Aqueous solutions at 20-25% concentration serve municipal water fluoridation networks across Germany and France. Long-term utility contracts lock in volume commitments, though F-Gas Regulation reporting costs compress margins for uncertified blenders.
- Pharmaceutical Grade:Ultra-purified material meeting EMA and EFSA batch certification requirements supplies active ingredient synthesis for European pharmaceutical manufacturers. Extended dossier cycles and analytical testing protocols create defensible margin pools for qualified producers.
- Food Grade:EFSA-purity benchmarks govern fluoride additive applications in food processing.
- Technical Grade:Semiconductor etching specifications command premium positioning over industrial material.
Leading the category by volume: Industrial Grade. Growing fastest: Pharmaceutical Grade.
Application:
End-use demand concentrates in Western European municipal contracts, though battery electrolyte intermediates are redirecting acid volumes toward chemical synthesis.
- Water Treatment:Municipal fluoridation programs in Sweden, Norway, Germany, and France consume the majority of industrial-grade supply. Tender structures specify multi-year service agreements with minimum volume guarantees, creating sticky supplier relationships.
- Chemical Synthesis:Fluorochemical precursor demand from lithium-ion battery manufacturing and pharmaceutical intermediates is accelerating fastest. Belgian and French integrated fluorochemical platforms are unifying production lines to serve this expanding pool.
- Fertilizers:Phosphoric acid substitution in Eastern European blending operations narrows historical price premiums.
- Glass Manufacturing:Metal surface treatment and opacifier applications maintain steady offtake.
Water Treatment dominates volume flows. Chemical Synthesis climbs the fastest as fluorinated electrolyte demand expands.
End User:
Procurement authority and contract structure vary sharply across customer types, from centralized municipal tenders to fragmented agricultural purchasing.
- Municipalities:Scandinavian and German water authorities specify performance-based service agreements bundling bulk delivery with fluoridation system monitoring. IXOM Limited and similar logistics specialists anchor competitiveness through specialized tanker capabilities.
- Chemical Industry:Semiconductor fabricators and pharmaceutical manufacturers demand technical-grade and pharmaceutical-grade material with full ECHA dossier traceability.
- Agriculture:Fertilizer blenders in Poland and Romania increasingly substitute phosphoric acid for cost reasons.
- Construction:Metal surface treatment applications for infrastructure projects maintain modest offtake.
Municipalities lock in the largest contracted volumes. Chemical Industry purchases expand most quickly on battery and pharma demand.
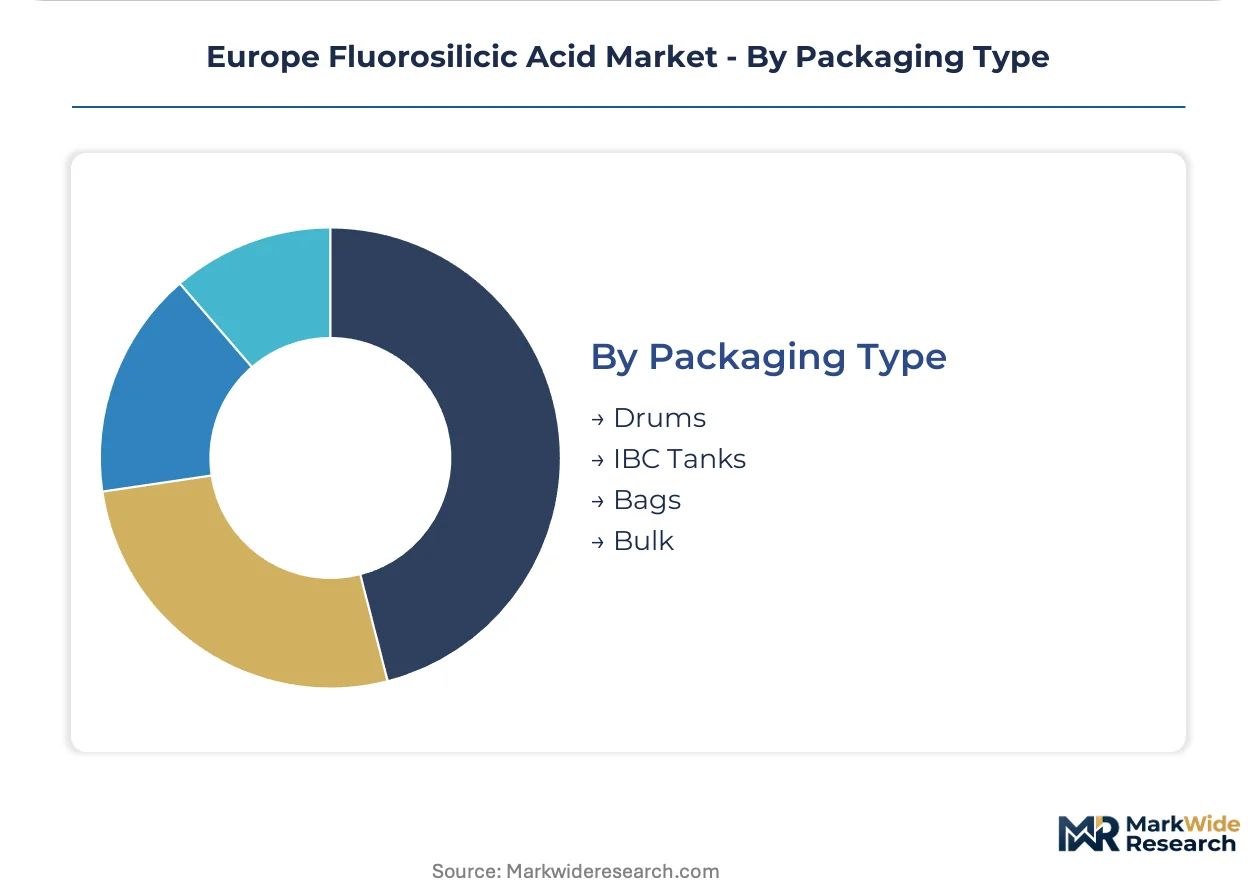
Packaging Type:
Logistics economics and corrosive material handling requirements concentrate supply in bulk and IBC formats for high-volume users.
- Bulk:Dedicated tanker fleets serve municipal utilities and large chemical processors across Belgium, France, and Germany. Capital-intensive fleet requirements filter smaller distributors from formal supply chains.
- IBC Tanks:Intermediate volumes for mid-scale chemical synthesis and food processing applications balance handling efficiency with flexibility.
- Drums:Small-batch pharmaceutical and laboratory applications require certified containment.
- Bags:Limited to solid fluorosilicate salt derivatives rather than aqueous acid.
Bulk packaging leads by tonnage moved. IBC Tanks gain share fastest among flexible procurement users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal water fluoridation contracts concentrate demand in Western European utilities, while chemical synthesis applications redirect volumes toward Belgian and French manufacturing nodes. REACH compliance costs and F-Gas Regulation obligations filter supplier participation by certification capability. Production gravity favors integrated fluorochemical platforms near Antwerp and the Rhine-Ruhr corridor.
Germany
Municipal utilities in North Rhine-Westphalia and Bavaria specify multi-year fluoridation service agreements with minimum volume guarantees. The country's federal drinking water directive tightens feedstock qualification standards, forcing suppliers to consolidate ECHA dossier documentation. Düsseldorf-based water authorities anchor demand for industrial-grade material through performance-based procurement structures.
France
Paris and Lyon metropolitan water networks expand fluoridation coverage under national public health mandates. ANSM oversight of pharmaceutical-grade applications extends batch certification cycles for active ingredient manufacturers. The Rhône-Alpes cluster houses integrated fluorochemical production serving both municipal utilities and semiconductor fabricators.
Belgium
Antwerp's phosphate fertilizer off-gas capture facilities supply feedstock to integrated acid purification operations. The country's central location enables bulk tanker distribution across the Benelux and northern France. REACH registration obligations elevate operational overhead for regional blenders without established ECHA dossier management.
Sweden
Stockholm and Gothenburg municipal authorities pioneered long-term tender structures bundling bulk delivery with fluoridation system monitoring. The country's national chemical agency enforces stringent substance traceability requirements under EU F-Gas Regulation amendments. Scandinavian logistics specialists anchor competitiveness through specialized corrosive material handling capabilities.
Poland
Fertilizer blenders in Silesia and Greater Poland increasingly substitute phosphoric acid for fluorosilicic acid in agricultural applications. The country's national water utility maintains limited fluoridation infrastructure compared to Western European counterparts. Warsaw-based distributors face margin compression from cheaper phosphate alternatives in Eastern European blending operations.
Europe Fluorosilicic Acid Market Key Industry Players
Multi-year service contract acquisition dominates the current landscape as municipal utilities lock in supply security. The vendor base concentrates around integrated fluorochemical platforms and specialized bulk logistics operators, with certification capability serving as the primary filtering mechanism. Three archetypes occupy distinct positions: phosphate-derived feedstock integrators, regional logistics specialists with tanker fleet assets, and technical-grade purification operators serving semiconductor specifications. Competitive intensity centers on ECHA dossier completeness and long-term tender participation rather than spot price undercutting.
Among integrated chemical platforms, Solvay occupies a position exemplifying feedstock security through phosphate fertilizer off-gas integration. IXOM Limited anchors the logistics-specialist archetype with bulk distribution capabilities serving Scandinavian municipal authorities. Honeywell International sits within the technical-grade purification tier, representing semiconductor etching specification compliance. These three entities collectively illustrate how certification depth and asset specificity divide competitive position in European fluorosilicic acid supply.
| Leading Market Players |
|---|
| Solvay |
| IXOM Limited |
| Honeywell International |
| The Mosaic Company |
| ICL Group |
| LANXESS |
| Derivados Del Fluor |
| Hydrite Chemical |
| Univar Solutions |
| Others |
Cost & Logistics Intelligence
Phosphate fertilizer off-gas capture economics in the Antwerp corridor cascade through three distinct pricing tiers downstream. Municipal utilities in Germany and France absorb industrial-grade volumes under long-term service agreements, while semiconductor fabricators pay substantial premiums for technical-grade purification protocols certified to ECHA standards.
Pricing Analysis
Volume flows concentrate in industrial-grade municipal contracts with thin margins, while pharmaceutical-grade and technical-grade tiers capture wider spreads through batch certification cycles. Price differentiation rests on ECHA dossier completeness and EFSA purity benchmarks rather than commodity spot dynamics. Cost compression in agricultural applications intensifies as Polish and Romanian fertilizer blenders substitute phosphoric acid for fluorosilicic acid. Municipal procurement officers show lowest price sensitivity due to regulatory mandates, whereas Eastern European agricultural buyers exhibit highest elasticity to phosphate alternatives.
Supply Chain Analysis
Dual-sourcing requirements from Scandinavian water authorities mandate qualified backup suppliers for every active contract, filtering single-source dependencies from formal procurement channels. Feedstock security draws from Belgian phosphate fertilizer off-gas facilities, French integrated fluorochemical platforms, and German purification operations. Raw material dependencies encompass phosphate rock supply, sulfuric acid for scrubbing operations, and membrane electrolysis equipment. Single-source vulnerability concentrates around Antwerp corridor capture capacity. Distribution runs through specialized bulk tanker fleets serving municipal utilities and IBC formats for mid-scale chemical synthesis users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antwerp corridor production concentration creates a structural capacity bottleneck that props pricing across all purity tiers. Municipal fluoridation mandates ensure baseline offtake regardless of cyclical pressure.
For Market Incumbents: Deepen backward integration into phosphate fertilizer off-gas capture to secure feedstock against Belgian production concentration risk. Expand ECHA dossier management capabilities to defend municipal contract renewals against emerging logistics specialists. Lock in multi-year service agreements with minimum volume guarantees before REACH registration tiers filter additional competitors.
For New Entrants and Emerging Players: Begin with pharmaceutical-grade batch certification to access defensible margin pools unconstrained by agricultural substitution pressure. Target Scandinavian municipal authorities with performance-based service agreements bundling bulk delivery with fluoridation system monitoring. Pursue acquisition of specialized tanker fleet assets rather than greenfield purification capacity.
For Investors and Strategic Acquirers: ECHA classification procedure extensions are the leading indicator that compliance capability scarcity will concentrate supplier economics toward established dossier managers. Long-term viability favors integrated fluorochemical platforms with captive phosphate-derived feedstock and unified technical-grade production lines. Watch for F-Gas Regulation amendment timing as the signal for import dependency ratio shifts favoring domestic manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Capture | Antwerp corridor phosphate off-gas facilities anchor supply security against Belgian concentration risk. |
| Membrane Electrolysis Purification Scale-Up | Belgian and French nodes unify industrial and technical-grade lines to serve semiconductor fabricators. |
| Long-term Municipal Service Agreements | Swedish and Norwegian tender structures lock in sticky supplier relationships with outcome metrics. |
| EFSA Pharmaceutical-Grade Certification | Extended batch certification cycles create defensible margin pools for active ingredient manufacturers. |
| Specialized Bulk Logistics Fleet Expansion | IXOM Limited's tanker capabilities demonstrate asset specificity required for Scandinavian water authorities. |
Research Approach
Document review covered ECHA registration databases, EU F-Gas Regulation amendment filings, and municipal tender documentation from Swedish, Norwegian, German, and French water authorities, complemented by interviews with plant managers at integrated fluorochemical platforms, procurement leads at municipal utilities, distribution channel partners in Benelux bulk logistics, and technical R&D directors specializing in membrane purification. Secondary validation drew from customs and trade data, Cefic fluorochemical reports, SEC 10-K disclosures from listed chemical producers, and national chemical agency substance notifications. Bottom-up volume triangulation across purity tiers and end-use applications was cross-checked against top-down market sizing from production capacity and trade flow analysis.
Segmentation outputs across product type, application, end user, and packaging format were modeled over the projection horizon, with CAGRs derived from trend extrapolation of municipal fluoridation program expansion, battery electrolyte intermediate demand, and agricultural substitution patterns. Industry-specific forecast inputs incorporated REACH registration tier implementation timelines and EU Green Deal precursor control proposal trajectories.
REACH enforcement intensity, F-Gas Regulation reporting threshold amendments, and phosphoric acid substitution velocity in Eastern European fertilizer blending are the dominant revision risks to modeled assumptions. Deviation in ECHA classification procedure timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Construction Chemicals Market
Chemicals
Mercuric Chloride Market
Chemicals
Myclobutanil Market
Chemicals
Methoprene Market
Chemicals
Fluorene Market
Chemicals
Desalination Chemicals Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Inorganic Chemicals Market
Chemicals
China Amines Market
Chemicals
Malonic Acid Market
Chemicals
Trifluoroacetic Acid (TFA) Market
Chemicals
3-Dimethylacrylic Acid Methyl Ester Market
Chemicals
Azodicarbonamide (ADC) Market
Chemicals
Egypt Acidulants Market
Chemicals
Asia-Pacific Gamma Butyrolactone Market
Chemicals
Cumene Market