
 North America Food Sweetener Market | 2026-2036
North America Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Sweetener Market Analytics
Ingredient platform licensing is reconfiguring margin pools away from bulk commodity sales toward proprietary formulation services. Cargill, Incorporated leverages its vertically integrated stevia supply chain to capture value across extraction and refinement stages. Tate & Lyle anchors its position through specialized fiber-based sweetening systems that reduce sugar without sensory compromise. Ingredion Incorporated competes through clean-label texturants that offset mouthfeel loss in reduced-calorie applications.
Food sweeteners encompass caloric and non-caloric substances that impart sweetness to edible products, typically measured by sucrose equivalence and thermal stability profiles that determine processing viability. Their primary commercial purpose centers on palatability enhancement while meeting caloric reduction targets set by health-conscious food manufacturers. Sugar alternatives within the stevia and aspartame categories command premium positioning as beverage brands pursue zero-calorie claims without synthetic aftertaste liabilities. Crystallized and liquid forms diverge in margin structure, with liquid concentrates capturing higher value per unit in fountain and ready-to-drink applications where dissolution efficiency matters.
The FDA governs sweetener safety through GRAS determinations and added sugars labeling mandates, while Health Canada maintains distinct approval pathways for novel food ingredients including steviol glycosides. These frameworks shape product development timelines and cross-border formulation standardization costs for multinational food manufacturers. Stakeholders must monitor evolving GRAS notification requirements and state-level sugar tax proposals that could fragment pricing power across provincial and state jurisdictions.
Market Dynamics
The North America Food Sweetener Market is experiencing a fundamental restructuring as FDA-mandated added sugars disclosure compresses reformulation timelines and forces manufacturers to abandon legacy sucrose-dominant formulations. This regulatory pressure cascades through procurement decisions, R&D budgets, and supplier qualification protocols.
Growth Catalysts
- Clean-label beverage mandates:Major soft drink producers across the United States are accelerating stevia and monk fruit integration to satisfy zero-sugar claims without synthetic aftertaste liabilities.
- GRAS notification streamlining:The FDA's evolving novel sweetener approval pathways are reducing time-to-market for new glycoside variants extracted from underutilized plant sources.
- Sports nutrition concentration:Protein and hydration brands in California and Texas manufacturing clusters are driving demand for heat-stable sweetening systems that survive UHT processing.
Market Restraints
- Stevia leaf supply volatility:Agricultural concentration in China's Guangxi province exposes North American extractors to climate-driven input cost swings and currency fluctuation risk.
- Sensory matching limitations:Bulking agents required in sugar-reduced baked goods fail to replicate Maillard browning and moisture retention, constraining application breadth.
- Cross-border formulation friction:Health Canada's distinct novel food ingredient pathways for steviol glycosides force dual-track product development, elevating compliance overhead for multinational manufacturers.
Strategic Opportunities
- Precision fermentation sweeteners:Biosynthetic production of rare sugars like allulose through microbial cell factories is hybridizing biotechnology with traditional extraction, opening domestic manufacturing options.
- Mexican beverage expansion:Carbonated and ready-to-drink tea segments in Monterrey and Guadalajara industrial corridors remain underpenetrated by advanced sweetening systems relative to US saturation.
- Fiber-sweetener convergence:Resistant dextrins and soluble corn fibers that deliver sweetness with prebiotic functionality are capturing formulation share in functional food categories.
Industry Challenges
- Sensory scientist scarcity:Formulation teams struggle to recruit flavor chemists capable of masking off-notes in high-intensity natural sweeteners, delaying product launches.
- Legacy equipment retrofit costs:Dry blending infrastructure designed for crystalline sucrose requires capital-intensive modification to handle hygroscopic alternative powders and liquid concentrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Sweetener Market |
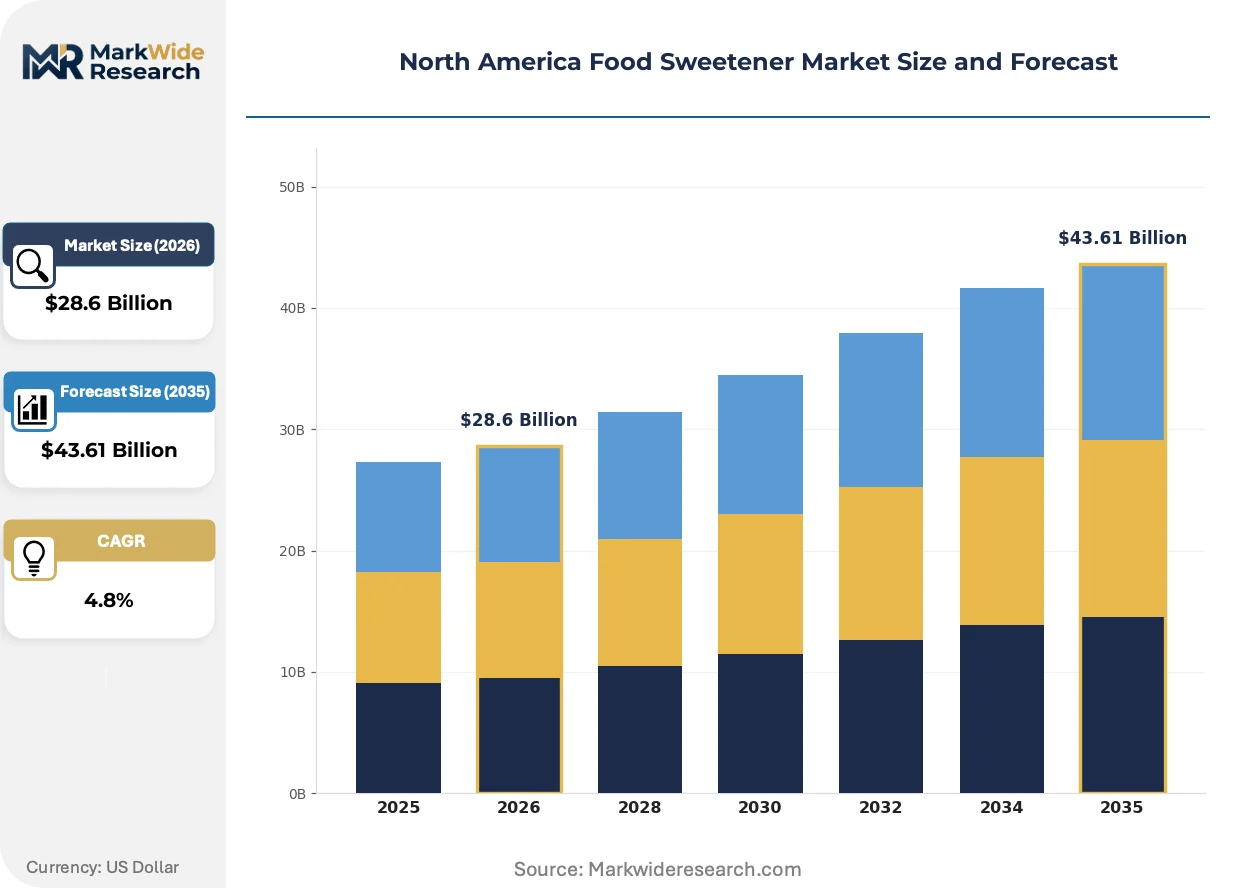
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugar, High Fructose Corn Syrup, Stevia, Aspartame Form: Liquid, Powder, Granulated, Crystallized Application: Beverages, Baked Goods, Dairy Products, Confectionery End User: Food Manufacturers, Restaurants, Retailers, Households |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Tate & Lyle, Ingredion Incorporated, Kerry Group, Roquette Frères, International Flavors & Fragrances Inc., Stevia First Corporation, Associated British Foods, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Sweetener Market Evolving Landscape
Reformulation chemistry is advancing rapidly as manufacturers pursue sugar reduction targets without sacrificing shelf stability or consumer acceptance. Three converging developments are redefining competitive advantage in ingredient supply.
Enzymatic conversion technology is hybridizing upstream processing capabilities, enabling manufacturers to transform commodity starches into rare sugars with caloric profiles below sucrose. Beverage producers in the Midwest and Southeast are adopting these systems at pilot scale, compressing reliance on traditional extraction supply chains and enabling captive production of proprietary sweetening bases.
The FDA's updated Nutrition Facts label requirements, mandating gram-level disclosure of added sugars, are forcing CPG manufacturers to front-load R&D spending on alternative systems. This regulatory compression is most acute in ready-to-eat cereal and dairy categories, where reformulated products must maintain bowl-life stability and fermentation control previously managed by sucrose osmotic pressure.
Direct procurement from ingredient technology firms is displacing traditional distributor relationships in the beverage sector. Large-format bottlers in Texas and California are negotiating exclusive supply agreements for custom glycoside blends, bypassing regional chemical distributors that historically managed inventory and technical service. This channel compression is concentrating volume with vertically integrated suppliers capable of co-developing application-specific solutions.
North America Food Sweetener Market Segmentation
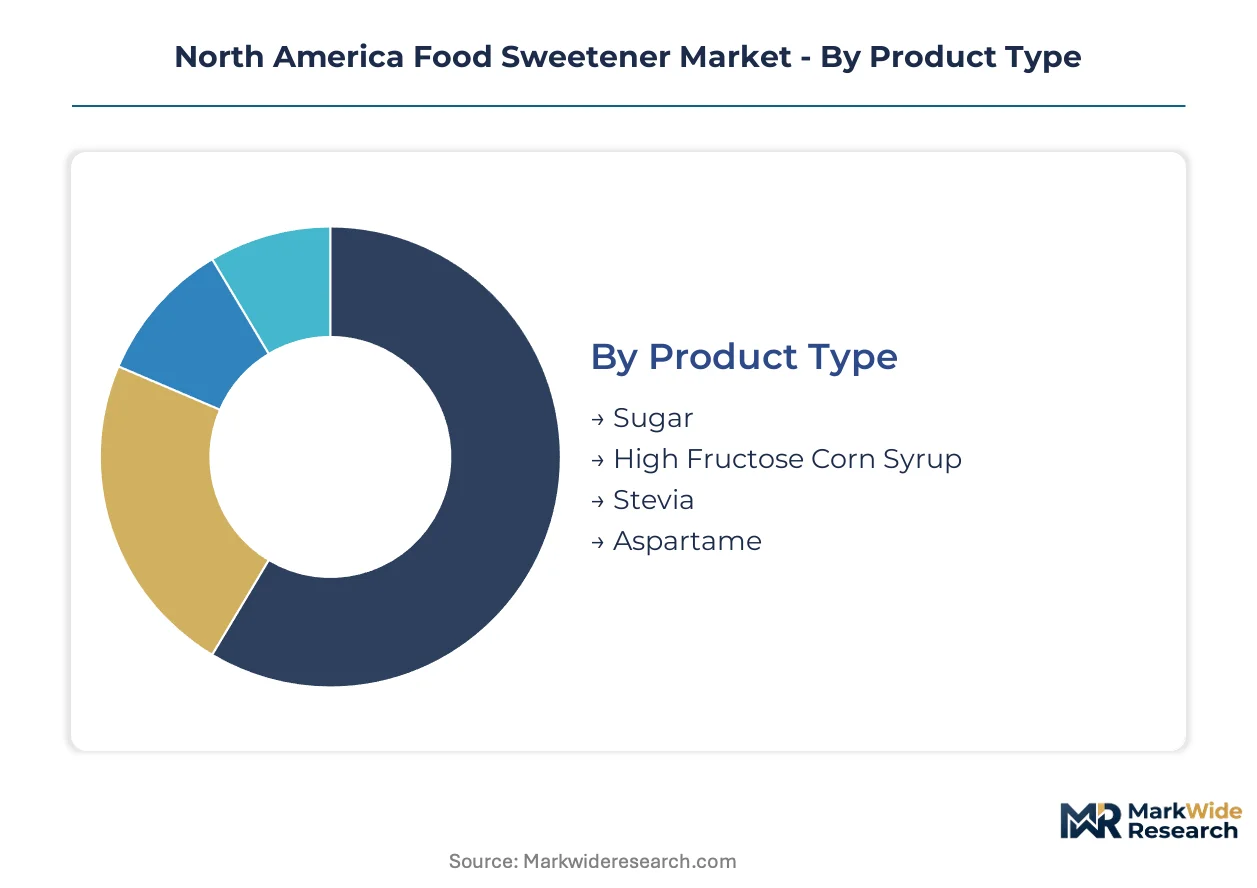
Sweetener procurement decisions in North America diverge sharply across product categories, physical forms, and end-use applications. Each segmentation dimension carries distinct margin structures, regulatory exposure, and reformulation complexity that reshape supplier relationships and manufacturing investment priorities.
Product Type:
Cost tier differentiation separates commodity-driven bulk sweeteners from premium-positioned natural alternatives with proprietary extraction profiles.
- Stevia:Glycoside concentrates extracted from stevia leaves deliver zero-calorie sweetness with thermal stability suitable for UHT processing. Beverage manufacturers in California and Texas manufacturing clusters are locking in multi-year supply contracts for Reb M and Reb D variants to secure clean-label positioning.
- Aspartame:The methyl ester of aspartic acid and phenylalanine dipeptide provides intense sweetness at low dosage costs but faces mounting formulation retreat as consumers reject synthetic additives. Carbonated soft drink producers are accelerating phase-out timelines in response to retail channel pressure.
- Sugar:Sucrose from cane and beet sources retains dominance in baked goods and confectionery where Maillard browning and crystallization control remain irreplaceable.
- High Fructose Corn Syrup:Enzymatically converted corn starch syrups maintain cost advantage in fountain beverages and mass-market packaged goods despite added-sugar labeling headwinds.
Sugar commands the established base. The steepest expansion runs through stevia glycoside variants.
Form:
Physical state determines dissolution efficiency, handling infrastructure requirements, and value capture per unit across manufacturing contexts.
- Liquid:Pumpable concentrates integrate directly into beverage batching systems without dry-blending stages, commanding premium positioning in ready-to-drink and fountain applications where dissolution speed drives line efficiency.
- Powder:Hygroscopic alternative sweeteners in powder form require climate-controlled handling infrastructure but enable precise dosing in dry-mix applications. Sports nutrition manufacturers in the Mountain West are retrofitting facilities to manage these inputs.
- Granulated:Free-flowing crystals approximate sucrose handling characteristics, minimizing equipment retrofit costs for legacy bakeries transitioning to reduced-sugar formulations.
- Crystallized:Purified crystal structures from stevia and allulose extraction deliver standardized sweetness intensity for pharmaceutical and premium food applications with exacting specification requirements.
Granulated formats anchor current volume. Liquid concentrates are climbing the fastest as beverage line speeds accelerate.
Application:
End-use category dictates thermal stability requirements, sensory matching complexity, and regulatory scrutiny intensity.
- Beverages:The largest demand concentration spans carbonated soft drinks, sports drinks, and ready-to-drink teas where clean-label mandates and zero-sugar claims drive stevia and monk fruit adoption. Reformulation cycles here are compressing from 18-month to 9-month timelines.
- Baked Goods:Sugar reduction faces fundamental technical barriers around moisture retention, browning chemistry, and yeast fermentation control. Commercial bakeries in the Midwest are testing fiber-sweetener hybrid systems to replicate sucrose functionality.
- Dairy Products:Yogurt and flavored milk applications require sweetening systems compatible with live culture viability and acid stability through shelf life.
- Confectionery:Hard candies and chocolate coatings demand precise crystallization control and melting point management that alternative sweeteners struggle to replicate at commercial scale.
Beverages represent the dominant revenue pool. Baked goods present the most complex technical expansion pathway.
End User:
Customer type determines procurement scale, technical service requirements, and formulation co-development intensity.
- Food Manufacturers:Large CPG producers negotiate direct supply relationships with integrated ingredient firms, bypassing distributors to secure custom glycoside blends and application-specific technical support. These buyers drive volume concentration and specification standardization.
- Restaurants:Foodservice operators prioritize cost stability and handling simplicity, resisting complex alternative sweetener systems that require staff retraining or equipment modification.
- Retailers:Private label development teams at major grocery chains are building in-house formulation capabilities to control clean-label positioning in store-brand beverage and bakery portfolios.
- Households:Consumer-packaged tabletop sweeteners represent a fragmented, promotion-sensitive segment where brand recognition and packaging convenience outweigh technical performance differentiation.
Food manufacturers concentrate procurement leverage. Retailer private label development is gaining share fastest as channel verticalization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North America, with Mexican beverage manufacturers showing highest price sensitivity to stevia input costs while U.S. premium brands absorb premiums for proprietary glycoside blends. Canadian reformulation timelines lag twelve to eighteen months behind U.S. adoption curves due to Health Canada's distinct novel food approval pathways.
United States
Carbonated soft drink producers in Atlanta and Purchase manufacturing corridors are locking in multi-year Reb M supply contracts to secure clean-label positioning. The FDA's added sugars disclosure mandate compresses reformulation cycles from eighteen to nine months. California and Texas beverage clusters are driving adoption of heat-stable stevia variants for UHT-processed sports drinks.
Canada
Health Canada's steviol glycoside approval pathway requires separate safety assessments not recognized under FDA GRAS determinations. Toronto-area dairy processors face dual-track development costs when exporting to U.S. retail channels. Quebec's maple syrup industry is experimenting with glycoside blending to reduce caloric density in traditional confectionery applications.
Mexico
Monterrey and Guadalajara industrial corridors remain underpenetrated by advanced sweetening systems relative to U.S. saturation levels. Mexican beverage tax structures incentivize cost-minimizing formulations over premium natural alternatives. Bimbo and regional bakery chains are testing fiber-sweetener hybrids to maintain price competitiveness in mass-market pan dulce segments.
California
Precision fermentation startups in South San Francisco and Berkeley are biosynthesizing rare sugars through microbial cell factories. The state's SB 347 clean-label procurement standards for institutional foodservice are accelerating stevia adoption in school beverage contracts. Los Angeles-based functional beverage brands are driving demand for prebiotic fiber-sweetener convergence in kombucha and adaptogenic drink formulations.
Texas
Large-format bottlers in Dallas-Fort Worth are negotiating direct supply agreements that bypass traditional chemical distributors. The state's absence of sugar taxation reduces reformulation urgency compared to California and Philadelphia jurisdictions. Houston petrochemical corridors are attracting enzymatic conversion technology pilots that transform commodity starches into proprietary sweetening bases.
North America Food Sweetener Market Competitive Landscape
Vertically integrated agricultural processors and specialized formulation houses split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: upstream crop handlers controlling stevia leaf supply chains, midstream extractors with proprietary glycoside refinement patents, and downstream application specialists co-developing custom blends. Dominant competitive moves include exclusive supply agreement negotiations with large-format bottlers and enzymatic conversion technology licensing to compress rare sugar production costs.
Among the named players, Cargill, Incorporated exemplifies upstream-backward integration through captive stevia cultivation and extraction infrastructure. Tate & Lyle occupies a position as a formulation specialist anchoring fiber-based sweetening system development. Ingredion Incorporated represents the texturant-convergence archetype, linking sweetener supply with mouthfeel restoration capabilities for reduced-calorie applications.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle |
| Ingredion Incorporated |
| Kerry Group |
| Roquette Frères |
| International Flavors & Fragrances Inc. |
| Stevia First Corporation |
| Associated British Foods |
| Others |
Value Network & Pricing Analysis
Stevia leaf supply volatility in China's Guangxi province determines both three-tier pricing spreads across premium glycoside variants and supply chain restructuring toward enzymatic conversion alternatives. FDA-mandated added sugars disclosure compresses buyer timelines, forcing manufacturers to absorb premium inputs or sacrifice clean-label positioning.
Pricing Analysis
After-sales technical service contracts drive lifetime value for integrated sweetener suppliers, separating commodity extractors from formulation partners. Three-tier pricing structure across premium Reb M/D glycosides, standard Reb A extracts, and economy-grade aspartame blends reflects purity certification and thermal stability performance. Pricing pressure stems from beverage bottlers consolidating volume with fewer suppliers capable of co-development. Food manufacturers exhibit lowest price sensitivity, absorbing premiums for proprietary blends, while Mexican mass-market bakeries prioritize cost minimization.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for stevia-dependent formulators. Raw material sourcing draws from Guangxi stevia cultivation, Brazilian cane sugar estates, and Midwest corn processing corridors for enzymatic feedstocks. Single-source vulnerability concentrates in Chinese glycoside extraction infrastructure. Distribution runs through direct procurement agreements with large-format bottlers, displacing traditional chemical distributors in Texas and California beverage clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American food sweetener demand sits in early-cycle expansion as clean-label beverage reformulation accelerates stevia and monk fruit penetration beyond legacy synthetic alternatives.
For Market Incumbents: Entrench proprietary glycoside extraction patents and captive stevia cultivation to defend margin pools against precision fermentation entrants. Secure multi-year supply agreements with California and Texas beverage clusters before enzymatic conversion technology achieves cost parity. Prioritize fiber-sweetener hybrid R&D to capture baked goods reformulation demand where sensory matching barriers remain highest. For New Entrants and Emerging Players: Pursue white-space opportunities in Mexican Monterrey and Guadalajara industrial corridors where advanced sweetening systems remain underpenetrated relative to U.S. saturation. Target foodservice channel partnerships delivering cost-stable liquid concentrate systems that minimize equipment retrofit requirements for restaurant operators. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors precision fermentation platforms and enzymatic conversion capabilities over traditional agricultural extraction. Long-term viability hinges on domestic manufacturing options that decouple from Chinese supply concentration. Watch FDA GRAS notification streamlining for novel glycoside variants as the inflection signal indicating regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Biosynthetic allulose production in South San Francisco reduces dependency on Chinese stevia leaf supply chains. |
| Exclusive Supply Agreement Negotiation | Direct procurement relationships with Texas bottlers bypass distributor margins and lock in volume concentration. |
| Fiber-Sweetener Hybrid Development | Resistant dextrin systems replicate sucrose functionality in Midwest commercial bakeries facing Maillard browning barriers. |
| GRAS Notification Streamlining Investment | FDA pathway optimization accelerates time-to-market for Reb M and Reb D glycoside variants from underutilized plant sources. |
| Mexican Manufacturing Footprint Expansion | Monterrey production facilities capture cost-sensitive beverage tax structures while serving underpenetrated regional demand. |
Research Methodology
Desk research of FDA GRAS notifications, Health Canada novel food approvals, and trade customs data preceded structured interviews with beverage formulation directors, sweetener procurement leads at CPG manufacturers, stevia extraction plant managers, and enzymatic conversion technology R&D heads. Bottom-up volume modeling across product type, physical form, and application segments was triangulated against top-down industry aggregation.
Assumptions held FDA labeling mandates and Health Canada approval pathways fixed while varying stevia leaf supply scenarios and precision fermentation cost curves across the analysis window. Segmentation dimensions modeled include glycoside variant tier, thermal stability specification, end-use thermal processing requirement, and regional regulatory cluster. CAGRs were derived from regression analysis of historical adoption curves applied to reformulation timeline compression.
Sensitivities concentrate around Chinese agricultural output volatility, FDA enforcement intensity on added sugars disclosure, and precision fermentation yield improvements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
Stevia Mints Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
Natural Sweeteners Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
United States Food Sweetener Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
France Food Sweetener Market
Sweeteners
Maltodextrin Market
Sweeteners
China Saccharin Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Fructose Market
Sweeteners
China Allulose Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
Erythritol Market