
 Sugar Polyols Market | 2026-2036
Sugar Polyols Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Polyols Market Analytics
Consolidation among multinational food manufacturers is repositioning procurement leverage toward suppliers with integrated polyol production networks. Cargill leverages its global agricultural sourcing infrastructure to secure feedstock cost advantages across sorbitol and erythritol lines. Roquette Frères anchors its competitive stance through deep specialization in plant-based carbohydrate chemistry and European manufacturing scale.
Sugar polyols constitute a class of hydrogenated carbohydrate sweeteners characterized by hydroxyl group saturation that reduces caloric density and suppresses Maillard browning relative to sucrose. Their primary commercial purpose centers on bulk sweetening in reduced-sugar and sugar-free formulations where crystallization control, humectancy, and cooling effects prove functionally essential. Sorbitol dominates volume throughput due to mature supply chains and cost-competitive hydrogenation of glucose feedstocks, while erythritol captures accelerating demand from clean-label beverage and confectionery developers seeking near-zero caloric impact. Powder and crystalline forms command premium positioning in pharmaceutical tableting and direct-compression applications where particle-size distribution governs dissolution performance.
FDA nutrition labeling mandates and EFSA health claim frameworks are tightening added-sugar disclosure requirements, directly stimulating polyol substitution in reformulated packaged foods across the United States and European Union. REACH chemical registration protocols and evolving EFSA novel food opinions govern market access for emerging polyol variants and fermentation-derived production pathways. China's GB food additive standards and NMPA pharmaceutical excipient classifications further shape product specifications for suppliers targeting Asia-Pacific commercialization. Stakeholders must monitor regulatory divergence between jurisdictions on sugar alcohol labeling, daily intake thresholds, and digestive tolerance claims to anticipate reformulation timelines and regional portfolio prioritization.
Market Dynamics
FDA's updated nutrition labeling mandates for added sugars are forcing systematic reformulation across packaged food categories, redirecting procurement budgets toward hydrogenated carbohydrate sweeteners that preserve bulk functionality while reducing caloric disclosure.
Growth Catalysts
- Clean-label beverage formulation:Erythritol demand accelerates as beverage developers seek near-zero caloric impact without synthetic sweetener stigma. Formulators prize its cooling effect and crystallization control in reduced-sugar carbonated drinks.
- China's GB food additive standards:Domestic sorbitol and xylitol production capacity expansion under NMPA pharmaceutical excipient classifications supports both local bakery applications and export supply to Southeast Asian confectionery markets.
- Maillard browning suppression:Sugar polyols' hydroxyl group saturation enables extended shelf stability in reduced-sugar baked goods, a functional property driving adoption across European industrial bakery procurement.
Market Restraints
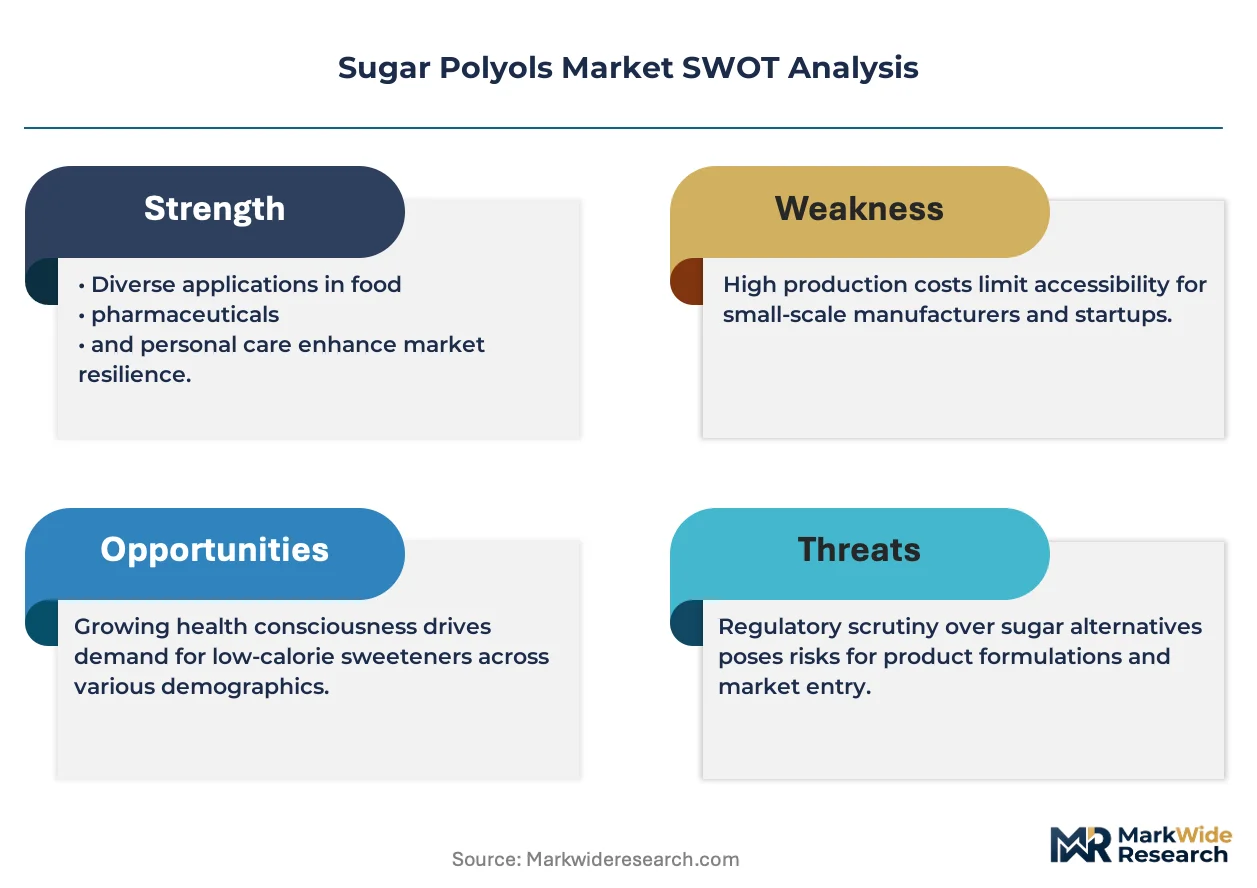
- Glucose feedstock volatility:Sorbitol hydrogenation economics remain tethered to agricultural commodity swings, compressing margin predictability for producers lacking integrated starch processing.
- Digestive tolerance thresholds:EFSA daily intake guidance and FDA labeling requirements for sugar alcohol laxation warnings constrain formulation ceilings in confectionery targeting mass-market distribution.
- High-intensity sweetener substitution:Stevia and monk fruit extracts compete for clean-label positioning in beverage applications where bulk sweetness requirements are minimal.
Strategic Opportunities
- Pharmaceutical tableting expansion:Powder and crystalline polyol grades with controlled particle-size distribution command premium positioning in direct-compression applications for Asia-Pacific generic drug manufacturing.
- Fermentation-derived erythritol pathways:Novel production technologies using engineered yeast strains bypass traditional hydrogenation infrastructure, opening capacity expansion for mid-scale entrants.
- India's FSSAI reduced-sugar claims:Health claim frameworks for diabetic-friendly foods create formulation pull in domestic confectionery and traditional sweet categories previously dependent on sucrose.
Industry Challenges
- REACH novel food registration timelines:Emerging polyol variants face extended EFSA opinion processes that delay commercial launch windows by 18-24 months versus established hydrogenated carbohydrates.
- Particle engineering expertise scarcity:Pharmaceutical-grade crystallization control requires specialized process engineering talent concentrated among European and Japanese equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Polyols Market |
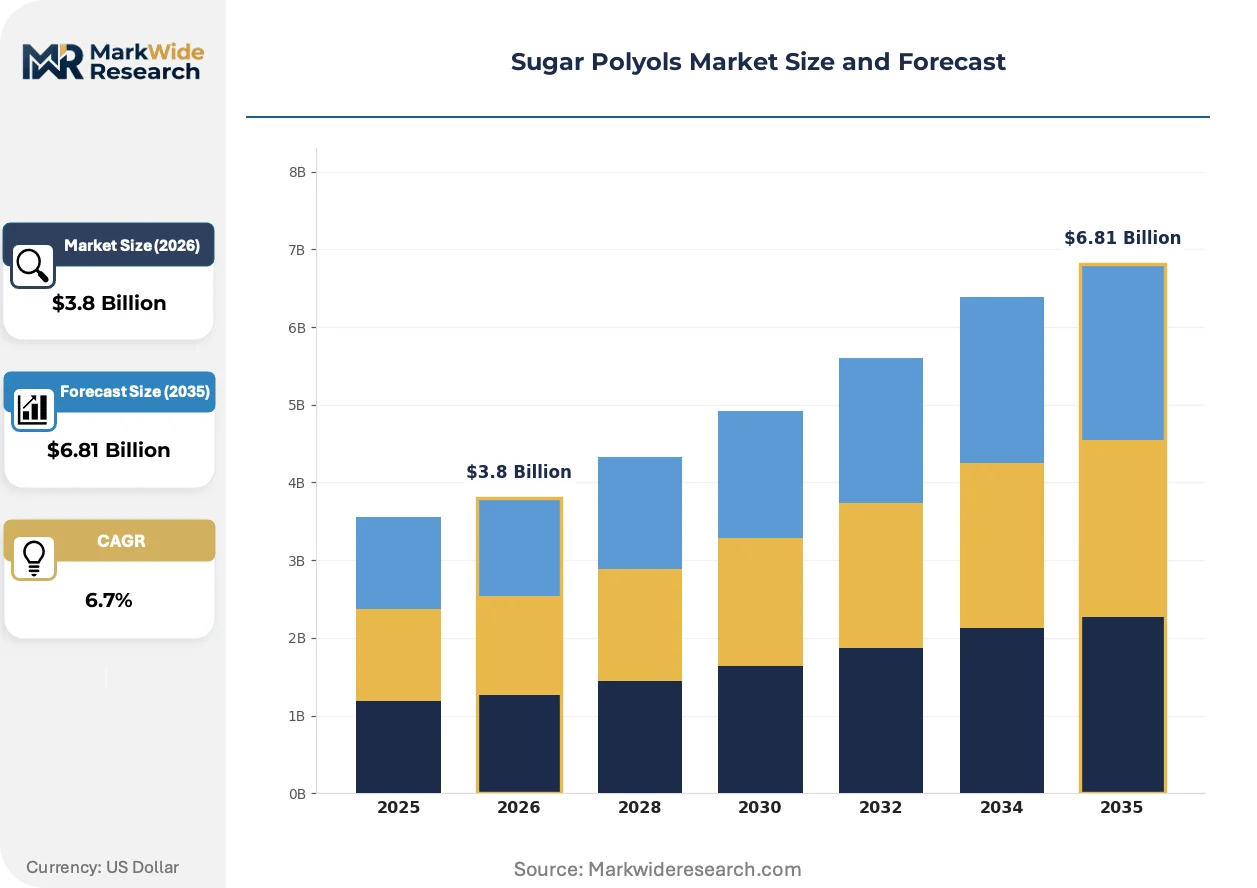
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbitol, Mannitol, Xylitol, Erythritol Application: Bakery, Confectionery, Dairy, Beverages End User: Food Manufacturers, Pharmaceuticals, Cosmetics, Nutraceuticals Form: Powder, Liquid, Granules, Crystals |
| Companies Covered | Cargill, Archer Daniels Midland, DuPont, Roquette Frères, Ingredion, Südzucker AG, Tereos, Jungbunzlauer Suisse AG, Gulshan Polyols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Polyols Market Evolving Landscape
Continuous hydrogenation reactor technology and precision fermentation platforms are restructuring production economics, while regulatory disclosure mandates reshape formulation priorities across packaged food value chains.
Continuous-flow hydrogenation systems are automating glucose-to-sorbitol conversion with tighter temperature control and reduced catalyst consumption. European and Chinese producers deploy these systems to compress unit costs and improve batch consistency for food-grade output. The technology is automating quality assurance protocols that previously required manual sampling intervention.
EFSA's evolving novel food opinions and REACH chemical registration protocols govern market access for fermentation-derived polyol variants and non-traditional hydrogenation feedstocks. These frameworks create compliance differentiation between established glucose-based sorbitol and emerging cellulosic or C5 sugar pathways. European Union beverage and confectionery formulators face reformulation timelines accelerated by 2025 labeling enforcement.
Direct procurement relationships between food manufacturers and polyol producers are displacing traditional distributor intermediaries in bulk sweetener sourcing. Large bakery and confectionery groups negotiate multi-year offtake agreements with hydrogenation specialists to secure crystalline grade supply. This pattern concentrates most visibly in China and Germany where industrial food manufacturing clusters align with major production facilities.
Sugar Polyols Market Segmentation
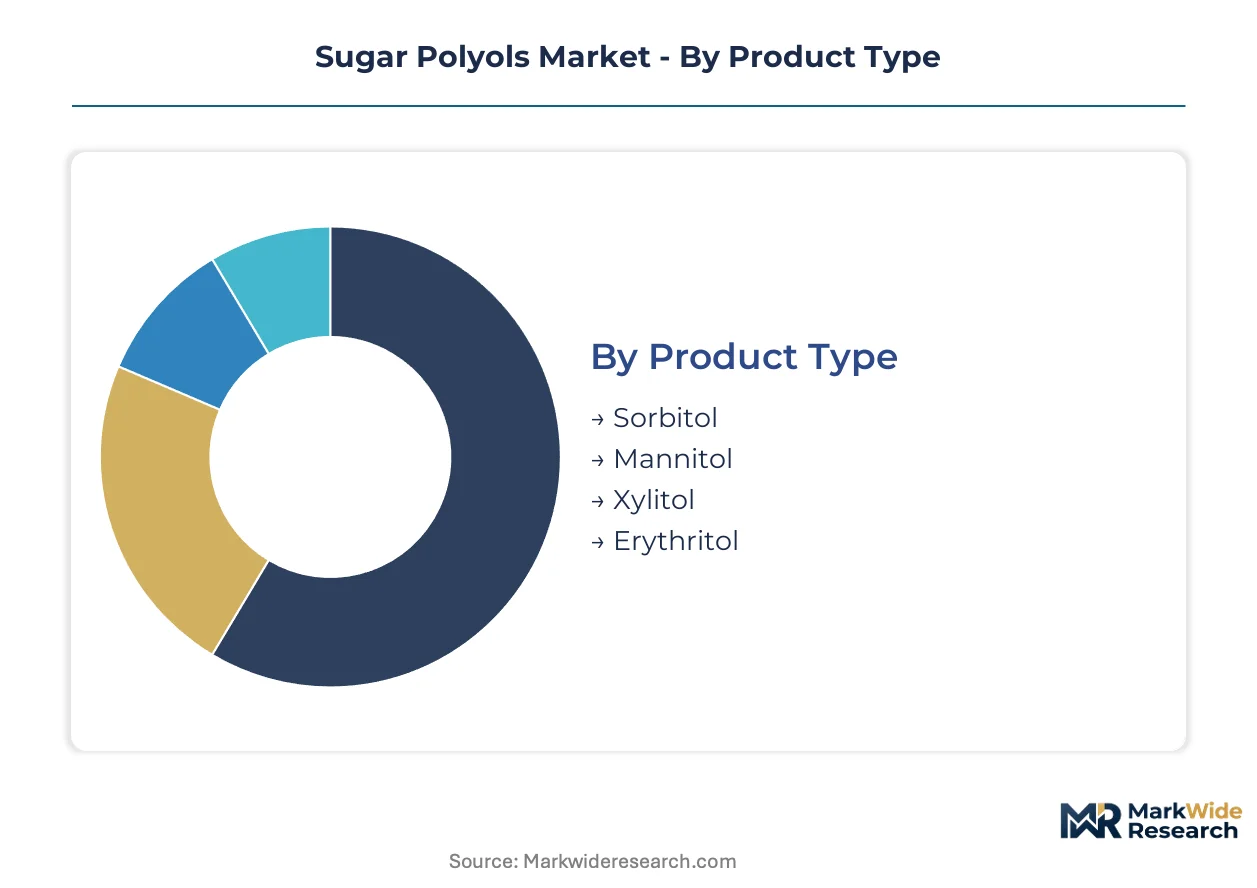
Sugar polyols derive commercial value from functional differentiation across hydrogenation chemistry, crystallization behavior, and end-use formulation requirements. Procurement decisions hinge on caloric density targets, Maillard suppression needs, and digestive tolerance thresholds that vary sharply by application.
Product Type:
Supply concentration clusters around mature hydrogenation infrastructure and fermentation capacity investments, with feedstock integration determining margin sustainability.
- Sorbitol:Derived from catalytic hydrogenation of glucose feedstocks, this polyol dominates volume throughput due to mature supply chains and cost-competitive production economics. Food manufacturers across China and Germany anchor procurement in sorbitol for reduced-calorie bakery applications where humectancy and crystallization control prove essential. Glucose feedstock volatility compresses margin predictability for producers lacking integrated starch processing.
- Erythritol:Fermentation-derived from glucose using engineered yeast strains, this polyol delivers near-zero caloric impact with superior digestive tolerance. Beverage developers in the United States and European Union prioritize erythritol for clean-label carbonated drinks where cooling effects and crystallization control differentiate formulation performance. Novel fermentation pathways bypass traditional hydrogenation infrastructure, opening capacity expansion for mid-scale entrants.
- Xylitol:Hydrogenated from xylose extracted from hardwood or agricultural residues, this five-carbon polyol commands premium positioning in dental-friendly confectionery and pharmaceutical applications.
- Mannitol:Produced through hydrogenation of fructose or mannose, this polyol finds concentrated demand in pharmaceutical tableting and parenteral formulations where low hygroscopicity governs stability requirements.
Today's leader: Sorbitol. Tomorrow's challenger: Erythritol.
Application:
Cost tier stratification separates premium functional applications from commodity bulk sweetening, with reformulation timelines accelerating under regulatory disclosure mandates.
- Bakery:Industrial bakers leverage polyol humectancy and Maillard browning suppression to extend shelf stability in reduced-sugar formulations. European procurement concentrates on sorbitol and maltitol syrups for soft bread and cake applications where moisture retention governs texture performance.
- Confectionery:Hard candies and chewing gum formulations exploit polyol cooling effects and non-cariogenic properties to support sugar-free and dental health claims. Xylitol captures premium positioning in gum bases across Japan and Scandinavian markets.
- Beverages:Erythritol demand climbs fastest in carbonated and still drinks where clean-label positioning and near-zero caloric impact satisfy FDA added-sugar disclosure requirements without synthetic sweetener stigma.
- Dairy:Frozen dessert and yogurt applications utilize polyol freezing point depression and crystallization control to maintain texture in reduced-sugar formulations.
Beverage applications expand most quickly; bakery retains volume dominance.
End User:
Customer type determines specification stringency, with pharmaceutical and food-grade certifications creating tiered entry barriers.
- Food Manufacturers:Bakery and confectionery groups negotiate multi-year offtake agreements with hydrogenation specialists to secure crystalline grade supply. Direct procurement relationships displace traditional distributor intermediaries in bulk sweetener sourcing.
- Pharmaceuticals:Powder and crystalline polyol grades with controlled particle-size distribution command premium positioning in direct-compression tablet applications. NMPA pharmaceutical excipient classifications in China and USP-NF standards in the United States govern specification compliance.
- Nutraceuticals:Dietary supplement formulators utilize polyols as excipients and active ingredients in diabetic-friendly and dental health products.
- Cosmetics:Humectant applications in skincare and oral care formulations exploit polyol hygroscopicity and skin tolerance properties.
Food manufacturers drive volume; pharmaceuticals capture margin.
Form:
Physical form dictates equipment compatibility and dissolution performance, with particle engineering expertise concentrated among specialized suppliers.
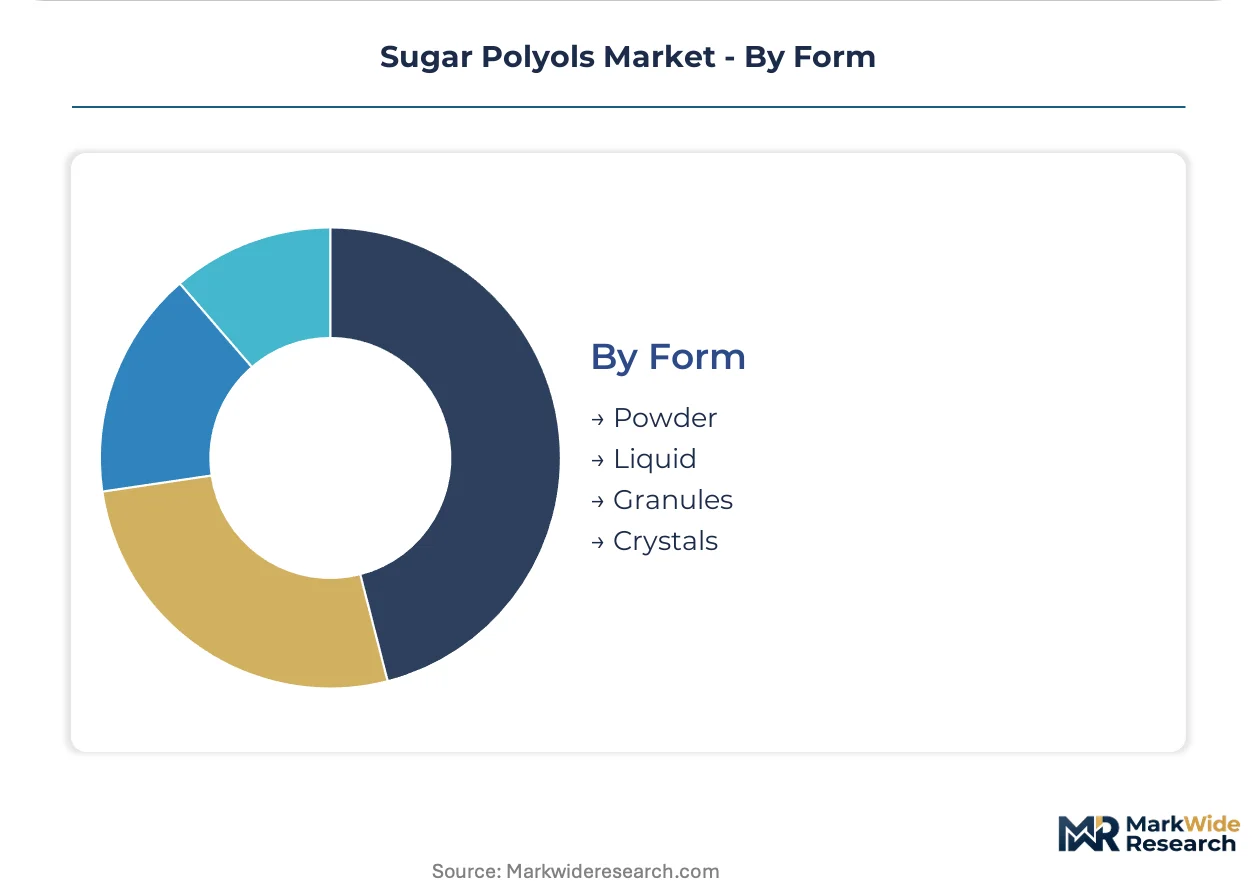
- Powder:Fine-ground polyols serve pharmaceutical direct-compression and instant beverage applications where rapid dissolution governs performance. Particle-size distribution specifications separate food-grade from pharmaceutical-grade supply tiers.
- Crystals:Controlled crystallization produces defined particle geometries for confectionery coating and chewing gum applications where mouthfeel and dissolution rate prove critical.
- Liquid:Sorbitol syrups dominate industrial bakery and confectionery bulk sweetening where handling efficiency and moisture management prioritize liquid delivery.
- Granules:Intermediate particle sizing bridges powder and crystal applications in tableting and dry mix formulations.
Powder commands pharmaceutical premium; liquid retains food manufacturing scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hydrogenation engineers and fermentation biotechnologists concentrate in industrial clusters across China, Germany, and the United States, anchoring regional production capabilities and export competitiveness.
China
Domestic sorbitol and xylitol capacity expansion serves both local bakery demand and Southeast Asian confectionery export markets. NMPA pharmaceutical excipient classifications under GB food additive standards govern quality specifications for dual-use food and pharma output. Shandong Peninsula hydrogenation facilities scale crystalline-grade production for direct-compression tablet applications.
Germany
Industrial bakery procurement drives maltitol syrup demand for reduced-sugar bread and cake formulations with extended shelf stability. REACH chemical registration protocols and EFSA novel food opinions shape reformulation timelines for emerging polyol variants. North Rhine-Westphalia hosts continuous-flow hydrogenation reactor deployments automating glucose-to-sorbitol conversion.
United States
FDA updated nutrition labeling mandates for added sugars accelerate beverage reformulation toward erythritol and other bulk sweeteners. Clean-label carbonated drink developers prioritize near-zero caloric impact without synthetic sweetener stigma. Midwest agricultural processing clusters integrate starch refining with captive hydrogenation infrastructure.
India
FSSAI reduced-sugar health claims for diabetic-friendly foods create formulation pull in domestic confectionery and traditional sweet categories. Domestic sorbitol procurement expands for industrial bakery applications in Maharashtra and Gujarat. Hyderabad fermentation specialists develop engineered yeast strains for novel erythritol production pathways.
Japan
Xylitol commands premium positioning in dental-friendly chewing gum bases across domestic and Scandinavian export markets. METI industrial standards and JIS specifications govern pharmaceutical-grade crystallization control for direct-compression applications. Osaka-Kobe chemical manufacturing corridor concentrates particle engineering expertise for premium polyol grades.
Sugar Polyols Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hydrogenation infrastructure and fermentation platform investments. Market structure tilts toward consolidated supply at the commodity sorbitol tier while fragmenting across emerging erythritol pathways. Three archetypes dominate: integrated agricultural processors with captive starch supply, European hydrogenation specialists with deep carbohydrate chemistry expertise, and Asian fermentation technology developers. Capacity expansion and direct procurement relationship-building constitute the dominant competitive moves.
Among integrated agricultural processors, Cargill and Archer Daniels Midland occupy positions anchored in global grain sourcing networks that secure feedstock cost advantages. Roquette Frères exemplifies the European hydrogenation specialist archetype through plant-based carbohydrate chemistry depth. Südzucker AG represents the diversified sugar conglomerate pivoting toward polyol value-added derivatives.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| DuPont |
| Roquette Frères |
| Ingredion |
| Südzucker AG |
| Tereos |
| Jungbunzlauer Suisse AG |
| Gulshan Polyols |
| Others |
Value Network & Pricing Analysis
FDA-mandated added-sugar disclosure requirements are forcing beverage and bakery formulators toward pharmaceutical-grade crystalline polyols, compelling hydrogenation specialists to upgrade quality systems and compressing margins on standard food-grade output.
Pricing Analysis
Capacity additions in China are reshaping price floors for crystalline sorbitol and erythritol grades, eroding premium capture for European producers. Three-tier pricing structure across pharmaceutical, food-grade, and technical specifications governs transaction structures, with FDA and EFSA certification tiers commanding substantial premia. Cost compression in standard sorbitol syrup runs through glucose feedstock volatility and continuous-flow reactor automation. Food manufacturers exhibit highest price sensitivity in bulk liquid procurement, while pharmaceutical tablet developers tolerate premium crystalline grades.
Supply Chain Analysis
Dual-sourcing mandates from multinational confectionery groups require hydrogenation specialists to qualify redundant crystalline-grade suppliers across China and Germany. Feedstock integration draws from Shandong corn starch processors and North Rhine-Westphalia wheat refiners. Supply chain risk centers on single-source vulnerability for engineered yeast strains in fermentation-derived erythritol pathways. Distribution runs through direct procurement relationships displacing traditional bulk sweetener distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: pharmaceutical-grade crystallization control and clean-label positioning now command decisive procurement preference over commodity bulk sweetening.
For Market Incumbents: Cement feedstock cost advantages through backward integration into regional starch processing, particularly in Midwest agricultural clusters and Shandong corn refining corridors. Defend against fermentation-derived erythritol entrants by locking multi-year offtake agreements with beverage formulators seeking supply security. For New Entrants and Emerging Players: Contract fermentation partners offer the most penetrable channel for novel erythritol pathways, bypassing capital-intensive hydrogenation infrastructure. White-space targets include pharmaceutical tableting applications in Hyderabad and Osaka-Kobe corridors where particle engineering expertise concentrates. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale fermentation technology developers possessing engineered yeast platforms and regulatory pre-qualification. Watch EFSA novel food opinion timelines as inflection indicators for commercial launch windows.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Hydrogenation Reactor Deployment | Automated glucose-to-sorbitol conversion compresses unit costs for Chinese and German producers. |
| Engineered Yeast Strain Development | Novel fermentation pathways bypass traditional hydrogenation infrastructure for erythritol expansion. |
| Pharmaceutical Excipient Certification | NMPA and USP-NF classifications unlock premium positioning in direct-compression tablet applications. |
| Direct Procurement Relationship Building | Multi-year offtake agreements with bakery and confectionery groups displace distributor intermediaries. |
| Particle Engineering Capability Acquisition | European and Japanese equipment supplier partnerships secure crystallization control for premium grades. |
Research Methodology
Bottom-up bakery and beverage formulation modeling reconciled against top-down hydrogenation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at starch processing facilities, procurement leads at industrial confectionery groups, technical R&D directors at fermentation specialists, and pharmaceutical excipient quality officers combined with secondary validation from FDA GRAS notifications, EFSA novel food opinions, NMPA pharmaceutical standards, customs trade data, and SEC filings from diversified agricultural processors.
Input-output matrices map glucose feedstock availability through hydrogenation and fermentation pathways to end-use demand across food, pharmaceutical, and nutraceutical applications. Segmentation dimensions include polyol chemistry type, crystallization grade tier, end-use industry, and regional regulatory cluster. CAGRs derive from capacity expansion announcements, offtake agreement volumes, and reformulation timeline acceleration under disclosure mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA novel food registration timelines and glucose feedstock price volatility. Deviation in FDA enforcement posture on added-sugar labeling would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Date Sugar Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
South Korea Allulose Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
Glucose Syrup Market
Sweeteners
Sodium Saccharin Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
High-Fructose Corn Syrup (HFCS) Market
Sweeteners
Invert Sugar Market
Sweeteners
United States Xylitol Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Organic Palm Sugar Market
Sweeteners
Sucrose Esters Market