
 Metaverse Market | 2026-2036
Metaverse Market Size, Share, and Industry Trends Forecast 2026-2036
Metaverse Market Analysis
Cloud-native rendering pipelines are repositioning capital allocation away from on-premise GPU clusters toward distributed edge infrastructure. NVIDIA Corporation leverages its CUDA ecosystem to dominate high-fidelity simulation workloads. Microsoft Corporation anchors enterprise adoption through Azure-powered mixed reality services. Epic Games, Inc. specializes in real-time 3D engines that power both gaming and architectural visualization.
The metaverse comprises persistent, shared virtual environments rendered in real time, typically requiring sub-20 millisecond latency and spatial computing architectures that fuse optical waveguides with inertial measurement units. Its primary purpose is enabling synchronous digital presence for commerce, collaboration, and entertainment. Virtual Reality hardware still commands the highest unit margins among product types, though Mixed Reality is displacing pure VR in enterprise training. Gaming absorbs the majority of current end-user spending, while Healthcare applications are expanding fastest as surgical simulation gains reimbursement traction.
FCC spectrum allocations shape wireless bandwidth available for untethered headsets, while GDPR and the EU AI Act impose data residency and algorithmic transparency requirements on European deployments. The SEC scrutinizes tokenized virtual asset offerings as unregistered securities. Stakeholders must weigh regulatory fragmentation against the cost of region-specific compliance architectures.
Market Dynamics
Cloud-native rendering pipelines are redistributing capital from centralized GPU farms toward distributed edge nodes, while the EU AI Act imposes algorithmic transparency mandates that reshape liability for autonomous virtual environments.
Growth Catalysts
- Defense simulation contracts:The United States Department of Defense is accelerating procurement of persistent virtual training environments for joint-force exercises. These contracts mandate sub-20 millisecond latency standards that drive infrastructure investment.
- EU AI Act compliance frameworks:European liability clarity for autonomous virtual agents is prompting enterprise pilot programs in surgical simulation and industrial digital twins. Reimbursement pathways for medical training applications are formalizing.
- Optical waveguide miniaturization:Advances in photonic integrated circuits are reducing headset weight and power consumption. This materials breakthrough is expanding addressable use cases beyond gaming into all-day enterprise wear.
Market Restraints
- GPU supply concentration:Advanced semiconductor fabrication for real-time ray-tracing hardware depends on a concentrated foundry base in Taiwan. Geopolitical exposure constrains capacity expansion timelines.
- FCC spectrum scarcity:Millimeter-wave allocations for untethered VR remain limited in dense urban deployments. Wireless bandwidth constraints force trade-offs between fidelity and mobility.
- GDPR data residency costs:European mandates for local processing of biometric gaze-tracking data require redundant regional infrastructure. Compliance architecture adds 15-25% to deployment costs versus non-resident alternatives.
Strategic Opportunities
- India's skilling infrastructure:The country's PLI scheme for electronics manufacturing is attracting assembly investment for mid-tier headsets. Domestic cloud providers are building edge nodes to support regional latency requirements.
- Neural interface convergence:Integration of electromyography sensors with haptic feedback gloves is creating new input modalities for accessibility applications. This technology pairing opens healthcare rehabilitation segments.
- Japan's METI digital twin mandate:National infrastructure planning now requires 3D virtual replicas for urban development approvals. Architectural visualization platforms are pivoting to capture this regulatory-driven demand.
Industry Challenges
- Spatial computing talent scarcity:Engineers with simultaneous expertise in optical physics, real-time rendering, and human factors are concentrated at a handful of research institutions. Recruitment timelines for mixed reality teams now exceed 9 months.
- Legacy ERP integration friction:Enterprise metaverse deployments must synchronize with existing SAP and Oracle systems for asset management. API standardization gaps force custom middleware development.
- ISO/TS 9241-330 certification delays:Ergonomic safety testing for extended VR wear lacks harmonized international protocols. Product launch schedules slip 6-12 months awaiting multi-jurisdiction approval alignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metaverse Market |
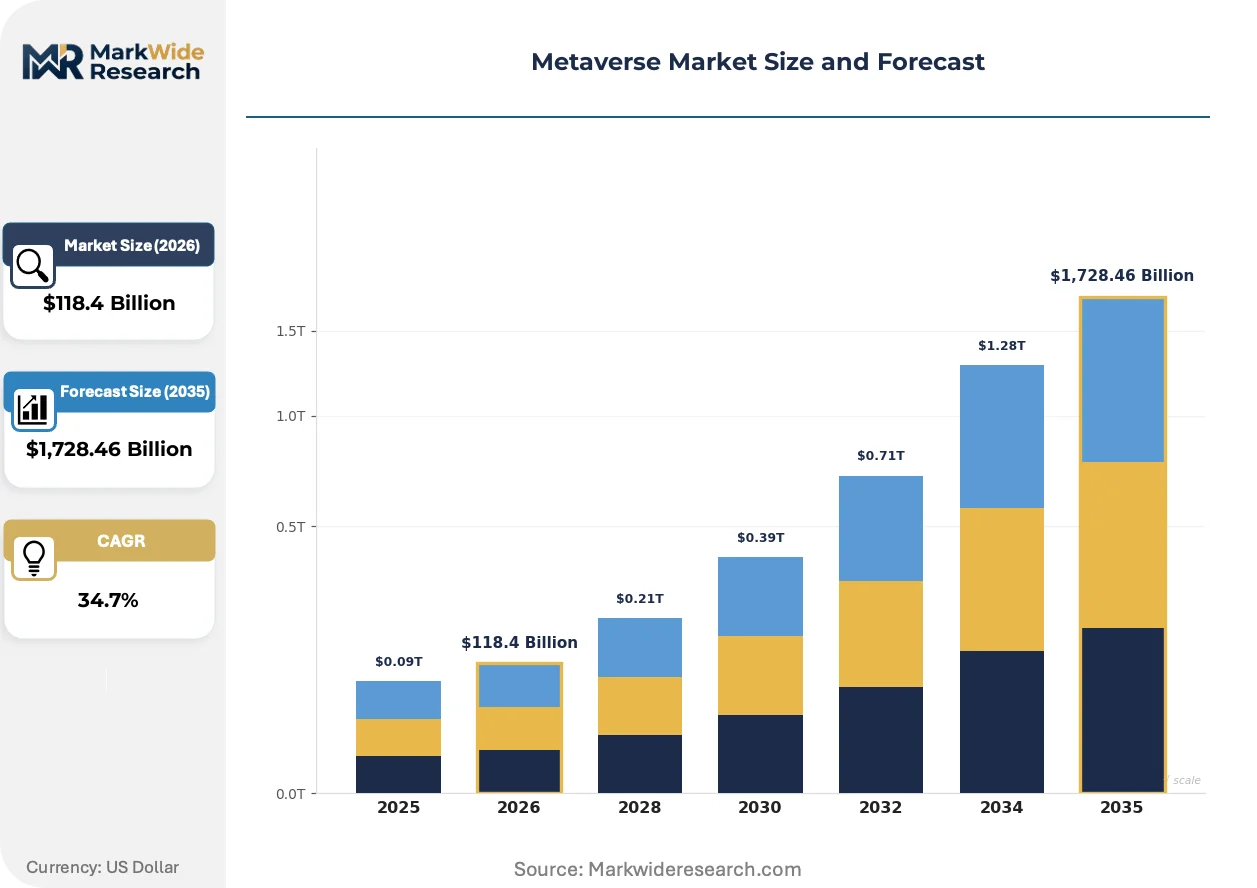
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $1,728.46 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality, Augmented Reality, Mixed Reality, Software End User: Gaming, Education, Healthcare, Real Estate Technology: Blockchain, 3D Modeling, Artificial Intelligence, Cloud Computing Application: Social Interaction, Virtual Events, E-commerce, Training |
| Companies Covered | Meta Platforms, Inc., Tencent Holdings Ltd., Microsoft Corporation, NVIDIA Corporation, Roblox Corporation, Epic Games, Inc., Alphabet, Inc., Unity Software Inc., Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metaverse Market Emerging Trajectories
Generative AI is compressing content production timelines for virtual environments, while regulatory fragmentation forces region-specific compliance architectures. Buyers are renegotiating procurement models to share infrastructure risk.
Foveated rendering powered by eye-tracking hardware is automating computational load distribution in real-time graphics pipelines. Surgical training centers in Germany and South Korea are adopting these systems to maintain photorealism at reduced hardware cost. The technology is automating the trade-off between visual fidelity and rendering expense that previously constrained mobile headset adoption.
REACH chemical restrictions on rare-earth magnet processing are forcing headset manufacturers to redesign actuator assemblies for haptic feedback. Industrial consequences include supply chain requalification cycles and alternative sourcing from Australian and Canadian mining operations. European assembly plants are most affected, with some relocating final integration to Switzerland to leverage Swissmedic-adjacent quality frameworks.
Enterprise buyers are consolidating vendor relationships from point-solution contracts to multi-year platform subscriptions with outcome-linked pricing. System integrators and value-added resellers are being displaced by direct cloud-provider relationships in the United States defense and healthcare verticals. This concentration is most visible in federal contracting, where three agencies now mandate single-platform standards for cross-agency virtual collaboration.
Metaverse Market Segmentation
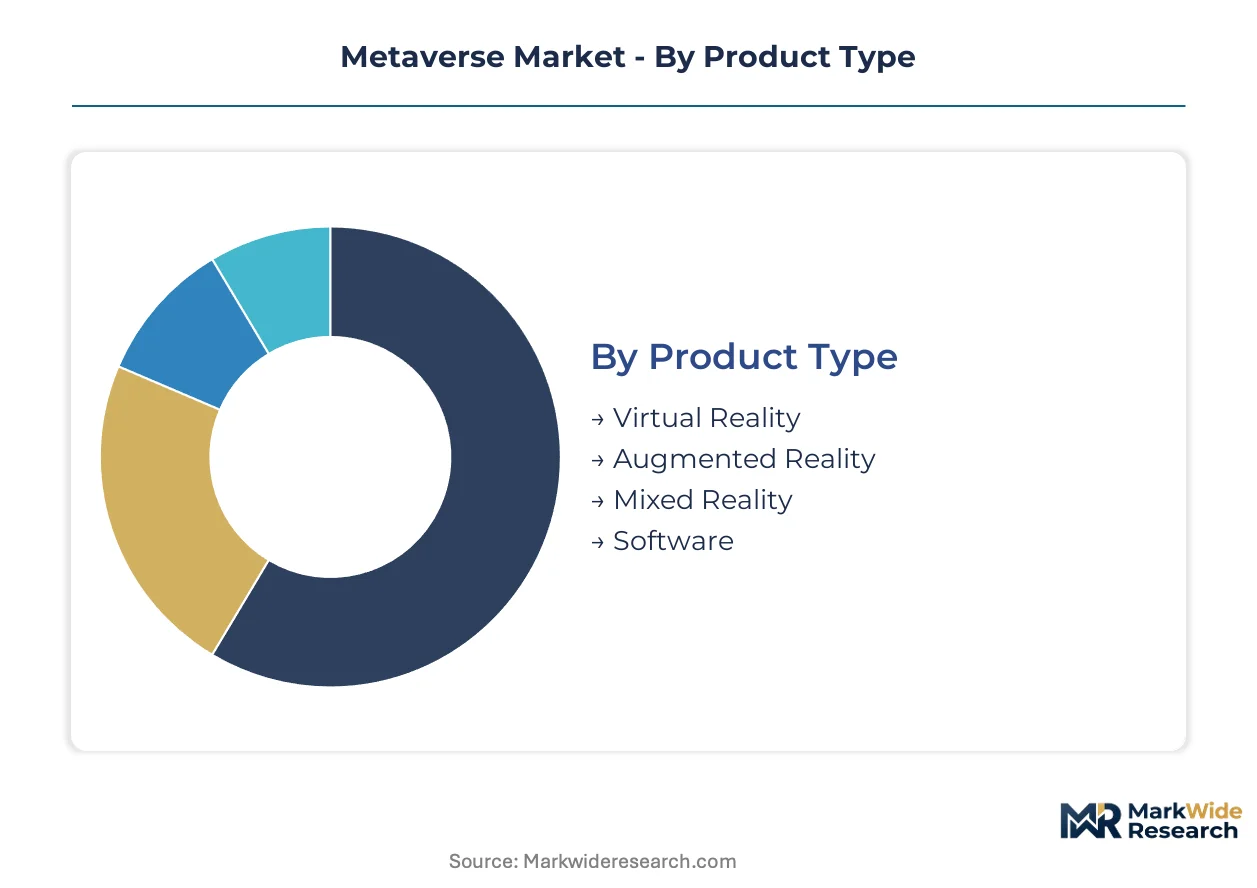
Segmentation reveals how certification burdens and latency requirements fragment procurement strategies across hardware, software, and service layers. Each dimension carries distinct regulatory footprints that reshape vendor selection criteria and deployment timelines.
Product Type:
Certification pathways diverge sharply: VR headsets face FCC emissions testing and ISO/TS 9241-330 ergonomic validation, while software layers navigate GDPR biometric data residency and EU AI Act algorithmic transparency mandates.
- Virtual Reality:Fully immersive headsets with sub-20 millisecond latency requirements demand FCC Part 15 certification for wireless transmission. Defense simulation contracts in the United States concentrate procurement volume here, though GPU supply constraints in Taiwan extend lead times.
- Mixed Reality:Optical waveguide architectures blending physical and digital layers require stricter eye-safety testing under IEC 62471 photobiological standards. Enterprise training budgets in Germany and South Korea are accelerating adoption for surgical simulation applications.
- Augmented Reality:Smartphone-dependent overlays face lighter hardware certification but heavier app-store content moderation. Consumer gaming absorbs majority spend.
- Software:Persistent world-building platforms must comply with GDPR data residency and SEC scrutiny of tokenized asset offerings. Cloud-native rendering pipelines dominate new deployments.
Virtual Reality sits at the top of the volume ranking, with Mixed Reality climbing the fastest.
End User:
Customer type determines reimbursement pathways and procurement cycle length, from consumer discretionary spend to formalized enterprise budgets with multi-year platform subscriptions.
- Gaming:Consumer discretionary spend absorbs the majority of current end-user revenue. Real-time 3D engines from Epic Games power both AAA titles and user-generated content platforms.
- Healthcare:Surgical simulation gains formal reimbursement traction in Germany and South Korea. FDA and EMA validation requirements for medical training applications extend sales cycles but lock in long-term contracts.
- Education:Institutional procurement lags enterprise adoption due to fragmented budget authority and lack of standardized learning outcome metrics.
- Real Estate:Architectural visualization pivots toward Japan's METI digital twin mandate for urban development approvals. Regulatory-driven demand creates predictable procurement pipelines.
Gaming commands the largest revenue pool, with Healthcare expanding most quickly as reimbursement formalizes.
Technology:
Technology layers stack vertically, with infrastructure components requiring capital-intensive certification and application layers facing lighter compliance but heavier competitive substitution.
- Cloud Computing:Distributed edge infrastructure demands local data center certifications varying by jurisdiction. GDPR residency requirements add 15-25% to European deployment costs versus alternatives.
- Artificial Intelligence:Autonomous virtual agents trigger EU AI Act liability frameworks and algorithmic transparency mandates. Enterprise pilot programs in surgical simulation and industrial digital twins are formalizing around these standards.
- Blockchain:Tokenized virtual asset offerings face SEC securities scrutiny and fragmented global regulatory treatment. Compliance architecture forces region-specific platform variants.
- 3D Modeling:Generative AI compression of content production timelines reduces labor intensity but raises intellectual property clearance burdens.
Cloud Computing anchors infrastructure investment, with Artificial Intelligence gaining share fastest as regulatory clarity emerges.
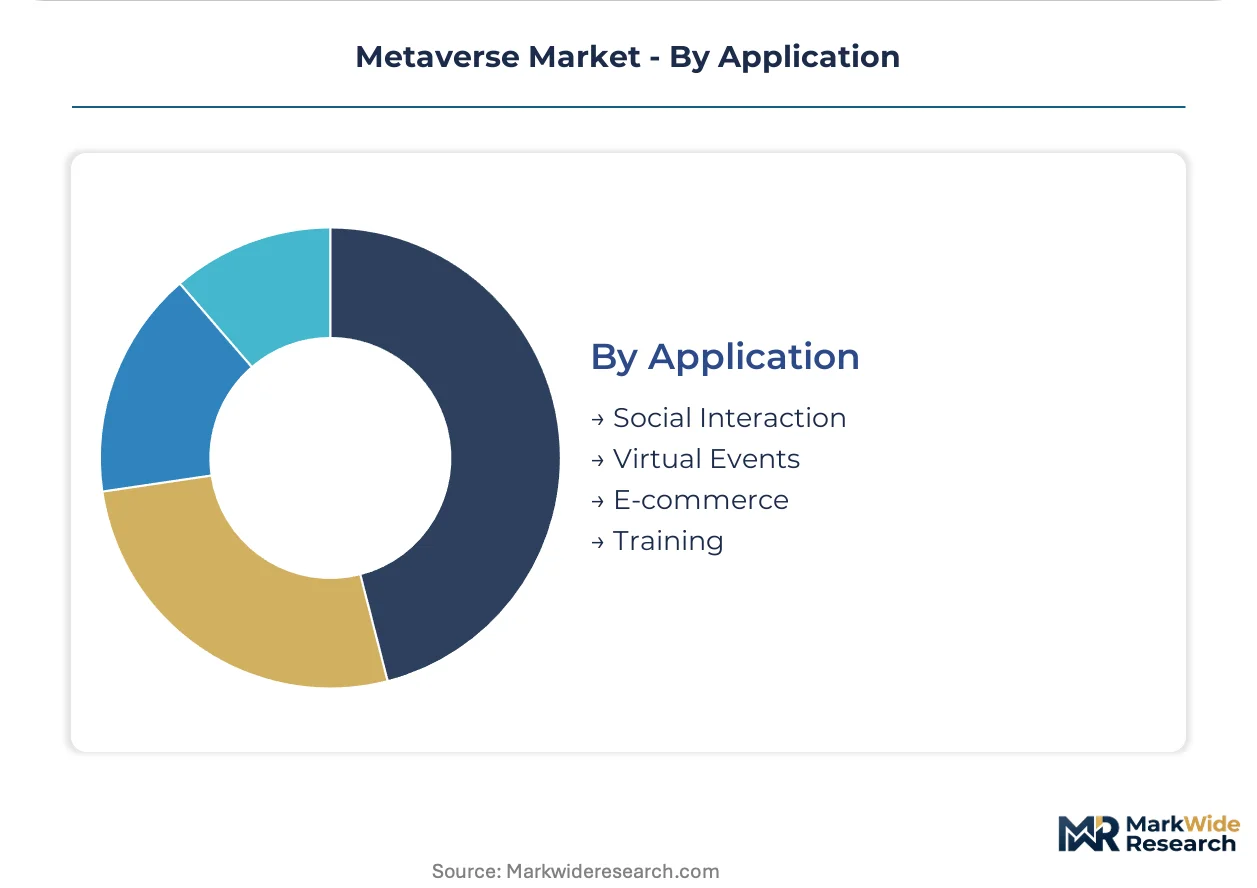
Application:
Application segments map directly to latency tolerance and synchronous presence requirements, with high-stakes training demanding stricter performance guarantees than social or commerce use cases.
- Training:Enterprise and defense applications mandate sub-20 millisecond latency with 99.99% uptime guarantees. United States Department of Defense contracts are consolidating around single-platform standards for joint-force exercises.
- Virtual Events:Conference and exhibition platforms pivoted from pandemic-driven demand toward hybrid persistent environments. Monetization models remain unsettled.
- Social Interaction:Consumer platforms face content moderation obligations under EU Digital Services Act and analogous frameworks. User acquisition costs exceed enterprise sales cycle investments.
- E-commerce:Virtual storefronts struggle with payment rail integration and return logistics for physical goods. Tokenized asset sales trigger securities regulatory exposure.
Training leads in average contract value, with Virtual Events recovering fastest as hybrid formats stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors cloud-native rendering infrastructure investment, while defense simulation contracts and enterprise training budgets concentrate procurement across distinct national regulatory environments. Market formation varies sharply by jurisdiction, with spectrum allocation, data residency mandates, and industrial policy sculpting deployment timelines.
United States
Department of Defense joint-force exercise contracts mandate sub-20 millisecond latency standards that drive edge infrastructure buildout. FCC millimeter-wave spectrum scarcity constrains untethered headset deployment in dense urban corridors. Seattle and Austin clusters host Azure-powered mixed reality service development for federal healthcare and defense verticals.
Germany
Surgical simulation centers in Munich and Heidelberg are formalizing reimbursement pathways for medical training applications. EU AI Act algorithmic transparency mandates reshape liability frameworks for autonomous virtual agents deployed in industrial digital twins. Bavaria's automotive engineering base is pivoting toward persistent virtual environments for factory planning approvals.
South Korea
Seoul's surgical training institutes adopt foveated rendering systems to maintain photorealism at reduced hardware cost. MFDS validation requirements for medical device software extend sales cycles but lock in long-term platform contracts. Pangyo Techno Valley hosts concentrated real-time 3D engine development for enterprise and consumer segments.
Japan
METI digital twin mandates for urban development approvals create predictable procurement pipelines for architectural visualization platforms. IEC 62471 photobiological standards for optical waveguide eye-safety testing slow product launch schedules. Tokyo and Osaka metropolitan areas concentrate mixed reality pilot programs for infrastructure planning.
India
PLI scheme incentives for electronics manufacturing attract mid-tier headset assembly investment. Domestic cloud providers build edge nodes in Mumbai and Bangalore to support regional latency requirements for enterprise training deployments. TRAI spectrum consultations shape wireless bandwidth availability for untethered device adoption.
Metaverse Market Vendor Landscape
Global majors compete with regional champions across cloud infrastructure, rendering hardware, and real-time engine licensing. Market structure tilts toward platform consolidation, with three to four entities capturing majority contract value in defense and healthcare verticals. Two archetypes dominate: vertically integrated hardware-software stacks and specialized engine licensors. Competitive moves center on direct cloud-provider relationships displacing system integrators, and multi-year platform subscriptions with outcome-linked pricing replacing point-solution contracts.
Within the vertically integrated tier, Meta Platforms, Inc. and Apple Inc. occupy positions exemplifying captive hardware-software-ecosystem control. Microsoft Corporation anchors enterprise adoption through Azure-powered service delivery. Among specialized engine providers, Epic Games, Inc. and Unity Software Inc. represent contrasting licensing models for real-time 3D content creation. NVIDIA Corporation sits within the infrastructure layer, with CUDA ecosystem dominance shaping high-fidelity simulation workload distribution.
| Leading Market Players |
|---|
| Meta Platforms, Inc. |
| Tencent Holdings Ltd. |
| Microsoft Corporation |
| NVIDIA Corporation |
| Roblox Corporation |
| Epic Games, Inc. |
| Alphabet, Inc. |
| Unity Software Inc. |
| Apple Inc. |
| Others |
Supply Flow & Price Mechanics
Spatial computing engineers concentrated in Silicon Valley and Seoul command compensation premiums that widen pricing spreads between premium-tier enterprise headsets and economy consumer devices. Labor-cost differentials between these talent clusters and emerging assembly hubs in India directly stratify final product pricing across certification tiers.
Pricing Analysis
Input-cost pass-through from optical waveguide components and GPU modules dominates pricing dynamics. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated surgical training systems from enterprise collaboration hardware and consumer gaming headsets. Price differentiation rests on ISO/TS 9241-330 ergonomic certification and GDPR-compliant data residency architecture. Pricing pressure stems from REACH chemical restrictions forcing rare-earth magnet redesigns in haptic actuators. Consumer gaming segments exhibit highest price sensitivity; defense simulation buyers show lowest elasticity due to mandated performance specifications.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan's concentrated foundry capacity for real-time ray-tracing semiconductors. Manufacturing draws from Taiwan, South Korea, and China for advanced photonic integrated circuits, rare-earth magnet processing, and precision actuator assembly. Raw material dependencies include gallium arsenide substrates, neodymium-iron-boron magnets, and specialized optical polymers. Tariff exposure on Chinese-sourced rare-earth elements compounds supply risk. Distribution runs through direct cloud-provider relationships displacing traditional system integrators in United States federal verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: India's PLI scheme offers 15-25% cost savings on European GDPR-compliant deployments versus domestic EU assembly.
For Market Incumbents: Deploy CUDA ecosystem lock-in as the defensive lever. NVIDIA anchors high-fidelity simulation workloads through proprietary parallel computing architecture that raises switching costs for defense and healthcare buyers. Incumbents should deepen backward integration into optical waveguide manufacturing to offset REACH-driven magnet supply disruptions. Consolidate procurement relationships around multi-year platform subscriptions before cloud providers displace remaining system integrators. For New Entrants and Emerging Players: Direct-to-developer channels through Epic Games' Unreal Engine marketplace offer lowest customer acquisition friction. White-space targets include India's domestic skilling infrastructure and Japan's METI-mandated urban digital twin segment. Surgical simulation reimbursement formalization in Germany and South Korea creates penetrable entry points without incumbent certification headwinds. Pursue outcome-linked pricing models that transfer infrastructure risk to enterprise buyers. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized haptic feedback glove developers lacking neural interface integration. Long-term viability favors entities with simultaneous optical physics, real-time rendering, and regulatory compliance capabilities. Acquisition target archetypes include mid-tier headset assemblers with Indian PLI qualification and Swissmedic-adjacent quality frameworks. Watch foveated rendering adoption rates in German surgical training centers as inflection indicator for hardware cost compression viability.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Rendering Migration | Azure-powered edge nodes reduce latency for United States Department of Defense joint-force exercises. |
| EU AI Act Compliance Certification | Algorithmic transparency mandates reshape liability for autonomous surgical simulation agents in Munich centers. |
| Optical Waveguide Miniaturization | Photonic integrated circuit advances enable all-day enterprise wear beyond gaming use cases. |
| Neural Interface Convergence | Electromyography-haptic pairing opens healthcare rehabilitation segments with accessibility applications. |
| Direct Federal Platform Standard | Single-platform mandates at three United States agencies consolidate vendor relationships and displace resellers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged cloud infrastructure architects, surgical training center directors, defense procurement officers, and optical waveguide manufacturing leads. Secondary validation drew from SEC hyperscaler capex disclosures, FCC spectrum allocation filings, FDA medical device submissions, and EU AI Act implementation guidance. Bottom-up segment sizing triangulated against top-down infrastructure investment forecasts.
Comparable-period anchoring linked projection models to historical cloud rendering deployment cycles and VR headset shipment patterns across prior technology transitions. Segmentation dimensions spanned hardware certification tier, software deployment model, end-use vertical latency requirements, and regional regulatory cluster. CAGRs derived from unit economics modeling of edge infrastructure buildout costs and reimbursement pathway formalization timelines. Forecast inputs incorporated GPU foundry capacity expansion schedules and REACH chemical restriction implementation phases.
The model assumes a particular technology adoption path; alternative pathways for foveated rendering or neural interface input would alter the outlook. Forecasts reflect assumptions about EU AI Act enforcement consistency and Taiwan foundry capacity stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global on-Demand Laundry Service Market
Others
Middle East and Africa Medium Voltage Switchgear Market
Others
Fluorite Market
Others
North America Commercial Vehicles Lubricants Market
Others
Global Simulation in Healthcare Market
Others
Coriolis Meters Market
Others
Aircraft Exterior Lighting Market
Others
Ultra Mobile Devices (UMD) Market
Others
North America Compressor Oil Market
Others
Augmented Reality in BFSI Market
Others
High-Performance Films Market
Others
Versatile Video Coding Market
Others
Global Sportswear Market
Others
Healthcare Bioconvergence Market
Others
Profiling Floats Market
Others
Football Sportswear Market