
 Healthcare Bioconvergence Market | 2026-2036
Healthcare Bioconvergence Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Bioconvergence Market Intelligence
The EU Green Deal is expanding sustainability mandates across pharmaceutical supply chains, forcing bioconvergence platforms to demonstrate reduced solvent use and biodegradable material inputs. Thermo Fisher Scientific leverages its global distribution network to sustain instrument revenue across gene therapy and synthetic biology workflows. Ginkgo Bioworks anchors its competitive position through automated foundry operations that lower cell engineering costs for contract customers. Galvani Bioelectronics specializes in bioelectronic medicine, competing against traditional small-molecule approaches for chronic disease management.
Healthcare bioconvergence denotes the integration of biological systems with engineering, computing, and materials science to create therapeutics, diagnostics, and regenerative platforms that function at molecular precision. Manufacturing relies on living cell cultures, programmable genetic circuits, and nanoscale fabrication to produce entities that self-assemble, sense physiological states, or execute therapeutic logic in vivo. Gene therapy product types command premium pricing due to complex CMC requirements and limited manufacturing capacity, while synthetic biology technology platforms attract venture funding for their scalability across multiple therapeutic modalities. Diagnostic tools represent a mature revenue base with steady hospital procurement cycles, whereas personalized medicine applications are capturing faster growth as reimbursement frameworks adapt to companion diagnostic requirements.
FDA gene therapy CMC guidance, EMA's ATMP framework, and ISO 13485 quality management standards collectively shape market access timelines and clinical trial design for bioconvergent products. Regulators on both sides of the Atlantic are tightening expectations for vector characterization, potency assays, and long-term follow-up protocols that add development cost but reduce safety liabilities. Stakeholders must monitor how FDA and EMA convergence or divergence on gene editing oversight reshapes platform investment decisions and geographic manufacturing placement.
Market Dynamics
Gene therapy CMC complexity is concentrating manufacturing investment among platforms capable of vector characterization at scale, forcing smaller developers toward contract relationships and reshaping competitive boundaries across therapeutic modalities.
Growth Catalysts
- NIH Funding Priorities:Federal research allocations in the United States are directing capital toward synthetic biology infrastructure, accelerating platform development for programmable genetic circuits.
- EU Green Deal Mandates:Sustainability requirements across pharmaceutical supply chains are pulling bioconvergence platforms toward reduced solvent use and biodegradable material inputs.
- Boston-San Diego Cluster Density:Geographic concentration of biotech talent and venture capital in these hubs is compressing development timelines for cell engineering startups.
Market Restraints
- Plasmid DNA Supply Bottleneck:Limited qualified manufacturers of GMP-grade plasmid DNA are creating input cost volatility for viral vector production.
- FDA Potency Assay Requirements:Evolving guidance on gene therapy release specifications is extending regulatory friction and validation timelines.
- Autologous Cell Therapy Manufacturing:Patient-specific production models face inherent technical limitations in batch standardization and scale economics.
Strategic Opportunities
- EMA ATMP Framework Expansion:Accelerated assessment pathways in Europe are creating regulatory tailwinds for first-in-class bioelectronic medicine submissions.
- Allogeneic Platform Pivot:Off-the-shelf cell therapies represent emerging application white space with manufacturing advantages over autologous approaches.
- Companion Diagnostic Integration:Reimbursement adaptation for personalized medicine is opening channel innovation for diagnostic-therapeutic combination products.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:The intersection of synthetic biology and electrical engineering requires hybrid skill sets that remain rare in labor markets.
- ISO 13485 Certification Burden:Quality management system implementation for convergent medical devices demands 18-24 month compliance timelines.
- Legacy IT Integration:Automated foundry operations face friction connecting with established pharmaceutical ERP and LIMS infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Bioconvergence Market |
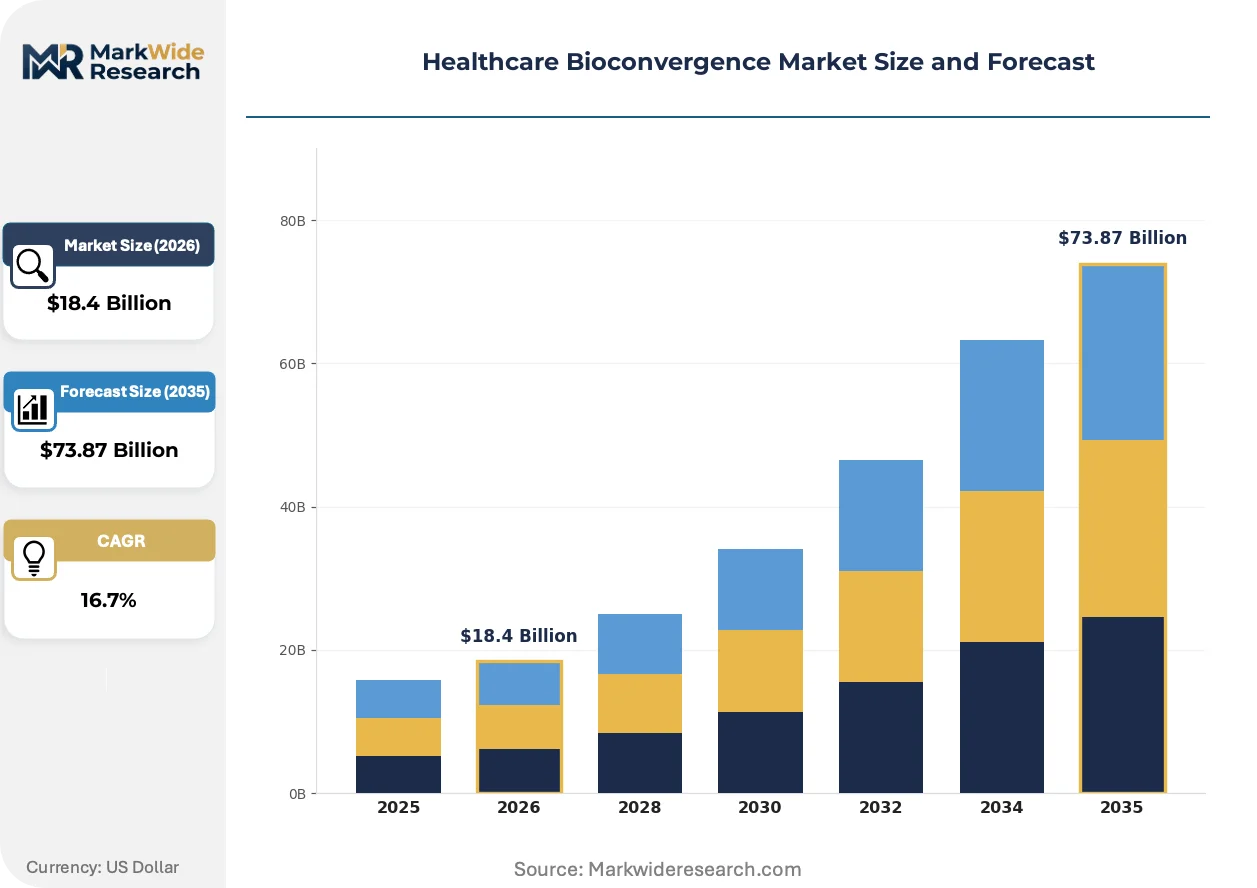
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $73.87 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopharmaceuticals, Biomaterials, Gene Therapy, Diagnostic Tools Technology: CRISPR, Nanotechnology, Synthetic Biology, Wearable Devices Application: Personalized Medicine, Regenerative Medicine, Drug Development, Clinical Diagnostics End User: Hospitals, Research Laboratories, Pharmaceutical Companies, Contract Research Organizations |
| Companies Covered | BiomX, SetPoint Medical Corporation, BICO - The Bio Convergence Company, BioConvergent Health, Galvani Bioelectronics, Ginkgo Bioworks, Singota Solutions, Thermo Fisher Scientific, Anima Biotech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Bioconvergence Market Strategic Shifts & Innovations
Computational design tools are compressing the cell engineering cycle from months to weeks, while regulatory frameworks on both sides of the Atlantic tighten around characterization standards for complex biologics.
Automated foundry operations are overtaking traditional contract research organization models for early-stage cell line development. Synthetic biology startups are adopting these platforms at accelerating pace to reduce iteration costs. The shift is overtaking conventional service-based relationships and compressing competitive moats around proprietary strain libraries.
EMA's ATMP framework revisions are tightening expectations for viral vector lot release and long-term follow-up protocols. These changes are extending development timelines but reducing downstream safety liabilities. Gene therapy sponsors in Europe are responding by front-loading CMC investment and securing dedicated manufacturing slots earlier in clinical development.
Hospital procurement for diagnostic platforms is fragmenting as specialized bioconvergence tools bypass traditional group purchasing organizations. Academic medical centers and integrated delivery networks are negotiating direct relationships with synthetic biology vendors for companion diagnostic workflows. This pattern is most visible in the United States, where NIH-funded institutions prioritize technology access over standardized purchasing contracts.
Healthcare Bioconvergence Market Segmentation
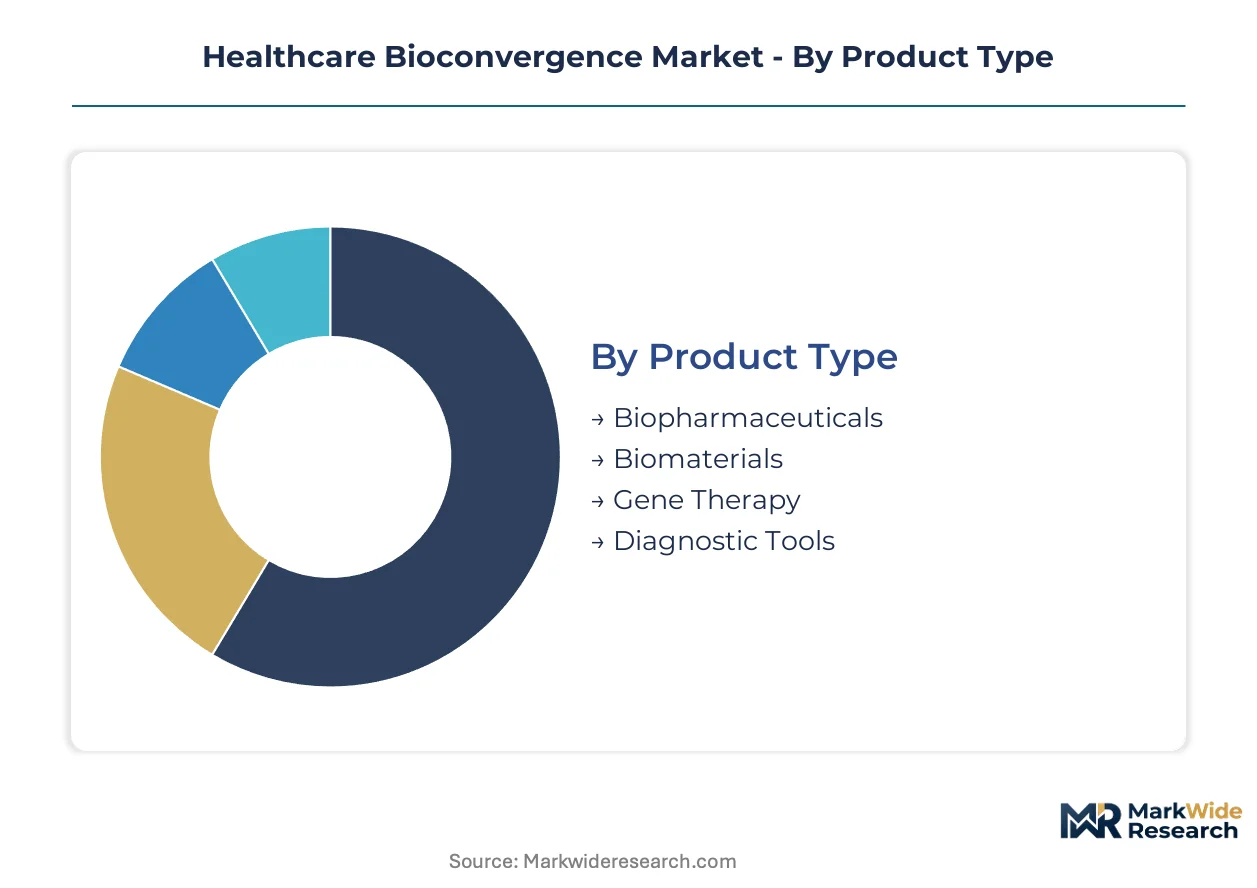
Bioconvergence market segmentation reveals distinct capital intensity profiles across product categories, with gene therapy platforms demanding vector manufacturing infrastructure while diagnostic tools leverage existing hospital procurement channels. Technology and application dimensions further stratify investment requirements, creating divergent competitive entry barriers.
Product Type:
Gene therapy platforms absorb the heaviest upfront capital, requiring viral vector manufacturing suites and GMP-grade plasmid DNA supply chains that strain balance sheets before commercial validation.
- Biopharmaceuticals:Engineered proteins and monoclonal antibodies produced through mammalian cell culture systems. Demand concentrates in Boston and San Diego biotech clusters where NIH-funded institutions prioritize programmable therapeutic platforms for oncology and autoimmune indications.
- Gene Therapy:Viral and non-viral vector systems delivering genetic payloads for inherited and acquired diseases. Manufacturing complexity limits qualified production capacity, forcing sponsors toward dedicated CMO relationships and early CMC investment under FDA guidance.
- Biomaterials:Scaffold structures and biodegradable substrates for tissue integration. Synthetic biology foundries in the United States are lowering iteration costs for contract customers seeking standardized material inputs.
- Diagnostic Tools:Molecular and companion diagnostic platforms for disease detection and patient stratification. Academic medical centers negotiate direct vendor relationships that bypass traditional group purchasing organizations.
Most installed capacity flows through biopharmaceuticals. Expansion is steepest in gene therapy.
Technology:
Platform selection determines regulatory pathway complexity, with CRISPR-based products facing evolving oversight frameworks across FDA and EMA jurisdictions while wearable devices navigate ISO 13485 certification timelines.
- CRISPR:Programmable nuclease systems for gene editing applications. EMA's ATMP framework revisions are extending development timelines but reducing downstream safety liabilities for European sponsors.
- Nanotechnology:Sub-micron delivery vehicles and sensing architectures. FDA potency assay requirements create validation friction that concentrates investment among platforms with established characterization protocols.
- Synthetic Biology:Automated foundry operations for cell engineering and genetic circuit design. Venture funding priorities in the United States are accelerating adoption across multiple therapeutic modalities.
- Wearable Devices:Bioelectronic interfaces for physiological monitoring and therapeutic intervention. Galvani Bioelectronics anchors competitive positioning in chronic disease management against traditional small-molecule approaches.
Manufacturing scale clusters around synthetic biology foundries. Regulatory tailwinds are strongest for CRISPR platforms.
Application:
Application segmentation tracks reimbursement adaptation speed, with personalized medicine capturing faster growth as companion diagnostic frameworks mature while regenerative medicine faces longer clinical validation cycles.
- Personalized Medicine:Patient-specific therapeutic and diagnostic combinations guided by molecular profiling. Reimbursement frameworks in the United States are adapting to companion diagnostic requirements, opening channel innovation for integrated product submissions.
- Regenerative Medicine:Cell-based therapies and tissue engineering platforms for structural repair. Autologous production models face inherent technical limitations in batch standardization that allogeneic approaches are beginning to address.
- Drug Development:Discovery and preclinical validation services leveraging convergent technologies. Contract research organizations absorb demand from pharmaceutical companies seeking externalized platform access.
- Clinical Diagnostics:Hospital and laboratory testing infrastructure for disease detection. Procurement cycles remain steady but fragmenting as specialized bioconvergence tools bypass traditional purchasing contracts.
Revenue concentration sits with clinical diagnostics. Share gains are fastest in personalized medicine.
End User:
End-user segmentation reflects divergent purchasing authority, with pharmaceutical companies commanding platform development budgets while research laboratories prioritize technology access over standardized contracts.
- Pharmaceutical Companies:Integrated drug developers scaling bioconvergent manufacturing platforms. Thermo Fisher Scientific sustains instrument revenue across gene therapy and synthetic biology workflows through global distribution reach.
- Research Laboratories:Academic and government institutions advancing foundational science. NIH funding priorities direct capital toward synthetic biology infrastructure in the United States.
- Hospitals:Integrated delivery networks and academic medical centers adopting diagnostic and therapeutic platforms. EU Green Deal mandates are forcing supply chain sustainability demonstrations for procurement eligibility.
- Contract Research Organizations:Externalized service providers for development and manufacturing. Automated foundry operations are overtaking traditional CRO models for early-stage cell line development.
Platform investment originates primarily with pharmaceutical companies. Adoption velocity is highest among research laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare bioconvergence traces its commercial lineage to the United States, where NIH-funded research institutions and venture capital networks first scaled synthetic biology platforms into therapeutic manufacturing. Geographic expansion now follows regulatory pathway clarity and clustered talent pools.
United States
Federal research allocations through the NIH direct capital toward programmable genetic circuits and automated foundry infrastructure. FDA gene therapy CMC guidance shapes development timelines and potency assay requirements for sponsors. Boston and San Diego biotech clusters compress development cycles for cell engineering startups through concentrated venture funding and institutional partnerships.
Germany
Industrial demand for precision manufacturing equipment drives adoption of bioconvergent production platforms across pharmaceutical supply chains. EMA's ATMP framework and EU Green Deal mandates force sustainability demonstrations for procurement eligibility. The Rhine-Ruhr and Munich regions host concentrated automation engineering talent serving contract manufacturing organizations.
United Kingdom
Academic medical centers negotiate direct vendor relationships for companion diagnostic workflows, bypassing traditional group purchasing organizations. MHRA alignment with EMA gene editing oversight frameworks influences platform investment decisions. The Golden Triangle of London, Oxford, and Cambridge anchors bioelectronic medicine research against traditional small-molecule approaches.
Switzerland
Swissmedic's rigorous quality standards attract sponsors seeking regulatory credibility for complex biologics submissions. Precision manufacturing heritage supports demand for nanoscale fabrication and scaffold engineering capabilities. The Basel-Zurich corridor concentrates pharmaceutical headquarters and contract research infrastructure.
Singapore
Government biomanufacturing initiatives attract synthetic biology platform operators seeking Asia-Pacific regional hubs. Alignment with international ISO standards facilitates export-oriented production for gene therapy vectors. The one-north research precinct clusters contract development talent alongside multinational pharmaceutical operations.
Healthcare Bioconvergence Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the Healthcare Bioconvergence Market. Foundry operators with automated cell engineering infrastructure face pressure from specialized developers outsourcing manufacturing to contract partners. Three archetypes dominate: integrated platform owners controlling proprietary strain libraries, instrument distributors sustaining revenue across workflow categories, and bioelectronic medicine specialists competing against pharmacological interventions. Competitive moves concentrate on securing dedicated manufacturing slots early in clinical development and front-loading CMC investment to compress regulatory timelines.
Within the integrated platform tier, Ginkgo Bioworks and BICO - The Bio Convergence Company exemplify divergent approaches to automated foundry scale. Thermo Fisher Scientific occupies a position bridging instrument supply and global distribution reach across gene therapy and synthetic biology workflows. Galvani Bioelectronics anchors the bioelectronic medicine archetype, representing competitive positioning against traditional therapeutic modalities for chronic disease management.
| Leading Market Players |
|---|
| BiomX |
| SetPoint Medical Corporation |
| BICO - The Bio Convergence Company |
| BioConvergent Health |
| Galvani Bioelectronics |
| Ginkgo Bioworks |
| Singota Solutions |
| Thermo Fisher Scientific |
| Anima Biotech Inc. |
| Others |
Cost & Logistics Intelligence
Pharmaceutical companies with dedicated gene therapy pipelines command substantial pricing leverage through early manufacturing slot commitments and CMC investment front-loading. Their procurement concentration around qualified viral vector facilities creates tiered access structures where sponsors securing dedicated capacity extract preferential terms from contract manufacturing organizations.
Pricing Analysis
Project-based pricing with milestone-linked payments dominates gene therapy platform transactions, separating early-stage cell engineering from commercial-scale vector production. Price differentiation rests on GMP certification tier and manufacturing scale, with FDA-registered facilities commanding premiums over pre-qualified operations. Cost compression in autologous cell therapy manufacturing is intensifying because batch standardization failures force rework and waste. Academic medical centers exhibit highest price sensitivity due to fixed NIH grant funding, while commercial-stage biopharmaceutical sponsors prioritize speed over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from gene therapy sponsors require qualified plasmid DNA suppliers in both the United States and Germany to mitigate single-source vulnerability. Raw material dependencies center on GMP-grade plasmid DNA, specialized cell culture media, and chromatography resins. Supply chain risk concentrates in viral vector manufacturing capacity constraints that extend lead times for clinical-grade material. Distribution runs through temperature-controlled logistics networks connecting foundry operations to sponsor quality release facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Healthcare Bioconvergence Market functions as a geographic-arbitrage opportunity between United States NIH funding density and European EMA accelerated assessment pathways, with regulatory timeline differentials creating cost-of-capital spreads for platform developers.
For Market Incumbents: Cement proprietary strain library advantages through automated foundry capacity expansion in Boston and San Diego clusters. Secure dedicated manufacturing slots for gene therapy vector production to preempt competitor access. The emerging threat of allogeneic platform pivots demands defensive patent positioning around off-the-shelf cell engineering protocols. For New Entrants and Emerging Players: Enter via bioelectronic medicine applications where Galvani Bioelectronics has validated reimbursement pathways but not saturated therapeutic indications. The United Kingdom Golden Triangle presents the most penetrable geography given MHRA alignment with EMA frameworks and academic medical center procurement fragmentation. A direct hospital system partnership model bypasses traditional group purchasing organization gatekeeping. For Investors and Strategic Acquirers: Pharmaceutical companies with gene therapy pipeline gaps are the most active acquirer in this space, seeking automated foundry capabilities to internalize CMC complexity. Long-term viability hinges on platform adaptability across multiple therapeutic modalities rather than single-product dependency. The signal to watch is FDA-EMA convergence or divergence on gene editing oversight, which would reshape geographic manufacturing placement decisions materially.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Foundry Scale-Up | Ginkgo Bioworks and BICO compress cell engineering iteration costs for contract customers through proprietary infrastructure. |
| EMA ATMP Accelerated Pathway | Galvani Bioelectronics leverages European regulatory tailwinds for first-in-class bioelectronic medicine submissions ahead of FDA timelines. |
| Companion Diagnostic Integration | Thermo Fisher Scientific sustains instrument revenue across gene therapy workflows by embedding diagnostic-therapeutic combination products. |
| GMP Plasmid DNA Supply Agreement | Singota Solutions addresses input cost volatility through qualified manufacturer relationships securing viral vector production inputs. |
| ISO 13485 Certification Investment | Wearable device developers reduce 18-24 month compliance timelines through early quality management system implementation. |
Research Approach
Multiple input streams — primary interviews with regulatory affairs leads, CMC executives, and hospital procurement managers; secondary validation against FDA filings, EMA submissions, and ClinicalTrials.gov records; and bottom-up platform capacity modeling reconciled with top-down venture funding flow analysis — were integrated to construct market estimates. Cross-referencing sponsor-reported manufacturing timelines with foundry operator utilization rates enabled triangulation of capacity-constrained segment growth.
Historical capacity expansion patterns were cross-referenced against expert panel inputs on vector manufacturing yield improvements across the projection horizon. Segmentation dimensions modeled include product type, technology platform, application area, and regional regulatory cluster complexity. CAGRs were derived from fitted growth curves incorporating NIH funding allocation trajectories and EMA ATMP approval velocity trends. Industry-specific forecast inputs encompass plasmid DNA supply expansion schedules and automated foundry deployment pipelines.
Inputs from regulatory filing databases and institutional procurement records were available through the study window; gaps in real-time manufacturing utilization rates introduce uncertainty bands around capacity-constrained segment projections. Deviation in FDA gene therapy CMC guidance finalization timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
High-Performance Films Market
Others
Asia-Pacific Medical Simulation Market
Others
Global Fertility Tracking Apps Market
Others
Mexico Retail Market
Others
United States Cigarette Market
Others
Convenience Stores Market
Others
Global Digital Market
Others
Smart Plug Market
Others
Global Pregnancy Tracker Apps Market
Others
Coloring Apps Market
Others
Drum Motor Market
Others
Japan Coal Market
Others
Global Snow Sports Apparel Market
Others
Channel-In-A-Box (Ciab) Market
Others
Advanced Combat Helmet Market
Others
Fenoxanil Market