
 Middle East and Africa Medium Voltage Switchgear Market | 2026-2036
Middle East and Africa Medium Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Medium Voltage Switchgear Market Insights
Capital-intensity divergence between integrated manufacturers and assembly-focused regional firms is redrawing competitive boundaries in the Middle East and Africa Medium Voltage Switchgear Market. ABB Ltd. leverages its global manufacturing footprint to supply gas-insulated systems for Gulf utility tenders. Schneider Electric SE anchors its position through localized production hubs serving North African markets. Siemens AG competes on digital switchgear platforms that integrate grid automation software with hardware.
Medium voltage switchgear encompasses electrical equipment designed to control, protect, and isolate power circuits operating between 1 kV and 52 kV, typically employing vacuum or SF6 interruption technology within metal-enclosed assemblies. These systems form critical nodes in distribution networks, substations, and industrial facilities where reliable fault clearing prevents cascading outages. Air insulated switchgear retains cost advantages for outdoor substations in arid climates across the Middle East, while gas insulated variants command premium positioning where space constraints dominate in dense African urban centers. Digital technology adoption is accelerating fastest among utility end users seeking remote monitoring capabilities, though conventional electromechanical protection still occupies substantial share in price-sensitive procurement cycles.
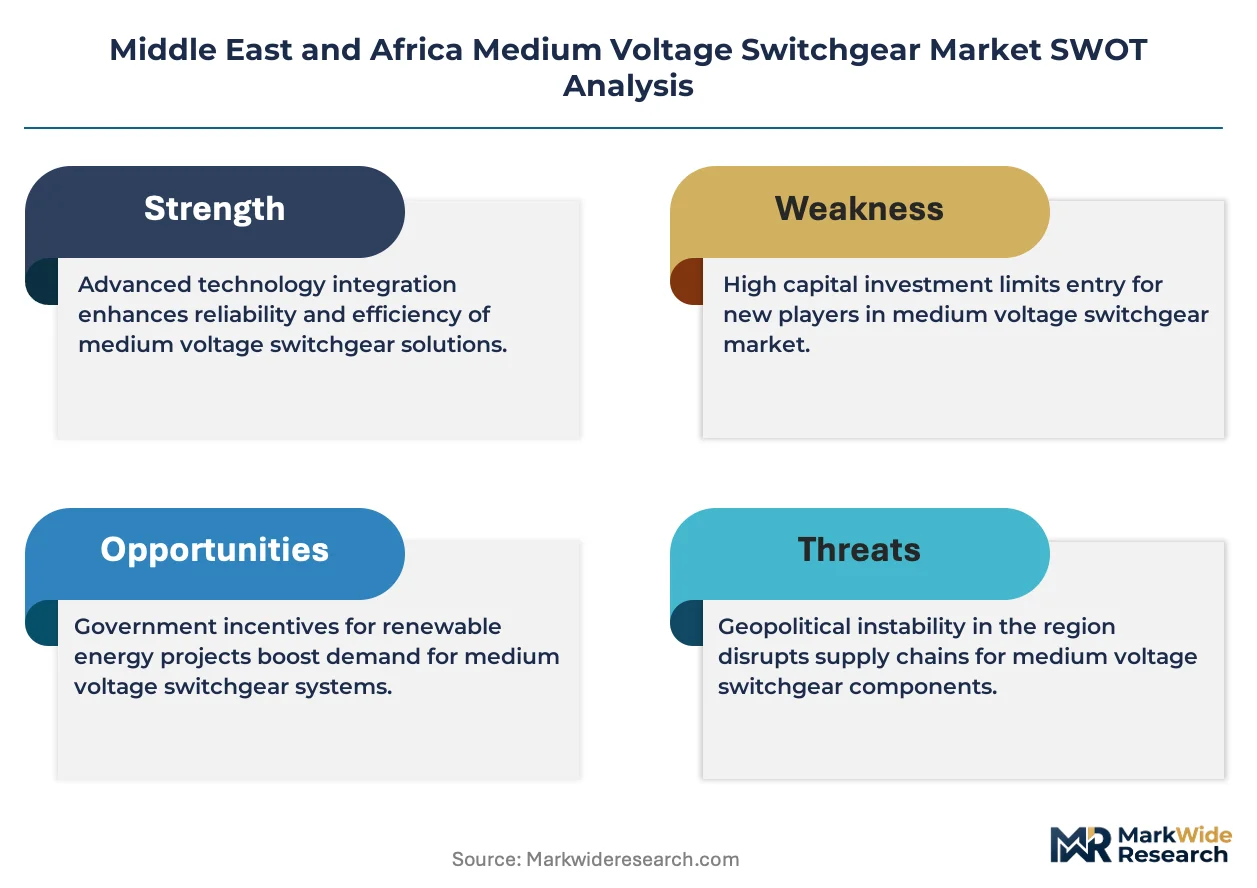
SASO in Saudi Arabia and NERSA in South Africa enforce divergent certification pathways that fragment product homologation timelines for manufacturers serving both markets. IEC 62271 standards provide baseline harmonization, yet local content requirements and ambient temperature derating rules force design modifications. Stakeholders must monitor how Egypt's regulatory authority and the UAE's ESMA adapt their technical codes to accommodate smart grid interoperability demands without creating additional market access barriers.
Market Dynamics
Grid modernization mandates across the Middle East and Africa are compressing procurement cycles for medium voltage switchgear as utilities race to integrate distributed solar and urban load centers. This structural pressure is redrawing supplier relationships and technical specifications simultaneously.
Growth Catalysts
- SASO Technical Regulations:Saudi Arabia's tightened certification standards for electrical equipment are forcing quality upgrades that benefit established manufacturers with testing capabilities. Utilities now specify IEC 62271 compliance as baseline for tender participation.
- Renewable Integration Targets:Utility-scale solar and wind deployments in Morocco and Egypt require new substation infrastructure. Switchgear orders from renewable project developers are outpacing traditional fossil-fuel plant procurement.
- Urban Load Concentration:Rapid city expansion in Lagos, Nairobi, and Dubai is driving underground distribution network investments. Gas-insulated switchgear captures preference where land scarcity dominates substation planning.
Market Restraints
- Copper and Aluminum Volatility:Raw material price swings for conductor metals compress margins on fixed-price tenders. Regional assemblers lack hedging instruments available to integrated multinationals.
- SF6 Regulatory Pressure:Environmental scrutiny of sulfur hexafluoride insulation is tightening across European-influenced North African markets. Vacuum interruption technology faces performance limitations at higher voltage classes.
- Import Dependency:Core components including vacuum interrupters and cast resin transformers concentrate supply in East Asian manufacturing hubs. African buyers absorb extended lead times and currency exposure.
Strategic Opportunities
- Ethiopia and Tanzania Grid Expansion:Underpenetrated East African markets are executing rural electrification programs with World Bank financing. Medium voltage distribution infrastructure lags generation capacity additions.
- Digital Switchgear Convergence:Integration of IoT sensors with traditional protection relays creates recurring revenue streams. Remote monitoring capabilities command 15-25% price premiums over electromechanical equivalents.
- UAE Smart Grid Mandates:ESMA interoperability standards are accelerating communication-protocol standardization. Vendors with certified digital platforms secure preferred supplier status with Dubai Electricity and Water Authority.
Industry Challenges
- Protection Relay Programming Expertise:Shortage of technicians fluent in IEC 61850 communication standards delays commissioning. Training programs at South African technical universities cannot match deployment timelines.
- Multi-Standard Certification Burden:Divergent ambient temperature derating rules between Gulf Cooperation Council and Sub-Saharan African markets force product variant proliferation. Engineering teams maintain parallel design tracks.
- Legacy Electromechanical Fleet Integration:Utilities with installed bases of mechanical protection resist full digital retrofits. Hybrid upgrade paths require custom engineering that erodes project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Medium Voltage Switchgear Market |
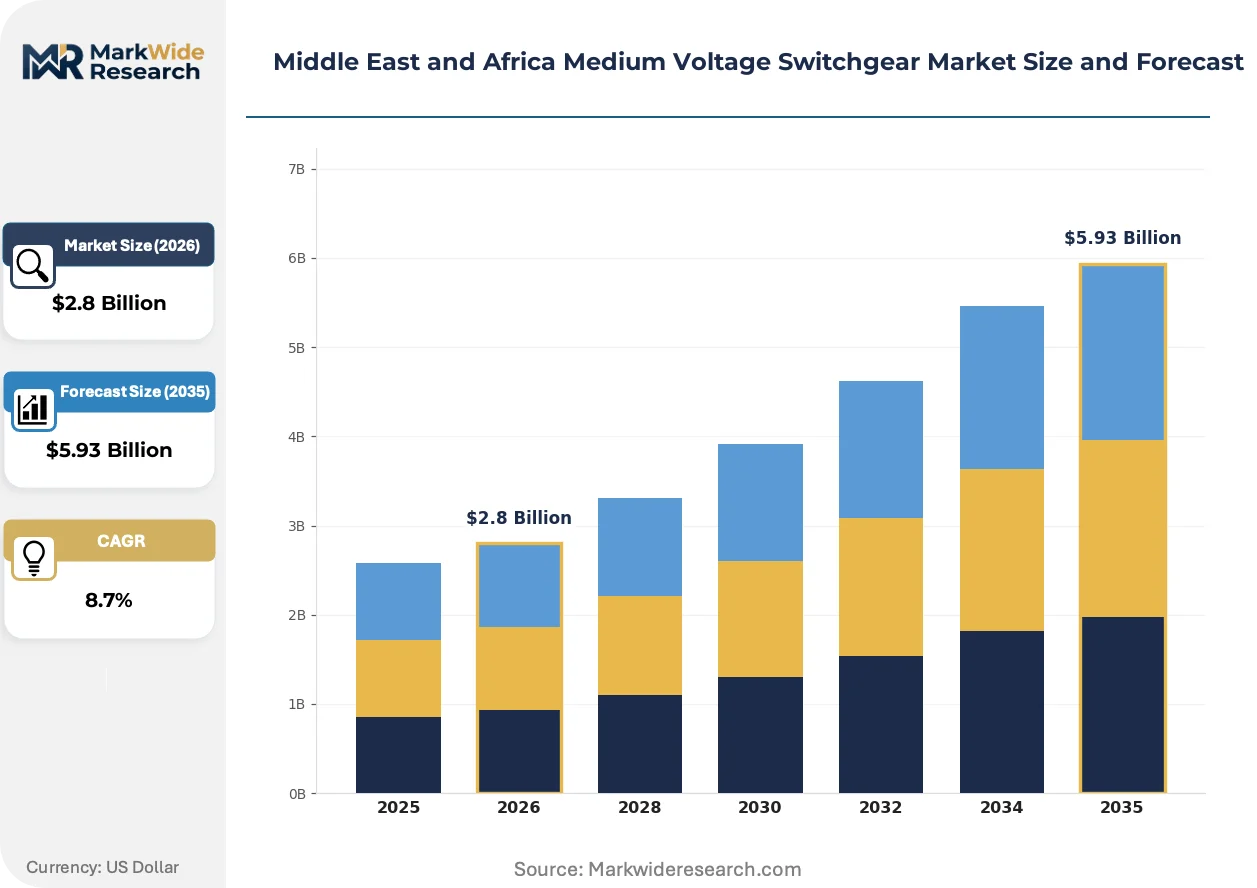
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Insulated, Air Insulated, Hybrid, Others Installation Type: Indoor, Outdoor, Modular, Compact End User: Utilities, Industrial, Commercial, Infrastructure Technology: Digital, Conventional, Automated, Smart |
| Companies Covered | ABB Ltd., Schneider Electric SE, Siemens AG, Eaton Corporation Plc., Alfanar Group, Havells Group, Hitachi Industrial Equipment Systems Co. Ltd., Mitsubishi Electric Corporation, Al Ahelia Switchgear Co., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Medium Voltage Switchgear Market Trends and Innovations
Modular substation architectures are displacing conventional brick-and-mortar construction across arid Middle Eastern environments. This shift is compressing project timelines and altering competitive positioning between switchgear suppliers and EPC contractors.
Digital twin technology is decomposing traditional switchgear specification workflows. Engineering teams at Saudi Aramco and ADNOC now simulate thermal and electrical performance before physical procurement. This capability compresses design validation cycles and reduces field modification costs. Equipment vendors without simulation partnerships lose technical specification influence.
NERSA's grid code revisions in South Africa are mandating distributed energy resource interoperability for new substation investments. These standards force switchgear suppliers to certify communication interfaces with inverter-based generation. Municipal distributors in Cape Town and Johannesburg now reject tenders lacking certified smart grid compatibility. Compliance costs favor suppliers with established local testing relationships.
Consolidated procurement by Gulf utility holding groups is compressing supplier margins while extending contract durations. Abu Dhabi National Energy Company and Saudi Electricity Company now negotiate multi-year framework agreements covering switchgear, transformers, and services. This pattern displaces project-by-project competition and rewards scale. Regional assembly specialists without manufacturing depth struggle to meet total-cost-of-ownership evaluation criteria.
Middle East and Africa Medium Voltage Switchgear Market Segmentation
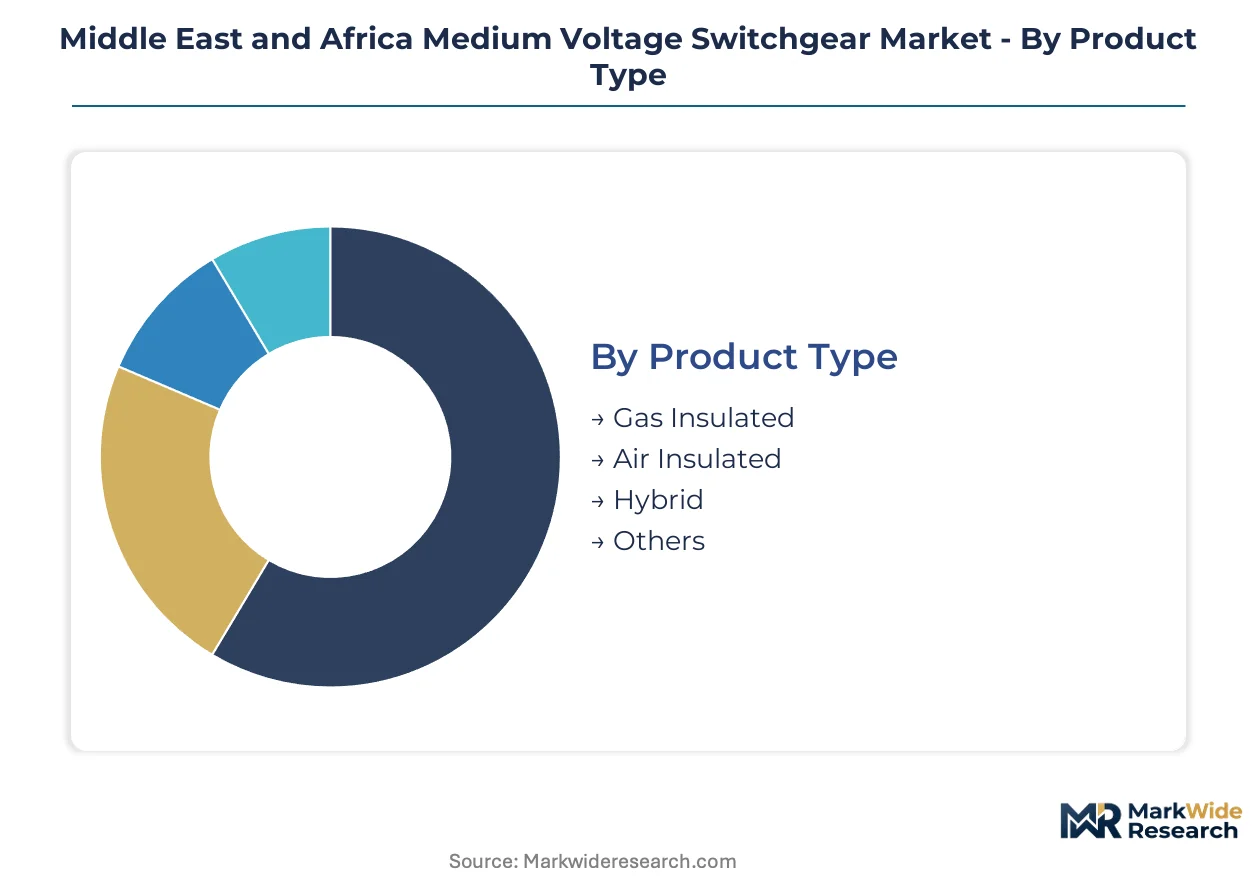
Segmentation in the Middle East and Africa Medium Voltage Switchgear Market reveals how procurement channels fragment across utility tenders, industrial direct sales, and contractor-mediated projects. Each dimension—product technology, installation environment, end-use application, and intelligence level—carries distinct margin profiles and certification requirements that reshape supplier priorities.
Product Type:
Channel concentration varies sharply by insulation technology, with gas-insulated systems flowing primarily through EPC contractors serving dense urban substations while air-insulated variants dominate utility direct procurement for transmission extensions.
- Gas Insulated:Sulfur hexafluoride or fluoronitrile-insulated switchgear occupies minimal footprint through three-phase common tank designs. Demand clusters in Dubai, Riyadh, and Lagos where land scarcity forces underground substation deployment. SF6 regulatory pressure in North African markets is accelerating vacuum interruption migration in lower voltage classes.
- Air Insulated:Open-air conductor arrangements with porcelain or composite insulators withstand ambient temperatures exceeding 50°C without derating penalties. Saudi Electricity Company and Eskom specify these for outdoor transmission substations across arid zones where maintenance access remains uncomplicated.
- Hybrid:Combines gas-insulated busbars with air-insulated circuit breakers to balance footprint reduction against capital constraints. Moroccan ONEE and Egyptian EETC have specified hybrid configurations for renewable integration substations.
- Others:Solid-insulated switchgear using epoxy resin or thermoplastic housings addresses SF6 phase-out mandates in European-influenced procurement.
Air Insulated dominates installed base across the region's transmission corridors. Gas Insulated is where expansion concentrates as urban load centers densify.
Installation Type:
Cost tier separation runs deepest here, with indoor specifications commanding 40-60% premiums over outdoor equivalents due to civil works and climate conditioning requirements.
- Indoor:Metal-enclosed assemblies housed in purpose-built substation buildings require HVAC conditioning against sand infiltration and humidity. UAE and Saudi utilities specify these for coastal installations where salt fog accelerates corrosion.
- Outdoor:Weatherproof enclosures with IP54+ ratings accommodate direct exposure across North African and Sub-Saharan climates. South Africa's municipal distributors favor these for rural electrification extensions where building costs prove prohibitive.
- Modular:Prefabricated skid-mounted substations compress commissioning timelines from months to weeks. ADNOC and Saudi Aramco have adopted modular architectures for remote oilfield power distribution.
- Compact:Reduced-dimension designs for urban retrofit applications where existing substation footprints cannot expand. Nairobi and Lagos utilities specify these for downtown network reinforcement.
Outdoor configurations retain volume leadership across the region's vast geographic spread. Modular solutions are climbing the fastest as project timelines compress.
End User:
Customer type determines specification authority, with utilities maintaining centralized technical standards while industrial buyers prioritize operational continuity over first cost.
- Utilities:Grid operators including Saudi Electricity Company, DEWA, and Eskom specify IEC 62271 compliance with localized ambient temperature deratings. Procurement runs through multi-year framework agreements covering thousands of bays.
- Industrial:Mining, petrochemical, and cement operations demand arc-flash resistant designs with extended mechanical endurance. Sasol and Ma'aden specify vacuum interruption for high-switching-frequency process loads.
- Commercial:Data centers, hospitals, and airports require dual-source configurations with transfer switching capabilities. Dubai's aviation and hospitality sectors drive demand for compact indoor installations.
- Infrastructure:Metro systems, ports, and desalination plants need corrosion-resistant specifications for harsh operational environments. Riyadh Metro and Doha Metro projects have absorbed significant gas-insulated volumes.
Utilities command the largest absolute procurement volumes. Industrial end-use is gaining share fastest as private power generation expands.
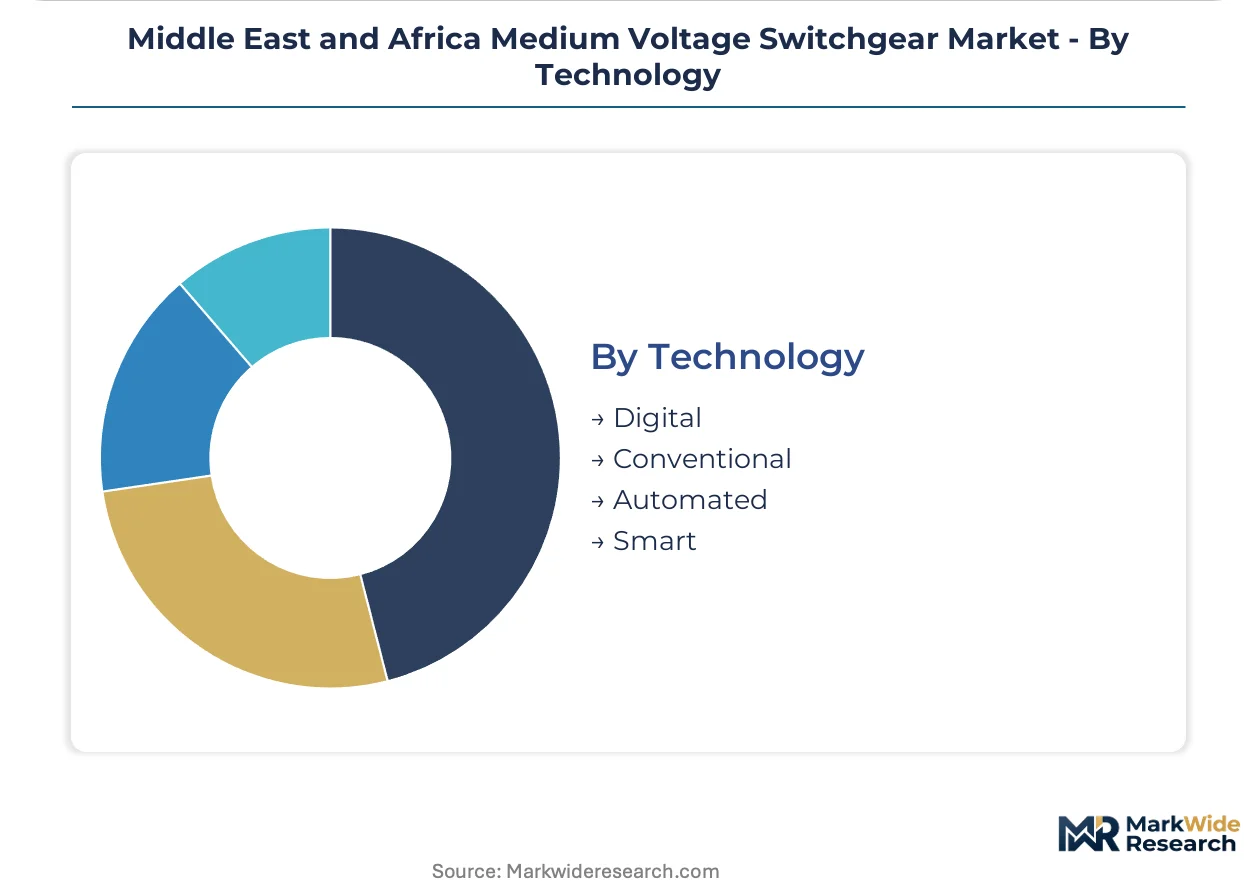
Technology:
Maturity gradients separate legacy electromechanical protection from digitally native platforms, with margin structures inverting as software and service content rises.
- Digital:IEC 61850-compliant platforms with embedded sensors and edge computing enable predictive maintenance and remote diagnostics. DEWA's smart grid roadmap mandates digital compatibility for all new substation investments.
- Conventional:Electromechanical protection relays and discrete instrumentation maintain lowest first cost. South African municipal distributors with constrained capital budgets continue specifying these for greenfield rural extensions.
- Automated:Programmable logic controllers and SCADA integration enable unmanned substation operation. Moroccan ONEE deploys these for solar farm collector substations in remote desert locations.
- Smart:AI-enabled fault prediction and self-healing grid algorithms represent the intelligence frontier. Saudi Arabia's Vision 2030 smart city initiatives are piloting these at NEOM and The Line.
Conventional technology retains the deepest installed base across legacy utility fleets. Digital platforms are where supplier investment and utility specification pressure now converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Middle East and Africa diverge sharply between Gulf utilities prioritizing space-constrained urban infrastructure and Sub-Saharan operators extending rural distribution networks with cost-optimized outdoor specifications.
Saudi Arabia
Saudi Electricity Company drives demand through giga-project electrification and renewable integration mandates under Vision 2030. SASO technical regulations enforce IEC 62271 compliance with ambient temperature deratings above 50°C. NEOM and The Line developments in the northwest are specifying digital switchgear platforms for smart city infrastructure.
United Arab Emirates
Dubai Electricity and Water Authority and Abu Dhabi National Energy Company consolidate procurement through multi-year framework agreements covering substation equipment. ESMA interoperability standards mandate smart grid compatibility for new installations. Dubai's metro extensions and data center clusters absorb premium gas-insulated volumes in dense coastal zones.
South Africa
Eskom's transmission expansion and municipal distributor rehabilitation programs sustain procurement despite fiscal constraints. NERSA grid code revisions mandate distributed energy resource interoperability for new substation investments. Cape Town and Johannesburg utilities now reject tenders lacking certified communication interfaces with inverter-based generation.
Egypt
Egyptian Electricity Transmission Company accelerates substation construction to accommodate utility-scale solar deployments in Benban and Kom Ombo. The country's regulatory authority adapts technical codes to accommodate smart grid interoperability demands. New administrative capital construction east of Cairo is driving compact switchgear specifications for underground distribution.
Morocco
ONEE executes rural electrification programs and renewable integration substations with World Bank financing support. Ambient derating rules for desert climates force design modifications distinct from Gulf specifications. Ouarzazate solar complex and Atlantic port expansions are absorbing hybrid switchgear configurations balancing footprint reduction against capital constraints.
Middle East and Africa Medium Voltage Switchgear Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Middle East and Africa Medium Voltage Switchgear Market. European-headquartered electrical equipment majors anchor the premium segment through gas-insulated and digital platform offerings. Regional assembly specialists compete on price-sensitive tenders with localized production hubs. Strategic moves concentrate on framework agreement consolidation with Gulf utility holding groups and certification investments to meet divergent SASO and NERSA requirements.
Among the integrated tier, ABB Ltd. and Schneider Electric SE exemplify archetypes competing through global manufacturing footprints versus localized production strategies. Siemens AG occupies a position emphasizing digital convergence with grid automation software. Alfanar Group and Al Ahelia Switchgear Co. represent Middle East-based specialists leveraging proximity to Saudi and UAE procurement centers. Eaton Corporation Plc. and Havells Group sit within the diversified electrical equipment category with broader portfolio exposure beyond switchgear specialization.
| Leading Market Players |
|---|
| ABB Ltd. |
| Schneider Electric SE |
| Siemens AG |
| Eaton Corporation Plc. |
| Alfanar Group |
| Havells Group |
| Hitachi Industrial Equipment Systems Co. Ltd. |
| Mitsubishi Electric Corporation |
| Al Ahelia Switchgear Co. |
| Others |
Pricing and Supply Chain Analysis
Multi-year framework agreements with Saudi Electricity Company and Dubai Electricity and Water Authority lock in supply access for gas-insulated systems while providing price visibility across volatile copper and aluminum cycles. These contracts insulate integrated manufacturers from spot market swings that compress regional assemblers operating on fixed-price tenders.
Pricing Analysis
Project-based procurement dominates utility tenders across the Gulf Cooperation Council, with pricing stratifying across premium, standard, and economy tiers based on IEC 62271 certification grade and after-sales service bundling. SASO compliance costs widen spreads between certified multinationals and uncertified regional suppliers. Cost compression in the economy tier is intensifying because raw material volatility erodes assembler margins on unhedged positions. Municipal distributors in South Africa exhibit highest price sensitivity, while petrochemical operators like Sasol and Ma'aden prioritize arc-flash resistant specifications over first cost.
Supply Chain Analysis
China, South Korea, and Germany anchor vacuum interrupter and cast resin transformer production, with East Asian hubs feeding core components to Middle Eastern assembly plants. Regional manufacturers draw from concentrated East Asian supply for vacuum bottles, epoxy insulators, and spring operating mechanisms. Single-source vulnerability in vacuum interrupter supply exposes African buyers to extended lead times and currency fluctuation. Distribution runs through EPC contractors for urban substation projects and direct utility procurement for rural transmission extensions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Medium Voltage Switchgear Market is entering a cyclical recovery phase as Gulf utilities accelerate renewable integration substations under Vision 2030 and comparable national programs. Grid modernization mandates are compressing procurement cycles and resetting supplier relationships.
For Market Incumbents: Fortify SASO and NERSA certification portfolios to defend against emerging Turkish and Indian competitors bidding on African rural electrification tenders. Prioritize backward integration into vacuum interrupter sourcing or captive resin casting capacity to offset copper volatility and protect margins on fixed-price framework agreements with Abu Dhabi National Energy Company. For New Entrants and Emerging Players: Differentiate on digital switchgear platforms with IEC 61850-native protection for UAE smart grid mandates, where ESMA interoperability standards create certification barriers for legacy suppliers. Target Ethiopia and Tanzania rural electrification programs financed by World Bank facilities, penetrating through modular substation architectures that compress commissioning timelines against incumbent brick-and-mortar approaches. For Investors and Strategic Acquirers: Regional assembly specialists with established SASO testing relationships and localized production in Saudi Arabia or the UAE represent priority acquisition targets as Gulf utility consolidation favors suppliers with in-country manufacturing depth. Watch NERSA grid code revision implementation pace as the signal indicating when South African municipal distributor rehabilitation budgets unlock.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Investment | Unlocks tender participation for Saudi Electricity Company giga-project electrification under tightened technical regulations. |
| Digital Platform Development | Captures 15-25% price premiums from DEWA smart grid mandates requiring remote monitoring capabilities. |
| Modular Substation Architecture | Compresses ADNOC oilfield project timelines from months to weeks against conventional construction. |
| East African Market Entry | Positions suppliers for Ethiopia and Tanzania rural electrification with World Bank financing support. |
| Vacuum Interruption Migration | Addresses SF6 regulatory pressure in North African markets while maintaining performance at higher voltage classes. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of IEC standards documentation, utility procurement databases, and regulatory filings from SASO and NERSA. Utility planning officers, EPC contractors, and aftermarket service heads at Saudi Electricity Company, Eskom, and Moroccan ONEE provided operational perspective on specification trends and commissioning challenges. Customs data on copper and aluminum trade flows, combined with SEC 10-K disclosures from listed electrical equipment manufacturers, anchored supply cost assumptions. Bottom-up bay-level demand estimates triangulated against top-down grid investment forecasts across the analysis window.
Segmentation dimensions modeled span insulation technology, installation environment, end-user category, and intelligence level across the projection horizon. Product mix shifts between air-insulated and gas-insulated configurations, digital versus conventional protection platforms, and utility versus industrial procurement channels informed volume and value trajectories. CAGRs derived from regression analysis of historical tender awards against announced grid investment programs, with renewable integration targets and urban load growth as key demand drivers.
Material uncertainties — commodity price volatility, regulatory timeline slippage, and currency fluctuation in Sub-Saharan markets — sit outside the modeled envelope. Forecasts reflect assumptions on framework agreement renewal rates and smart grid mandate implementation pace. Recalibration cycles align with material shifts in Gulf renewable deployment schedules and NERSA grid code enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Underwater Lighting Market
Others
Construction Wearables Market
Others
Thailand Travel Retail Market
Others
Global Emergency Spill Response Market
Others
UK Automotive LED Lighting Market
Others
Global Military and Aerospace Sensors Market
Others
Coalescing Filter Market
Others
Cashew Kernel Market
Others
Wood Stoves Market
Others
Europe Aircraft Lighting Systems Market
Others
Eye Balm Market
Others
Global Fertility Tracking Apps Market
Others
Latin America Automotive HVAC Market
Others
Managed Video As a Service Market
Others
Global Duty-Free Retailing Market
Others
Exosome Technologies Market