
 Augmented Reality in BFSI Market | 2026-2036
Augmented Reality in BFSI Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Reality in BFSI Market Analysis
Bank branch distribution is fragmenting as AR-enabled self-service kiosks and remote advisory platforms displace traditional teller-centric layouts. Microsoft anchors enterprise-grade mixed reality deployments for institutional trading floors. Google competes through cloud-based AR core integrations that power mobile banking overlays. Meta differentiates via social AR filters repurposed for brand-driven financial literacy campaigns.
Augmented Reality in BFSI overlays digital information onto physical environments through spatial computing, computer vision, and real-time rendering to enable immersive financial interactions. Head-mounted displays and mobile applications constitute the primary delivery modalities, with latency thresholds below 20 milliseconds required for seamless transaction authorization. Virtual Banking leads application adoption as institutions close underutilized branches, while Investment Visualization represents the fastest-growing segment as robo-advisors integrate three-dimensional portfolio modeling. Wearable Devices remain nascent in banking contexts due to security certification gaps, though pilot programs at Swiss and Singaporean private banks signal emerging traction.
The EU AI Act classifies biometric authentication through AR as high-risk, mandating conformity assessments before market deployment, while the SEC scrutinizes AR-enhanced investment presentations for misleading visual simulations. India's RBI issues periodic guidance on virtual KYC interfaces, pushing banks toward auditable AR audit trails. Stakeholders must weigh regulatory compliance costs against customer acquisition gains as spatial banking interfaces mature from novelty to infrastructure.
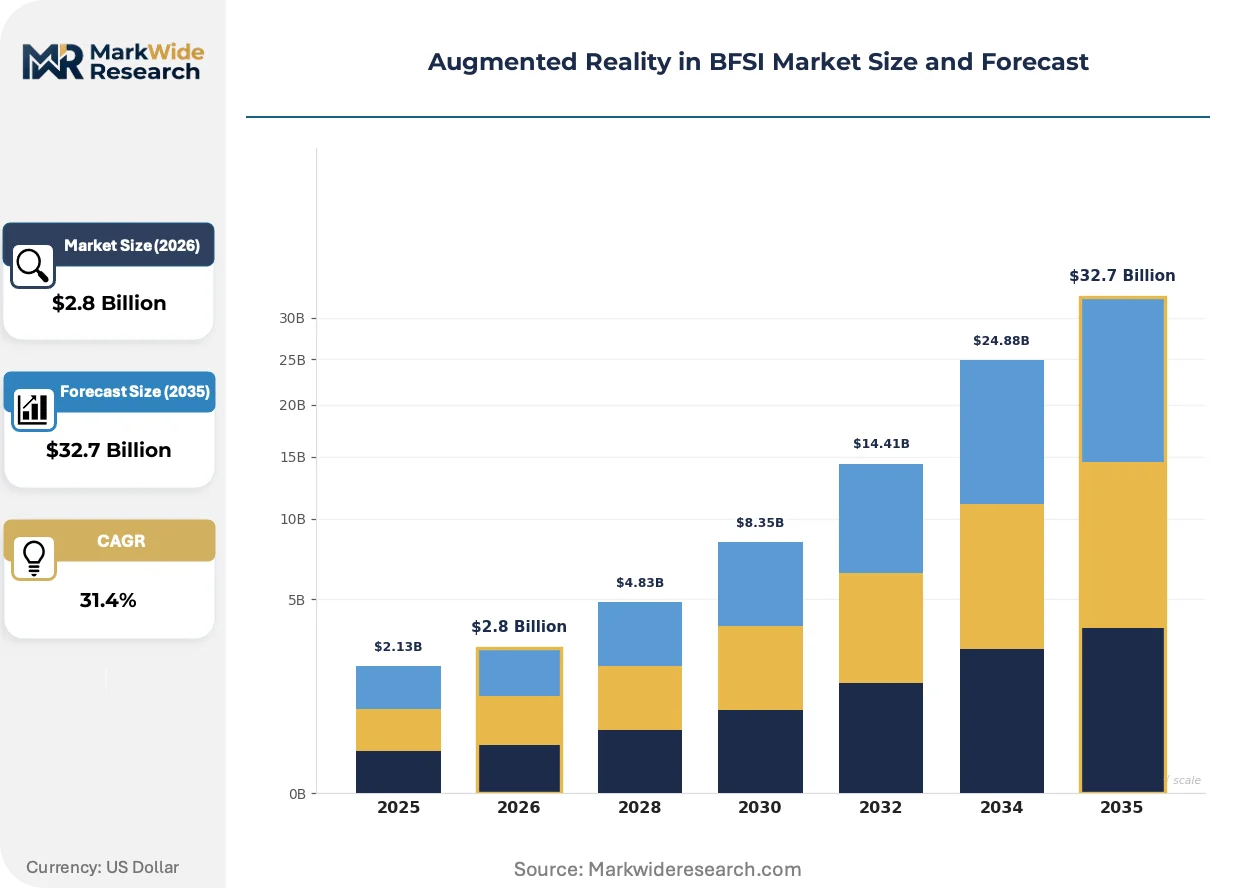
Market Dynamics
Bank branch closures accelerate as spatial computing interfaces replace physical teller interactions, compressing real estate footprints while expanding service reach through immersive visualization tools.
Growth Catalysts
- EU AI Act compliance mandates:High-risk classification of biometric AR authentication creates standardized security benchmarks that reduce buyer uncertainty and accelerate procurement cycles for compliant vendors.
- Wealth management digitization:High-net-worth client segments demand three-dimensional portfolio visualization, pulling robo-advisory platforms toward spatial computing integrations.
- Cloud edge infrastructure:Sub-20 millisecond latency thresholds for transaction authorization now achievable through distributed computing nodes, enabling real-time AR banking experiences previously impossible.
Market Restraints
- GDPR biometric data governance:Cross-border data localization requirements for facial and iris recognition templates increase compliance overhead for multi-jurisdictional deployments.
- Head-mounted display supply concentration:Enterprise-grade hardware sourcing concentrates among limited semiconductor foundries, creating procurement bottlenecks for scaled rollouts.
- Legacy core banking integration:Real-time AR interfaces require API architectures that many incumbent institutions lack, forcing expensive middleware development.
Strategic Opportunities
- India's virtual KYC guidance:RBI-mandated auditable AR audit trails create first-mover advantages for banks building compliant spatial onboarding infrastructure.
- Wearable device certification gaps:Swiss and Singaporean private bank pilot programs signal emerging demand for wrist-worn authentication hardware before mass-market availability.
- 5G and edge AI convergence:Combined low-latency connectivity with on-device inference enables branchless AR advisory without cloud dependency, opening rural and emerging market penetration.
Industry Challenges
- Spatial computing talent scarcity:Computer vision engineers with financial services domain expertise command premium compensation, constraining in-house development velocity.
- SEC enhanced disclosure scrutiny:AR-enhanced investment presentations face heightened review for misleading visual simulations, extending compliance review timelines.
- Multi-modal authentication standardization:Absence of unified protocols for combining biometric, behavioral, and environmental signals in AR contexts fragments vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Reality in BFSI Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $32.7 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Virtual Banking, Financial Education, Customer Engagement, Investment Visualization Technology: Wearable Devices, Mobile Applications, Head-Mounted Displays, Projection-Based AR End User: Retail Banks, Investment Firms, Insurance Companies, Wealth Management Service Type: Consulting Services, Integration Services, Technical Support, Maintenance |
| Companies Covered | Unity Technologies, Apple, Microsoft, TeamViewer, Snap Inc, Google, Meta, Blippar Group Limited, PTC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Reality in BFSI Market Emerging Trajectories
Spatial banking interfaces mature from experimental deployments toward core infrastructure, driven by regulatory clarity, hardware cost curves, and generational shifts in wealth management client expectations.
Mobile AR core technology is hybridizing cloud-based rendering with on-device spatial mapping to enable persistent financial data overlays across physical branch environments. Retail banking divisions at major institutions pilot these capabilities for self-service navigation and product comparison. The convergence is compressing deployment timelines from multi-year infrastructure projects to quarterly software releases.
EU AI Act high-risk system classifications are reshaping vendor qualification criteria for biometric authentication deployments across European financial services. Conformity assessment requirements now precede market entry, filtering out undercapitalized technology providers. Private banking segments in Germany and France accelerate procurement of pre-certified AR platforms to avoid deployment delays.
Wealth advisory procurement patterns favor immersive visualization capabilities over traditional reporting formats among next-generation high-net-worth clients. Three-dimensional portfolio modeling displaces static PDF statements in client acquisition and retention. This preference shift concentrates demand in United States coastal metropolitan markets where technology-forward advisory practices compete for asset inflows.
Augmented Reality in BFSI Market Segmentation
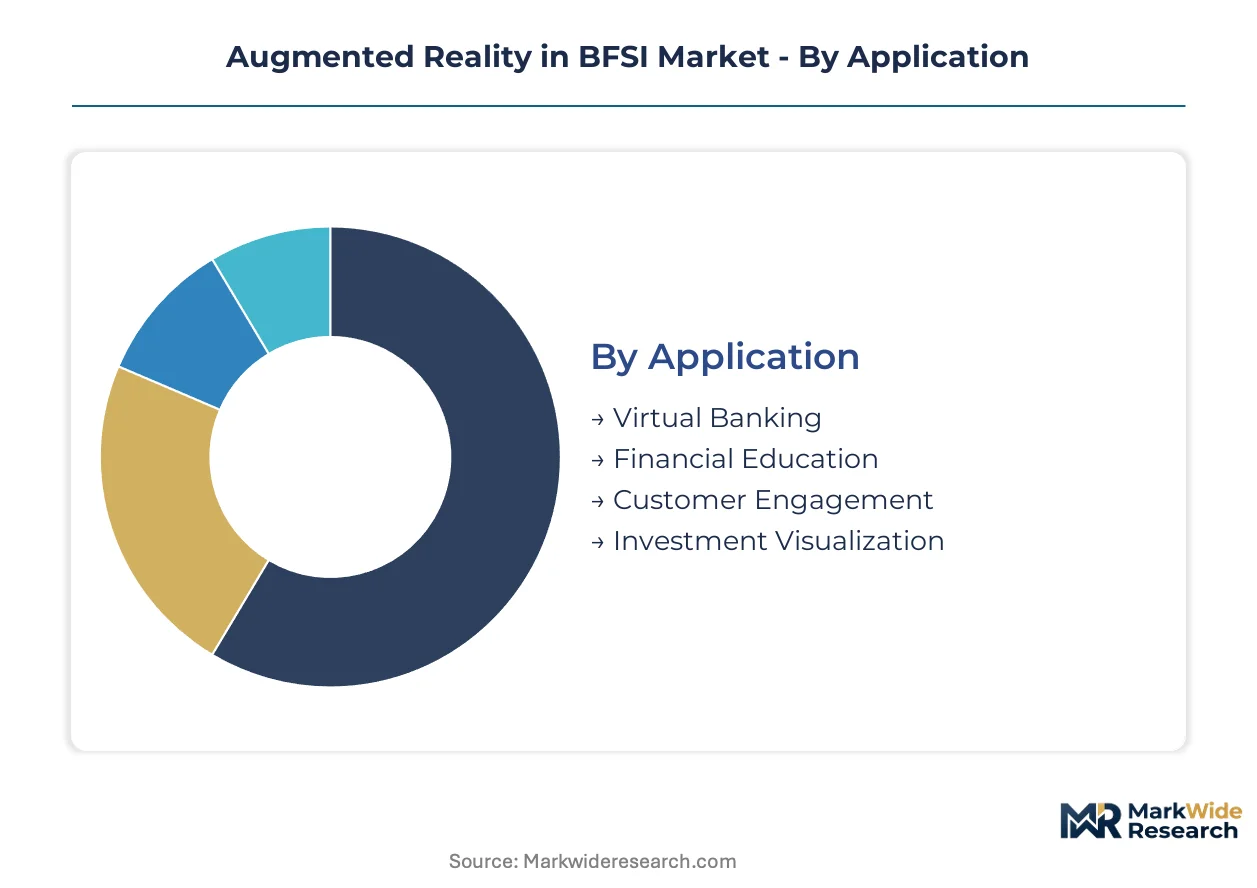
Spatial banking interfaces fragment across multiple deployment vectors, each carrying distinct hardware requirements, compliance burdens, and client interaction models. Procurement cycles vary dramatically—mobile rollouts complete in quarters while head-mounted enterprise systems stretch across fiscal years.
Application:
Virtual Banking compresses deployment timelines to under six months for pilot programs, while Investment Visualization demands extended calibration periods for regulatory-compliant visual simulations.
- Virtual Banking:Self-service kiosks and remote advisory platforms displace physical teller interactions through spatial computing interfaces. Demand concentrates in United States retail banking divisions closing underutilized branches, driven by real estate cost reduction mandates.
- Investment Visualization:Three-dimensional portfolio modeling enables immersive wealth advisory experiences with sub-20 millisecond latency thresholds for real-time rendering. High-net-worth client segments in coastal United States metropolitan markets pull robo-advisory platforms toward spatial computing integrations.
- Financial Education:Gamified literacy modules deploy through mobile AR overlays for mass-market customer onboarding.
- Customer Engagement:Brand-driven spatial campaigns utilize social AR filters repurposed from consumer technology ecosystems.
Virtual Banking dominates installed base. Investment Visualization is where expansion concentrates.
Technology:
Cost tiers separate consumer-grade mobile deployments from enterprise head-mounted systems requiring semiconductor foundry allocation and security certification.
- Mobile Applications:Cloud-based AR core integrations power banking overlays through existing smartphone infrastructure without hardware procurement. Distributed computing nodes achieve transaction authorization latency below 20 milliseconds across United States and European deployments.
- Head-Mounted Displays:Enterprise-grade mixed reality systems anchor institutional trading floor deployments with persistent spatial mapping capabilities. Supply concentration among limited semiconductor foundries creates procurement bottlenecks for scaled rollouts.
- Wearable Devices:Wrist-worn authentication hardware pilots at Swiss and Singaporean private banks signal emerging demand before mass-market availability.
- Projection-Based AR:Spatial computing interfaces for branch environments require dedicated physical infrastructure investment.
Mobile Applications capture volume leadership. Head-Mounted Displays command margin concentration.
End User:
Customer acquisition economics vary sharply—retail banks prioritize scale while wealth management segments absorb premium pricing for immersive visualization capabilities.
- Retail Banks:Branch transformation initiatives deploy AR-enabled self-service kiosks to compress real estate footprints while expanding service reach. United States institutions including JPMorgan Chase and Bank of America pilot spatial interfaces for high-net-worth client segments.
- Wealth Management:Next-generation client preferences favor three-dimensional portfolio modeling over static reporting formats in client acquisition and retention. Technology-forward advisory practices in United States coastal metropolitan markets compete for asset inflows through immersive capabilities.
- Investment Firms:Institutional trading floors adopt enterprise-grade mixed reality for data visualization and collaborative analysis.
- Insurance Companies:Claims assessment and policy visualization applications remain in early pilot phases across European markets.
Retail Banks dominate procurement volume. Wealth Management is climbing the fastest.
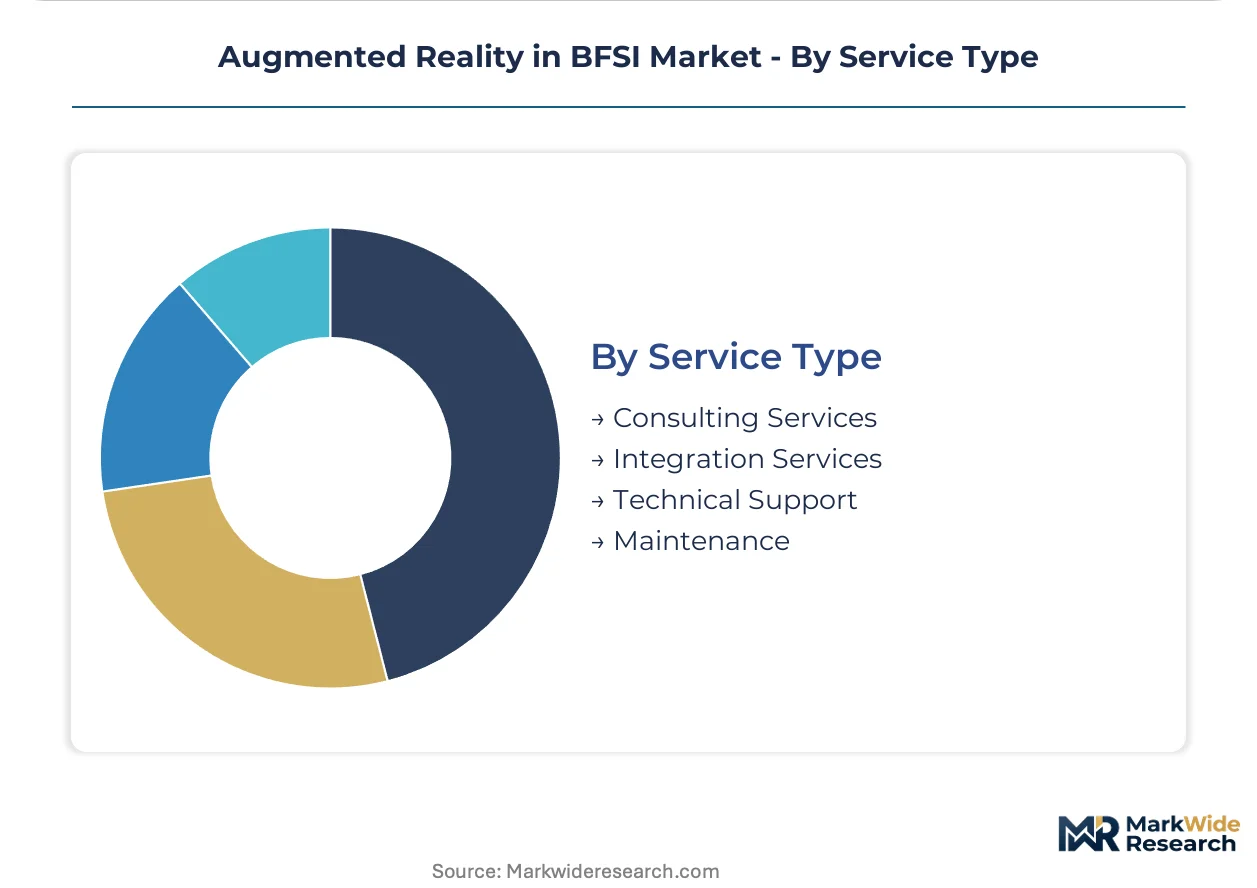
Service Type:
Margin structures invert across the service lifecycle—integration commands upfront premiums while maintenance generates recurring revenue with lower customer acquisition cost.
- Integration Services:API architecture development connects real-time AR interfaces to legacy core banking systems lacking native spatial computing support. Middleware development costs burden incumbent institutions with decades-old infrastructure.
- Consulting Services:Regulatory compliance advisory spans EU AI Act conformity assessments for biometric authentication and SEC disclosure scrutiny for AR-enhanced investment presentations. European private banking segments in Germany and France accelerate procurement of pre-certified platforms.
- Technical Support:Latency threshold monitoring and spatial computing troubleshooting require specialized computer vision engineering expertise.
- Maintenance:Hardware certification renewal and software patch management sustain deployed AR infrastructure across multi-year operational lifecycles.
Integration Services dominates upfront revenue. Consulting Services is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States wealth management corridors while European compliance burdens compress margins for biometric authentication deployments. Spatial banking procurement cycles run 40% shorter in North American markets compared to EU conformity assessment timelines. Japan and Singaporean private banking segments absorb hardware premiums unavailable to mass-market retail divisions elsewhere.
United States
JPMorgan Chase and Bank of America pilot AR-enabled wealth visualization tools for high-net-worth clients in coastal metropolitan markets. SEC scrutiny of AR-enhanced investment presentations extends compliance review timelines for misleading visual simulations. New York and San Francisco technology-forward advisory practices compete for asset inflows through three-dimensional portfolio modeling capabilities.
Germany
Private banking segments accelerate procurement of pre-certified AR platforms to avoid EU AI Act deployment delays. GDPR biometric data governance mandates cross-border data localization for facial and iris recognition templates. Frankfurt and Munich wealth management divisions drive enterprise-grade mixed reality adoption for institutional client segments.
India
RBI-mandated auditable AR audit trails for virtual KYC interfaces create first-mover advantages for compliant spatial onboarding infrastructure. The central bank issues periodic guidance pushing banks toward transparent authentication records. Mumbai and Bangalore retail banking divisions pilot self-service kiosks displacing physical teller interactions in underutilized branches.
Switzerland
Swiss private banks operate wrist-worn authentication hardware pilots before mass-market wearable device availability. FINMA-aligned data governance standards exceed baseline GDPR requirements for biometric template storage. Zurich and Geneva wealth management clusters absorb premium hardware costs unavailable to retail banking segments in neighboring jurisdictions.
Singapore
Monetary Authority of Singapore guidelines on digital identity verification accelerate spatial computing procurement for private banking client onboarding. The regulator's technology risk management framework mandates resilience standards for real-time AR transaction authorization. Marina Bay financial district institutions deploy sub-20 millisecond latency infrastructure for immersive advisory experiences.
Augmented Reality in BFSI Market Vendor Landscape
Cloud-platform giants and enterprise-software specialists split the market along deployment-modality lines. Consolidation pressures concentrate among mobile AR core providers while head-mounted display sourcing bottlenecks favor vertically integrated hardware-software bundles. Three archetypes dominate: hyperscale cloud providers with distributed computing nodes, enterprise mixed-reality platform vendors with persistent spatial mapping, and social-media-origin AR filter specialists repurposing consumer technology. Competitive moves center on strategic partnerships for legacy core banking API integration and pre-certification investments for EU AI Act conformity assessments.
Within the enterprise-platform tier, Microsoft anchors institutional trading floor deployments with enterprise-grade mixed reality systems. Google occupies a position among cloud-based AR core integrators powering mobile banking overlays through distributed computing infrastructure. Meta exemplifies the social-AR-repurposing archetype, adapting consumer filter technology toward brand-driven financial literacy campaigns. Unity Technologies represents the content-pipeline specialist archetype, supplying spatial computing development environments across deployment modalities.
| Leading Market Players |
|---|
| Unity Technologies |
| Apple |
| Microsoft |
| TeamViewer |
| Snap Inc |
| Meta |
| Blippar Group Limited |
| PTC |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific fiber-optic cable latency costs cascade through AR banking infrastructure procurement, amplifying price spreads between cloud-edge deployments and on-premise enterprise systems while compressing margins for vendors without semiconductor foundry allocation.
Pricing Analysis
The customization-premium spread separates standard mobile AR core integrations from configured-to-order enterprise mixed reality deployments. SaaS-tiered subscription models dominate mobile banking overlays, while project-based licensing governs head-mounted display rollouts with embedded security certification. Price differentiation hinges on EU AI Act pre-certification status and latency guarantee tiers, with pressure intensifying on mid-market vendors lacking conformity assessment investment. Retail banking divisions exhibit acute price sensitivity, whereas Swiss and Singaporean private banks absorb hardware premiums unavailable elsewhere.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates semiconductor component sourcing for enterprise-grade head-mounted displays. Taiwan, South Korea, and the United States concentrate advanced foundry capacity for spatial computing processors. Raw material dependencies include gallium nitride substrates, high-resolution OLED microdisplays, and precision optical waveguides. Single-source vulnerability in EUV lithography equipment constrains scaled rollouts. Distribution runs through vertically integrated hardware-software bundles rather than component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
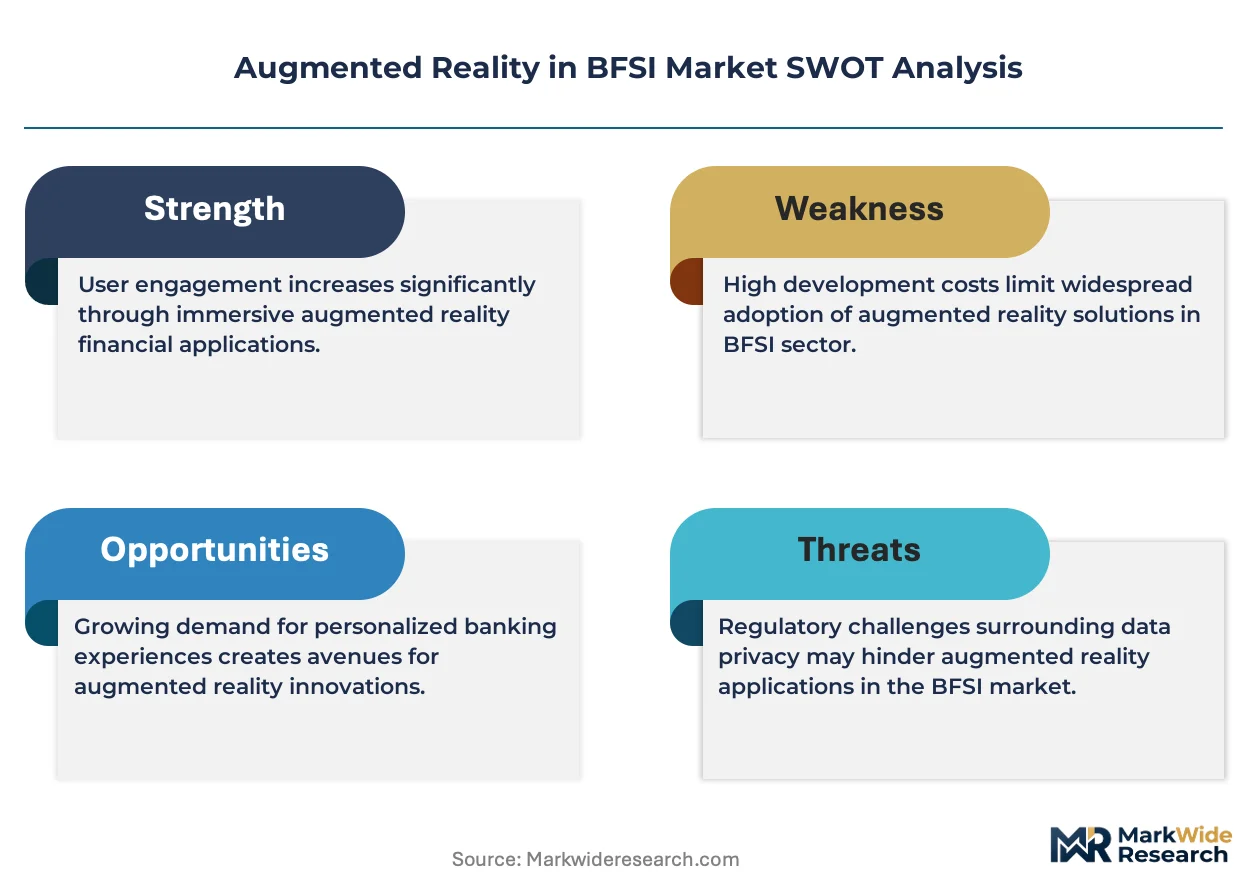
This market rewards regulatory entrenchment as the core defensive moat, with EU AI Act conformity assessments creating switching costs that lock in compliant vendors across multi-year procurement cycles.
For Market Incumbents: Build regulatory certification moats through accelerated EU AI Act pre-assessment investment. Microsoft and Google anchor enterprise cloud-edge infrastructure, but emerging cloud-native entrants threaten latency-optimized middleware layers. Incumbents should deepen backward integration into semiconductor allocation agreements and secure captive supply of enterprise head-mounted display components. For New Entrants and Emerging Players: Establish a beachhead in India's RBI-mandated virtual KYC audit trail segment before incumbent middleware consolidation. Wearable device certification gaps at Swiss private banks offer penetrable white space absent hyperscale competition. Go-to-market positioning should emphasize sub-20 millisecond latency guarantees through distributed edge node partnerships rather than cloud-centralized architectures. For Investors and Strategic Acquirers: Computer vision specialists with financial services domain expertise represent the priority acquisition archetype, commanding premium valuations due to talent scarcity. Long-term viability across the analysis window rests on regulatory compliance automation capabilities rather than hardware differentiation. The signal to watch is EU AI Act enforcement intensity against non-compliant biometric authentication deployments.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Conformity assessments filter undercapitalized vendors from European private banking procurement. |
| Edge Infrastructure Partnership | Sub-20 millisecond latency guarantees enable branchless AR advisory in rural Indian markets. |
| Legacy Core Banking API Integration | Middleware development connects real-time spatial interfaces to decades-old incumbent infrastructure. |
| Wearable Device Certification Pursuit | Swiss and Singaporean pilots signal emerging demand before mass-market hardware availability. |
| Spatial Computing Talent Acquisition | Computer vision engineers with financial domain expertise constrain in-house development velocity. |
Methodological Framework
The analysis maps virtual banking deployments, investment visualization platforms, and biometric authentication systems, each validated through primary interviews with spatial computing engineering leads, regulatory compliance officers at European private banks, RBI technology policy advisors, and wealth management CTOs at United States coastal institutions. Secondary sources include SEC disclosure filings for AR-enhanced investment presentations, EU AI Act implementation guidance, RBI circulars on virtual KYC, and hyperscaler capex disclosures for distributed edge infrastructure. Bottom-up deployment sizing triangulates against top-down banking IT spend allocation estimates.
Assumptions held fixed include EU AI Act enforcement timelines and semiconductor foundry capacity expansion plans, while variables included 5G network densification rates and generational wealth transfer velocity among technology-forward client segments. The projection horizon spans mobile application adoption curves, head-mounted display enterprise penetration, and wearable device certification pathways. CAGRs derive from segment-level deployment velocity calibrated to regulatory milestone achievement and hardware cost curve trajectories. Industry-specific inputs include latency threshold compliance rates and biometric authentication template storage cost curves.
Sensitivities concentrate around EU AI Act enforcement intensity, Taiwan semiconductor supply disruptions, and RBI guidance revisions on auditable AR audit trails. Forecasts reflect documented assumptions regarding cloud-edge infrastructure maturation and spatial computing talent pipeline expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Transportation Lighting Market
Others
Global Electroshock Weapons Market
Others
Europe Legal Services Market
Others
Saudi Arabia Cat Food Market
Others
Bamboo Straws Market
Others
Global Drug Discovery Informatics Market
Others
Semiconductor Gas Filters Market
Others
Bicycle Panniers Market
Others
Signal Transformer Market
Others
Security Envelopes Market
Others
Printing Machines Market
Others
Global Retail Media Networks Market
Others
Senior Cat Food Market
Others
Australia Content Services Platform Market
Others
Asia-Pacific Legal Services Market
Others
Cloud Digital Video Recorder Market