
 Global Nano Batteries Market | 2026-2036
Global Nano Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nano Batteries Market Outlook
Software-defined battery management is expanding what nano battery suppliers monetize beyond hardware sales. Amprius Technologies leverages its silicon nanowire anode platform to sustain technology leadership in aviation-grade energy density. Samsung SDI Co. Ltd. anchors Asian manufacturing scale through its integrated electrode-to-pack operations. Sila Nanotechnologies Inc. differentiates by controlling nanoparticle synthesis in-house, avoiding raw material bottlenecks that constrain competitors.
Nano batteries employ active materials with at least one dimension below 100 nanometers, typically silicon nanowires or lithium-metal foils engineered for surface-area-to-volume ratios exceeding 10^7 per meter. This architecture delivers gravimetric energy densities above 400 Wh/kg, enabling commercial applications where weight reduction directly extends operational range. Solid-state product types command premium positioning due to their elimination of flammable liquid electrolytes and compatibility with lithium-metal anodes. Electric vehicle applications absorb the largest share of capital deployment, though medical devices represent the fastest-growing demand pool as implantable devices require biocompatible miniaturized power sources.
FDA device regulations in the United States govern nano battery integration into implantable medical equipment, while EPA rules track nanomaterial discharge from manufacturing facilities. China's SAMR enforces GB standards for cell safety testing that foreign suppliers must pass before domestic market access. REACH compliance in Europe mandates registration of engineered nanomaterials above one ton annual volume, adding documentation costs that favor established producers over new entrants. Stakeholders must monitor how divergent nanomaterial classification regimes across Washington, Beijing, and Brussels reshape competitive access before committing to regional capacity investments.
Market Dynamics
Solid-state nano battery architectures are compressing development timelines as automotive OEMs demand lithium-metal compatibility without liquid electrolyte flammability risks. This structural shift forces cathode suppliers to requalify production lines for sulfide-based solid electrolytes while anode specialists scale silicon nanowire capacity.
Growth Catalysts
- Aviation electrification mandates:FAA certification pathways for electric propulsion systems are pulling aviation-grade energy density requirements above 400 Wh/kg, creating qualified demand pools for silicon nanowire anode suppliers.
- China's dual carbon goals:MIIT production quotas for new energy vehicles are accelerating domestic solid-state cell pilot lines, with GB standards for nanomaterial handling tightening certification requirements that filter out marginal producers.
- Implantable medical device miniaturization:FDA device regulations for biocompatible power sources are expanding addressable markets for thin-film lithium cells in neuromodulation and cardiac rhythm management applications.
Market Restraints
- Silicon nanowire precursor costs:High-purity silane gas supply concentrates in East Asian chemical clusters, exposing anode manufacturers to input cost volatility when semiconductor fabrication competes for the same feedstock.
- Solid electrolyte manufacturing yield gaps:Sulfide-based ceramic processing remains below 60% first-pass yield in volume production, constraining cell cost reduction trajectories regardless of scale investment.
- REACH nanomaterial registration burdens:ECHA documentation requirements for engineered nanomaterials above one ton annual volume favor established producers with dedicated regulatory affairs functions over new entrants.
Strategic Opportunities
- Indian electric two-wheeler electrification:PLI scheme incentives for advanced chemistry cell manufacturing are attracting nano battery technology licensors seeking to localize production outside China-dependent supply chains.
- Maritime battery propulsion:IMO decarbonization targets for short-sea shipping are opening vessel-scale procurement opportunities for solid-state systems with thermal runaway immunity requirements.
- Digital health wearable convergence:Skin-interfaced biosensors requiring flexible form factors are pulling stretchable battery architectures that nano-structured electrodes uniquely enable.
Industry Challenges
- Dry electrode coating skill scarcity:Solvent-free electrode manufacturing requires process engineers with thin-film deposition expertise that conventional lithium-ion production lines do not cultivate.
- Multi-jurisdictional certification timelines:Concurrent UN 38.3 transport testing, UL 9540A thermal propagation validation, and GB/T safety assessments stretch product qualification cycles to 24-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nano Batteries Market |
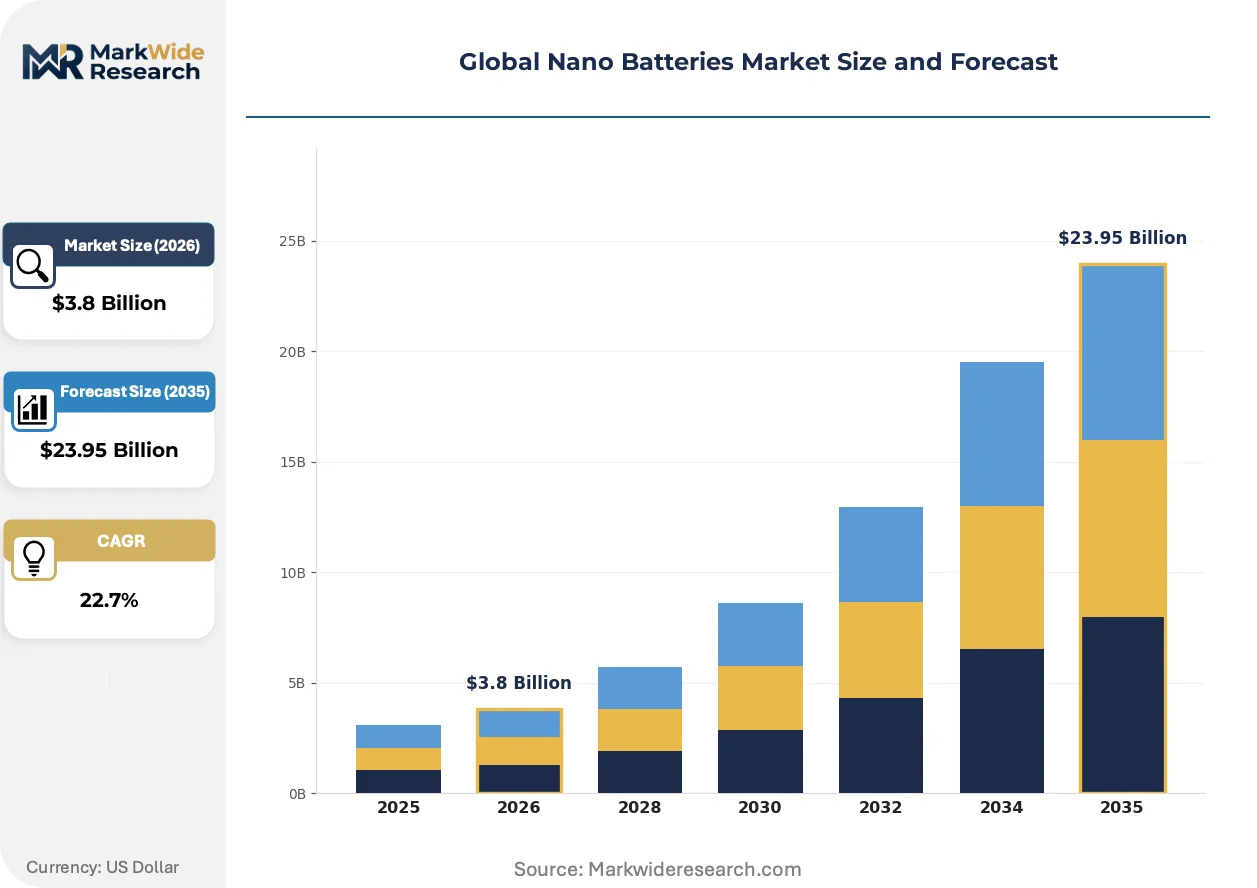
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Ion, Solid State, Nickel Cadmium, Lead Acid Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Medical Devices Technology: Nanostructured Electrode, Electrode Coating, Composite Materials, Energy Density Improvement End User: Automotive, Electronics Manufacturers, Utility Providers, Healthcare Facilities |
| Companies Covered | Amprius Technologies, A123 Systems LLC, Altairnano, Sila Nanotechnologies Inc., LG Energy Solution Ltd., Samsung SDI Co. Ltd., Group14 Technologies, 6K Inc., Nexeon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nano Batteries Market Strategic Shifts
Silicon nanowire anode technology is rewriting competitive boundaries between aviation and automotive battery suppliers as gravimetric density targets converge across previously distinct end-use specifications.
Solid-state electrolyte integration is rewriting how cell manufacturers structure R&D partnerships, with sulfide ceramic specialists now licensing directly to automotive OEMs rather than tiered through traditional cathode suppliers. Aviation battery procurement teams at electric vertical takeoff manufacturers are compressing supplier qualification cycles from 48 months to 18 months. This acceleration is compressing the addressable market for incumbent liquid electrolyte architectures that cannot meet combined energy density and safety requirements.
REACH nanomaterial classification revisions are forcing European cell manufacturers to resubmit safety data sheets for silicon-based active materials previously grandfathered under bulk substance registrations. ECHA's 2023 guidance on nanomaterial thresholds triggered reformulation efforts across anode coating operations. German automotive suppliers are responding by consolidating procurement with anode material producers holding pre-validated registration dossiers.
Aviation OEMs are unbundling battery system procurement from airframe integration contracts, creating direct purchasing relationships with cell manufacturers that bypass traditional tier-one electrical system suppliers. This disintermediation concentrates negotiation leverage with airframers holding type certification authority. The pattern is most visible in electric regional aircraft development programs where range guarantees depend on cell-level performance warranties rather than system-level integration commitments.
Global Nano Batteries Market Segmentation
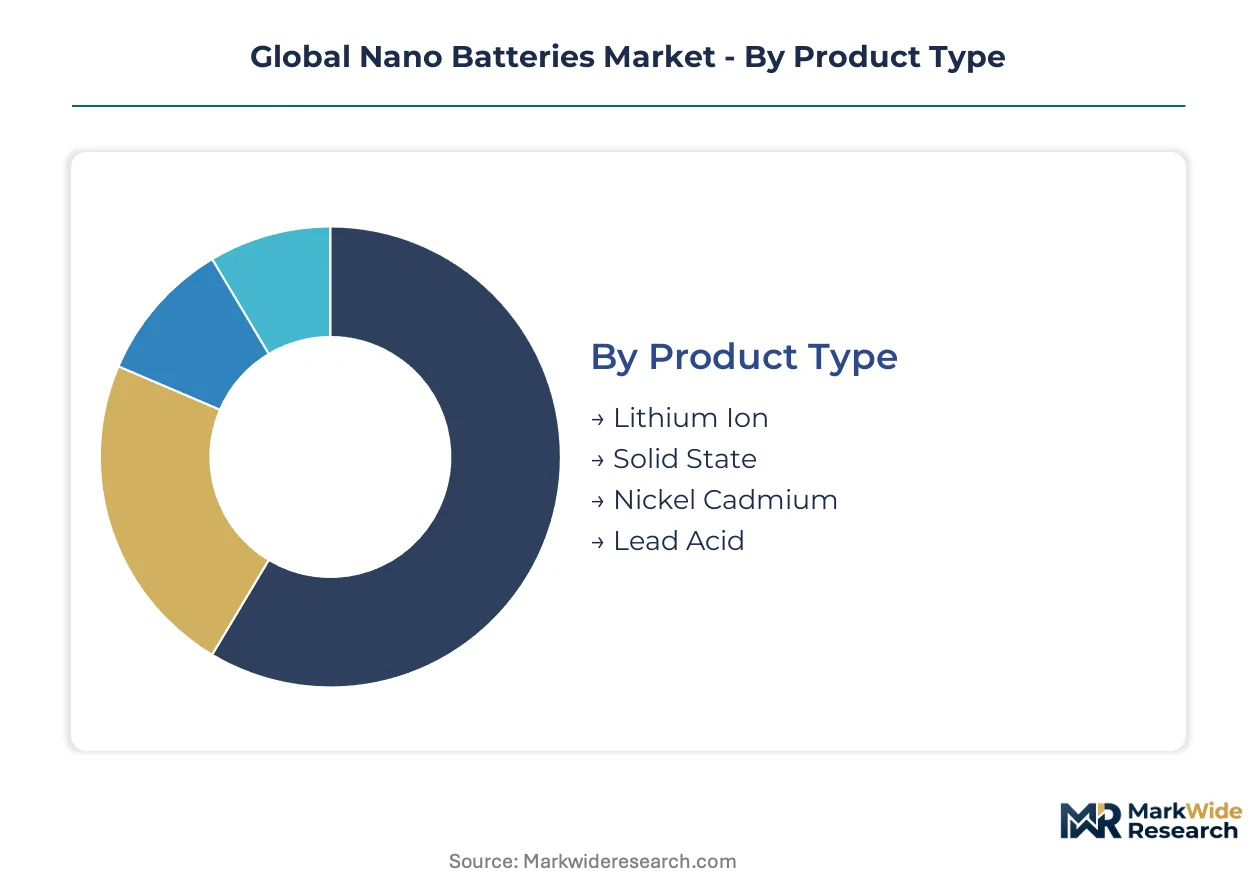
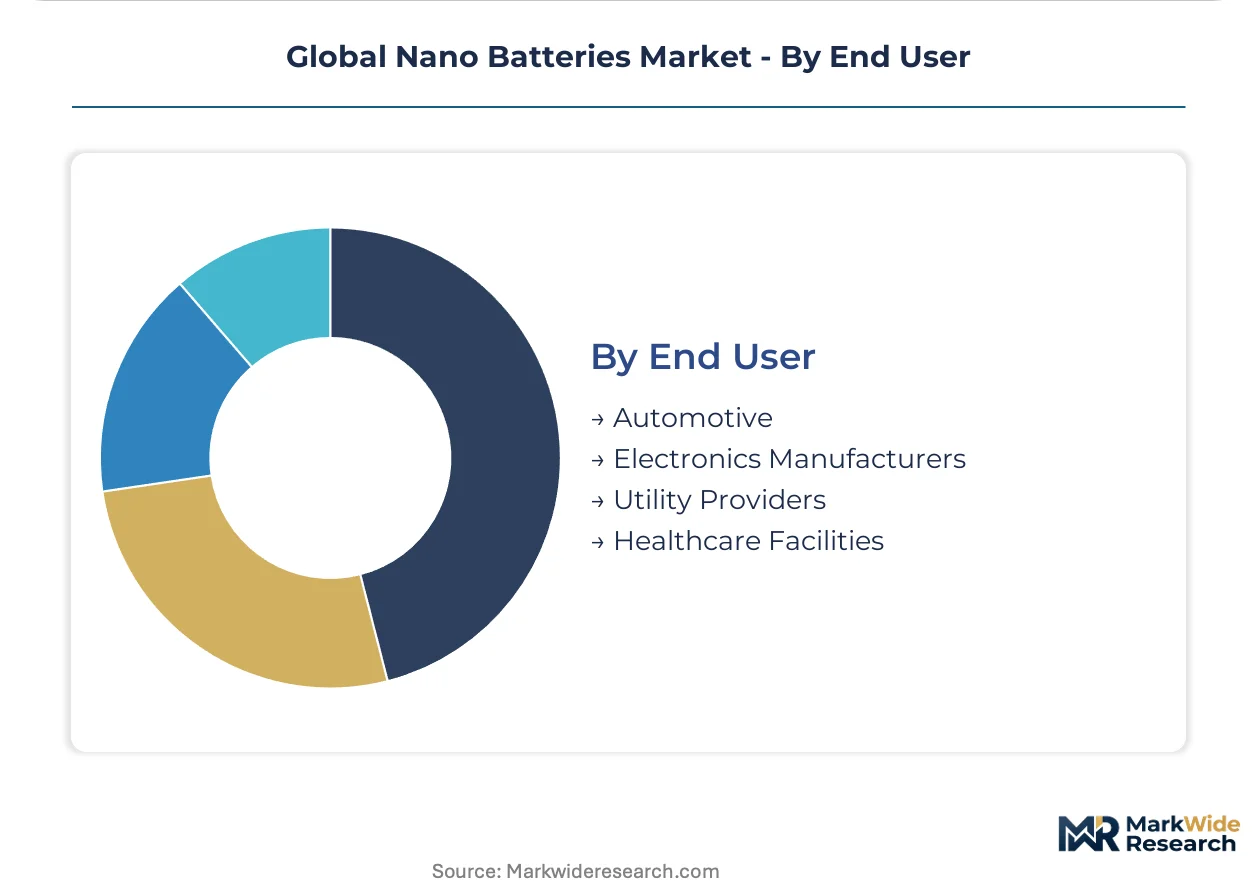
Nano battery procurement patterns diverge sharply across product architectures and end-use specifications. Upgrade cycles in automotive electrification and medical device miniaturization are compressing technology refresh timelines and reshaping supplier qualification priorities.
Product Type:
Replacement economics favor architectures that extend cycle life and reduce thermal management overhead in existing installations.
- Solid State:Eliminates flammable liquid electrolytes through ceramic or sulfide-based ionic conductors. BMW and Volkswagen suppliers in Germany's automotive corridor are qualifying these cells for next-generation electric vehicle platforms where lithium-metal anode compatibility unlocks range extension.
- Lithium Ion:Employs nanostructured silicon or lithium-metal foils within conventional liquid electrolyte formats. Aviation-grade energy density requirements above 400 Wh/kg are pulling demand from electric vertical takeoff manufacturers seeking certified cell suppliers.
- Nickel Cadmium:Legacy chemistry with limited nano-material integration, retained in industrial backup power where capital constraints block architecture migration.
- Lead Acid:Minimal nano-technology penetration; confined to cost-sensitive automotive starter applications where weight and energy density tradeoffs are tolerated.
Solid State leads volumes today; Lithium Ion is gaining share fastest.
Application:
Margin structures vary by certification burden and performance warranty terms rather than raw material costs alone.
- Electric Vehicles:OEM procurement teams specify gravimetric density thresholds and thermal runaway immunity as non-negotiable gate criteria. China's MIIT production quotas for new energy vehicles are accelerating domestic solid-state pilot line investment.
- Medical Devices:Thin-film lithium cells power implantable neuromodulation and cardiac rhythm management hardware. FDA device regulations govern biocompatibility and hermetic sealing requirements that filter out non-specialized suppliers.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize volumetric energy density and fast-charge capability over cycle life extension.
- Renewable Energy Storage:Grid-scale installations demand cost-per-kWh economics that nano-structured electrodes have not yet achieved at utility procurement volumes.
Electric Vehicles leads volumes today; Medical Devices is climbing the fastest.
Technology:
Process control capabilities separate qualified suppliers from commodity competitors in this segment.
- Nanostructured Electrode:Silicon nanowire anode architectures deliver surface-area-to-volume ratios exceeding 10^7 per meter. Amprius Technologies sustains technology leadership through proprietary nanowire growth protocols.
- Electrode Coating:Dry electrode coating eliminates solvent recovery costs and enables thicker active material layers. Samsung SDI Co. Ltd. anchors manufacturing scale through integrated electrode-to-pack operations.
- Composite Materials:Hybrid ceramic-polymer electrolytes bridge conductivity and mechanical flexibility requirements in flexible form factor applications.
- Energy Density Improvement:Cross-cutting R&D focus spanning anode, cathode, and electrolyte innovations rather than discrete product category.
Nanostructured Electrode leads volumes today; Electrode Coating is expanding most quickly.
End User:
Procurement authority is consolidating with OEMs holding type certification authority rather than tiered system integrators.
- Automotive:Cell-level performance warranties now replace system-level integration commitments in contract structures. German automotive suppliers are consolidating procurement with anode material producers holding pre-validated REACH registration dossiers.
- Healthcare Facilities:Implantable device OEMs source directly from cell manufacturers, bypassing traditional medical device distributors. EMA and FDA dual-track submissions extend qualification cycles to 24-36 months.
- Electronics Manufacturers:Consumer device assemblers negotiate on volumetric density and unit cost with limited thermal safety requirements.
- Utility Providers:Grid operators specify cycle life and degradation rates under temperature-cycled operating conditions.
Automotive leads volumes today; Healthcare Facilities is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT production quotas are accelerating solid-state pilot line investment faster than Germany's automotive corridor can qualify next-generation cell architectures. Both jurisdictions are tightening nanomaterial handling standards that filter out marginal producers.
China
MIIT production quotas for new energy vehicles are pulling domestic OEM procurement toward solid-state nano battery architectures. SAMR enforces GB standards for cell safety testing that foreign suppliers must pass before domestic market access. The Yangtze River Delta hosts concentrated pilot line investment where CATL suppliers are scaling silicon nanowire anode capacity.
Germany
BMW and Volkswagen procurement teams are specifying gravimetric density thresholds above 400 Wh/kg for next-generation electric vehicle platforms. KBA type certification requirements are extending qualification cycles for lithium-metal compatible cell designs. The Stuttgart-Munich automotive corridor anchors European solid-state development where cathode suppliers are requalifying production lines for sulfide-based electrolytes.
United States
FAA certification pathways for electric propulsion systems are pulling aviation-grade energy density requirements above 400 Wh/kg. FDA device regulations govern nano battery integration into implantable medical equipment, expanding addressable markets for thin-film lithium cells. The San Francisco Bay Area concentrates silicon nanowire specialists where Amprius Technologies sustains technology leadership through proprietary growth protocols.
Japan
METI battery technology roadmaps are prioritizing solid-state architectures with lithium-metal anode compatibility for automotive applications. JIS standards for nanomaterial characterization are adding documentation burdens that favor established producers with dedicated regulatory affairs functions. The Nagoya-Tokyo industrial corridor hosts integrated electrode-to-pack operations where Samsung SDI Co. Ltd. anchors Asian manufacturing scale.
South Korea
MFDS medical device regulations are creating dual-track submission requirements with FDA for implantable nano battery suppliers. The country's national industrial policy is channeling R&D subsidies toward sulfide ceramic electrolyte processing. The Seoul Capital Area concentrates cathode material specialists where LG Energy Solution Ltd. is scaling next-generation cell architectures.
Global Nano Batteries Market Competitive Environment
Top-tier vendors anchor automotive and aviation procurement, while mid-cap specialists occupy medical device and consumer electronics niches. The vendor base separates into three strategic tiers: integrated cell manufacturers with electrode-to-pack operations, nanomaterial synthesis specialists controlling precursor supply, and technology licensors monetizing proprietary architectures. Dominant competitive moves include strategic partnerships with automotive OEMs for qualification cycles and backward integration into high-purity silane gas supply.
Within the nanomaterial synthesis tier, Sila Nanotechnologies Inc. and Group14 Technologies exemplify archetypes that control nanoparticle production in-house to avoid raw material bottlenecks. Samsung SDI Co. Ltd. anchors the integrated manufacturing vector through captive electrode-to-pack operations. Amprius Technologies occupies the aviation-specialist position where silicon nanowire anode platforms sustain technology leadership in energy density requirements above 400 Wh/kg.
| Leading Market Players |
|---|
| Amprius Technologies |
| A123 Systems LLC |
| Altairnano |
| Sila Nanotechnologies Inc. |
| LG Energy Solution Ltd. |
| Samsung SDI Co. Ltd. |
| Group14 Technologies |
| 6K Inc. |
| Nexeon |
| Others |
Value Chain & Pricing Dynamics
Dry electrode coating adoption is compressing manufacturing costs while concentrating procurement leverage with equipment suppliers holding thin-film deposition expertise. This process transition simultaneously reduces solvent recovery overhead and creates bottlenecks where qualified engineering talent pools remain shallow.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for solid-state cell architectures. Three-tier pricing structure across aviation-grade, automotive-qualified, and industrial-tier products segments buyers by certification burden. Cost compression in automotive-tier supply is intensifying because sulfide ceramic processing yields remain below volume thresholds. Consumer electronics assemblers exhibit highest price sensitivity; aviation OEMs accepting cell-level performance warranties show least.
Supply Chain Analysis
High-purity silane gas supply rests on Japanese and South Korean specialty chemical producers serving both semiconductor and battery anode markets. Raw material dependencies span lithium-metal foils, sulfide ceramic precursors, and silicon nanowire growth substrates. Single-source vulnerability concentrates in East Asian chemical clusters where semiconductor fabrication competes for identical feedstock. Distribution runs through qualified cell manufacturers directly to automotive OEMs and aviation airframers, bypassing traditional tier-one electrical integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH nanomaterial registration costs in Europe run substantially higher than GB standard compliance pathways in China, tilting greenfield investment toward jurisdictions with lighter documentation burdens.
For Market Incumbents: To counter silicon nanowire precursor cost volatility, secure long-term offtake agreements with high-purity silane suppliers in East Asian chemical clusters. Anchor manufacturing scale through backward integration into electrode coating operations, capturing margin that currently concentrates with equipment vendors holding dry deposition expertise. For New Entrants and Emerging Players: Solid-state maritime propulsion systems represent the most penetrable white-space target, where IMO thermal runaway immunity requirements filter out liquid electrolyte incumbents. Enter through technology licensing partnerships with sulfide ceramic specialists, avoiding capital-intensive pilot line construction. For Investors and Strategic Acquirers: Valuations sit cheapest among nanomaterial synthesis specialists controlling in-house particle production. Five-to-ten year viability hinges on successful navigation of multi-jurisdictional certification timelines. Watch FAA certification pathway acceleration for electric propulsion systems as the signal indicating aviation-grade demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Pilot Line Scale-Up | CATL suppliers in China's Yangtze River Delta are expanding silicon nanowire anode capacity to meet MIIT production quotas. |
| REACH Registration Dossier Consolidation | German automotive suppliers are narrowing procurement to anode producers with pre-validated ECHA documentation. |
| Aviation-Grade Certification Acceleration | FAA pathway compression from 48 to 18 months is rewiring supplier qualification economics for electric vertical takeoff manufacturers. |
| Silane Gas Supply Backward Integration | Anode manufacturers are securing captive high-purity precursor supply to offset semiconductor industry competition. |
| Medical Device Dual-Track Submission | Implantable cell suppliers are filing concurrent FDA and EMA applications, extending qualification cycles but locking biocompatible market access. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from solid-state cell engineering directors, automotive OEM procurement leads, aviation battery system architects, sulfide ceramic materials specialists, and implantable device regulatory affairs managers. Secondary validation drew from MIIT production quota disclosures, FAA certification pathway documentation, ECHA REACH registration databases, and SEC filings of publicly traded battery manufacturers. Bottom-up cell shipment modeling and top-down OEM procurement budget analysis were cross-referenced for triangulation.
Segment-weighting applied product architecture splits across solid-state and liquid electrolyte formats, with further granularity by end-use application tier and regional regulatory cluster. Growth trajectories across the analysis window were derived from OEM platform launch timelines and certification cycle compression rates. Industry-specific inputs included aviation energy density threshold evolution and GB standard revision schedules for nanomaterial handling.
The model holds under stable regulatory classification regimes for engineered nanomaterials; deviation in REACH threshold revisions or FAA pathway acceleration would shift capacity investment geography. Forecasts reflect documented assumptions regarding sulfide ceramic yield improvement curves and silane gas supply expansion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
AI Edge Computing Market
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
3D Electronics Market
Emerging and Next Generation Technologies
Global Metamaterial Market
Emerging and Next Generation Technologies
Next Generation Processors Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
North America Next Generation Computing Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market