
 MLDW Technology Market | 2026-2036
MLDW Technology Market Size, Share, and Industry Trends Forecast 2026-2036
MLDW Technology Market Analytics
Multi-source procurement for optical networking hardware is pivoting toward vertically integrated cloud platforms as enterprises consolidate vendor relationships. Snowflake leverages proprietary data architecture to sustain differentiation in workload-optimized deployments. Amazon Web Services anchors global infrastructure scale, while Databricks specializes in unified analytics workloads that compete with legacy data warehouse providers.
MLDW (Multi-Lambda Dense Wavelength) technology multiplexes multiple optical wavelengths onto single fiber strands, typically operating in the C-band and L-band with channel spacing of 100 GHz or less to maximize spectral efficiency. The primary commercial purpose centers on expanding fiber optic capacity without laying additional physical cable. Cloud-based deployment leads structural momentum as hyperscalers absorb capacity at scale, while edge computing segments represent the fastest-expanding margin pool due to latency-sensitive applications in autonomous systems and real-time telemetry. On-premises infrastructure retains entrenched positions within defense and classified aerospace environments where data localization remains non-negotiable.
FCC spectrum management rules in the United States, EU Green Deal energy-efficiency standards for data infrastructure, and Japan's METI guidelines on optical network reliability collectively shape product certification requirements and procurement eligibility. Compliance with these frameworks determines market access for transceiver and amplifier manufacturers serving regulated end users. Stakeholders must monitor divergence between regional energy-efficiency mandates and performance benchmarks as procurement criteria harden across telecommunications and defense verticals.
Market Dynamics
Telecommunications operators are consolidating optical infrastructure procurement around vertically integrated cloud platforms, compressing vendor relationships while hyperscalers absorb wavelength capacity at unprecedented scale across distributed fiber networks.
Growth Catalysts
- EU AI Act compliance mandates:Cross-border data processing architectures in Europe now require sovereign edge infrastructure, accelerating MLDW deployments in Frankfurt and Amsterdam data corridors to satisfy localization requirements.
- Industrial automation clusters:German automotive OEMs are integrating edge-computing MLDW nodes directly into production telemetry systems for real-time quality control and predictive maintenance workflows.
- C-band spectral expansion:Dense wavelength multiplexing in the extended C-band is unlocking additional fiber capacity without new cable deployment, particularly across Pacific submarine routes connecting Tokyo and Los Angeles.
Market Restraints
- Erbium-doped fiber amplifier supply concentration:Specialty photonic component manufacturing concentrates in select East Asian foundries, exposing procurement timelines to single-source bottlenecks during demand surges.
- EU Green Deal energy-efficiency standards:Thermal design power thresholds for data infrastructure are tightening certification windows, forcing redesign cycles that extend product qualification timelines by 8-14 months.
- Silicon photonics substitution threat:Co-packaged optical engines using CMOS-compatible processes are capturing intra-data center interconnect volumes below 10 kilometers, compressing addressable market for traditional discrete transceivers.
Strategic Opportunities
- Defense and classified aerospace verticals:On-premises MLDW infrastructure retains entrenched demand in facilities requiring air-gapped wavelength routing with zero external network dependency.
- Japan METI optical reliability guidelines:Seismic resilience mandates for critical communication infrastructure are creating procurement preference for hardened amplifier designs certified to enhanced environmental stress protocols.
- Coherent DSP-wavelength convergence:Integration of digital signal processing directly into line-side transponders is collapsing separate component procurement into unified platform decisions, favoring vertically integrated system vendors.
Industry Challenges
- Specialized photonic integration engineering:The intersection of III-V semiconductor fabrication and silicon photonics packaging requires talent pools concentrated in fewer than twelve global research clusters, constraining expansion timelines.
- FCC spectrum management certification complexity:Optical power level approvals for terrestrial and submarine deployments operate under divergent procedural tracks, fragmenting product qualification roadmaps and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MLDW Technology Market |
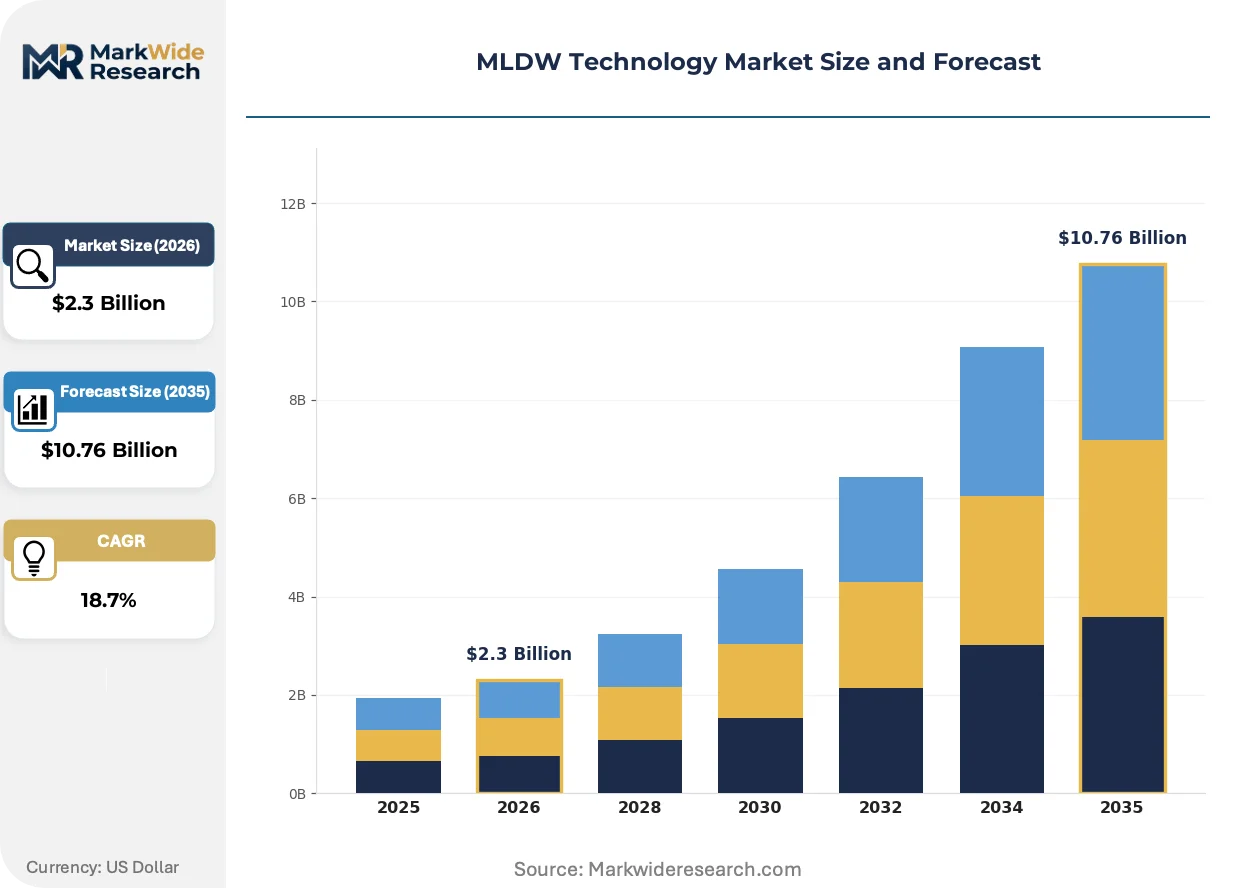
| Market Size in 2026 | $2.3 Billion |
| Market Size in 2035 | $10.76 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transceivers, Amplifiers, Switches, Sensors Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Telecommunications, Aerospace, Automotive, Defense Solution: Integrated Systems, Infrastructure Upgrades, Software Platforms, Analytics Tools |
| Companies Covered | Snowflake, Amazon Web Services, Google Cloud, Microsoft Azure, Databricks, Oracle, Teradata, IBM, Cloudera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MLDW Technology Market Evolving Landscape
Open optical line systems are dismantling traditional vendor lock-in architectures, enabling disaggregated procurement of transponders, amplifiers, and optical supervisory layers from competing suppliers within unified network management frameworks.
Pluggable coherent transceivers operating at 400G and 800G per wavelength is modularizing how telecommunications operators build transport networks. Regional carriers in Southeast Asia are adopting these hot-swappable interfaces to collapse capital deployment cycles from multi-year chassis upgrades to incremental port additions. This modularity is compressing the economic threshold for fiber capacity expansion in secondary metro markets previously served by leased dark fiber.
Japan's METI guidelines on optical network reliability are mandating redundant amplifier configurations and automated protection switching for designated critical infrastructure routes. Equipment vendors must now submit seismic stress testing documentation and 25-year operational life projections to qualify for public telecommunications procurement. Submarine cable consortiums connecting Tokyo, Singapore, and Sydney are restructuring maintenance liability frameworks to align with these extended durability requirements.
Enterprise buyers are consolidating optical networking procurement through hyperscale cloud marketplaces rather than direct OEM negotiations. Financial services firms in London and Singapore are sourcing wavelength services through AWS Direct Connect and Azure ExpressRoute portals, displacing traditional carrier managed wavelength contracts. This channel migration is most pronounced among multinational corporations operating distributed trading floors requiring sub-millisecond latency symmetry across Frankfurt, Chicago, and Tokyo.
MLDW Technology Market Segmentation
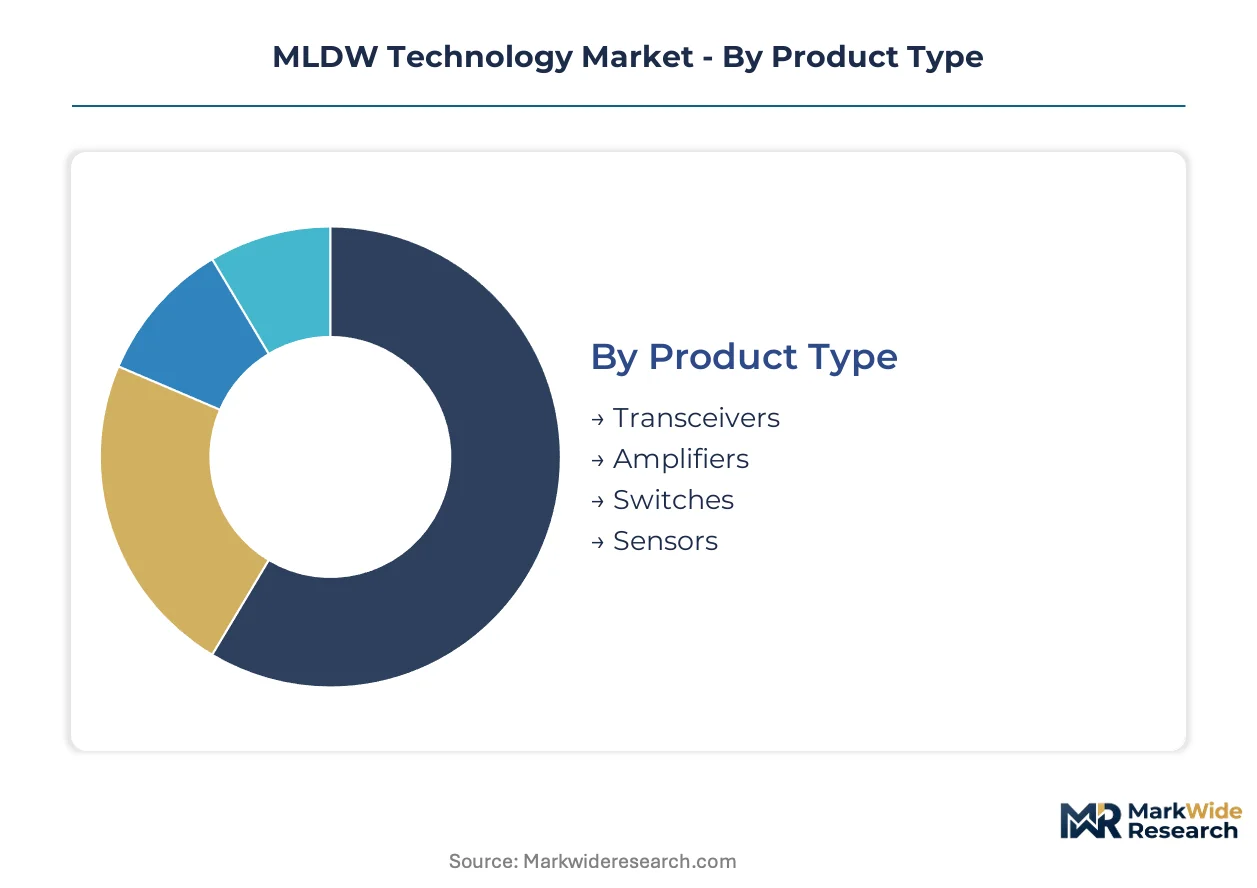
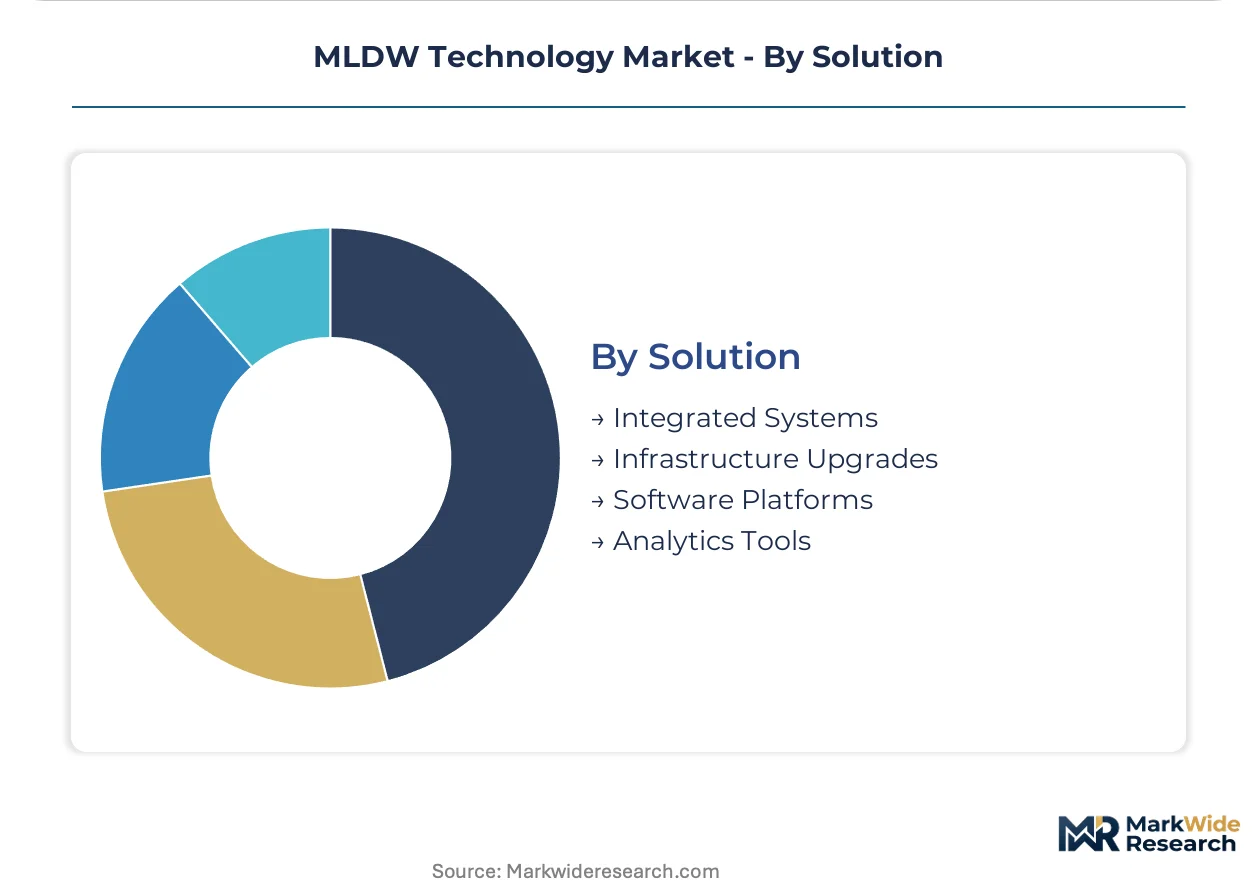
MLDW technology segments reflect divergent procurement cycles across optical networking infrastructure. Component-level purchases follow semiconductor fab capacity, while system-level deployments track data center construction timelines and sovereign compliance mandates.
Product Type:
Upgrade cycles for optical hardware compress as pluggable coherent interfaces modularize procurement decisions.
- Transceivers:Pluggable coherent modules operating at 400G and 800G per wavelength integrate digital signal processing with optical conversion. Demand clusters in hyperscale cloud interconnects across Tokyo, Frankfurt, and Los Angeles as hyperscalers absorb wavelength capacity at scale.
- Amplifiers:Erbium-doped fiber amplifiers and Raman amplification stages extend signal reach across submarine and terrestrial routes. Procurement concentrates in Pacific cable consortiums connecting East Asian foundries to North American landing stations, constrained by specialty photonic component supply bottlenecks.
- Switches:Optical circuit switches enable wavelength routing without electrical conversion.
- Sensors:Optical performance monitors and spectral analyzers support network supervisory layers.
Volume placements concentrate in Transceivers; the faster expansion belongs to Amplifiers.
Deployment:
Cost tier differentiation separates capital-intensive chassis upgrades from incremental port additions.
- Cloud-Based:Hyperscale operators provision wavelength capacity through unified orchestration platforms. AWS, Azure, and Google Cloud absorb the majority of new deployment volume across distributed fiber networks in Virginia, Dublin, and Singapore.
- Edge Computing:Latency-sensitive nodes deploy MLDW infrastructure for autonomous systems and real-time telemetry. German automotive OEMs integrate these systems directly into production quality control workflows.
- On-Premises:Air-gapped wavelength routing serves defense and classified aerospace facilities.
- Hybrid:Mixed cloud-edge architectures balance sovereignty requirements with scalability.
Cloud-Based deployments absorb the largest capital allocation; Edge Computing climbs the fastest as industrial automation clusters expand.
End User:
Application requirements dictate spectral efficiency targets and environmental hardening specifications.
- Telecommunications:Carriers consolidate optical infrastructure procurement around vertically integrated platforms. FCC spectrum management rules and EU Green Deal energy-efficiency standards shape certification requirements for terrestrial and submarine routes.
- Defense:Classified facilities mandate on-premises MLDW with zero external network dependency. Procurement prioritizes air-gapped wavelength routing and redundant amplifier configurations.
- Aerospace:Satellite ground stations and telemetry networks require hardened optical interfaces.
- Automotive:Production telemetry systems integrate edge-computing nodes for predictive maintenance.
Telecommunications dominates procurement volume; Defense maintains the steepest expansion trajectory amid sovereign infrastructure mandates.
Solution:
Customer type separates turnkey system purchases from modular software and analytics procurement.
- Infrastructure Upgrades:Chassis replacements and line-side transponder deployments extend existing fiber capacity. Regional carriers in Southeast Asia adopt hot-swappable interfaces to collapse multi-year upgrade cycles.
- Integrated Systems:Unified platforms combine transponders, amplifiers, and optical supervisory layers. Vertical integration favors vendors offering coherent DSP-wavelength convergence.
- Software Platforms:Open optical line systems enable disaggregated network management.
- Analytics Tools:Performance monitoring and predictive maintenance applications support operational visibility.
Infrastructure Upgrades represent the largest near-term revenue pool; Integrated Systems gain share fastest as procurement consolidates around unified platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and telecommunications operators concentrate regional demand for edge-computing MLDW nodes, while hyperscale cloud absorption drives capacity expansion across Pacific submarine corridors connecting East Asian foundries to North American landing stations.
United States
Hyperscale cloud operators in Virginia and California absorb wavelength capacity at unprecedented scale through AWS and Azure infrastructure. FCC spectrum management rules govern optical power level approvals for terrestrial and submarine deployments under divergent procedural tracks. Financial services firms in Chicago source wavelength services through cloud marketplaces, displacing traditional carrier managed contracts.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg integrate MLDW nodes directly into production telemetry systems for real-time quality control. EU AI Act compliance mandates require sovereign edge infrastructure in Frankfurt and Amsterdam data corridors to satisfy cross-border data localization requirements. Automotive OEMs in Stuttgart deploy edge-computing nodes for predictive maintenance workflows.
Japan
Submarine cable consortiums connecting Tokyo to Singapore and Sydney restructure maintenance liability frameworks around extended durability requirements. METI guidelines mandate redundant amplifier configurations and automated protection switching for designated critical infrastructure routes. Equipment vendors submit seismic stress testing documentation and 25-year operational life projections to qualify for public telecommunications procurement.
United Kingdom
Financial services firms in London consolidate optical networking procurement through hyperscale cloud marketplaces rather than direct OEM negotiations. EU Green Deal energy-efficiency standards shape thermal design power thresholds for data infrastructure certification. Trading floors require sub-millisecond latency symmetry across Frankfurt, Chicago, and Tokyo corridors.
Singapore
Regional carriers in Southeast Asia adopt pluggable coherent interfaces to collapse capital deployment cycles from multi-year chassis upgrades to incremental port additions. This modularity compresses the economic threshold for fiber capacity expansion in secondary metro markets previously served by leased dark fiber. Multinational corporations operating distributed trading floors source wavelength services through cloud portals.
MLDW Technology Market Competitive Landscape
Strategic partnerships dominate the current landscape as telecommunications operators consolidate optical infrastructure procurement around vertically integrated cloud platforms. The vendor base concentrates around three distinct tiers: hyperscale cloud providers absorbing wavelength capacity, specialized data platform vendors offering unified analytics, and legacy enterprise database providers defending installed base positions. Two competitive moves define current positioning: backward integration into proprietary data architectures and geographic expansion through submarine cable consortium participation.
Within the cloud infrastructure tier, Amazon Web Services and Microsoft Azure anchor global scale positions through distributed fiber network absorption. Snowflake occupies a differentiated position representing workload-optimized deployment architecture, while Databricks exemplifies unified analytics specialization competing with legacy data warehouse providers. Oracle and IBM sit within the enterprise-installed-base tier, defending positions through existing customer relationships rather than greenfield wavelength capacity capture.
| Leading Market Players |
|---|
| Snowflake |
| Amazon Web Services |
| Google Cloud |
| Microsoft Azure |
| Databricks |
| Oracle |
| Teradata |
| IBM |
| Cloudera |
| Others |
Value Network & Pricing Analysis
Erbium-doped fiber amplifier manufacturing costs hinge on specialty III-V semiconductor substrates sourced through East Asian foundries, cascading into premium pricing tiers for defense-certified transceivers versus standard telecommunications modules.
Pricing Analysis
Volume placements concentrate in standard-grade coherent transceivers serving hyperscale cloud interconnects, while margin pools accrue to hardened amplifier designs certified under Japan METI seismic resilience protocols. Price differentiation separates CE-marked commercial hardware from ITAR-restricted defense components requiring air-gapped wavelength routing. Cost compression in the standard telecommunications tier is intensifying because silicon photonics substitution threatens discrete transceiver volumes below ten kilometers. Financial services firms operating sub-millisecond latency trading floors exhibit the least price sensitivity; regional carriers in Southeast Asian secondary metro markets remain most price-sensitive.
Supply Chain Analysis
Photoresist and specialty doping materials for erbium-fiber fabrication rest on Japanese chemical producers and Taiwanese semiconductor foundries, with final amplifier assembly concentrating in South Korea and China. Raw material dependencies span rare-earth elements for doping, high-purity silica for fiber drawing, and indium phosphide for photonic integration. Single-source vulnerability in erbium-doped fiber amplifier manufacturing exposes procurement timelines to demand surge bottlenecks. Distribution runs through direct OEM relationships for defense verticals and hyperscale cloud marketplaces for enterprise wavelength services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty photonic component manufacturing capacity constraints prop pricing power for vertically integrated system vendors, as single-source bottlenecks in East Asian foundries limit rapid supply expansion.
For Market Incumbents: Acquire coherent DSP engineering teams to collapse separate component procurement into unified platform decisions. Backward integration into captive erbium-doped fiber amplifier production mitigates single-source exposure from East Asian foundry concentration. Certification investment under EU Green Deal thermal design power thresholds extends product qualification timelines but locks out modular competitors lacking capital reserves. For New Entrants and Emerging Players: Launch via open optical line system partnerships enabling disaggregated procurement from competing suppliers within unified network management frameworks. Edge-computing nodes for German automotive OEM production telemetry represent the most penetrable white-space target, as industrial automation clusters expand faster than hyperscale cloud absorption. Channel through hyperscale cloud marketplaces rather than direct OEM negotiations to bypass entrenched carrier relationships. For Investors and Strategic Acquirers: EU AI Act sovereign infrastructure mandates in Frankfurt and Amsterdam data corridors are the leading indicator that defense-classified verticals will sustain premium pricing tiers. Long-term viability favors vertically integrated system vendors offering coherent DSP-wavelength convergence over discrete component specialists facing silicon photonics substitution. Watch for submarine cable consortium restructuring around Japan METI extended durability requirements as the inflection signal for hardened amplifier design premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amplifier Manufacturing | Captive erbium-doped fiber production mitigates East Asian foundry single-source bottlenecks. |
| Open Optical Line System Certification | Disaggregated procurement frameworks dismantle traditional vendor lock-in architectures. |
| Edge-Computing Node Deployment | German automotive OEMs integrate MLDW infrastructure into predictive maintenance workflows. |
| Coherent DSP-Wavelength Convergence | Integration of digital signal processing collapses separate component procurement decisions. |
| Japan METI Seismic Resilience Qualification | Extended durability certification creates procurement preference for hardened amplifier designs. |
Research Methodology
Document review covered SEC filings from hyperscale cloud operators, FCC spectrum management dockets, EU AI Act implementation guidance, and Japan METI optical reliability standards, complemented by interviews with telecommunications procurement directors, defense systems integrators, submarine cable consortium engineers, and optical component manufacturing executives. Secondary validation drew from customs trade data for erbium-doped fiber amplifier shipments, hyperscaler capital expenditure disclosures, and telecommunications operator infrastructure spending reports. Bottom-up component demand modeling triangulated against top-down wavelength capacity absorption forecasts.
Market size and growth trajectory outputs across the analysis window reflect segment-level modeling of transceiver, amplifier, and switch procurement cycles, with deployment mode segmentation spanning cloud-based, edge-computing, on-premises, and hybrid architectures. CAGRs were derived from installed base replacement curves and hyperscale capacity absorption rates. Industry-specific forecast inputs included EU Green Deal thermal design power compliance timelines and Japan METI seismic stress testing documentation requirements.
The model assumes a particular technology adoption path; alternative pathways for silicon photonics co-packaged optical engines would alter the outlook for discrete transceiver demand below ten kilometers. Forecasts reflect assumptions regarding hyperscale cloud marketplace channel migration and defense air-gapped infrastructure mandates. Regulatory divergence between EU energy-efficiency standards and FCC spectrum management rules, alongside specialty photonic component supply concentration, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Next Generation Processors Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
Flexible PV Cell Market
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market
Emerging and Next Generation Technologies
Transparent Electronics Market