
 MET-PET Cartons Market | 2026-2036
MET-PET Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
MET-PET Cartons Market Foresight
Beverage industry demand is rebalancing toward shelf-stable liquid cartons as brands seek alternatives to conventional multilayer packaging. Amcor plc leverages its global manufacturing footprint to supply high-barrier MET-PET structures across multiple continents. Mondi Group anchors European demand through integrated paperboard and metallized film operations. Uflex Limited competes on cost-engineered solutions for emerging market dairy and juice applications.
MET-PET cartons are laminated packaging structures combining metallized polyethylene terephthalate film with paperboard substrates, typically achieving oxygen transmission rates below 0.1 cc per square meter per day to preserve sensitive contents. The primary commercial purpose centers on extending shelf life for liquid and semi-solid food products while enabling aseptic filling compatibility. Liquid cartons dominate current volume as the most mature application segment with established filling line infrastructure across dairy and juice operations. Composite cartons represent the fastest-growing structural category as brands pursue hybrid barrier performance without full aluminum lamination. Recyclable packaging types command margin premiums in European and North American retail procurement where Extended Producer Responsibility frameworks impose material recovery targets.
The US FDA regulates indirect food contact substances through 21 CFR compliance pathways that govern metallized layer migration limits into packaged contents. Europe's REACH and F-Gas Regulation restrict certain fluorinated barrier chemistries while the EU Green Deal pushes recycled content mandates across packaging value chains. India's BIS certification requirements and FSSAI food contact standards create formal compliance thresholds for imported MET-PET structures entering domestic dairy supply chains. Stakeholders must monitor evolving extended producer responsibility legislation and recycling infrastructure investments to align product development with emerging collection and reprocessing capabilities.
Market Dynamics
Europe's F-Gas Regulation and REACH compliance mandates are forcing rapid material substitution across the MET-PET carton supply chain, compressing development timelines for fluorinated barrier alternatives while recyclability targets harden procurement specifications in retail and foodservice channels.
Growth Catalysts
- EU Green Deal recycled content mandates:Extended Producer Responsibility frameworks in Germany and France now require minimum recycled thresholds in beverage packaging, pulling brands toward MET-PET structures with demonstrable circularity credentials.
- Dairy sector shelf-life extension:India's FSSAI food contact standards and Brazil's ANVISA dairy safety protocols are accelerating adoption of high-barrier cartons for ambient distribution in tropical climates.
- Aseptic filling line compatibility:Retrofit investments at juice processing facilities in India and Germany favor MET-PET laminates over aluminum-dependent alternatives, reducing line conversion costs.
Market Restraints
- Aluminum price volatility:Metallized PET film production remains tethered to aluminum vacuum deposition costs, exposing converters to London Metal Exchange fluctuations that compress margin predictability.
- European supply concentration:Specialty metallized film capacity clusters in Germany and Italy, creating single-source vulnerability for brands requiring REACH-compliant barrier specifications.
- Mechanical recycling incompatibility:Multi-layer paperboard-PET-aluminum structures face sorting contamination risks at European material recovery facilities, limiting circular economy claims.
Strategic Opportunities
- Brazil foodservice expansion:Quick-service restaurant chains in São Paulo and Rio de Janeiro are converting from rigid plastics to portion-controlled liquid cartons for fountain beverage and sauce applications.
- Water-soluble adhesive innovation:Delamination technology enabling clean fiber recovery is converging with paperboard substrate advances, opening premium positioning in German retail private label programs.
- India BIS certification acceleration:Streamlined import testing protocols for food-contact laminates reduce time-to-market for international suppliers targeting domestic dairy cooperatives.
Industry Challenges
- Vacuum metallization technician scarcity:Specialized operators capable of maintaining oxygen transmission rate consistency below 0.1 cc per square meter per day remain concentrated in European and Japanese equipment hubs.
- Legacy filling line integration:Aseptic carton converters face retrofit complexity when adapting existing Tetra Pak and SIG Combibloc infrastructure to MET-PET web tension specifications.
- Multi-jurisdiction certification sequencing:Simultaneous FDA 21 CFR, REACH, and BIS compliance testing creates timeline compression for product launches targeting transnational beverage brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MET-PET Cartons Market |
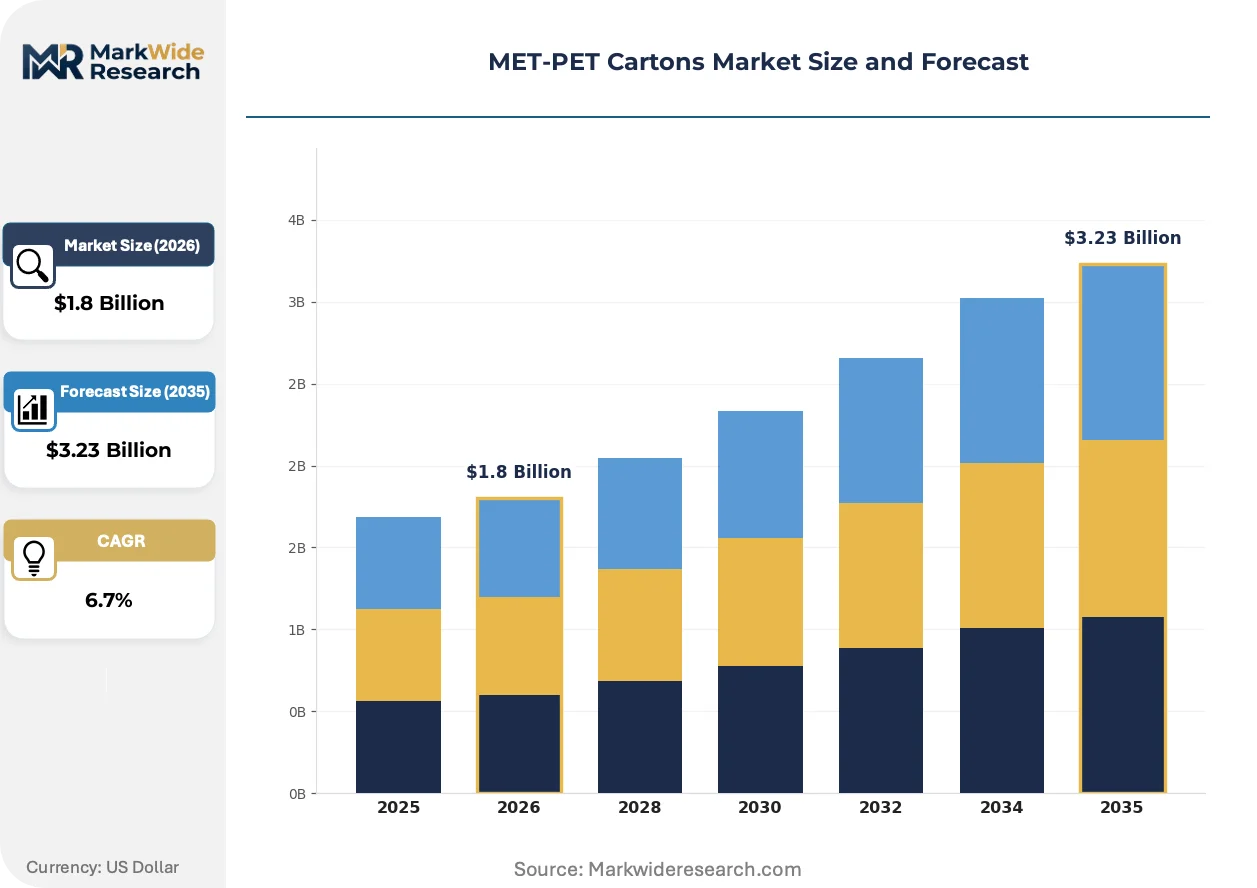
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cartons, Solid Cartons, Composite Cartons, Printed Cartons Application: Beverages, Dairy Products, Sauces, Ready Meals End User: Food Industry, Beverage Industry, Retail Sector, Foodservice Packaging Type: Recyclable, Biodegradable, Tamper-proof, Shelf-stable |
| Companies Covered | Amcor plc, Berry Global, Sealed Air Corporation, Mondi Group, Toray Industries, Uflex Limited, Constantia Flexibles, Silgan Holdings, Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MET-PET Cartons Market Shifts & Advancements
Barrier chemistry innovation and regulatory chemistry restrictions are running in parallel, forcing material scientists to engineer oxygen and moisture protection without fluorinated compounds or full aluminum lamination. Three converging developments are restructuring competitive positioning.
Silicon oxide (SiOx) and aluminum oxide (AlOx) transparent barrier coatings are converging with metallized PET substrates to create hybrid structures that maintain shelf-life performance while improving optical scanning compatibility at recycling facilities. German dairy brands and Indian juice processors are piloting these laminates at commercial scale. The technology is converging with existing filling infrastructure, reducing capital barriers to adoption.
REACH authorization restrictions on per- and polyfluoroalkyl substances (PFAS) are eliminating certain grease-resistant barrier chemistries from European food-contact applications. Converters must reformulate adhesive and coating systems to maintain performance under revised ECHA substance evaluation timelines. Liquid carton applications for fatty and acidic contents face the steepest compliance curves, with German and French regulators accelerating enforcement.
Beverage brand technical procurement teams are consolidating supplier relationships around vertically integrated converters capable of certifying full chain-of-custody documentation. This behavior compresses the qualified vendor pool while elevating contract duration and volume commitments. The shift is most visible in German retail and Indian dairy cooperative sourcing, where sustainability audit requirements now precede price negotiation.
MET-PET Cartons Market Segmentation
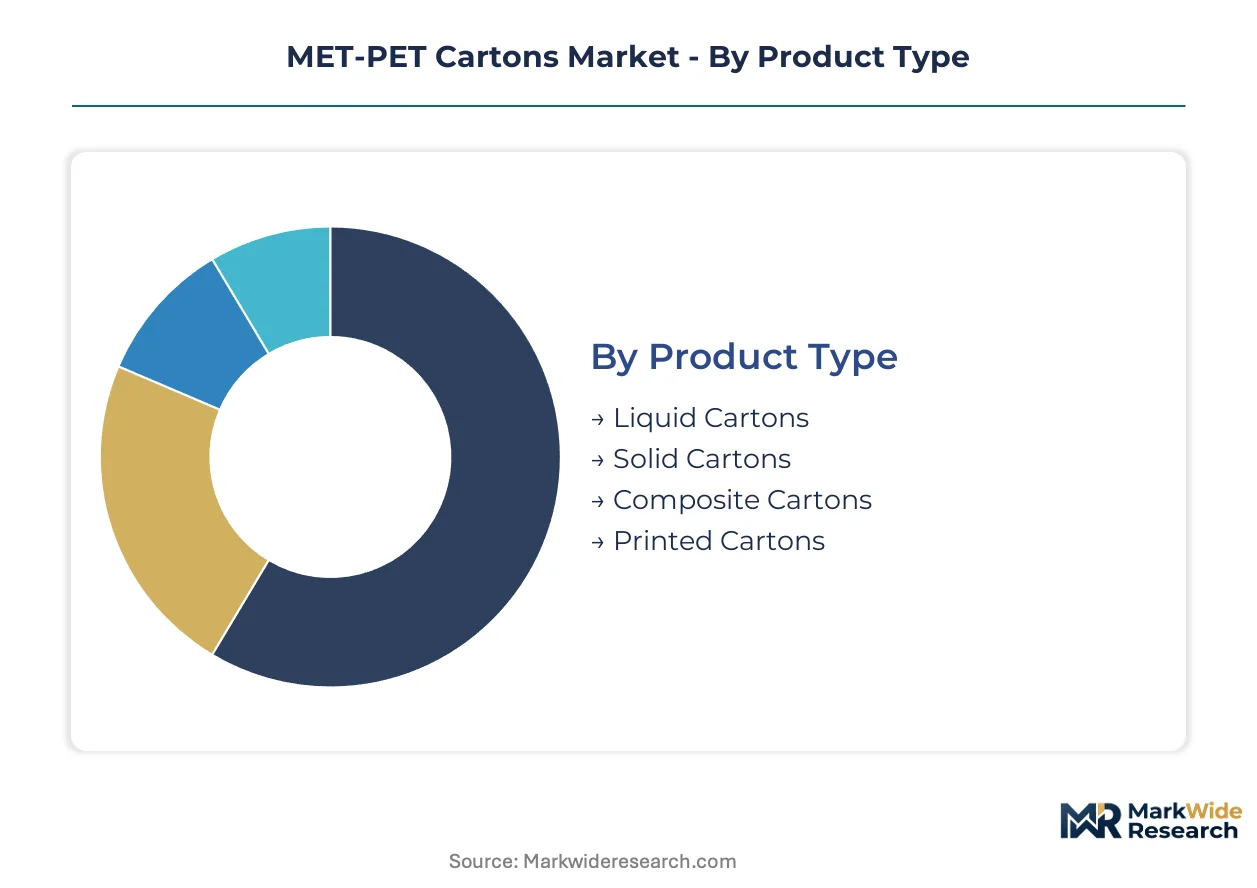
MET-PET carton specifications diverge sharply across filling infrastructure, barrier requirements, and end-use thermal stress. Procurement teams segment primarily by aseptic compatibility and recyclability credentials, with European retail and Indian dairy cooperatives driving the tightest performance specifications.
Product Type:
Buyers prioritize oxygen transmission rates and filling line compatibility when selecting carton structures, with aseptic juice processors and ambient dairy distributors maintaining distinct technical requirements.
- Liquid Cartons:These structures dominate current installed base with established oxygen barriers below 0.1 cc per square meter per day. German juice processors and Indian UHT milk cooperatives concentrate procurement here due to retrofit economics at existing Tetra Pak and SIG Combibloc lines.
- Composite Cartons:Hybrid paperboard-PET-aluminum laminates without full metal dependency are gaining share fastest. São Paulo quick-service restaurant chains and Rio de Janeiro foodservice distributors are converting rigid plastic sauce portions to these formats for portion control and shelf stability.
- Solid Cartons:Semi-rigid structures for dry and viscous contents employ reduced metallization layers. Indian confectionery and spice exporters utilize these for moisture-sensitive exports to Middle Eastern retail.
- Printed Cartons:Direct-to-substrate gravure and flexo capabilities enable brand differentiation at point-of-sale. German private label dairy programs specify these for retail shelf impact.
Volume sits with Liquid Cartons; growth tilts toward Composite Cartons.
Application:
End-use thermal stress and pH levels dictate barrier chemistry selection, with fatty and acidic contents facing the steepest reformulation curves under REACH PFAS restrictions.
- Beverages:Juice and nectar applications require aseptic filling compatibility with 6-12 month ambient shelf life. Indian processors and German retailers specify SiOx-AlOx hybrid coatings to replace fluorinated barriers under tightening ECHA timelines.
- Dairy Products:UHT milk and cream demand the tightest oxygen barriers for tropical distribution. Brazil's ANVISA dairy protocols and India's FSSAI standards are accelerating high-barrier carton adoption for ambient supply chains.
- Sauces:Acidic and fatty contents stress adhesive and coating systems. São Paulo foodservice distributors are shifting from rigid plastics to portion-controlled liquid cartons for fountain and condiment applications.
- Ready Meals:Retort-compatible structures face higher thermal stress than aseptic applications. European retail private label programs are piloting these for ambient meal kit components.
Dairy Products anchor current procurement volumes; Beverages are climbing the fastest as fluorinated barrier substitution accelerates.
End User:
Extended Producer Responsibility frameworks and sustainability audit requirements now precede price negotiation in consolidated supply relationships.
- Food Industry:Processors of ambient-stable goods specify chain-of-custody documentation for circularity claims. German dairy cooperatives and Indian milk federations dominate technical procurement here.
- Beverage Industry:Juice and nectar brands face the tightest Green Deal recycled content mandates. French and German retail procurement teams are consolidating vendor relationships around vertically integrated converters.
- Retail Sector:Private label programs specify optical scanning compatibility for recycling infrastructure. German supermarket chains are piloting water-soluble adhesive laminates for clean fiber recovery.
- Foodservice:Quick-service restaurant chains prioritize portion control and tamper evidence. Brazilian operators in São Paulo and Rio de Janeiro are converting from rigid plastics to liquid cartons.
Food Industry holds the largest contract volumes; Retail Sector is expanding most quickly as EPR compliance hardens.
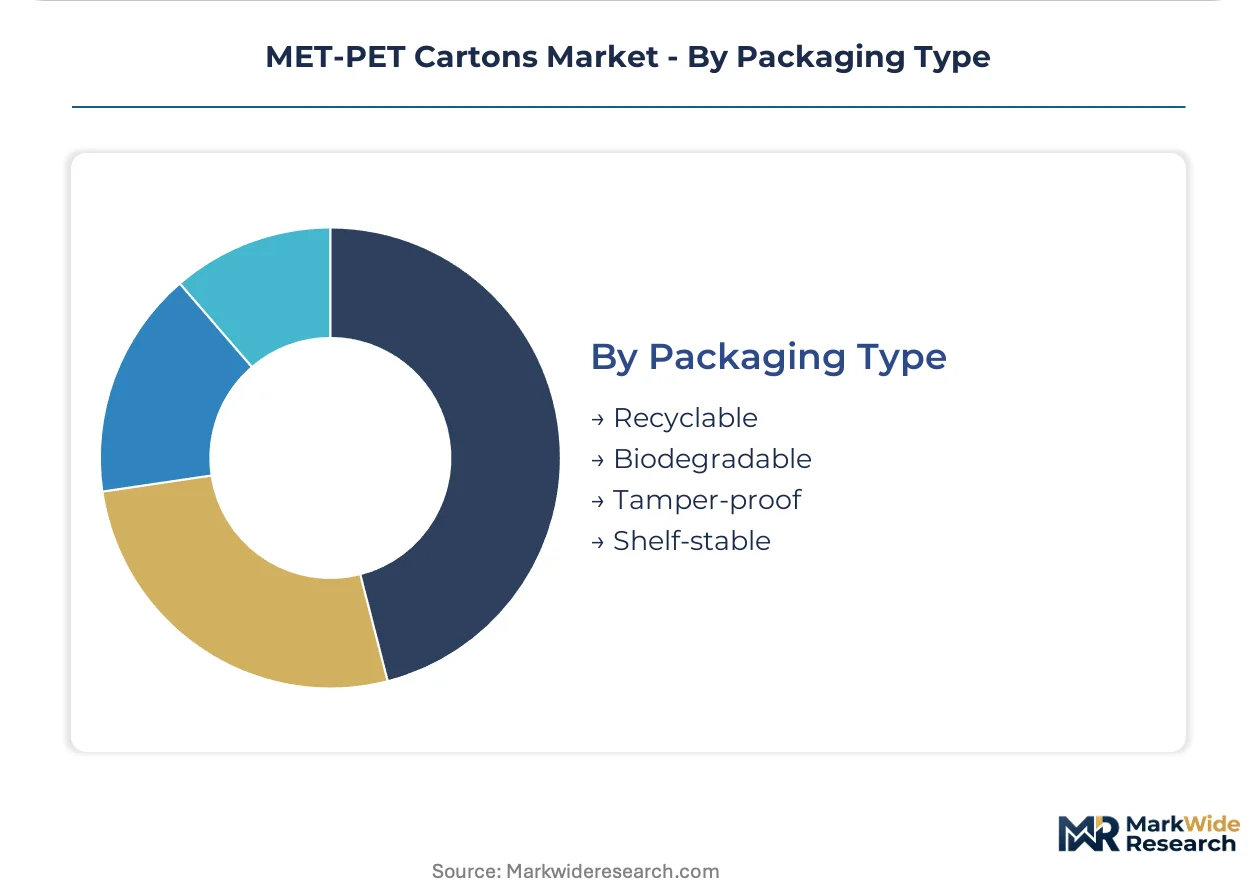
Packaging Type:
Material recovery facility compatibility and reprocessing economics determine premium positioning in European and North American procurement.
- Recyclable:Paperboard-fiber recovery rates depend on clean delamination technology. German retail programs command margin premiums for certified circular structures with demonstrated sorting compatibility.
- Tamper-proof:Induction seal and break-ring specifications dominate foodservice and pharmaceutical-adjacent applications. Brazilian quick-service chains specify these for fountain beverage safety.
- Shelf-stable:Ambient distribution capability without cold chain dependency drives adoption in tropical climates. Indian dairy and juice processors prioritize these for rural distribution expansion.
- Biodegradable:Limited commercial scale due to barrier performance trade-offs. Pilot programs in European organic retail channels test compostable adhesive alternatives.
Recyclable structures command the highest unit margins; Shelf-stable formats are gaining share fastest in tropical distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for food processing drive MET-PET carton concentration around dairy and juice manufacturing corridors. Brazil's Manaus Free Trade Zone and Germany's industrial clusters anchor regional supply networks.
Germany
Dairy cooperatives and juice processors dominate procurement for aseptic filling lines. The EU Green Deal and F-Gas Regulation mandate fluorinated barrier substitution by 2026. Bavaria's dairy processing belt around Munich anchors technical specification leadership.
India
UHT milk distribution expansion and tropical ambient storage requirements accelerate high-barrier carton adoption. FSSAI food contact standards and BIS certification create formal import thresholds. Maharashtra's dairy cooperatives and Karnataka's juice processing clusters concentrate demand.
Brazil
Quick-service restaurant chains convert rigid plastics to portion-controlled liquid cartons for fountain applications. ANVISA dairy safety protocols standardize shelf-life requirements. São Paulo and Rio de Janeiro foodservice distributors pilot composite carton formats.
United States
Shelf-stable beverage brands seek alternatives to multilayer packaging under Extended Producer Responsibility pressure. FDA 21 CFR compliance pathways govern metallized layer migration limits. California's beverage processing corridor and Midwest dairy operations drive technical procurement.
France
Retail private label programs specify optical scanning compatibility for recycling infrastructure. REACH PFAS restrictions eliminate certain grease-resistant barrier chemistries. Paris-region supermarket chains consolidate vendor relationships around circularity documentation.
MET-PET Cartons Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated converters commanding premium positioning in European retail while cost-engineered suppliers capture emerging market dairy volumes. The vendor base clusters around three strategic archetypes: global packaging conglomerates with metallized film captive supply, regional converters with filling line integration capabilities, and specialty barrier coaters with SiOx-AlOx hybrid technology. Capacity expansion and strategic partnerships dominate competitive moves as converters seek REACH-compliant barrier alternatives.
Among the integrated packaging conglomerates, Amcor plc and Mondi Group exemplify scale-driven positioning across multiple continents, while Uflex Limited occupies a cost-engineered niche for emerging market applications. Amcor leverages global manufacturing footprints to supply high-barrier structures. Mondi anchors European demand through integrated paperboard and metallized film operations. Uflex competes on price-engineered solutions for Indian dairy and juice processors.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Sealed Air Corporation |
| Mondi Group |
| Toray Industries |
| Uflex Limited |
| Constantia Flexibles |
| Silgan Holdings |
| Gerresheimer AG |
| Others |
Supply & Pricing Matrix
Vacuum metallization technician scarcity in Germany and Japan compresses labor-cost differentials into pricing-tier spreads, with European REACH-compliant converters commanding premium positioning against cost-engineered Indian suppliers serving tropical dairy markets.
Pricing Analysis
Short lead-time premiums for REACH-certified barrier specifications separate urgent procurement from contract-scheduled volumes, while spot aluminum price volatility creates margin compression at economy-tier converters. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and filling line integration depth. Price differentiation stems from SiOx-AlOx hybrid coating capabilities and demonstrated optical scanning compatibility at European material recovery facilities. Brand procurement teams at German retail chains exhibit lowest price sensitivity, while Indian dairy cooperatives prioritize cost-engineered solutions for rural distribution expansion.
Supply Chain Analysis
India's PLI scheme for food processing equipment and local-content mandates in Brazil's Manaus Free Trade Zone reshape sourcing patterns toward domestic assembly of metallized film lamination lines. Specialty metallized film capacity clusters in Germany, Italy, and Japan, drawing from aluminum vacuum deposition feedstock and paperboard substrate supply chains. Single-source vulnerability concentrates around REACH-compliant barrier specifications, with tariff exposure on imported metallized PET film intensifying at Indian and Brazilian converters. Distribution runs through vertically integrated packaging conglomerates with captive metallized film supply and regional converters with filling line integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
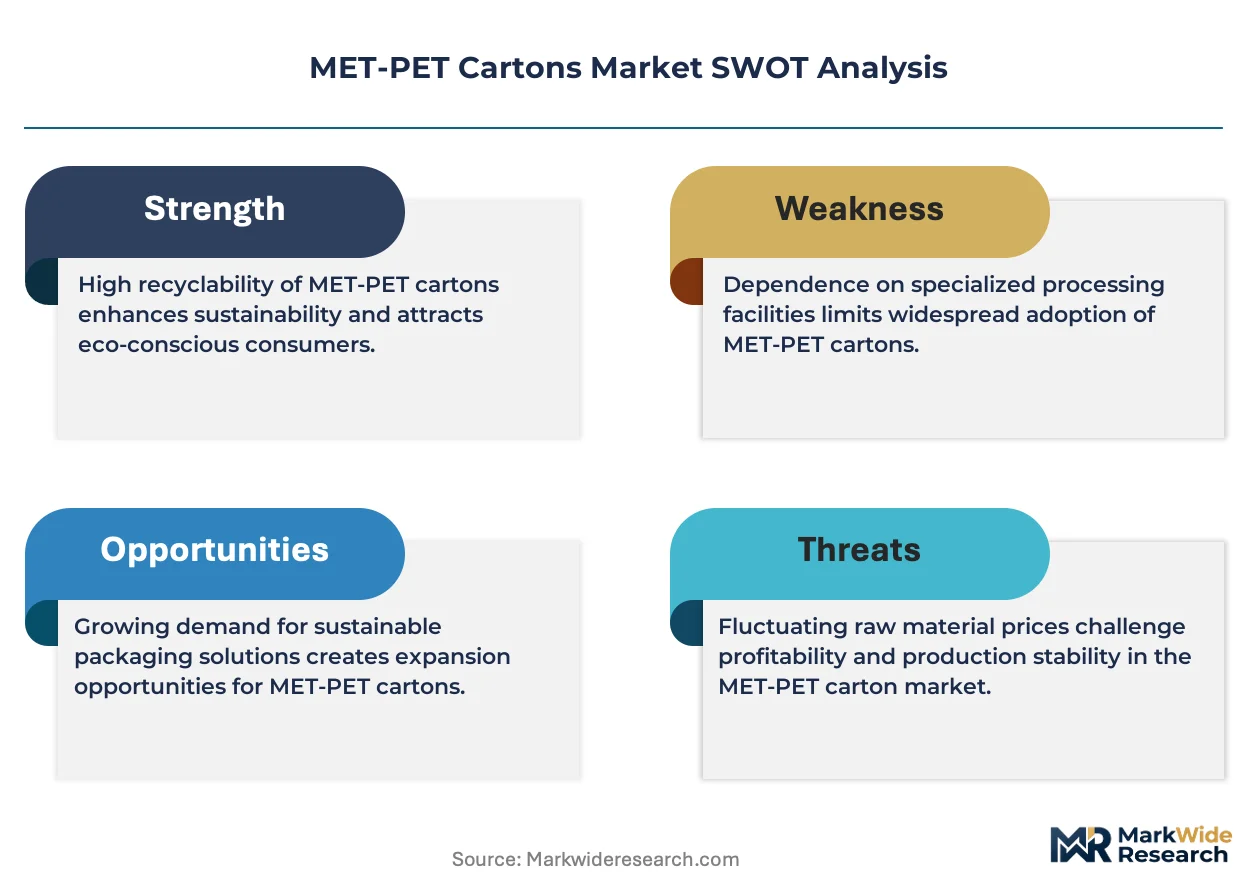
This market reads as a consolidation play where REACH PFAS substitution timelines and EPR compliance investments force smaller converters without barrier chemistry R&D capabilities toward exit or acquisition.
For Market Incumbents: Lock in multi-year offtake agreements with German dairy cooperatives and Indian milk federations before REACH authorization restrictions eliminate additional fluorinated barrier suppliers. Deepen backward integration into SiOx-AlOx coating technology to capture premium positioning as transparent barrier coatings displace conventional metallization for optical scanning compatibility. Prioritize certification investment for water-soluble adhesive delamination systems that enable clean fiber recovery claims in French and German retail procurement. For New Entrants and Emerging Players: Enter via São Paulo and Rio de Janeiro foodservice distribution networks where quick-service restaurant chains convert rigid plastics to portion-controlled liquid cartons for fountain applications. Target Brazilian ANVISA dairy safety protocol compliance as the most penetrable regulatory threshold, leveraging streamlined certification timelines against European REACH complexity. Pursue joint development agreements with Indian juice processors seeking aseptic filling line retrofit alternatives to aluminum-dependent laminates. For Investors and Strategic Acquirers: Re-rating potential sits with specialty barrier coaters possessing SiOx-AlOx hybrid technology and demonstrated filling line integration capabilities, given accelerating fluorinated chemistry substitution timelines under ECHA enforcement. Long-term viability favors converters with captive paperboard supply and in-house metallized film production across multiple regulatory jurisdictions. Watch for inflection at Indian BIS certification acceleration announcements signaling streamlined import pathways for international suppliers targeting domestic dairy cooperatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallized Film Production | Captive aluminum vacuum deposition capacity insulates margin from London Metal Exchange volatility at German converters. |
| SiOx-AlOx Hybrid Coating Scale-Up | Transparent barrier technology enables optical scanning compatibility at French material recovery facilities under EPR frameworks. |
| Water-Soluble Adhesive Certification | Demonstrated clean fiber recovery commands premium positioning in German retail private label procurement programs. |
| Brazil Foodservice Distribution Partnership | Quick-service restaurant fountain applications in São Paulo displace rigid plastics with portion-controlled liquid cartons. |
| India BIS Certification Acceleration | Streamlined import testing protocols reduce time-to-market for international suppliers targeting Maharashtra dairy cooperatives. |
Research Methodology
Multi-period observation of oxygen transmission rate specifications, filling line retrofit investments, and regulatory chemistry substitution timelines anchored the trend analysis, supplemented by interviews with vacuum metallization technicians, aseptic filling line engineers, dairy cooperative procurement managers, and retail private label category directors. Secondary validation drew from ECHA substance evaluation databases, BIS certification registries, ANVISA dairy safety protocols, and SEC filings of integrated packaging conglomerates. Bottom-up demand modeling across beverage, dairy, and foodservice applications triangulated against top-down supply capacity assessments at German, Italian, and Japanese metallized film production hubs.
Segment-weighting across liquid cartons, composite cartons, solid cartons, and printed cartons combined with application-level disaggregation by beverages, dairy products, sauces, and ready meals structured the analytical framework. End-user segmentation by food industry processors, beverage brands, retail private label programs, and foodservice distributors captured procurement behavior divergence under Extended Producer Responsibility frameworks. CAGRs derived from installed base growth at Tetra Pak and SIG Combibloc filling lines, tropical ambient distribution expansion in India and Brazil, and fluorinated barrier substitution velocity under REACH timelines. Forecast inputs incorporated aluminum price volatility scenarios and recycling infrastructure investment trajectories at European material recovery facilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA PFAS enforcement or prolonged aluminum supply disruption. Assumptions reflect current regulatory trajectories, filling line retrofit economics, and recycling infrastructure deployment schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Cupcake Box Market
Cartons
Mono Carton Market
Cartons
North America Corrugated Boxes Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Shaped Liquid Cartons Market
Cartons
Shaped Corrugated Packaging Market
Cartons
Interlocking Boxes Market
Cartons
GCC Folding Carton Market
Cartons
Metallized PET Cartons Market
Cartons
Folding Cartons Market
Cartons
Europe Corrugated Box Market
Cartons
Twist Opening Cartons Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Carton Liners Market
Cartons
Global Hand Carton Sealers Market
Cartons
Printed Folding Cartons Market