
 Soap Boxes Market | 2026-2036
Soap Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Soap Boxes Market Analytics
REACH compliance is expanding the cost-of-entry calculus for soap box suppliers targeting European personal care brands. WestRock leverages its North American containerboard footprint to serve mass-market soap producers with high-volume folding carton programs. Mondi Group anchors its competitive stance through integrated kraft paper operations that feed directly into recycled-content soap box specifications. DS Smith Plc competes on circular design credentials, operating closed-loop recycling systems that align with retailer sustainability mandates.
Soap boxes are paper-based or polymer containers engineered to protect bar soap from moisture, contamination, and mechanical damage during distribution and retail display, typically constructed from 12-24 point paperboard or food-grade polypropylene with moisture-barrier coatings. Folding cartons dominate volume due to their compatibility with high-speed auto-packing lines and cost efficiency for standard bar formats, while rigid boxes capture margin pools in the gift and luxury soap segments where structural integrity and unboxing experience command price premiums. Recycled materials represent the fastest-growing material category as brand owners respond to EPR legislation and consumer preference for post-consumer waste content.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications shape compliance requirements for soap boxes distributed through European and American retail channels, with ECHA restricting certain chemical coatings and the FDA governing indirect food-contact claims for soap packaging. China's GB standards and NMPA cosmetic labeling rules affect export-oriented suppliers serving the domestic personal care market. Stakeholders must monitor evolving EPR fee structures and substrate-specific recycling targets to align capital allocation with regulatory cost trajectories.
Market Dynamics
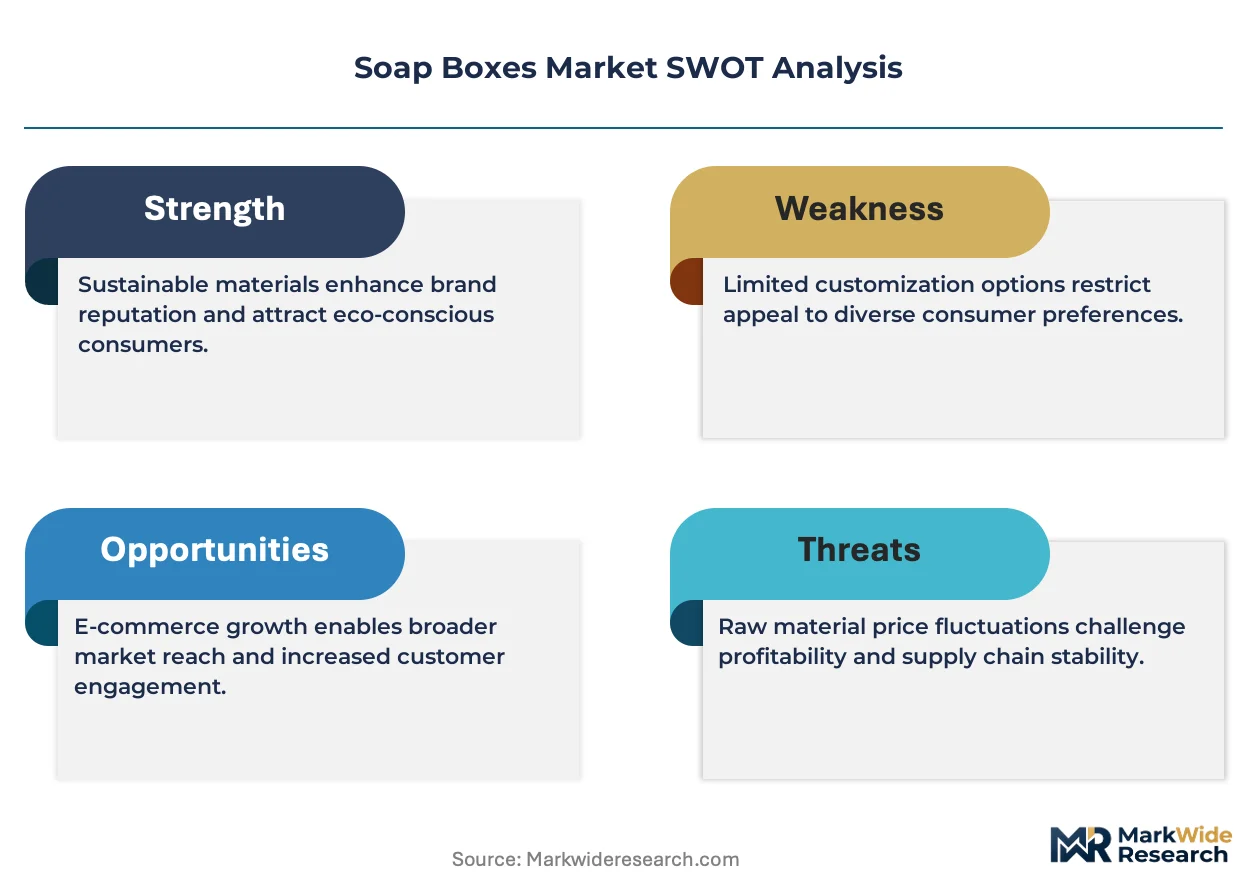
REACH compliance is expanding the cost-of-entry calculus for soap box suppliers targeting European personal care brands. The EU Packaging and Packaging Waste Regulation is compelling material shifts toward recycled content, while artisanal soap makers in North America are driving premium packaging demand.
Growth Catalysts
- EPR Legislation:Extended producer responsibility frameworks in Germany are mandating minimum recycled content thresholds for cosmetic packaging. This creates guaranteed demand pull for certified paperboard soap boxes.
- Artisanal Brand Expansion:Small-batch soap makers across the United States are adopting rigid gift boxes to differentiate at farmers markets and direct-to-consumer channels. Their preference for uncoated kraft finishes supports domestic paperboard mills.
- Moisture-Barrier Coatings:Advances in bio-based barrier technologies are eliminating the performance gap between conventional polyethylene-coated board and fully recyclable alternatives. Premium natural cosmetics brands are accelerating adoption.
Market Restraints
- Pulp Price Volatility:Northern bleached softwood kraft pulp contracts fluctuate with energy costs in Scandinavian supplier regions. Folding carton converters face margin compression when long-term brand contracts cannot pass through input spikes.
- Recycling Infrastructure Gaps:Mixed-fiber paperboard with polymer windows lacks sorted stream access in most North American municipalities. Contamination rates at materials recovery facilities limit circularity claims.
- Substitution by Naked Bars:Zero-waste retail formats in France and the Netherlands are eliminating packaging entirely for solid shampoo and soap. Unwrapped bar penetration in these markets constrains volume growth for box suppliers.
Strategic Opportunities
- India Premiumization:Ayurvedic and natural soap brands in Maharashtra and Karnataka are upgrading from flexible pouches to rigid boxes for gift sets. Domestic paperboard converters can capture this upgrade cycle before multinationals establish local folding carton capacity.
- Digital Print Integration:Hybrid web-fed presses combining flexo base units with inkjet personalization modules are enabling lot sizes below 5,000 units. Craft soap makers gain access to variable data printing for seasonal and limited-edition runs.
- EU Green Deal Alignment:The Packaging and Packaging Waste Regulation's 2030 recycled content targets are accelerating brand owner procurement of post-consumer waste paperboard. Suppliers with certified closed-loop supply chains command sourcing preference.
Industry Challenges
- Color Management Expertise:Water-based flexo inks on uncoated recycled substrates require press operators skilled in dot gain compensation and substrate-specific drying profiles. Talent scarcity in narrow-web folding carton print shops extends make-ready times.
- Legacy ERP Integration:Job shop management systems at mid-tier converters often lack API connectivity to brand owner specification portals. Manual data re-entry between customer PLM platforms and internal estimating modules introduces quoting delays.
- Coating Certification Timelines:FDA food-contact substance notifications for novel bio-barrier chemistries require 180-day review cycles. Product development pipelines compress as brand owners demand faster packaging refresh cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soap Boxes Market |
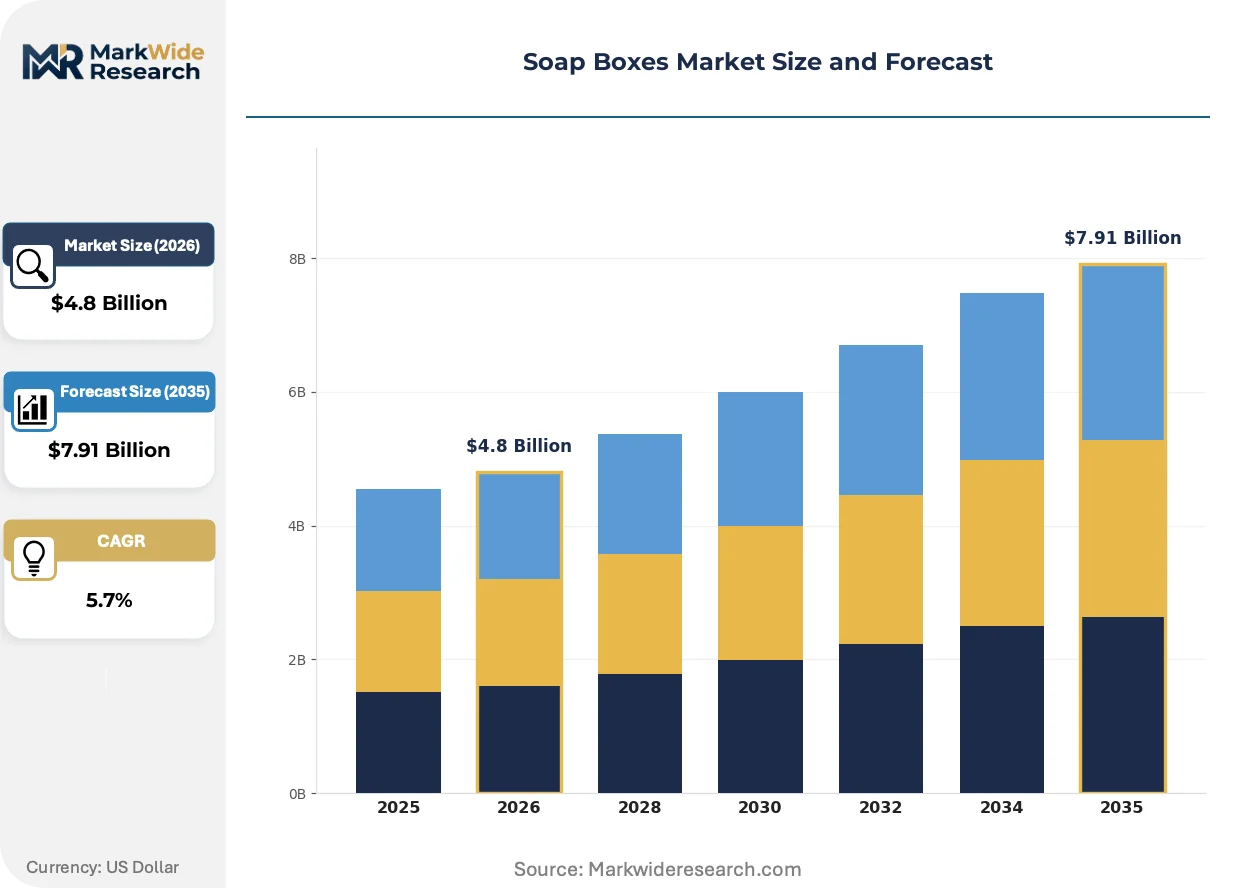
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Box Type: Folding Cartons, Rigid Boxes, Plastic Containers, Kraft Boxes Material: Paperboard, Plastic, Wood, Recycled Materials Closure Type: Sliding Lid, Tuck Flap, Snap Closure, Magnetic Closure Design Style: Minimalist, Vintage, Modern, Custom Prints |
| Companies Covered | WestRock, Mondi Group, DS Smith Plc, Smurfit Kappa Group, Stora Enso Oyj, International Paper, Packaging Corporation of America, Huhtamaki, Prefine Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soap Boxes Market Evolving Landscape
Digital production technologies and regulatory material mandates are converging to reshape how soap boxes are specified, printed, and recovered. Three developments are compressing traditional supply chain hierarchies.
Web-to-print configuration tools are decentralizing prepress authority from large converters to brand owners and their design agencies. Cloud-based 3D mockup platforms allow artisanal soap makers in Portland and Austin to approve structural prototypes without physical sampling. This capability is compressing the traditional converter-brand creative relationship and enabling micro-lot experimentation at previously uneconomical scales.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical grease barriers from paperboard specifications sold into EU cosmetic channels. ECHA's 2023 PFAS restriction proposal has forced coating suppliers to accelerate bio-based wax and clay alternatives. Premium natural soap brands in Germany and France are responding by specifying unbleached substrates with mineral oil-free barriers, accepting modest performance trade-offs for compliance security.
Direct-to-consumer subscription formats are fragmenting order profiles that folding carton equipment was optimized to aggregate. Soap brands shipping monthly boxes to individual households require pack counts of six or twelve rather than retail case packs of 48 or 96. This pattern is most visible in United States coastal metro markets where CPG startups bypass traditional retail distribution entirely, forcing converters to reconfigure die layouts and auto-packing line changeover protocols.
Soap Boxes Market Segmentation
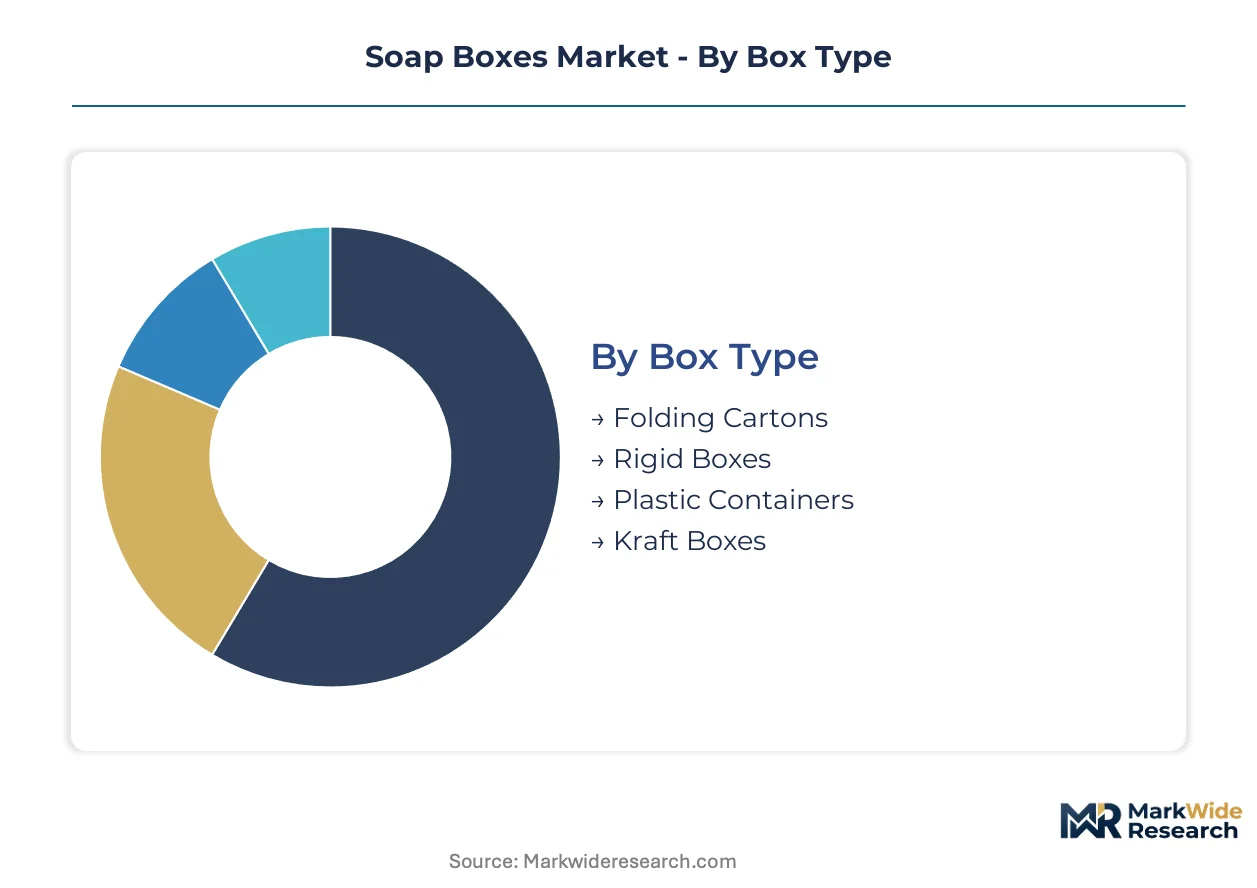
Soap box procurement patterns diverge sharply across price tiers and distribution channels. Brand owners select formats based on line speed compatibility, unboxing experience requirements, and regulatory compliance obligations in target markets.
Box Type:
Premium artisanal brands prioritize structural integrity and shelf differentiation over unit cost, while mass-market producers optimize for auto-packing throughput.
- Folding Cartons:Engineered from 12-24 point paperboard with pre-scored creases for high-speed erecting equipment. Demand concentrates among US mass-market soap producers running continuous auto-packing lines where changeover efficiency governs supplier selection. REACH-compliant barrier coatings now dominate European specifications.
- Rigid Boxes:Constructed from 2-3mm paperboard wrapped over rigid chipboard cores, delivering crush resistance for gift and luxury segments. Maharashtra's Ayurvedic brands in India are upgrading to rigid formats for festival gift sets, displacing flexible pouch alternatives.
- Plastic Containers:Injection-molded polypropylene with snap-fit lids, serving travel-size and wet-bar soap formats where moisture exclusion is critical.
- Kraft Boxes:Unbleached uncoated paperboard favored by zero-waste cosmetic brands seeking compostable end-of-life pathways.
Folding cartons lead volumes today; rigid boxes are gaining share fastest.
Material:
Raw material selection now tracks regulatory mandates as closely as performance specifications.
- Paperboard:Bleached kraft or SBS grades with clay-coated print surfaces. German sustainable cosmetics brands source FSC-certified paperboard soap boxes to meet EPR recycled content thresholds.
- Plastic:Food-grade polypropylene and PET with vapor-deposited barrier layers. FDA food-contact substance notifications govern US specifications for soap packaging with indirect food-contact claims.
- Wood:Paulownia and bamboo veneers for ultra-premium positioning in Japanese gift markets.
- Recycled Materials:Post-consumer waste paperboard with specified minimum content levels. EU Packaging and Packaging Waste Regulation targets are accelerating procurement of certified closed-loop supply chains.
Paperboard leads volumes today; recycled materials are expanding most quickly.
Closure Type:
Opening mechanics shape both production line integration and consumer experience expectations.
- Sliding Lid:Two-piece construction with drawer-style engagement, common in Japanese premium soap gift sets where ritual unboxing commands price premiums.
- Tuck Flap:Integrated dust flaps with friction-fit closure, compatible with standard folding carton glue lines at lowest unit cost.
- Snap Closure:Injection-molded plastic tabs engaging die-cut apertures, enabling resealability for multi-bar retail packs.
- Magnetic Closure:Concealed ferrite magnets in rigid box constructions, specified by US direct-to-consumer subscription brands for unboxing shareability.
Tuck flap leads volumes today; magnetic closure is climbing the fastest.
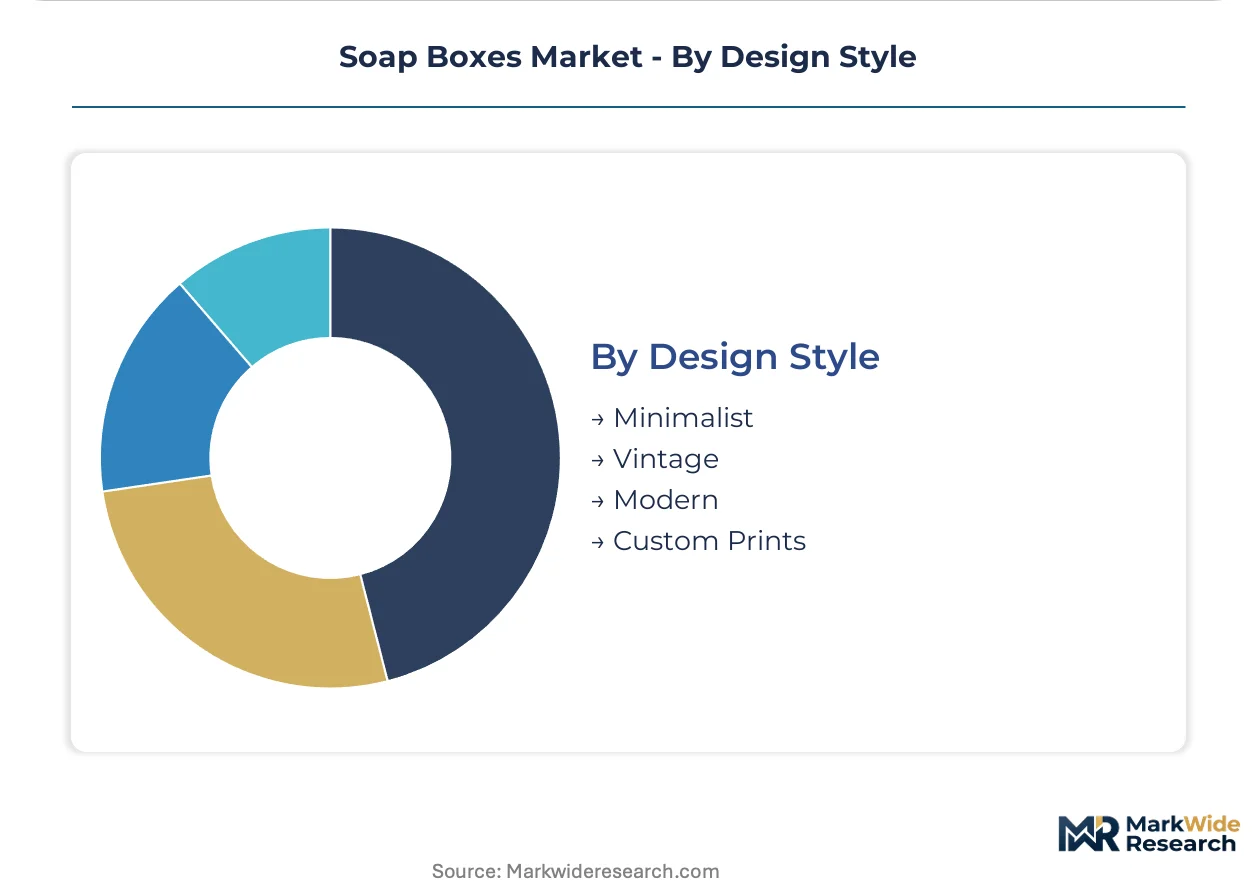
Design Style:
Visual identity execution now splits between template-driven efficiency and variable-data personalization.
- Minimalist:Uncoated substrates with single-color flexo printing and generous negative space. Portland and Austin craft soap makers specify this aesthetic for farmers market differentiation.
- Vintage:Ornate typography with gold foil stamping and embossing, serving heritage-positioned European apothecary brands.
- Modern:Bold geometric patterns with UV spot coating on glossy clay-coated board, targeting mass-market retail shelf impact.
- Custom Prints:Digital inkjet personalization enabling lot sizes below 5,000 units with variable data for seasonal and limited-edition runs.
Modern leads volumes today; custom prints are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern paperboard packaging industry traces its commercial roots to 19th-century Germany, where mechanized folding carton production first achieved industrial scale. This heritage shapes today's geographic concentration of soap box manufacturing expertise.
Germany
Artisanal cosmetics brands in Hamburg and Cologne drive premium rigid box demand for gift-format soaps. ECHA's REACH restrictions on PFAS coatings compel converters to source mineral oil-free barrier alternatives. The Baden-Württemberg cluster hosts specialized folding carton operations supplying FSC-certified paperboard to sustainable beauty brands.
United States
Direct-to-consumer subscription soap brands in Portland and Austin fragment order profiles with small-lot personalization requirements. FDA food-contact substance notifications govern indirect food-contact claims for soap packaging. Wisconsin and Ohio containerboard mills serve mass-market producers with high-volume folding carton programs optimized for auto-packing throughput.
India
Ayurvedic and natural soap manufacturers in Maharashtra and Karnataka upgrade from flexible pouches to rigid gift boxes for festival sets. BIS certification requirements for paperboard packaging create compliance thresholds for imported substrates. Mumbai-Pune corridor converters capture this upgrade cycle before multinational folding carton capacity localizes.
China
Export-oriented personal care suppliers in Guangdong and Zhejiang adapt soap box specifications to NMPA cosmetic labeling rules for domestic market entry. GB standards for packaging materials shape substrate selection for brands targeting Chinese retail channels. Yangtze River Delta converters integrate digital print modules to serve micro-lot orders from cross-border e-commerce soap brands.
France
Zero-waste retail formats in Paris and Marseille eliminate packaging entirely for solid shampoo and soap, constraining volume growth for box suppliers. ANSM oversight of cosmetic product claims extends to packaging material safety declarations. Provence-based natural soap cooperatives specify compostable kraft boxes for farmers market distribution.
Soap Boxes Market Competitive Landscape
The competitive structure tilts toward integrated paperboard producers with captive pulp supply and converter networks. Market concentration reflects capital intensity in containerboard production and the scale advantages of high-speed folding carton equipment. Two strategic archetypes dominate: North American containerboard giants leveraging fiber access for mass-market volume, and European specialty converters competing on circular design credentials. Dominant competitive moves include backward integration into recycled pulp processing and geographic expansion through converter acquisitions in high-growth Asian markets.
Among North American integrated producers, WestRock and Packaging Corporation of America exemplify the scale-driven archetype with extensive containerboard footprints serving high-volume soap brands. Mondi Group anchors the European specialist position through integrated kraft paper operations feeding directly into recycled-content specifications. DS Smith Plc occupies a distinct competitive position competing on closed-loop recycling systems that align with retailer sustainability mandates in EU cosmetic channels.
| Leading Market Players |
|---|
| WestRock |
| Mondi Group |
| DS Smith Plc |
| Smurfit Kappa Group |
| Stora Enso Oyj |
| International Paper |
| Packaging Corporation of America |
| Huhtamaki |
| Prefine Packaging |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters across Germany and Wisconsin anchor supply discipline through generational capital allocation patterns that resist cyclical price-cutting. Their patient reinvestment in FSC-certified paperboard coating lines sustains premium-tier pricing power even when mass-market folding carton contracts face pulp-cost pass-through disputes.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs soap box procurement, with certification grade and volume scale as primary differentiation drivers. Premium rigid boxes for German artisanal brands command substantial markups over mass-market folding cartons serving US grocery chains. Cost compression in standard-tier folding cartons is intensifying because long-term brand contracts cannot absorb Northern bleached softwood kraft pulp volatility. Mass-market soap producers exhibit highest price sensitivity, while direct-to-consumer subscription brands prioritize unboxing experience over unit cost.
Supply Chain Analysis
FSC and REACH certification gating restricts qualified supplier pools to converters with verified closed-loop pulp sourcing and mineral oil-free barrier documentation. Raw material flows concentrate in Germany, the United States, and India, with kraft paperboard, bio-based barrier coatings, and rigid chipboard cores as critical inputs. Single-source vulnerability persists for Scandinavian pulp supply exposed to energy cost shocks. Distribution runs through converter-direct relationships with brand owner specification portals, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in soap boxes rests on bio-barrier coating cost curves flattening faster than polyethylene alternatives, enabling premium-tier positioning without performance trade-offs.
For Market Incumbents: Cement supply security through backward integration into recycled pulp processing in Baden-Württemberg or Wisconsin mill clusters. Lock in FSC chain-of-custody certification ahead of EU Packaging and Packaging Waste Regulation threshold escalations to defend against Asian converter entrants with unverified sustainability claims. For New Entrants and Emerging Players: Begin with digital print-enabled micro-lot production for US coastal subscription soap brands, where order fragmentation has outpaced incumbent auto-packing line configurations. Target Maharashtra's Ayurvedic gift box upgrade cycle before multinational folding carton capacity localizes, leveraging domestic BIS certification familiarity as a go-to-market wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier European converters with stranded PFAS coating assets awaiting bio-barrier retooling. Long-term viability favors suppliers with certified closed-loop supply chains aligned to retailer sustainability mandates. Watch EPR fee structure announcements in Germany and France as inflection indicators for recycled content procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Pulp | Captive supply of post-consumer waste paperboard secures EPR compliance in German cosmetic channels. |
| Bio-Barrier Coating Certification | FDA food-contact substance clearance for novel chemistries unlocks premium natural soap brand specifications. |
| Digital Print Module Installation | Hybrid web-fed presses with inkjet personalization serve craft soap makers' sub-5,000 unit lot requirements. |
| Geographic Expansion in India | Mumbai-Pune corridor capacity captures Ayurvedic brand upgrade from flexible pouches to rigid gift boxes. |
| Closed-Loop Recycling System Development | DS Smith-style circular design credentials align with EU retailer sustainability mandates and sourcing preference. |
Research Methodology
Bottom-up folding carton and rigid box demand modeling reconciled against top-down containerboard capacity tracking forms the analytical core of this study. Primary interviews with procurement directors at sustainable cosmetics brands, folding carton plant managers, paperboard mill sales executives, and regulatory compliance officers at ECHA and FDA were validated against secondary sources including FSC chain-of-custody databases, EU Packaging and Packaging Waste Regulation implementation documents, and SEC filings from integrated packaging producers.
Input-output matrices map pulp cost trajectories, coating technology adoption curves, and brand owner specification shifts across the projection horizon. Segmentation dimensions include box type, material grade, closure mechanism, and design style, with regional regulatory cluster as an industry-specific overlay. CAGRs derive from slope consensus across bottom-up brand procurement forecasts and top-down converter capacity expansion plans, with Northern bleached softwood kraft pulp contract pricing and EPR fee structure evolution as key forecast inputs.
Caveats apply where REACH restriction scope expansion or zero-waste retail format penetration could materially shift the outlook. Forecasts reflect assumptions about bio-barrier coating performance parity achievement and recycling infrastructure development timelines. A model refresh is warranted upon material change in EU Packaging and Packaging Waste Regulation recycled content enforcement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Pick and Place Carton Packers Market
Cartons
Brick Liquid Carton Market
Cartons
Carton Display Market
Cartons
Litho Laminated Cartons Market
Cartons
Beverage Cartoners Market
Cartons
Child-Resistant Carton Box Market
Cartons
Global Printed Cartons Market
Cartons
Global Hand Carton Sealers Market
Cartons
Cupcake Box Market
Cartons
Folding Cartons Market
Cartons
MET-PET Cartons Market
Cartons
Wax Boxes Market
Cartons
Mailers Market
Cartons
Digital Printed Cartons Market
Cartons
Europe Corrugated Box Market
Cartons
North America Corrugated Boxes Market