
 Australia Metal Packaging Market | 2026-2036
Australia Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Metal Packaging Market Outlook
The Australian Packaging Covenant Organisation's 2025 recycled content mandate is hardening procurement standards across the supply chain. Orora Limited leverages its integrated recycling infrastructure to secure post-consumer aluminium feedstock at scale. Visy Industries Holdings Pty Ltd anchors its competitive position through captive paper and metal recycling operations spanning multiple states. Crown Holdings, Inc. specializes in lightweighting technologies for beverage cans, differentiating its product line for Australian brewers and soft drink bottlers.
Australia metal packaging encompasses rigid and semi-rigid containers fabricated from aluminium alloys, tinplate, and steel substrates, typically ranging from 0.15 mm to 0.40 mm in thickness, engineered to provide barrier protection against oxygen, light, and moisture for perishable goods. Aluminium cans command the largest product type position due to entrenched beverage industry demand and infinite recyclability without property degradation. Steel cans retain structural importance in food preservation applications where retort processing demands thermal resilience. Coating technology represents a critical innovation frontier, with epoxy-phenolic and polyester formulations enabling acidic food contact compliance while eliminating bisphenol A from interior linings.
TGA guidelines govern pharmaceutical metal packaging integrity, while the Australian Competition and Consumer Commission enforces country-of-origin labelling rules that affect metal container marking requirements. The National Packaging Targets administered by the Australian Packaging Covenant Organisation mandate 70% recycling recovery rates, directly shaping converter investment in closed-loop aluminium systems. Stakeholders must monitor the interplay between state-level container deposit schemes and federal recycled content standards to anticipate margin compression or opportunity windows.
Market Dynamics
Australian Packaging Covenant Organisation mandates are compressing converter margins while forcing capital redeployment toward closed-loop aluminium recovery systems and bisphenol A-free coating infrastructure.
Growth Catalysts
- Victoria-New South Wales manufacturing corridor:Beverage and food processing clusters concentrate procurement volumes, creating dense supplier networks that reduce logistics costs for can makers.
- TGA pharmaceutical integrity standards:Metal blister packs and tubes gain share as drug stability requirements harden against moisture and oxygen intrusion.
- Infinite aluminium recyclability:Container deposit schemes in Queensland, South Australia, and Western Australia generate predictable post-consumer feedstock streams for remelt operations.
Market Restraints
- Primary aluminium ingot volatility:London Metal Exchange price swings transmit directly to can sheet costs, compressing converter margins during supply shocks.
- Tinplate supply concentration:Three integrated steelmakers control food-grade electrolytic tinning capacity across Oceania, creating single-source vulnerability for vegetable and processed meat packers.
- Epoxy-phenolic coating substitution limits:Acidic tomato and citrus applications lack viable liner alternatives that match thermal resilience and migration compliance simultaneously.
Strategic Opportunities
- Tasmanian craft beverage expansion:Cider and whisky distillers outside mainland distribution networks seek small-batch can formats with premium finishing.
- 70% National Packaging Target compliance:Brands facing 2025 recycled content thresholds will pay premiums for verified post-consumer aluminium provenance.
- Digital printing convergence with lightweighting:Direct-to-can decoration eliminates paper labels, reducing material mass and enabling SKU proliferation for seasonal limited runs.
Industry Challenges
- Coating chemist scarcity:Formulation expertise for BPA-NI (non-intent) interior linings resides with a handful of retired specialists, slowing product qualification timelines.
- Retort equipment reconfiguration:Steel can thermal processing lines require capital-intensive pressure vessel upgrades to handle thinner-gauge substrates without deformation.
- Container deposit scheme interoperability:State-level barcode and sorting standard mismatches fragment reverse logistics, raising collection costs for national brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Metal Packaging Market |
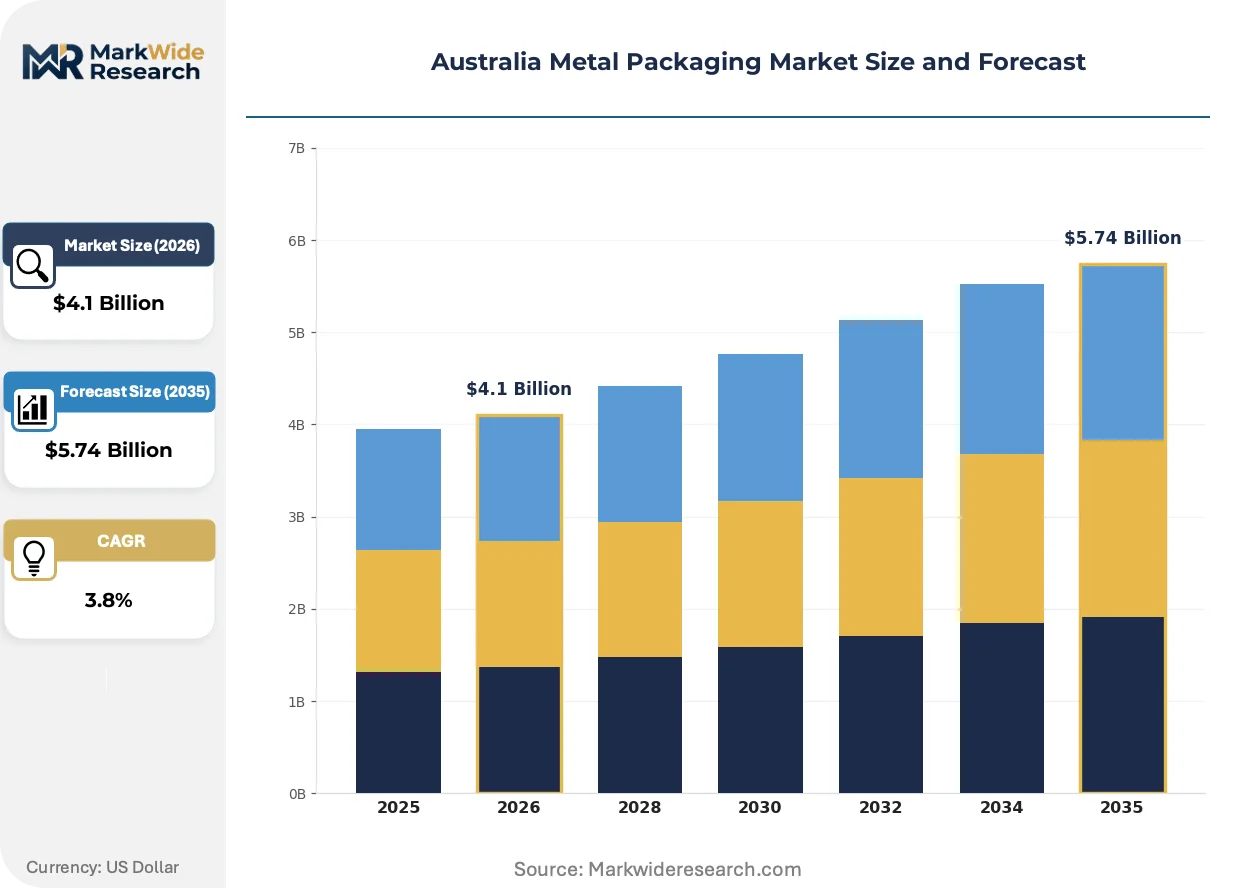
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminium Cans, Steel Cans, Tinplate Containers, Metal Foils End Use Industry: Beverage, Food, Pharmaceuticals, Personal Care Packaging Type: Rigid Packaging, Flexible Packaging, Cans, Foil Pouches Technology: Recycling Technology, Coating Technology, Printing Technology, Forming Technology |
| Companies Covered | Crown Holdings, Inc., Pact Group Holdings Ltd, Orora Limited, Perennial Packaging Group Pty Ltd, Silgan Holdings Inc., Visy Industries Holdings Pty Ltd, Amcor plc, NCI Packaging, Ball Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Metal Packaging Market Strategic Shifts
Digital manufacturing and regulatory chemistry mandates are redrawing technical specifications across aluminium and steel substrate lines, with sustainability verification becoming a discrete product attribute rather than a baseline assumption.
Two-piece drawn-and-ironed aluminium can technology is modularizing production economics for Australian craft brewers and ready-to-drink bottlers. Mid-scale regional players now access 50-100 million unit annual capacities without committing to 300+ million unit legacy line minimums. This fragmentation is compressing minimum efficient scale thresholds and enabling geographic dispersal of canning operations beyond Melbourne and Sydney corridors.
Australian Packaging Covenant Organisation recycled content mandates are forcing coating and substrate suppliers to document mass balance through ISO 14021-compliant chain-of-custody systems. Converters must retrofit metallurgical accounting infrastructure to verify post-consumer aluminium percentages in each production batch. Beverage brands with 2025 compliance deadlines are accelerating supplier audits and shifting procurement toward vertically integrated recyclers with in-house spectroscopic verification.
Single-serve format preference among Australian consumers is displacing multi-pack glass and PET alternatives in convenience and petrol channels. Craft beer, hard seltzer, and functional beverage entrants are specifying slimline and sleek can geometries to signal premium positioning. This SKU proliferation is forcing converters to absorb shorter run lengths and more frequent die changeovers, compressing line utilization rates at plants serving fragmented brand portfolios.
Australia Metal Packaging Market Segmentation
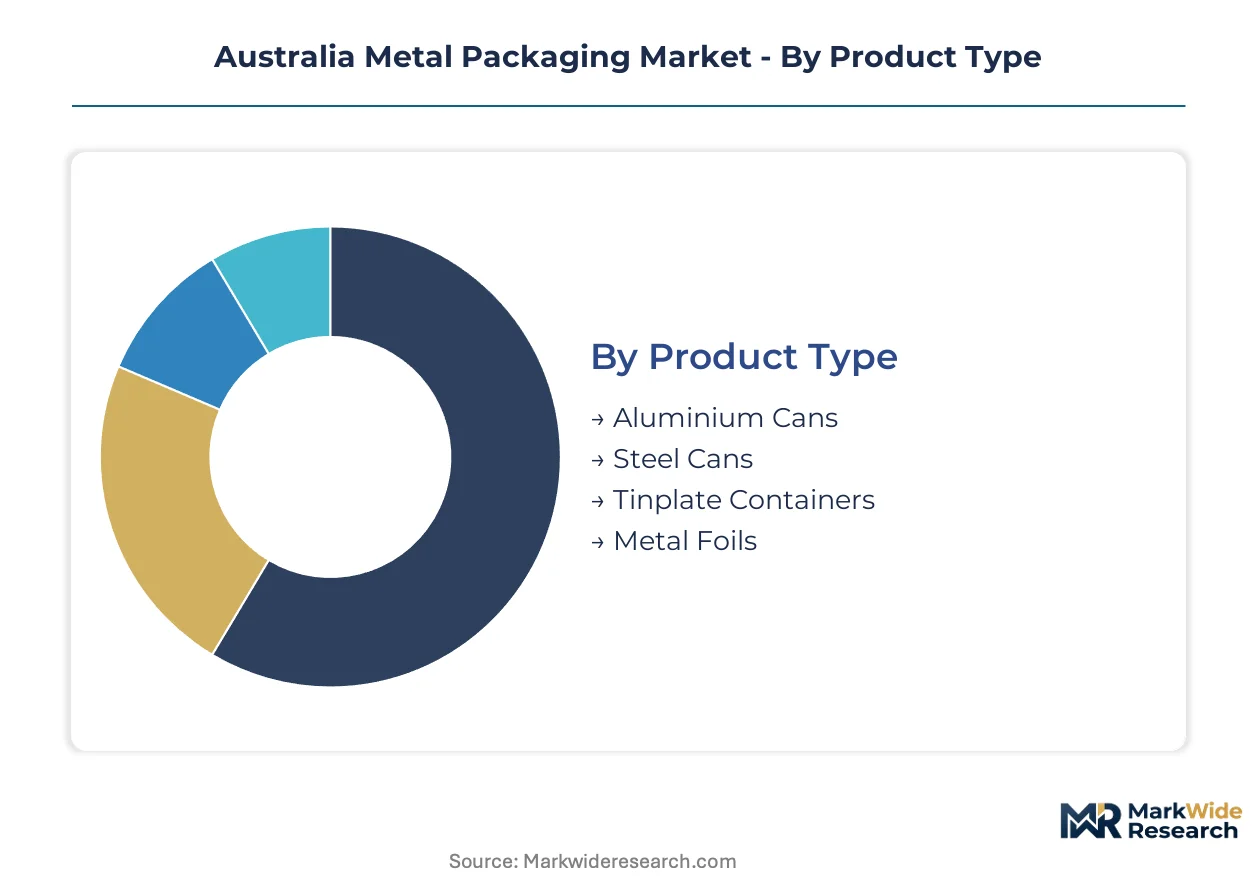
Metal packaging procurement decisions in Australia hinge on recyclability credentials, thermal processing requirements, and container deposit scheme compatibility. Each segmentation dimension reveals distinct margin structures and capital intensity profiles that shape converter strategic positioning.
Product Type:
Beverage brand sustainability commitments and food processor retort requirements drive substrate selection more than unit cost differentials.
- Aluminium Cans:Fabricated from 3104-H19 alloy with wall thickness down to 0.097 mm through drawn-and-ironed two-piece construction. Victorian and New South Wales beverage manufacturing corridors absorb the majority of domestic can sheet output, pressured by Australian Packaging Covenant Organisation recycled content verification demands.
- Steel Cans:Cold-rolled tinplate with electrolytic coating weights of 2.8/2.8 g/m² provides thermal resilience for retort sterilization cycles exceeding 121°C. Processed meat and vegetable packers concentrate procurement in Adelaide and regional Queensland where tinplate supply contracts with BlueScope Steel anchor procurement planning.
- Tinplate Containers:Three-piece welded bodies with double-seamed ends serve specialty food and industrial chemical applications requiring hermetic integrity.
- Metal Foils:Aluminium foil laminates from 6 to 50 micron gauges provide barrier layers for pharmaceutical blister packs and confectionery wraps.
Volume sits with aluminium cans; growth tilts toward metal foils in pharmaceutical barrier applications.
End Use Industry:
Regulatory compliance intensity and shelf stability requirements create divergent technical specifications across buyer categories.
- Beverage:Carbonated soft drink, craft beer, and ready-to-drink alcohol segments specify lightweight aluminium with direct-to-can digital decoration. Container deposit scheme interoperability across Queensland, South Australia, and Western Australia shapes reverse logistics design.
- Food:Retort processing demands steel can substrates capable of withstanding 40-minute sterilization cycles without seam deformation. Acidic tomato and citrus applications require epoxy-phenolic interior coatings compliant with TGA migration limits.
- Pharmaceuticals:TGA guidelines govern metal blister pack integrity against moisture vapor transmission.
- Personal Care:Aerosol and tube formats specify tinplate or aluminium with compatibility for propellant and emulsion chemistries.
Procurement volume concentrates in beverage; food applications show steepest expansion trajectory from ready-meal format adoption.
Packaging Type:
Structural rigidity versus material efficiency trade-offs determine format selection across distribution channel requirements.
- Rigid Packaging:Two-piece aluminium cans and three-piece steel cans provide stack strength for palletized distribution. Beverage and processed food sectors dominate rigid format procurement through Melbourne and Sydney manufacturing clusters.
- Flexible Packaging:Foil laminates and semi-rigid retort pouches reduce material mass per unit of product protected. Pharmaceutical and confectionery sectors drive foil laminate demand with barrier specifications against oxygen and light intrusion.
- Cans:Cylindrical geometries optimize pallet cube efficiency and retail shelf space utilization.
- Foil Pouches:Stand-up and flat pouch configurations serve single-serve and sample-size personal care and pharmaceutical applications.
Rigid formats capture volume share; flexible configurations are expanding most quickly in pharmaceutical unit-dose applications.
Technology:
Capital deployment priorities reflect regulatory chemistry mandates and circular economy infrastructure gaps.
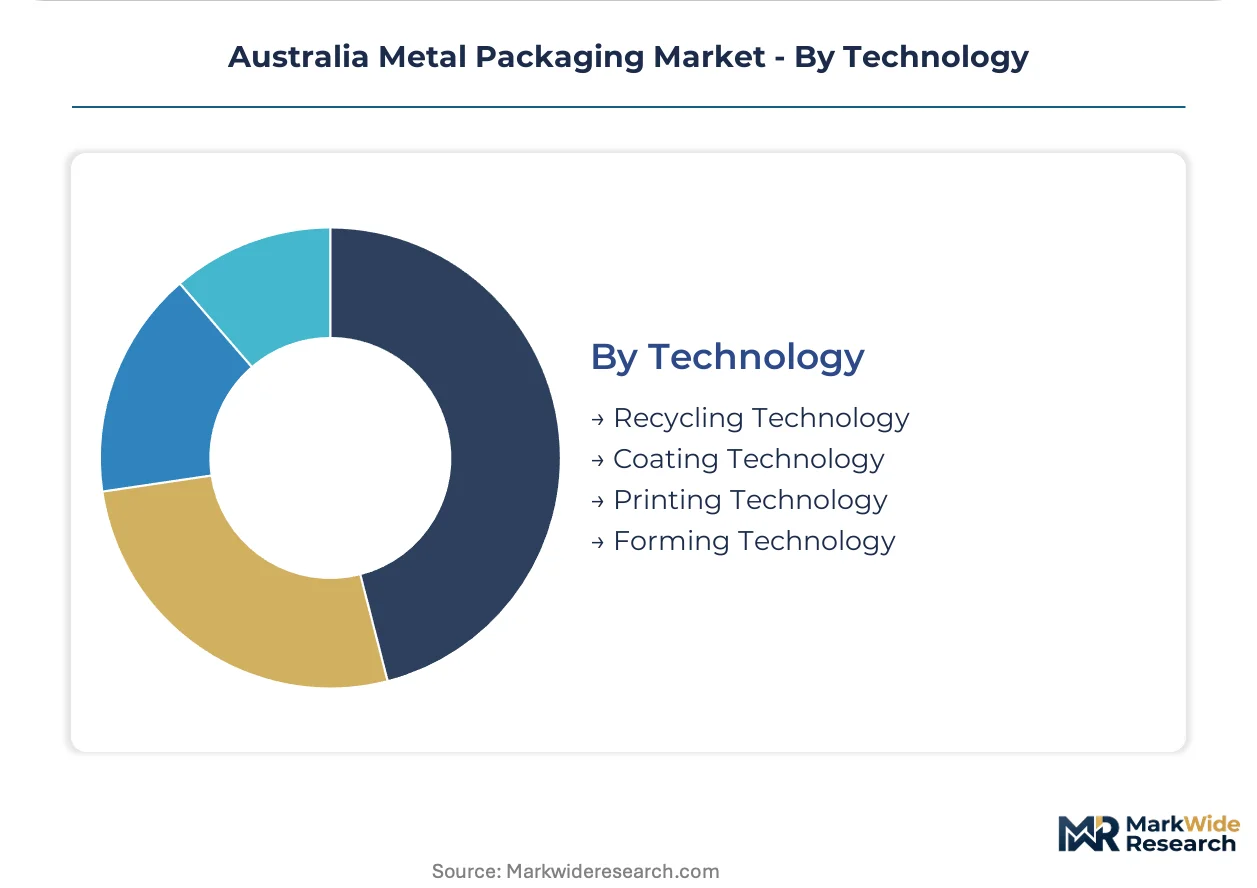
- Recycling Technology:Closed-loop aluminium remelt systems with spectroscopic sorting achieve post-consumer feedstock verification for Australian Packaging Covenant Organisation compliance. Orora Limited and Visy Industries operate captive recycling infrastructure across multiple states.
- Coating Technology:BPA-NI (non-intent) epoxy-phenolic and polyester formulations eliminate bisphenol A while maintaining acid food contact compliance. Coating chemist scarcity constrains qualification timelines for reformulated interior linings.
- Printing Technology:Direct-to-can digital decoration eliminates paper labels and enables short-run SKU proliferation for seasonal beverage releases.
- Forming Technology:Drawn-and-ironed can manufacturing and three-piece can welding lines represent distinct capital equipment categories with different scale economies.
Recycling technology commands capital allocation; coating technology represents the fastest-climbing investment priority as 2025 compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic can sheet production concentrates in Victoria and New South Wales, yet beverage brand procurement extends across all states as container deposit schemes mature. Regional demand patterns diverge sharply between established manufacturing corridors and emerging craft beverage clusters.
New South Wales
Sydney's beverage manufacturing belt drives aluminium can procurement volumes for multinational soft drink and beer brands. The state's container deposit scheme, administered by Return and Earn, generates post-consumer aluminium feedstock for closed-loop remelt operations. Western Sydney industrial precincts host converting facilities that supply both domestic brands and export-oriented food processors.
Victoria
Melbourne anchors Australia's densest metal packaging ecosystem, with drawn-and-ironed can lines serving craft brewers and ready-to-drink alcohol entrants. Australian Packaging Covenant Organisation compliance deadlines are compelling local converters to install spectroscopic verification systems for recycled content documentation. The city's food manufacturing corridor in the outer metropolitan ring sustains steel can demand for retort-processed vegetables and processed meats.
Queensland
Container deposit scheme infrastructure in South-East Queensland creates predictable aluminium recovery streams for remelt operations. Brisbane's logistics hub position enables efficient distribution of empty cans to emerging beverage producers in the Gold Coast and Sunshine Coast hinterlands. State-level procurement for tropical fruit processors maintains steady tinplate demand for acidic food applications.
South Australia
The longest-running container deposit scheme in Australia, established decades before other states, delivers the nation's most mature reverse logistics network for aluminium recovery. Adelaide's smaller-scale beverage manufacturing base relies on imported can sheet from eastern states, with local converting limited to specialty food and wine applications. The state's regulatory leadership on packaging recovery has shaped national policy discourse.
Western Australia
Perth's geographic isolation from eastern manufacturing centers creates distinct procurement economics for beverage producers. The state container deposit scheme, implemented later than South Australia's model, is still optimizing collection density across vast distances. Local craft distillers and brewers in the Margaret River and Swan Valley regions are driving small-batch can format demand that eastern converters serve through consolidated freight arrangements.
Australia Metal Packaging Market Competitive Environment
The competitive structure tilts toward integrated recyclers with captive aluminium recovery infrastructure. Three strategic archetypes dominate: multinational can makers with lightweighting technology portfolios, Australasian packaging conglomerates with backward integration into paper and metal recycling, and regional specialists serving craft beverage niches. Dominant competitive moves center on spectroscopic verification system deployment for recycled content compliance and modular can line installations for sub-100 million unit annual capacities.
Within the integrated recycler archetype, Orora Limited and Visy Industries Holdings Pty Ltd anchor competitive positioning through captive recycling infrastructure spanning multiple states. Crown Holdings, Inc. occupies a distinct position as a multinational specialist in drawn-and-ironed beverage can technology. These three exemplify the structural divide between domestic vertically integrated players and technology-focused international operators.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Pact Group Holdings Ltd |
| Orora Limited |
| Perennial Packaging Group Pty Ltd |
| Silgan Holdings Inc. |
| Visy Industries Holdings Pty Ltd |
| Amcor plc |
| NCI Packaging |
| Ball Corporation |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange aluminium ingot pricing cascades through Australian can sheet procurement, stratifying converter margins across beverage-grade, food-grade, and specialty coating tiers as brands negotiate recycled content premiums.
Pricing Analysis
Throughput-linked contracts anchor converter pricing to annual can production volumes, with beverage brands paying premiums for verified post-consumer aluminium provenance. Price differentiation separates premium certified-recycled grades from standard primary-aluminium tiers, while food processors absorb higher tinplate costs for retort-compatible steel. Cost compression in standard beverage grades is intensifying as container deposit scheme interoperability demands fragment reverse logistics economics. Craft brewers exhibit highest price sensitivity due to small-batch volume scale, whereas multinational soft drink bottlers leverage long-term offtake agreements to lock in feedstock costs.
Supply Chain Analysis
Dual-sourcing requirements from BlueScope Steel and imported Asian tinplate force food canners to maintain qualification across multiple electrolytic coating suppliers. Raw material dependencies rest on Australian bauxite refining, imported can sheet coil, and epoxy-phenolic resin formulations from specialty chemical producers. Single-source vulnerability concentrates in food-grade tinplate capacity, where three integrated steelmakers control Oceania supply. Distribution runs through Melbourne and Sydney converting clusters, with consolidated freight arrangements serving Perth-isolated Western Australian beverage producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive aluminium recovery infrastructure to secure post-consumer feedstock at scale ahead of Australian Packaging Covenant Organisation compliance deadlines.
For Market Incumbents: Hedge against primary aluminium volatility by locking long-term scrap supply contracts with container deposit scheme operators. Invest in spectroscopic verification systems to document mass balance for brand audits. Defend share against modular can line entrants by absorbing shorter run lengths through digital printing convergence. For New Entrants and Emerging Players: Australian Packaging Covenant Organisation mandates in Australia open a window for regional craft beverage specialists offering verified closed-loop aluminium provenance. Target Tasmanian cider and whisky distillers seeking premium small-batch formats with direct-to-can decoration. Enter through coating technology partnerships that bypass scarce formulation expertise bottlenecks. For Investors and Strategic Acquirers: The window for entry favors integrated recyclers with captive remelt infrastructure and multi-state collection network density. Long-term viability hinges on spectroscopic verification capability as a compliance moat. Watch for state-level container deposit scheme harmonisation as the inflection signal for national brand procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | Captive post-consumer aluminium feedstock secures Australian Packaging Covenant Organisation compliance premiums from beverage brands. |
| BPA-NI Coating Qualification Investment | Epoxy-phenolic formulation expertise addresses chemist scarcity and unlocks acidic food processor contracts. |
| Modular Can Line Deployment | Mid-scale regional capacity serves craft beverage fragmentation beyond Melbourne-Sydney manufacturing corridors. |
| Digital Printing Convergence | Direct-to-can decoration eliminates label mass and enables SKU proliferation for seasonal limited runs. |
| Container Deposit Scheme Interoperability | Standardised barcode and sorting systems reduce reverse logistics costs for national brand owners. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across converter operations managers, beverage procurement leads, coating formulation specialists, and steel mill account executives. Australian Bureau of Statistics trade data, Australian Packaging Covenant Organisation progress reports, BlueScope Steel sustainability disclosures, and TGA pharmaceutical packaging guidelines supplied quantitative benchmarks. Bottom-up can sheet consumption estimates by state and end-use category were cross-validated against top-down packaging value chain assessments.
Granularity-level modeling deployed product type, end-use industry, and technology dimensions at the state level, with recycled content verification status as an overlay variable. CAGRs were derived from trend extrapolation of aluminium can shipment volumes and steel can retort processing demand, moderated by container deposit scheme expansion timelines and coating substitution feasibility curves across the projection horizon. London Metal Exchange price scenarios and tinplate supply contract structures informed cost-side sensitivity analysis.
The model assumes a particular technology adoption path; alternative pathways for BPA-NI coating qualification would alter the outlook if migration compliance timelines accelerate or epoxy-phenolic substitutes fail thermal resilience testing. Deviation in state-level container deposit scheme harmonisation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
Pressurized Metal Containers Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Metal Pails Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Europe Metal Cans Market
Metal Packaging
Honeycomb Aluminum Foil Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Saudi Arabia Metal Packaging Market