
 Bi-Metal Cans Market | 2026-2036
Bi-Metal Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Bi-Metal Cans Market Outlook
Aluminum is rebalancing bi-metal can economics as brewers and soft-drink bottlers seek lighter, more recyclable primary packaging. Ball Corporation leverages its North American smelter partnerships to sustain captive aluminum supply. Crown Holdings anchors European beverage contracts through integrated steel-tinplate operations. Silgan Holdings differentiates via specialty-coating technologies for acidic food applications.
Bi-metal cans are cylindrical containers fabricated from two dissimilar metals—typically steel bodies with aluminum ends—joined through seaming or welding, with wall gauges ranging from 0.15 mm to 0.25 mm depending on internal pressure requirements; they serve as hermetically sealed vessels for carbonated beverages, retorted foods, and aerosol products requiring corrosion resistance and structural integrity. Aluminum cans dominate beverage applications due to their superior recyclability and weight advantages, while steel cans retain cost leadership in shelf-stable food segments where oxygen barrier performance outweighs material density concerns. Composite cans and specialty cans occupy narrower niches—premium cosmetics and pharmaceutical inhalers—where customization commands margin premiums over commodity volumes.
The EPA regulates volatile organic compound emissions from can-coating operations in the United States, pushing manufacturers toward waterborne and UV-cured alternatives. ECHA's REACH framework restricts chromium-based passivation chemistries in European tinplate, compelling suppliers to certify alternative surface treatments. India's BIS mandates specific migration limits for heavy metals in food-contact metal packaging, shaping export compliance for regional producers. Stakeholders must monitor how diverging national recycling-deposit schemes and extended producer responsibility laws alter material-cost structures and regional sourcing strategies.
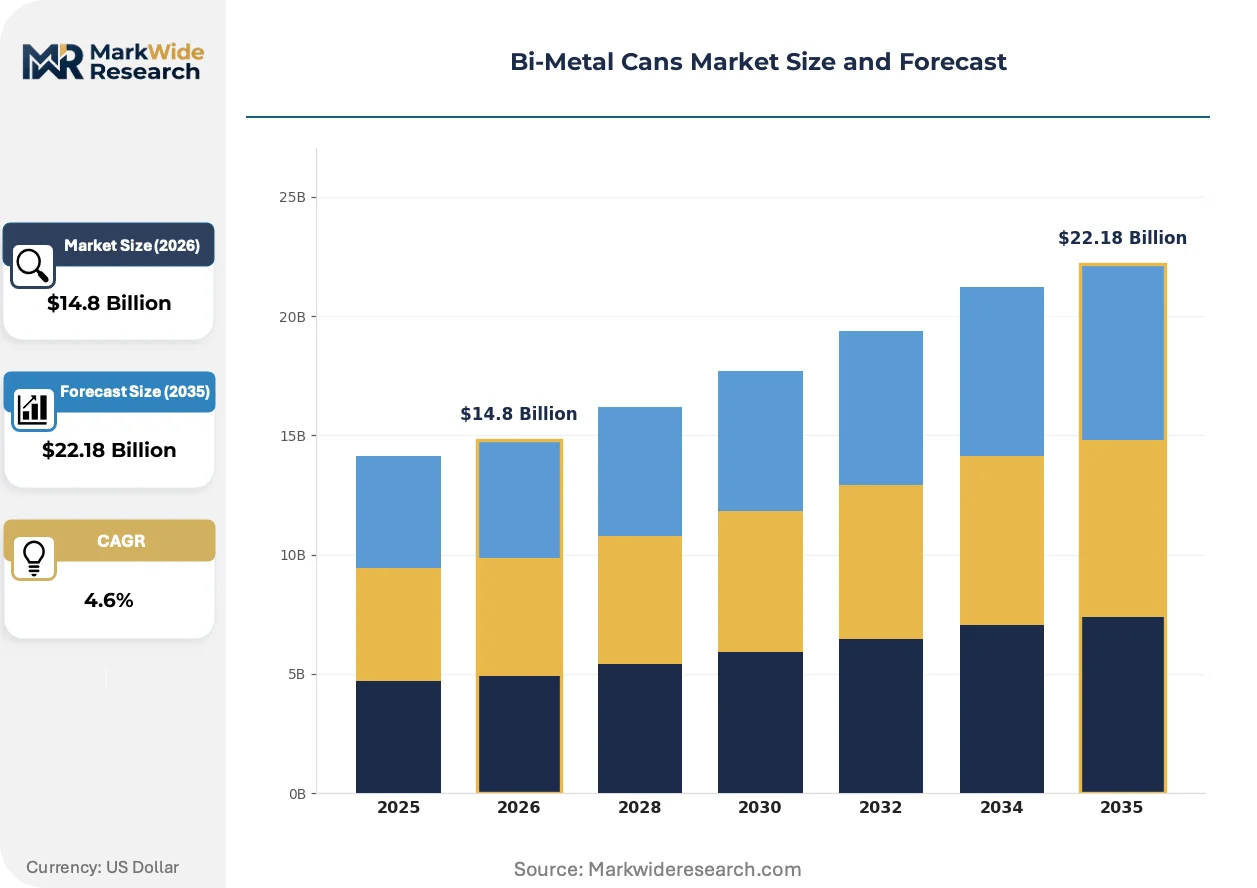
Market Dynamics
Aluminum-tinplate cost differentials are forcing beverage canners to reconfigure material specifications mid-contract, while Europe's F-Gas Regulation accelerates coating-line retrofits across continental manufacturing plants.
Growth Catalysts
- REACH-compliant surface treatments:ECHA's restriction of chromium-based passivation chemistries in tinplate is compelling suppliers to certify alternative coatings, opening demand for compliant bi-metal can stock.
- Beverage canning clusters:Brazil's southeastern manufacturing corridor is expanding aluminum-body lines to serve export volumes, concentrating demand for compatible aluminum end-stock.
- UV-cured coating adoption:EPA volatile organic compound limits are pushing United States can-coating operations toward waterborne and UV-cured alternatives, retrofitting existing steel-tinplate infrastructure.
Market Restraints
- Steel-tinplate cost volatility:Input price fluctuations for cold-rolled steel are compressing margin predictability for food-can producers locked into annual supply contracts.
- Aluminum smelter concentration:Captive aluminum supply chains concentrate among North American primary producers, creating bottleneck risk for beverage canners outside integrated networks.
- Retort compatibility limits:Aluminum's thermal performance ceiling restricts its penetration into shelf-stable food segments where steel-tinplate oxygen barriers remain mandatory.
Strategic Opportunities
- India food-contact compliance:BIS heavy-metal migration limits are reshaping export certification requirements, creating first-mover advantage for compliant regional producers.
- Aerosol specialty coatings:Convergence of epoxy-phenolic and polyester coating technologies is enabling corrosion-resistant bi-metal cans for cosmetic and pharmaceutical inhaler applications.
- Extended producer responsibility laws:EU packaging-waste directives are mandating recycled-content thresholds, advantaging aluminum-end cans with established closed-loop recycling infrastructure.
Industry Challenges
- Seaming technician shortage:Precision double-seaming skills for aluminum-to-steel joints are aging out of the workforce faster than apprenticeship programs can replenish.
- Coating-line capex cycles:Waterborne system conversions require eighteen-to-twenty-four-month installation timelines, stranding capital during regulatory transition windows.
- Multi-jurisdiction certification complexity:Simultaneous FDA, EFSA, and BIS food-contact approvals are extending product launch timelines for global can suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bi-Metal Cans Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Composite Cans, Specialty Cans End User: Beverage Industry, Food Industry, Personal Care, Pharmaceutical Application: Soft Drinks, Alcoholic Beverages, Packaged Foods, Household Products Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Ardagh Group, Ball Corporation, Crown Holdings, Tata Group, NCI Packaging, Kian Joo Can Factory Berhad, The Tinplate Company of India Limited, Cerviflan Industrial e Comercial Ltd, Silgan Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bi-Metal Cans Market Strategic Shifts
Digital printing and smart-can technologies are compressing minimum order quantities while enabling traceability mandates, fundamentally altering how beverage brands manage seasonal packaging cycles and recall protocols.
Laser-etched QR codes and near-field communication tags embedded in aluminum can ends are decentralizing supply chain visibility. Craft brewers and regional soft-drink bottlers are adopting these identifiers for anti-counterfeiting and consumer engagement. The technology is decentralizing quality-control accountability from centralized labs to distributed retail scanning points.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in can-coating solvent recovery systems. This is forcing capital deployment into carbon adsorption and thermal oxidation alternatives. Aerosol and food-can segments with high solvent throughput are accelerating equipment replacement timelines ahead of statutory deadlines.
Beverage brand procurement teams are consolidating supplier panels and demanding recycled-content certificates with batch-level traceability. Direct-to-contractor relationships are displacing distributor-mediated aluminum stock purchases in North America and Western Europe. This pattern is most visible among multinational brewers operating under science-based emissions targets.
Bi-Metal Cans Market Segmentation
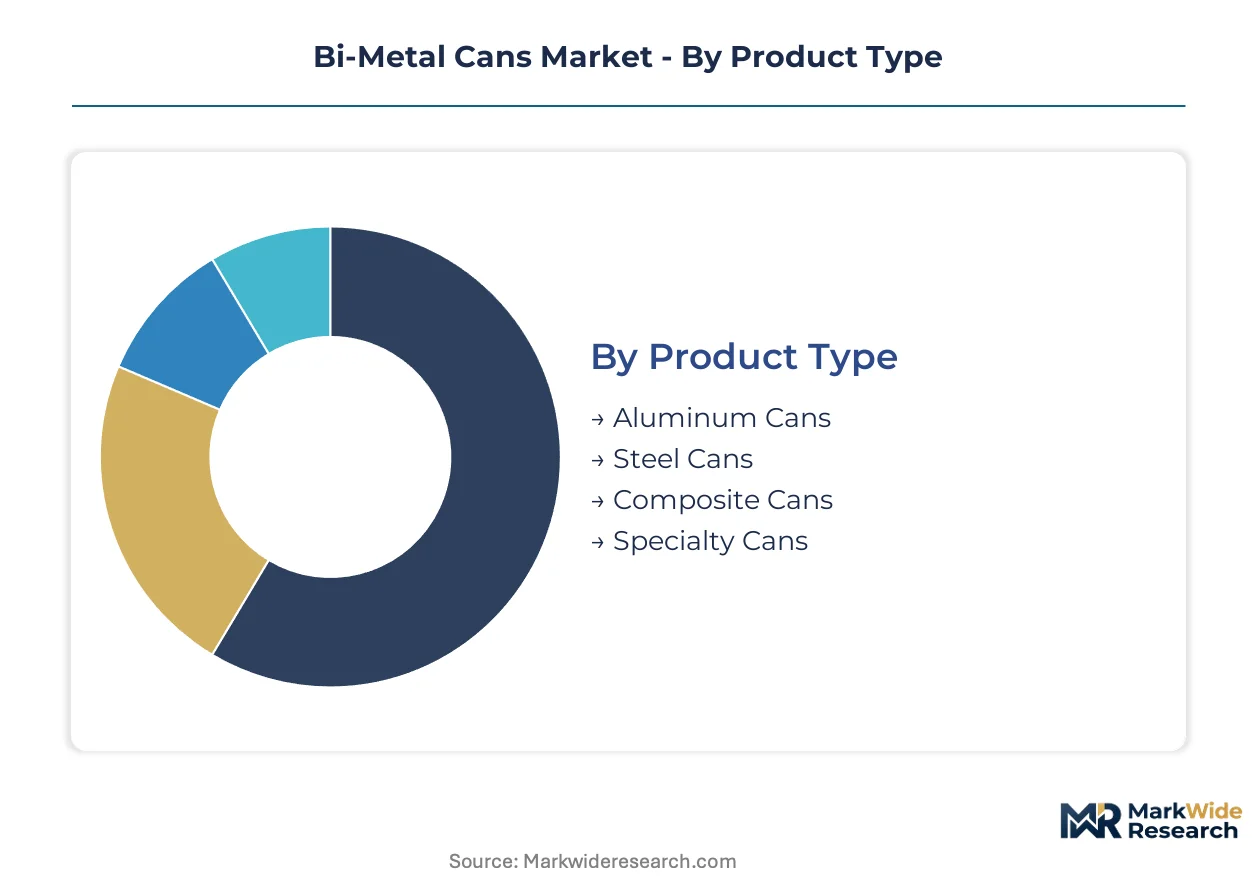
Bi-metal can segmentation reveals divergent material economics across beverage, food, and industrial end-uses. Product specifications vary sharply by internal pressure requirements, thermal processing needs, and recyclability mandates that reshape procurement priorities.
Product Type:
The customization-vs-standardization spectrum runs from commodity aluminum beverage bodies to highly engineered specialty cans with proprietary coating stacks.
- Aluminum Cans:Fabricated from 3104-H19 or 3004-H19 alloy with wall gauges of 0.097 mm to 0.115 mm for two-piece draw-and-wall-ironed construction. Demand concentrates in Brazil's southeastern canning corridor where Ball Corporation and Crown Holdings are expanding aluminum-body lines to serve carbonated soft drink export volumes under ECHA REACH-compliant surface treatments.
- Steel Cans:Cold-rolled tinplate or tin-free steel with electrolytic chromium coatings, typically 0.18 mm to 0.22 mm wall thickness for three-piece welded construction. Food canners in India's Maharashtra and Gujarat states favor steel-tinplate for retorted shelf-stable products requiring oxygen barrier performance beyond aluminum's thermal ceiling.
- Composite Cans:Spiral-wound paperboard bodies with metal ends, serving premium dry goods and gift packaging where structural rigidity matters less than print quality and unboxing experience.
- Specialty Cans:Aerosol and pharmaceutical inhaler formats with epoxy-phenolic internal coatings resisting propellant corrosion and acidic formulations.
Leading the category by volume: Aluminum Cans. Growing fastest: Specialty Cans.
End User:
Margin concentration follows the carbonation intensity and regulatory scrutiny of each vertical.
- Beverage Industry:Carbonated soft drink and beer canners drive aluminum specification standardization across North American and Western European supply chains, with procurement teams demanding recycled-content certificates at batch-level traceability.
- Food Industry:Retort processors in Thailand and Indonesia anchor steel-tinplate demand for shelf-stable seafood and ready meals where 121°C sterilization cycles exceed aluminum structural limits.
- Personal Care:Aerosol deodorant and hair spray brands in Germany and France are retrofitting coating lines under F-Gas Regulation phasedowns, concentrating specialty can demand.
- Pharmaceutical:Metered-dose inhaler manufacturers require corrosion-resistant bi-metal constructions with FDA and EFSA dual certification, extending product launch timelines.
Volume leadership sits with Beverage Industry. Steepest expansion trajectory: Pharmaceutical.
Application:
Pressure differentials and thermal processing requirements segment the market into ambient-fill versus retort-compatible specifications.
- Soft Drinks:High-carbonation formulations at 90-100 psi internal pressure demand aluminum two-piece cans with precision-engineered dome geometries for stack strength.
- Alcoholic Beverages:Craft brewers in Oregon and Colorado are adopting laser-etched QR codes and NFC-enabled aluminum ends for anti-counterfeiting and consumer engagement, compressing minimum order quantities.
- Packaged Foods:Low-acid canned goods requiring botulism-risk thermal processing lock in steel-tinplate three-piece construction across Midwest US and Ontario canneries.
- Household Products:Aerosol cleaners and insecticides utilize internally coated steel bodies with aluminum domes, with solvent recovery systems converting to carbon adsorption under EPA VOC limits.
Soft Drinks dominates application volume. Alcoholic Beverages climbs fastest on premiumization and smart-can adoption.
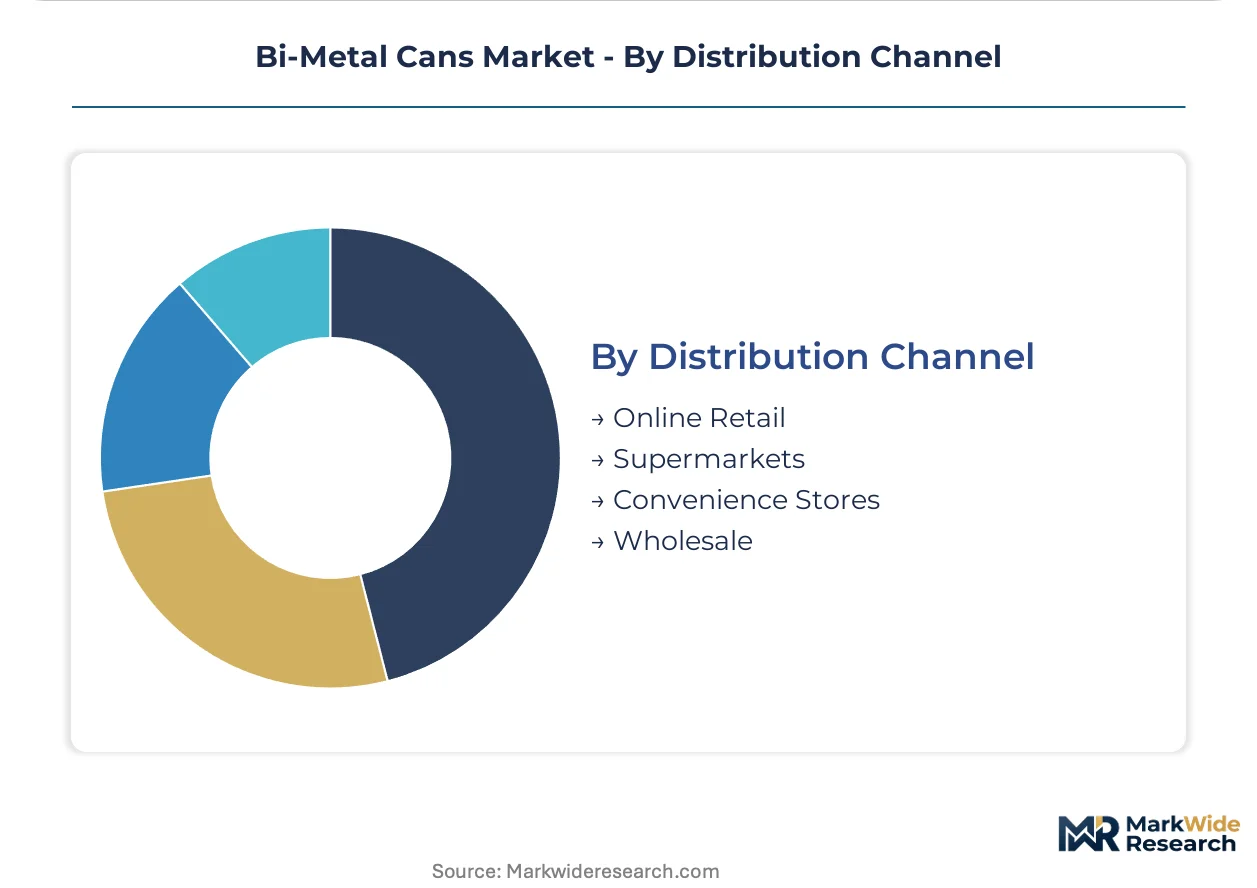
Distribution Channel:
Channel concentration reflects the procurement scale and technical specification complexity of end-users.
- Online Retail:Direct-to-contractor aluminum stock purchases are displacing distributor-mediated flows among multinational brewers with science-based emissions targets, batch-level traceability requirements, and consolidated supplier panels.
- Supermarkets:Private-label beverage and food canners in the UK and Netherlands anchor high-volume, standardized specifications with limited coating customization.
- Convenience Stores:Single-serve beverage formats in Japan's vending-dense urban corridors drive small-diameter aluminum can demand with premium print finishes.
- Wholesale:Institutional foodservice canners in Mexico and Colombia purchase steel-tinplate through regional distributors with annual volume contracts insulating against cold-rolled steel price volatility.
Wholesale leads channel volume. Online Retail expands most quickly on procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's southeastern manufacturing corridor, where beverage canners are expanding aluminum-body lines to serve both domestic consumption and export volumes.
United States
Carbonated soft drink bottlers in the Midwest and Southeast are retrofitting coating lines under EPA volatile organic compound limits. The agency's push toward waterborne and UV-cured alternatives is stranding capital during eighteen-to-twenty-four-month installation timelines. Chicago and Milwaukee anchor steel-tinplate food canning clusters where retort processors require oxygen barrier performance beyond aluminum's thermal ceiling.
Germany
Aerosol deodorant and hair spray brands are accelerating equipment replacement ahead of F-Gas Regulation phasedowns for hydrofluorocarbon solvent recovery systems. ECHA's REACH framework restricts chromium-based passivation chemistries in tinplate, compelling suppliers to certify alternative surface treatments. The Rhine-Ruhr industrial belt concentrates specialty can production for cosmetic and pharmaceutical inhaler applications.
Brazil
Southeastern canning clusters in São Paulo state are expanding aluminum-body lines to serve export beverage volumes under ECHA REACH-compliant surface treatments. Ball Corporation and Crown Holdings are scaling capacity to capture carbonated soft drink demand. The region's manufacturing corridor benefits from proximity to both domestic consumption centers and Atlantic shipping routes.
India
Food canners in Maharashtra and Gujarat favor steel-tinplate for retorted shelf-stable products requiring 121°C sterilization cycles. BIS mandates specific migration limits for heavy metals in food-contact metal packaging, reshaping export certification requirements for regional producers. Mumbai and Ahmedabad anchor three-piece welded construction capacity serving domestic ready meal and seafood processors.
Japan
Convenience store vending-dense urban corridors in Tokyo and Osaka drive small-diameter aluminum can demand with premium print finishes. METI standards shape container specifications for single-serve beverage formats. The Kanto and Kansai regions concentrate can-coating expertise adapted to high-frequency, low-volume production runs.
Bi-Metal Cans Market Competitive Environment
Capacity expansion dominates the current landscape as beverage canners reconfigure material specifications mid-contract. The vendor base organizes around three tiers: integrated multinationals with captive aluminum supply, regional specialists in steel-tinplate food applications, and coating technology providers. Strategic archetypes include smelter-integrated fabricators, retort-compatible steel specialists, and UV-cured coating innovators. M&A activity and geographic expansion represent the dominant competitive moves as players seek to secure batch-level traceability capabilities and recycled-content certificates.
Among North American-integrated fabricators, Ball Corporation and Crown Holdings exemplify the smelter-partnership archetype, anchoring beverage supply chains through upstream aluminum access. Silgan Holdings occupies a position within the specialty-coating tier, representing technology-driven differentiation for acidic food and aerosol applications. These three entities collectively illustrate how procurement centralization and regulatory compliance are reshaping competitive positioning across material specifications and end-use segments.
| Leading Market Players |
|---|
| Ardagh Group |
| Ball Corporation |
| Crown Holdings |
| Tata Group |
| NCI Packaging |
| Kian Joo Can Factory Berhad |
| The Tinplate Company of India Limited |
| Cerviflan Industrial e Comercial Ltd |
| Silgan Holdings |
| Others |
Value Chain & Pricing Dynamics
Multinational brewer procurement teams are consolidating supplier panels and demanding batch-level traceability certificates, anchoring contract-based long-term offtake pricing with volume-scale differentiation. This buyer concentration feeds directly into how aluminum and steel-tinplate stock flows through manufacturing corridors.
Pricing Analysis
Volume leadership sits with commodity aluminum beverage bodies where margins compress under recycled-content mandates, while specialty aerosol and pharmaceutical cans command premium-mid-economy pricing differentiation through FDA-EFSA dual certification tiers. Price differentiation rests on coating complexity and thermal processing compatibility. Cost compression in standard beverage grades is intensifying because EPA VOC limits are stranding capital during coating-line retrofits. Private-label food canners show highest price sensitivity; pharmaceutical inhaler manufacturers least.
Supply Chain Analysis
Dual-sourcing requirements from Ball Corporation and Crown Holdings are compelling beverage canners to qualify both North American smelter partnerships and Brazilian aluminum-body lines simultaneously. Raw material flows draw from Australian bauxite, Chilean copper for alloys, and Indian cold-rolled steel for tinplate. Single-source vulnerability concentrates in captive aluminum networks outside integrated smelter partnerships. Distribution runs through direct-to-contractor channels displacing regional distributors among multinational brewers with science-based emissions targets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum smelter concentration creates a structural capacity bottleneck that props pricing power for integrated fabricators with upstream supply access. Supply constraints favor incumbents with locked-in raw material flows.
For Market Incumbents: To counter steel-tinplate cost volatility compressing margin predictability, secure backward integration into captive aluminum smelter partnerships in Brazil's southeastern corridor and invest in REACH-compliant surface treatment certification ahead of ECHA enforcement timelines. Channel control through direct-to-contractor relationships displaces distributor-mediated flows. For New Entrants and Emerging Players: Begin with aerosol specialty coating applications for cosmetic and pharmaceutical inhaler segments where epoxy-phenolic corrosion resistance commands premium positioning and regulatory barriers slow incumbent response. India's BIS-compliant food-contact metal packaging for Maharashtra and Gujarat retort processors offers the most penetrable geography with first-mover certification advantage. For Investors and Strategic Acquirers: Distressed-cycle entries favor coating-technology specialists with UV-cured and waterborne system capabilities in Germany's Rhine-Ruhr industrial belt where F-Gas Regulation phasedowns are accelerating equipment replacement. Long-term viability across the analysis window hinges on recycled-content infrastructure and batch-level traceability capabilities. Watch EPA enforcement intensity on VOC limits as inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Smelter Partnership Lock-in | Captive aluminum supply from North American primary producers secures volume priority during raw material tightness. |
| Coating-Line Retrofit | UV-cured system conversion under EPA VOC limits opens contract wins from Midwest carbonated soft drink bottlers. |
| REACH Certification Investment | Alternative surface treatment approval enables European beverage supply continuity as ECHA restricts chromium passivation. |
| Direct-to-Contractor Channel | Bypassing distributors captures multinational brewer procurement consolidation with batch-level traceability requirements. |
| Specialty Can Capacity Addition | Epoxy-phenolic coating lines for pharmaceutical inhalers penetrate FDA-EFSA dual-certification bottleneck. |
Study Parameters
Document review covered SEC filings from packaging manufacturers, ECHA REACH registration databases, and EPA enforcement records, complemented by interviews with canning plant engineers, beverage procurement directors, coating technology R&D leads, and steel-tinplate distribution channel partners. Secondary validation drew from customs trade data, BIS certification registries, and Ball Corporation and Crown Holdings capacity announcements. Bottom-up volume modeling triangulated against top-down aluminum and steel consumption forecasts.
Cross-referencing historical production data against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use vertical, application pressure requirements, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating beverage export volume trajectories from Brazil's southeastern corridor and F-Gas Regulation compliance timelines in Germany.
Underlying measurement precision varies by segment; aluminum beverage can volumes carry tighter precision than specialty pharmaceutical formats where dual-certification timelines introduce uncertainty. Forecasts reflect assumptions on smelter capacity expansion and coating technology adoption curves. Deviation in EPA enforcement intensity or ECHA restriction timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
United Kingdom Metal Packaging Market
Metal Packaging
Cans Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
North America 3 Piece Metal Cans Market
Metal Packaging
Global Laminated Steel for Cans Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Indonesia Metal Packaging Market
Metal Packaging
Metal Drums Market
Metal Packaging
APAC Food Cans Market
Metal Packaging
United States Aluminium Cans Market
Metal Packaging
Metal Cans Market