
 Three Piece Cans Market | 2026-2036
Three Piece Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Three Piece Cans Market Outlook
Specialty food processors is reorganizing procurement priorities around extended shelf-life packaging, pulling demand from commodity beverage fillers. Crown leverages its integrated steel supply chain to control input costs across North American and European plants. Ardagh Group S.A. competes through geographic diversification, sustaining production networks that span developed and emerging markets. Ball Corporation anchors its position in beverage-adjacent can formats while extending technical capabilities into precision-engineered food containers.
Three-piece cans consist of separate cylindrical bodies and two end pieces joined by seaming, typically fabricated from tinplate or tin-free steel with internal lacquer coatings ranging from 3 to 7 grams per square meter to prevent metal-food interaction. Their primary commercial purpose is hermetic containment of thermally processed foods, industrial chemicals, and coatings requiring oxygen exclusion and structural rigidity. Food cans dominate volume shipments, reflecting mature demand from vegetable, fruit, and seafood packers, while chemical cans command margin premiums due to compliance-intensive lining specifications and smaller batch production. Aluminum material adoption is accelerating in beverage-facing formats where lightweighting reduces logistics expenditure, though steel retains cost advantages in corrosive-content applications.
FDA food-contact substance regulations and EPA hazardous material packaging standards govern North American market access, with OSHA workplace safety rules further shaping plant-level manufacturing requirements. The EU Green Deal and REACH chemical restrictions are elevating recycled-content mandates and restricting certain epoxy-based internal coatings across European supply chains. Stakeholders must monitor evolving substitution risks from two-piece draw-redraw and DWI technologies, alongside polymer-based barrier innovations that threaten three-piece formats in select end uses.
Market Dynamics
Steel supply concentration and REACH-mandated coating reformulations are compressing manufacturer margins while forcing accelerated R&D cycles across European and North American production networks.
Growth Catalysts
- Shelf-stable protein demand:Food manufacturers in China and Southeast Asia are expanding thermal processing capacity for canned seafood and prepared meals, pulling three-piece steel can orders from domestic fabricators.
- EU Green Deal recyclability mandates:The European Commission's packaging waste directive is elevating metal container preference over polymer alternatives in institutional procurement specifications.
- Tin-free steel substitution:Chromium-coated steel adoption is reducing raw material exposure to tin price volatility while maintaining corrosion resistance for acidic food contents.
Market Restraints
- Epoxy-based coating restrictions:ECHA's bisphenol A regulatory scrutiny is forcing reformulation of internal lacquer systems at 15-20% incremental coating cost.
- Input concentration risk:Cold-rolled steel coil supply clusters in Hebei Province and the Ruhr Valley create geographic vulnerability to energy price shocks and export control fluctuations.
- Two-piece DWI displacement:Drawn-and-wall-ironed aluminum can technology is capturing beverage volume previously filled in three-piece steel formats, particularly for carbonated soft drinks.
Strategic Opportunities
- India processed food infrastructure:FSSAI-mandated food safety modernization is driving first-time canning line investments among domestic vegetable and dairy processors.
- Industrial chemical containment:Specialized phenolic and vinyl lining formulations for agrochemical and coating solvent applications command 40-60% margin premiums over commodity food cans.
- Digital print direct-to-metal:UV-cured inkjet decoration systems are enabling short-run SKU proliferation for seasonal and private-label food brands without cylinder engraving lead times.
Industry Challenges
- Seamer technician scarcity:Double-seam integrity certification programs are failing to replace retiring workforce cohorts in Midwestern US and Northern European plant locations.
- Coating validation timelines:FDA food-contact notification reviews for novel internal lacquer chemistries extend 18-24 months, delaying product launches for reformulated BPA-free systems.
- Legacy line retrofit complexity:Welder and beader equipment from 1990s-era installations requires mechanical synchronization with automated inspection systems, constraining throughput gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Three Piece Cans Market |
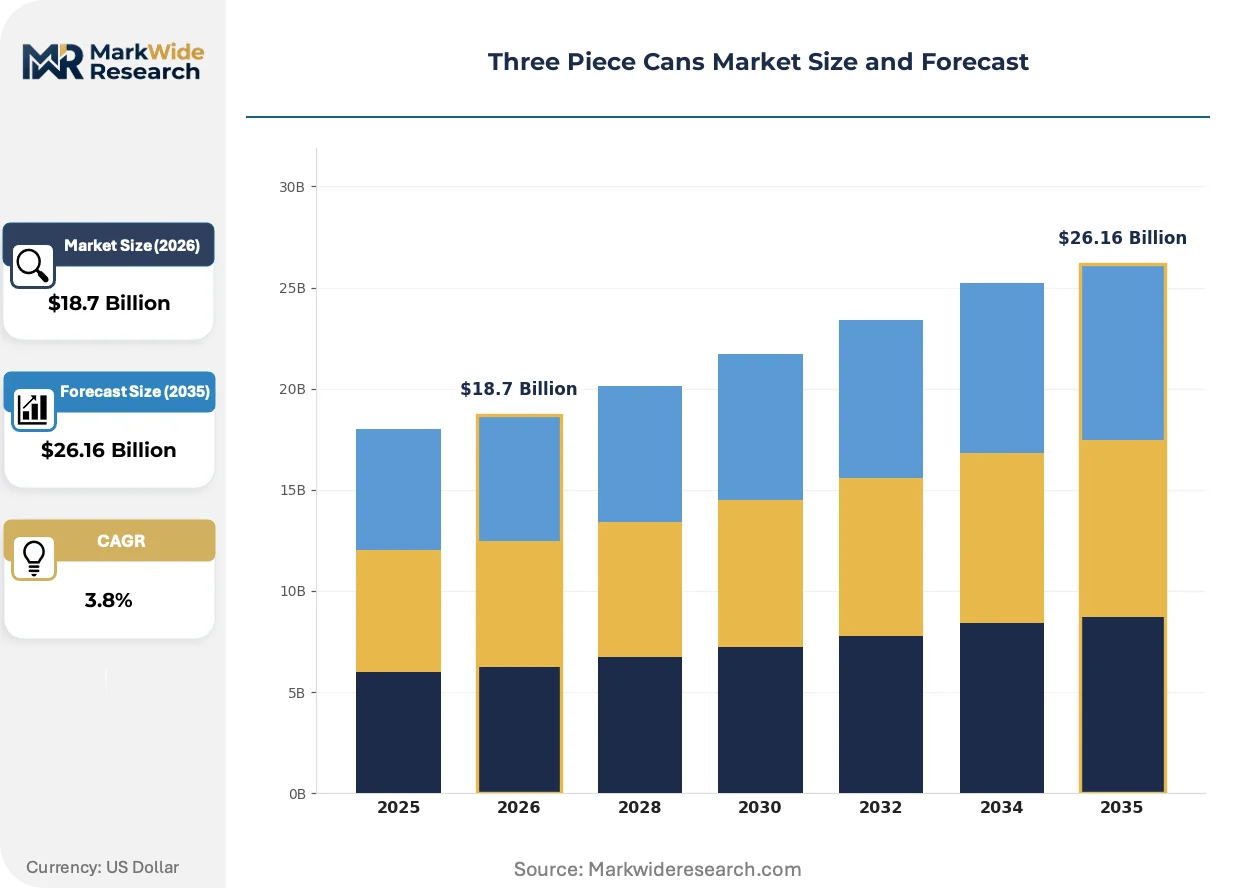
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Cans, Beverage Cans, Chemical Cans, Paint Cans Size: Small, Medium, Large, Extra Large Material: Steel, Aluminum, Biodegradable Plastics, Coated Metals End User: Food Manufacturers, Beverage Producers, Household Use, Industrial Packaging |
| Companies Covered | Crown, Ardagh Group S.A, Ball Corporation, CPMC Holdings Limited, Toyo Seikan Group Holdings Ltd., CanPack, Can-One Berhad, Silgan Containers, Metal Container Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Three Piece Cans Market Strategic Shifts
Material science advances and regulatory chemistry constraints are simultaneously enabling and complicating next-generation three-piece can development across food and industrial chemical applications.
Water-based internal coating systems are fragmenting the incumbent solvent-borne lacquer market as European canmakers accelerate compliance with VOC emission thresholds. Specialty food processors in France and Germany are piloting acrylic-epoxy hybrid formulations for high-acid fruit applications. The technology is fragmenting supplier relationships, forcing compounders to establish regional blending facilities rather than centralized European production.
REACH authorization list expansion is restricting organotin catalyst use in polyester coating cure chemistry, compelling reformulation toward bismuth and zirconium alternatives. The industrial consequence is elevated batch-to-batch viscosity control requirements and tightened specification windows for film weight application. Food can segments in Italy and Spain are responding with dedicated coating validation laboratories co-located at manufacturing sites.
Consolidated retail procurement is compressing supplier rosters as multinational grocery chains mandate single-source national can supply agreements with integrated decoration and logistics services. Regional canmakers in Poland and the Czech Republic are losing shelf placement to integrated European networks offering direct-store-delivery coordination. The shift is most visible in Central European private-label vegetable and legume categories where three-year contract durations are replacing annual tender cycles.
Three Piece Cans Market Segmentation
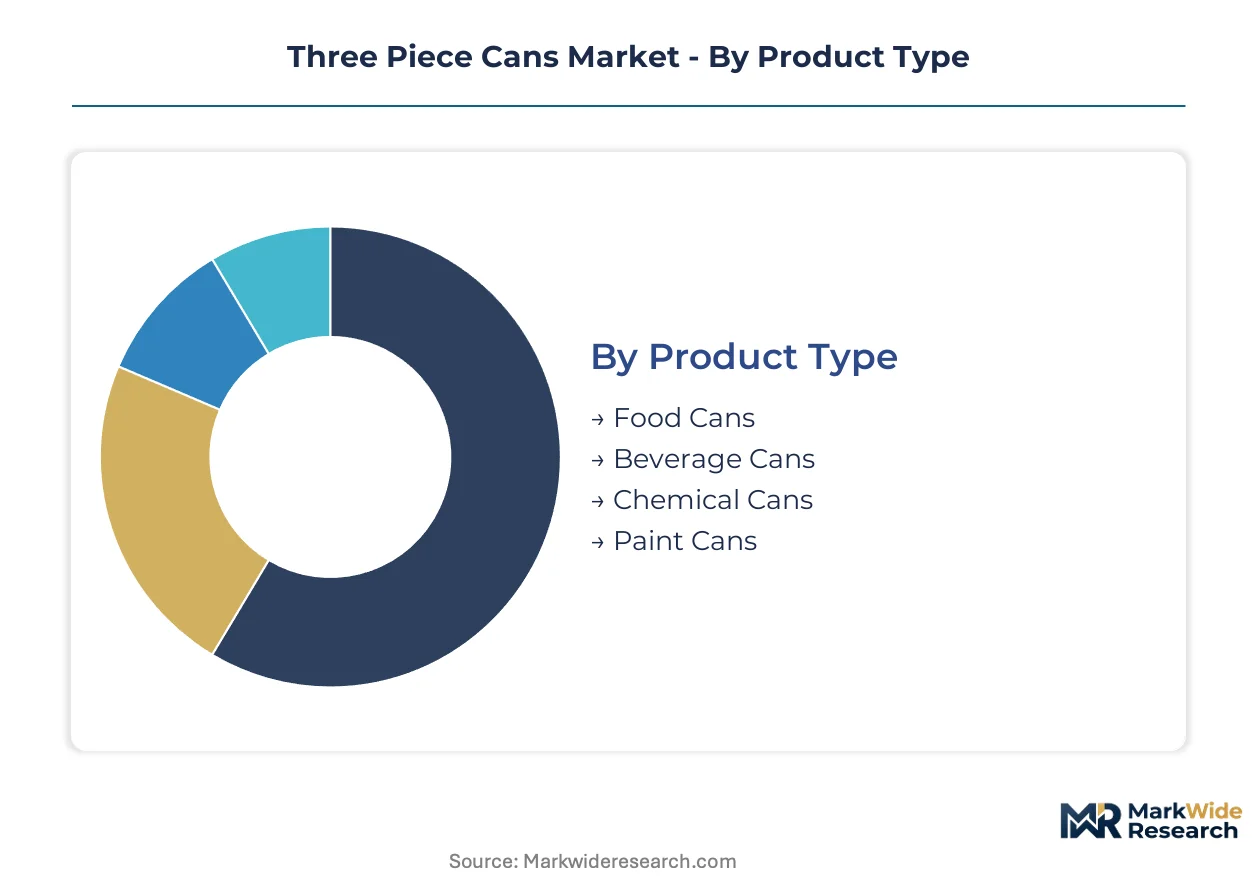
Three-piece can segmentation reveals divergent margin architectures across material grades and end-use specifications. Product type and material composition determine coating complexity and regulatory compliance burden, while size and end-user categories shape volume concentration and pricing power.
Product Type:
Margin pools concentrate in chemical and paint applications where specialized lining formulations command technical premiums, while food and beverage cans compete on scale economies and supply chain integration.
- Food Cans:Hermetic steel containers with internal lacquer coatings ranging from 3-7 grams per square meter prevent metal-food interaction for thermally processed vegetables, fruits, and seafood. Demand clusters in China and Southeast Asia where CPMC Holdings and Toyo Seikan serve domestic processors expanding thermal processing capacity for shelf-stable proteins and prepared meals.
- Chemical Cans:Phenolic and vinyl-lined steel vessels for agrochemical and solvent containment require compliance-intensive specification and smaller batch production. These configurations extract 40-60% margin premiums over commodity food formats due to customized lining validation and hazardous material certification requirements.
- Beverage Cans:Steel and aluminum formats for carbonated and still drinks face accelerating displacement from two-piece DWI aluminum technology in carbonated soft drink applications.
- Paint Cans:Lever-lid and plug-lid steel containers for architectural and industrial coatings leverage established regional supply chains with limited differentiation beyond logistics coordination.
The dominant share belongs to Food Cans, while Chemical Cans is closing the gap fastest through specialty lining premiums.
Size:
Volume throughput and line efficiency separate cost tiers, with medium formats capturing institutional procurement scale and small sizes enabling SKU proliferation for premium positioning.
- Small:Sub-200ml formats for single-serve beverages, specialty sauces, and sample-sized industrial products support short-run decoration and private-label proliferation through digital print direct-to-metal systems.
- Medium:200-500ml standard food and beverage containers dominate retail shelf placement and automated filling line economics across European and North American production networks.
- Large:Family-size and foodservice formats for institutional vegetable, fruit, and legume procurement concentrate demand through consolidated retail national supply agreements.
- Extra Large:Industrial-scale containers for chemical and coating bulk shipment require reinforced seaming and specialized handling equipment with limited format standardization.
Medium sizes anchor production planning, though Small formats are expanding most quickly through e-commerce and convenience channel penetration.
Material:
Raw material cost exposure and corrosion resistance requirements create distinct competitive positions, with steel maintaining cost advantages in acidic and corrosive contents while aluminum penetrates weight-sensitive logistics.
- Steel:Tinplate and chromium-coated tin-free steel retain dominance in corrosive food and chemical applications where structural rigidity and oxygen exclusion are paramount. REACH-mandated coating reformulations and ECHA bisphenol A scrutiny are forcing 15-20% incremental lacquer costs across European supply chains.
- Aluminum:Lightweight draw-redraw and DWI formats are capturing beverage volume through logistics expenditure reduction, though three-piece aluminum remains marginal outside specialty chemical applications.
- Biodegradable Plastics:Experimental barrier materials face technical validation gaps for hermetic thermal processing requirements and limited recycling infrastructure alignment with EU Green Deal mandates.
- Coated Metals:Hybrid substrates with polymer-ceramic barrier layers occupy niche positions in high-acid fruit applications requiring customized acrylic-epoxy hybrid validation.
Steel commands the installed base, yet Aluminum is gaining share fastest in beverage-adjacent lightweighting transitions.
End User:
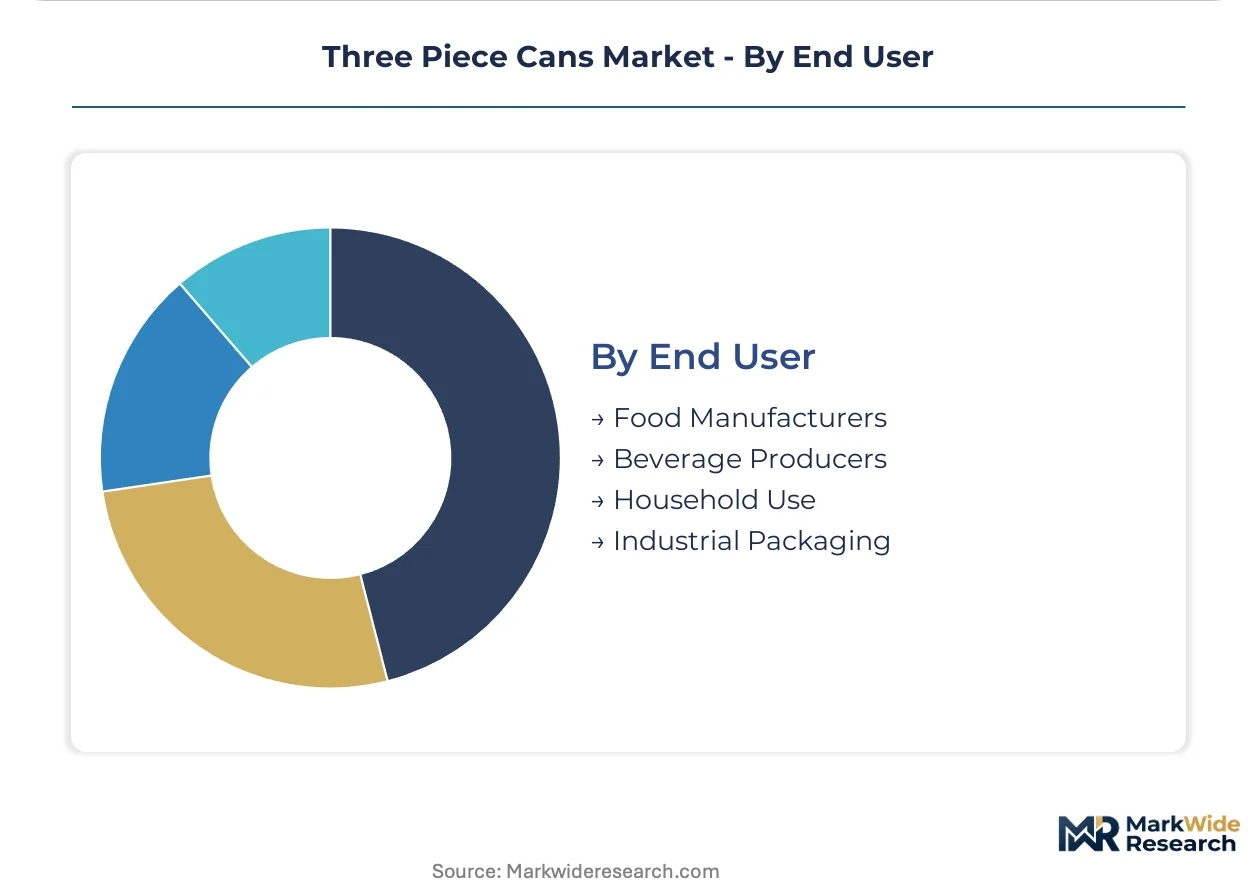
Procurement sophistication and specification control separate customer tiers, with industrial packers driving technical innovation and household channels prioritizing cost and availability.
- Food Manufacturers:Vegetable, fruit, and seafood packers in China, India, and Southeast Asia are expanding canning line investments under FSSAI-mandated safety modernization, pulling three-piece steel orders from domestic fabricators.
- Beverage Producers:Carbonated soft drink and ready-to-drink coffee fillers face format migration pressure toward two-piece aluminum, constraining three-piece volume retention outside specialty and regional brands.
- Household Use:Direct consumer purchase for home organization and small-batch storage represents residual demand with minimal specification requirements and price-sensitive procurement.
- Industrial Packaging:Agrochemical, coating, and solvent containment applications drive phenolic and vinyl lining R&D with extended FDA food-contact notification timelines of 18-24 months for novel chemistries.
Food Manufacturers hold the volume concentration, while Industrial Packaging is climbing the fastest through compliance-intensive margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fabricators export three-piece steel cans to Southeast Asian processors expanding thermal processing capacity for shelf-stable proteins. This trade corridor channels investment toward Hebei Province steel coil clusters and Yangtze River Delta coating facilities. European demand concentrates around REACH-compliant lacquer systems serving institutional procurement specifications.
China
CPMC Holdings Limited and Toyo Seikan Group Holdings Ltd. operate large-scale production facilities serving domestic food and beverage brands expanding canning line investments. MEE dual carbon goals are tightening emission thresholds for steel coil processing and coating application lines. Hebei Province cold-rolled steel supply clusters face energy price shock vulnerability from provincial grid capacity constraints.
United States
Crown leverages integrated steel supply chains across North American plants to control input costs for vegetable and seafood packers. FDA food-contact substance regulations and EPA hazardous material packaging standards govern market access for internal lacquer formulations. Midwestern US plant locations confront seamer technician scarcity as double-seam integrity certification programs fail to replace retiring workforce cohorts.
Germany
REACH chemical restrictions and EU Green Deal packaging waste directives elevate recycled-content mandates for metal container procurement. ECHA bisphenol A regulatory scrutiny forces 15-20% incremental coating cost for epoxy-based internal lacquer reformulation. Ruhr Valley steel coil supply concentration creates geographic vulnerability to export control fluctuations and energy price volatility.
India
FSSAI-mandated food safety modernization drives first-time canning line investments among domestic vegetable and dairy processors pulling three-piece steel orders. BIS standards alignment with international food-contact material specifications accelerates import substitution for coating chemistries. Maharashtra and Gujarat processing hubs expand thermal capacity for shelf-stable prepared meals targeting urban retail channels.
Japan
Toyo Seikan Group Holdings Ltd. anchors domestic fabrication serving precision-engineered food container specifications for seafood and high-acid fruit applications. METI industrial standards govern lacquer film weight application and corrosion resistance testing protocols. Kansai region coating validation laboratories co-locate at manufacturing sites to manage REACH-authorized organotin catalyst substitution toward bismuth alternatives.
Three Piece Cans Market Competitive Environment
Player mix skews toward integrated multinational metal packaging groups with captive steel supply arrangements and geographic diversification strategies. Tier concentration separates scale-driven beverage-adjacent fabricators from specialty food and chemical container specialists. Two strategic archetypes dominate: integrated steel-coating-seaming networks controlling input costs, and diversified geographic operators sustaining production across developed and emerging markets. Competitive moves concentrate on coating chemistry R&D acceleration and automated seaming equipment retrofit for legacy line synchronization.
Among Asia-Pacific-based fabricators, CPMC Holdings Limited and Toyo Seikan Group Holdings Ltd. exemplify the integrated multinational archetype with large-scale production facility concentrations. Crown represents the North American integrated steel supply chain model, while Ardagh Group S.A. occupies the geographic diversification position spanning developed and emerging market production networks. Ball Corporation sits within the beverage-adjacent technical extension archetype, leveraging precision-engineered container capabilities into food applications.
| Leading Market Players |
|---|
| Crown |
| Ardagh Group S.A |
| Ball Corporation |
| CPMC Holdings Limited |
| Toyo Seikan Group Holdings Ltd. |
| CanPack |
| Can-One Berhad |
| Silgan Containers |
| Metal Container Corporation |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day coating formulation lead times concentrate pricing power among integrated steel-coating-seaming networks in Hebei Province and the Ruhr Valley, while buyers face compressed negotiation windows during REACH-mandated reformulation cycles. This temporal compression rewards fabricators with captive lacquer blending facilities and penalizes regional canmakers dependent on third-party compounders.
Pricing Analysis
Legacy solvent-borne lacquer systems, water-based hybrid formulations, and next-generation acrylic-epoxy coatings stratify across premium, standard, and economy tiers based on corrosion resistance certification and FDA food-contact notification status. Price differentiation hinges on BPA-free coating validation and volume scale commitments, with specialty chemical can configurations extracting technical premiums over commodity food formats. Pricing pressure intensifies in beverage-facing steel segments as two-piece DWI aluminum captures carbonated soft drink volume. Regional vegetable packers in Central Europe exhibit highest price sensitivity due to consolidated retail procurement consolidation, while agrochemical containment buyers accept premium positioning for hazardous material certification.
Supply Chain Analysis
Inventory buffers of cold-rolled steel coil in Hebei Province, Yangtze River Delta coating facilities, and Ruhr Valley processing clusters reveal geographic concentration risk against energy price volatility and export control fluctuations. Raw material dependencies center on tinplate and chromium-coated tin-free steel, epoxy and acrylic lacquer resins, and organotin catalyst alternatives. Single-source vulnerability from Hebei Province steel concentration exposes fabricators to provincial grid capacity constraints. Distribution runs through integrated national supply agreements with direct-store-delivery coordination replacing fragmented regional tender cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Three-piece cans represent an early-cycle expansion story as FSSAI-mandated food safety modernization in India drives first-time canning line investments among domestic processors previously reliant on informal packaging.
For Market Incumbents: Secure backward integration into chromium-coated steel production to insulate margins from tin price volatility and Hebei Province supply concentration. Anchor coating validation laboratories at manufacturing sites to compress FDA food-contact notification timelines for BPA-free reformulations. Defend against two-piece DWI displacement by extending technical capabilities into precision-engineered food containers for high-acid fruit applications. For New Entrants and Emerging Players: Differentiate on digital print direct-to-metal capabilities for short-run SKU proliferation serving seasonal and private-label food brands without cylinder engraving lead times. Target India's Maharashtra and Gujarat processing hubs expanding thermal capacity for shelf-stable prepared meals. Penetrate through coating chemistry specialization for phenolic and vinyl-lined agrochemical containment commanding margin premiums. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because coating reformulation R&D cycles and REACH compliance burdens favor scaled integrated networks over fragmented regional fabricators. Acquisition focus should center on European canmakers with established lacquer blending facilities and validated BPA-free coating portfolios. Monitor ECHA authorization list expansion for organotin catalyst restrictions as inflection signal for accelerated industry consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Coil Processing | Crown's captive supply chains in North America demonstrate input cost control against Hebei Province volatility. |
| Coating Validation Laboratory Co-location | Toyo Seikan's Kansai region facilities compress REACH-authorized organotin substitution timelines toward bismuth alternatives. |
| Digital Print Direct-to-Metal Deployment | UV-cured inkjet systems enable short-run proliferation for private-label vegetable and legume categories. |
| Specialty Lining Formulation Development | Phenolic and vinyl systems for agrochemical containment extract 40-60% margin premiums over commodity food formats. |
| Automated Seamer Equipment Retrofit | Mechanical synchronization with inspection systems addresses Midwestern US technician scarcity constraints. |
Study Parameters
A spread of perspectives from plant managers at integrated steel-coating facilities, procurement leads at vegetable and seafood packers, coating compounder technical directors, and retail category buyers converged on the working assumptions. Primary fieldwork across China, Germany, India, and the United States combined with secondary validation from customs records, SEC filings, FDA food-contact substance notifications, and ECHA authorization list updates. Bottom-up volume modeling from canning line capacity installations triangulated against top-down steel coil consumption data.
Segmentation dimensions modeled span product type, material composition, size category, and end-user procurement sophistication across the projection horizon. CAGRs derived from installed base growth rates, replacement demand cycles, and penetration assumptions for thermal processing infrastructure. Forecast inputs incorporated FSSAI modernization timelines, REACH coating reformulation adoption curves, and two-piece DWI displacement rates in beverage applications.
Material uncertainties — ECHA bisphenol A regulatory escalation, Hebei Province energy grid constraints, seamer technician retirement cohorts — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these structural triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Specialty Tin Cans Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
Metal Drums Market
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
France Metal Packaging Market
Metal Packaging
Food and Beverages Metal Can Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
Metal Cans Market
Metal Packaging
PTP Aluminum Foil Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
North America 3 Piece Metal Cans Market